
 Motion Control Market | 2026-2036
Motion Control Market Size, Share, and Industry Trends Forecast 2026-2036
Motion Control Market Intelligence
The IEC 61508 functional safety standard is rotating market access toward vendors with certified components and systems. Siemens AG leverages its extensive portfolio in PLCs and drives to offer integrated automation solutions across multiple industries. Yaskawa Electric Corporation specializes in servo motors and robotics, anchoring its position in high-precision manufacturing applications in Asia. Rockwell Automation, Inc. competes on the basis of its Allen-Bradley control platform, maintaining a strong foothold within North American manufacturing.
Motion control encompasses the systems and components that precisely manage the position, velocity, and torque of moving parts in an automated machine. These systems utilize components like servo drives to achieve sub-micron positioning accuracy, which is critical for complex tasks. Servo drives and linear actuators represent a significant share of the product landscape, valued for their precision and speed. Within applications, robotics and CNC machinery command the highest performance requirements, driving innovation in closed-loop control technologies.
Compliance with Europe's CE marking requirements, China's GB standards for industrial machinery, and US OSHA machine guarding regulations governs market entry. These frameworks mandate specific safety integrations like emergency stops and performance verifications, directly influencing component design and system architecture. The central strategic decision for end-users remains whether to adopt fully integrated systems from a single vendor or assemble best-in-class components from multiple specialized sources.
Market Dynamics
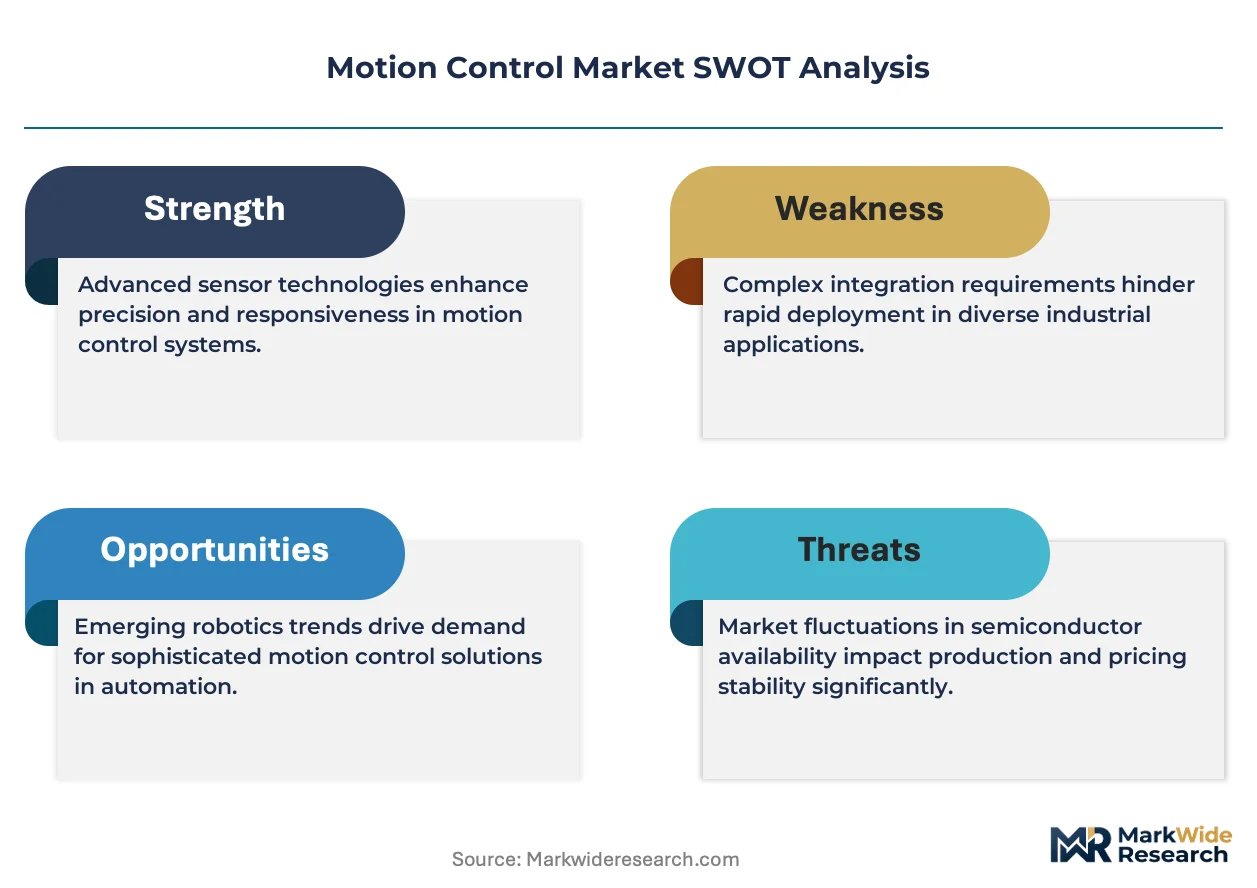
The convergence of demand for sub-micron precision in manufacturing and stricter functional safety mandates, such as IEC 61508, is the central force shaping system architecture. This dual pressure accelerates the adoption of advanced closed-loop control technologies across industrial applications.
Growth Catalysts
- Industry 4.0 Initiatives:Government and corporate programs promoting smart factories drive investment in networked motion control systems for real-time data exchange and process optimization.
- Semiconductor Miniaturization:The continuous push for smaller and more powerful microchips requires motion systems with sub-micron positioning accuracy for wafer handling and lithography.
- EU Machinery Directive:This regulation compels machine builders to incorporate advanced safety features and conduct thorough risk assessments, boosting demand for certified motion control components.
Market Restraints
- High Capital Outlay:The initial investment for high-performance servo systems, linear motors, and precision gearboxes remains a significant barrier for many potential end-users.
- Integration Complexity:Assembling a multi-axis system with best-in-class components from multiple vendors creates significant engineering challenges related to compatibility, communication protocols, and tuning.
- Specialized Component Sourcing:Critical parts like high-resolution encoders and rare-earth magnets are available from a concentrated group of suppliers, creating potential supply chain bottlenecks.
Strategic Opportunities
- Medical and Life Sciences:Growth in robotic surgery, lab automation, and medical imaging equipment presents a significant opportunity for high-precision, reliable motion control systems.
- AI and Machine Learning Integration:Embedding predictive maintenance and self-tuning algorithms into motion controllers offers a path to higher-value services and improved system uptime for end-users.
- SME Automation:The development of more accessible and easier-to-program collaborative robots with integrated motion control opens a large, underpenetrated market segment among small and medium enterprises.
Industry Challenges
- Engineering Skills Gap:A persistent shortage of mechatronics engineers and technicians capable of designing, commissioning, and maintaining sophisticated motion control systems constrains project execution.
- Legacy System Interoperability:Integrating modern motion control platforms with existing factory floor machinery and legacy IT infrastructure often proves complex, costly, and time-consuming.
- Safety Certification Timelines:The process to achieve system-level functional safety certification to standards like ISO 13849 or IEC 61508 can be lengthy, delaying market entry for new machines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motion Control Market |
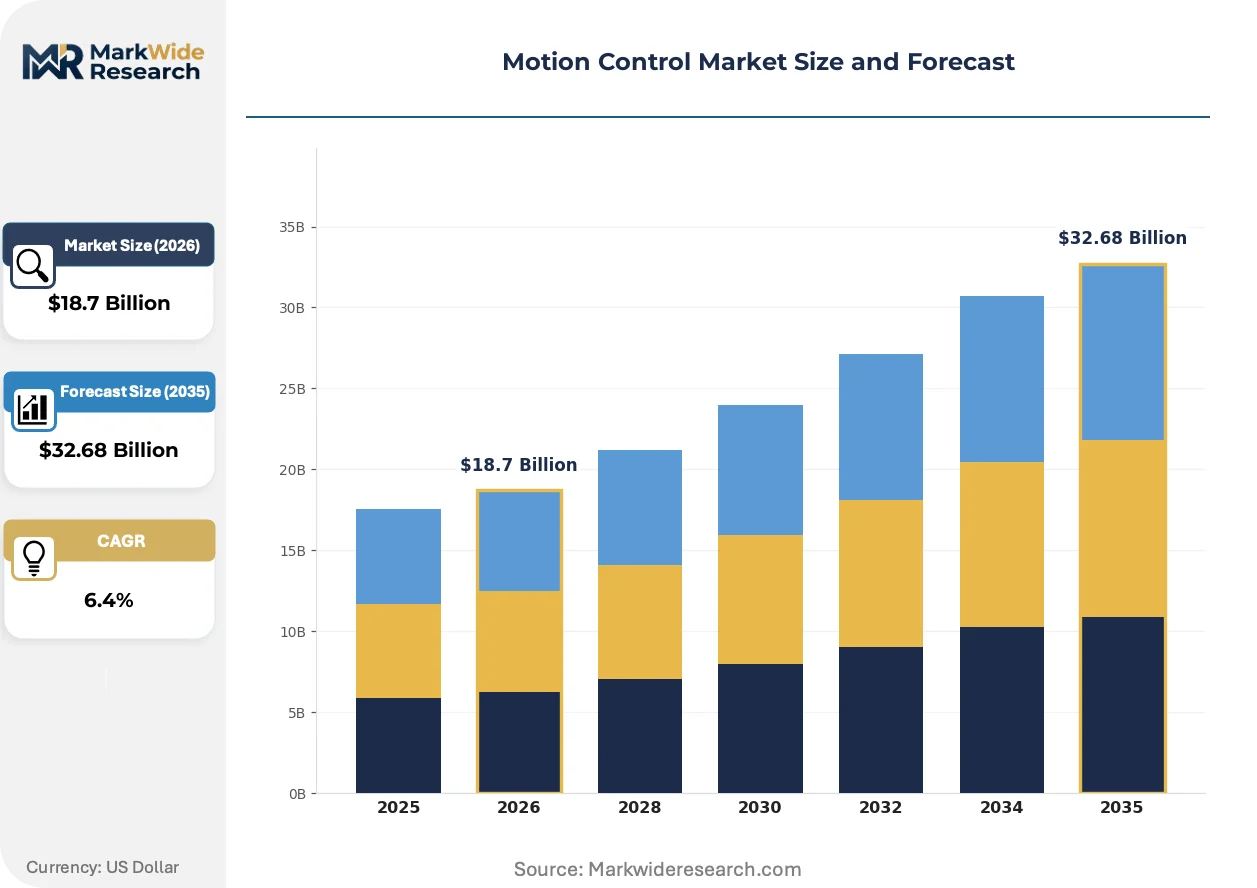
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servo Drives, Stepper Drives, Linear Actuators, Hydraulic Cylinders, Pneumatic Cylinders Technology: Closed Loop Control, Open Loop Control, Distributed Control Systems, Programmable Logic Controllers, Digital Signal Processors Application: Robotics, CNC Machinery, Packaging Equipment, Semiconductor Manufacturing, Textile Production End User: Automotive OEMs, Aerospace Manufacturers, Electronics Fabricators, Food & Beverage Processors, Pharmaceutical Plants |
| Companies Covered | Mitsubishi Electric Corporation, Yaskawa Electric Corporation, Siemens AG, Omron Corporation, FANUC Corporation, ABB Ltd., Rockwell Automation, Inc., Bosch Rexroth AG, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motion Control Market Strategic Shifts & Innovations
Software-defined capabilities and integrated system platforms are fundamentally altering market dynamics. This evolution moves the value proposition from discrete hardware performance toward the intelligence embedded in control algorithms and connectivity, impacting design and procurement choices.
Decentralized motion control places processing intelligence directly within servo drives or motors, reducing reliance on a central controller. Robotics and modular machine builders are rapidly adopting this architecture for enhanced flexibility and scalability. This approach is bifurcating the market between large, centralized systems for complex synchronized tasks and distributed intelligence for reconfigurable manufacturing lines.
Implementation of the IEC 61508 functional safety standard mandates verifiable risk reduction in automated systems. This directly influences component design, requiring features like Safe Torque Off (STO) to be integrated into servo drives and controllers. Machine builders, particularly those exporting to Europe, now prioritize pre-certified components to accelerate their own CE marking compliance process.
A preference for pre-integrated motion subsystems is replacing the traditional practice of sourcing individual components. This model disrupts the role of component-level distributors, favoring vendors that offer complete mechatronic solutions or engineered-to-order assemblies. The shift is most pronounced in high-throughput industries like packaging and electronics assembly where minimizing integration time is paramount.
Motion Control Market Segmentation
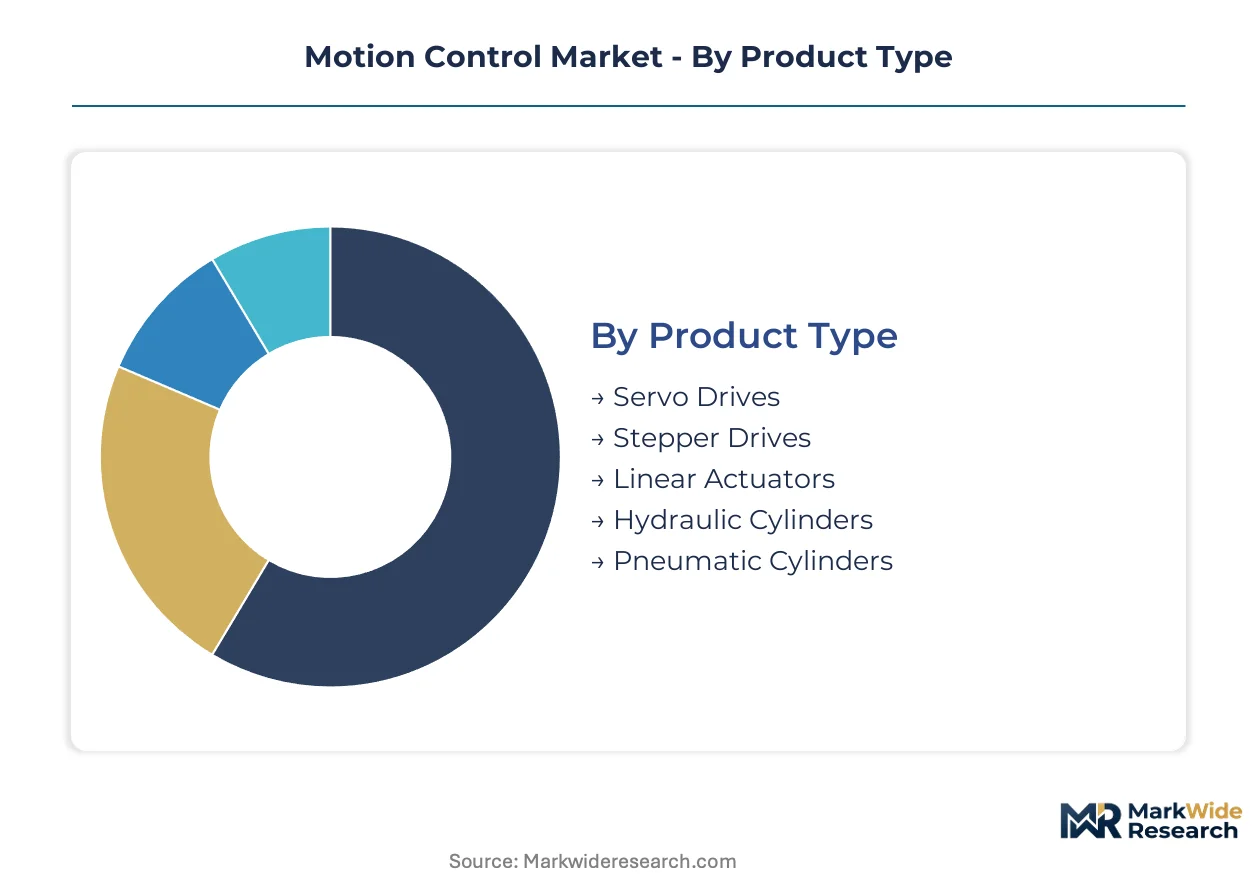
The Motion Control Market segments highlight diverse technological approaches and end-user requirements driving automation. Understanding these categories illuminates the specialized functions and performance tiers critical for industrial machinery. Each segment reflects distinct precision needs, operational environments, and integration complexities across manufacturing sectors.
Product Type:
The distribution channels for motion control components often vary based on the product type, with high-precision devices frequently supplied through specialized engineering firms.
- Servo Drives:These electronic devices control electric servomotors, providing precise position, velocity, and torque control in closed-loop systems. Demand concentrates in advanced robotics and CNC machinery requiring sub-micron accuracy.
- Linear Actuators:These components convert rotational motion into linear motion, offering direct, precise movement along a straight line. Their integration is crucial for high-speed pick-and-place systems and wafer handling in semiconductor fabrication.
- Stepper Drives:These drivers control stepper motors, converting digital pulses into discrete rotational movements without feedback for position. They find extensive use in simpler, cost-sensitive automation tasks like 3D printing and laboratory equipment.
- Hydraulic Cylinders:These devices use pressurized hydraulic fluid to generate powerful linear force and motion. Heavy-duty industrial applications, such as metal forming and construction equipment, rely on their robust force capabilities.
- Pneumatic Cylinders:Utilizing compressed air for linear motion, these actuators offer cost-effective and clean operation. Packaging and material handling systems frequently deploy pneumatic cylinders for rapid, repetitive tasks.
Hydraulic Cylinders dominate the installed base in traditional heavy industry. Servo Drives are where expansion concentrates for high-tech manufacturing.
Technology:
Technology adoption in motion control is heavily influenced by the required level of precision and the complexity of synchronization across multiple axes.
- Closed Loop Control:This system uses feedback sensors to continuously monitor and adjust the output, ensuring high accuracy in position, velocity, and torque. Robotics and semiconductor manufacturing rely on closed-loop systems for critical operational integrity.
- Distributed Control Systems:These systems integrate intelligence directly into individual motion components, allowing for localized control and enhanced system modularity. Industry 4.0 initiatives in smart factories accelerate their adoption for flexible production lines.
- Open Loop Control:Operating without feedback, this simpler control method sends commands without verifying the actual output. Cost-sensitive applications where precise positioning is not paramount, such as basic conveyor systems, often utilize open-loop control.
- Programmable Logic Controllers:PLCs provide robust, industrial-grade control for automated processes and machinery sequences. They serve as the central brain for many factory automation setups, coordinating motion and other machine functions.
- Digital Signal Processors:DSPs are specialized microprocessors optimized for rapid mathematical calculations, enabling real-time control algorithms for high-performance servo drives. Their processing power is essential for complex motion profiles in advanced manufacturing.
Closed Loop Control systems represent the fastest-growing trajectory due to escalating precision demands. Open Loop Control maintains a significant presence in less demanding applications.
Application:
The performance requirements for motion control systems vary significantly across different applications, with some demanding sub-micron accuracy and others prioritizing speed or force.
- Robotics:This segment demands highly dynamic, multi-axis motion control for precise manipulation and movement in automated tasks. The convergence of AI and robotics drives innovation in advanced motion algorithms for collaborative robots.
- Semiconductor Manufacturing:This application requires unparalleled precision for wafer handling, lithography, and inspection processes. Sub-micron positioning accuracy is non-negotiable, driving demand for the most advanced linear motors and controllers.
- CNC Machinery:Computer Numerical Control machines require extremely accurate and repeatable motion for cutting, milling, and grinding operations. The integration of advanced servo drives ensures the precision needed for complex part fabrication.
- Packaging Equipment:High-speed and synchronized motion are critical for efficient packaging lines, handling products from filling to sealing. Motion controllers optimize throughput and minimize waste in automated packaging processes.
- Textile Production:Motion control systems manage thread tension, loom movements, and fabric handling in automated textile machinery. These systems enhance production efficiency and product quality in modern textile factories.
Robotics applications continue to expand rapidly, driven by automation trends. Packaging Equipment remains a consistent, high-volume user of motion control technology.
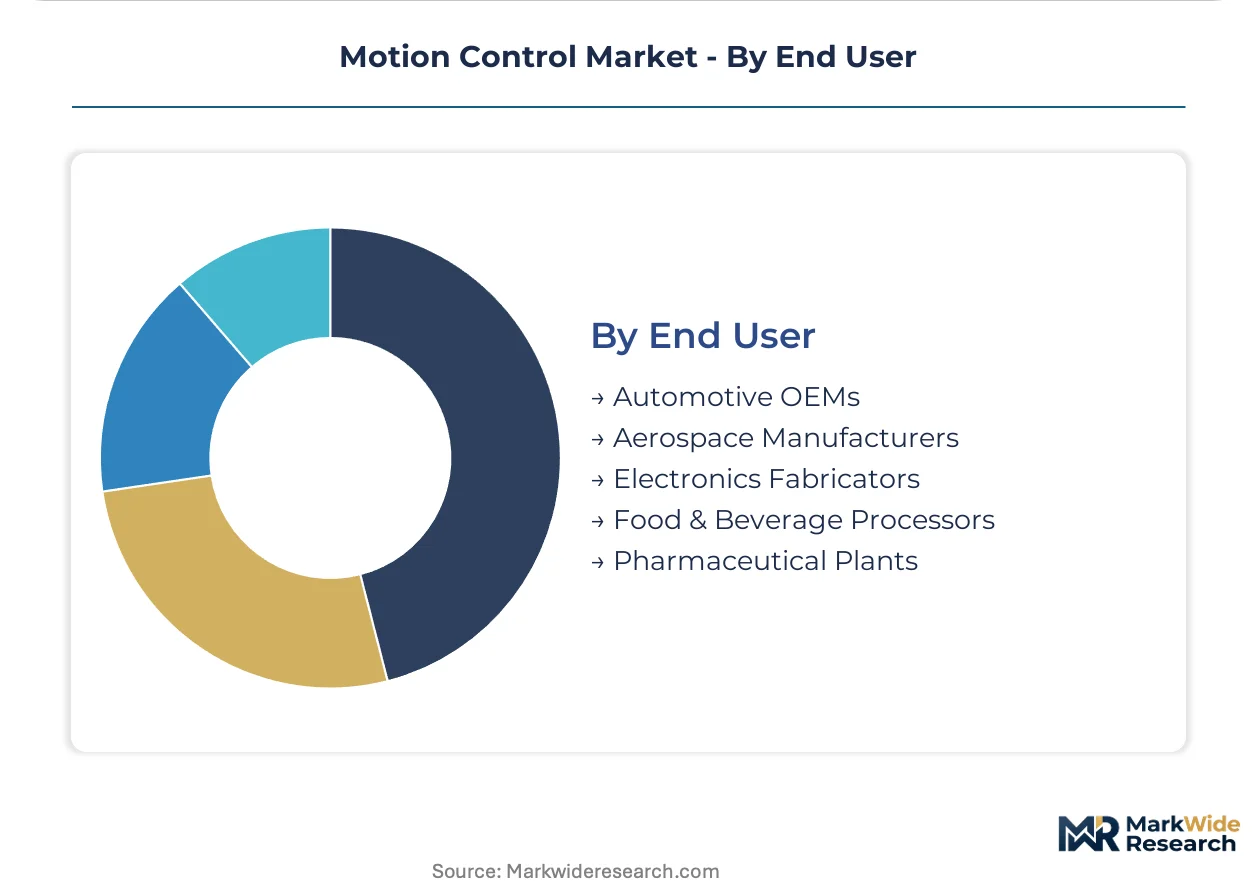
End User:
End-user industries dictate specialized compliance standards and investment cycles for motion control systems, influencing design and procurement decisions.
- Automotive OEMs:These manufacturers utilize motion control extensively for assembly lines, welding robots, and paint shops, demanding high reliability and throughput. The shift towards electric vehicles drives investment in new production automation.
- Electronics Fabricators:High-speed pick-and-place machines, automated inspection systems, and wafer processing equipment are central to electronics manufacturing. These operations require motion control with exceptional speed and sub-micron precision.
- Aerospace Manufacturers:Precision machining of complex components and robotic assembly of large structures are critical, requiring highly accurate and robust motion control systems. Stringent safety and quality standards govern component selection in this sector.
- Food & Beverage Processors:Automated sorting, packaging, and material handling systems ensure hygiene and efficiency in food production. Motion control solutions must withstand washdown environments and comply with food safety regulations.
- Pharmaceutical Plants:Sterile filling, precise dosing, and automated inspection of medical products rely on validated motion control systems. Compliance with regulatory bodies like the FDA and EMA is paramount for pharmaceutical equipment.
Electronics Fabricators exhibit the fastest expansion in motion control adoption. Food & Beverage Processors represent a stable, high-volume market for automation solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in high-performance automation drives regional market dynamics for motion control systems. Industrial automation clusters in Germany, Japan, and South Korea, alongside major manufacturing hubs in the United States and China, lead demand. These regions prioritize precision and efficiency, influencing investment patterns and technological adoption across various sectors.
United States
Electronics fabricators and automotive OEMs drive significant demand for advanced motion control systems in the United States. OSHA machine guarding regulations mandate specific safety integrations, influencing component design and system architecture. Silicon Valley and Detroit represent key concentrations for high-tech manufacturing and automotive production, accelerating adoption of sophisticated robotic and CNC solutions.
Germany
Industrial automation clusters in Germany exhibit high demand for integrated motion control solutions, particularly from automotive and machinery manufacturers. The EU Machinery Directive compels machine builders to incorporate enhanced safety features and conduct thorough risk assessments. Bavaria and North Rhine-Westphalia are central to advanced manufacturing, fostering innovation in closed-loop control technologies.
Japan
Robotics and CNC machinery applications anchor motion control demand in Japan, driven by a strong focus on high-precision manufacturing. Policies from METI encourage smart factory initiatives and investment in advanced automation technologies. The Kanto region, particularly around Tokyo, serves as a hub for leading robotics and electronics companies, pushing boundaries in sub-micron positioning accuracy.
South Korea
Electronics fabricators and the automotive industry fuel motion control expansion in South Korea, demanding high-speed and accurate systems. MFDS regulations, while primarily for pharmaceuticals, influence general manufacturing standards for precision and reliability. The Seoul Capital Area and Busan-Ulsan region host major industrial players, accelerating the adoption of advanced servo drives and linear actuators.
China
Electronics manufacturing and automotive production are major demand drivers for motion control technology across China. GB standards for industrial machinery govern market entry and mandate specific safety integrations in automated systems. The Yangtze River Delta and Pearl River Delta regions are pivotal manufacturing centers, adopting networked motion control for process optimization.
Motion Control Market Key Industry Players
Player mix skews toward established global industrial automation conglomerates offering extensive portfolios of motion control components and integrated systems. The market exhibits a tiered structure, with a few dominant players alongside specialized component manufacturers and regional integrators. Dominant competitive moves include portfolio diversification into software-defined capabilities and strategic partnerships to offer complete mechatronic solutions.
Companies like Siemens AG exemplify the archetype of a diversified industrial powerhouse, leveraging an extensive portfolio across PLCs and drives to offer integrated automation solutions. Yaskawa Electric Corporation represents a specialist in high-precision components, anchoring its position in servo motors and robotics for advanced manufacturing applications. Rockwell Automation, Inc. occupies a strong position within North American manufacturing, competing on the basis of its Allen-Bradley control platform and integrated system offerings.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Yaskawa Electric Corporation |
| Siemens AG |
| Omron Corporation |
| FANUC Corporation |
| ABB Ltd. |
| Rockwell Automation, Inc. |
| Bosch Rexroth AG |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
Project-based contracts for integrated motion control systems lock in both supply access and price visibility for complex industrial automation deployments. This structure manages risk for end-users and vendors across multi-year project cycles.
Pricing Analysis
Cost-plus contracts with raw material indexation often govern pricing for specialized motion control components like linear motors. Pricing stratifies across premium, standard, and economy tiers, driven by precision level and safety certification such as IEC 61508 compliance. Pricing softness reflects the high capital outlay required for advanced systems, particularly impacting smaller enterprises. Electronics fabricators exhibit lower price sensitivity compared to small and medium enterprises.
Supply Chain Analysis
Strategic stockpiling of critical components mitigates supply chain disruptions for high-performance motion control systems. Supply concentrates in Germany, Japan, and South Korea for advanced servo drives and linear actuators. The market relies on rare-earth magnets and high-resolution encoders, creating single-source vulnerability for specialized parts. Distribution runs through direct sales channels for integrated solutions and specialized engineering firms for high-precision devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motion control market represents a high-growth disruption, driven by the continuous push for sub-micron precision in semiconductor manufacturing. This technological inflection reshapes industrial automation landscapes globally.
For Market Incumbents:Shield core market share by deepening software-defined capabilities and offering integrated mechatronic solutions. This strategy counters the threat of integration complexity arising from best-of-breed component assembly. Investing in pre-certified components, particularly for IEC 61508 compliance, accelerates market entry for machine builders. Consolidating supply chains for critical components also strengthens market position.
For New Entrants and Emerging Players:Anchor in underpenetrated segments like SME automation and medical/life sciences. Collaborative robots with integrated motion control represent the most penetrable segment for new players. Focus on accessible, easier-to-program solutions to reduce integration complexity for small and medium enterprises. This approach leverages the growing demand for flexible, reconfigurable manufacturing lines.
For Investors and Strategic Acquirers:Specialized component manufacturers with strong intellectual property in closed-loop control systems offer compelling long-term viability over the next 5-10 years. These targets address the escalating precision demands in industrial automation. The signal to watch is increased M&A activity focused on companies integrating AI and machine learning into motion controllers. This indicates a shift towards higher-value, predictive maintenance services.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Control Platform Development | Enhances system flexibility and reduces reliance on discrete hardware, attracting Industry 4.0 initiatives. |
| Functional Safety Certification Investment | Accelerates CE marking compliance for machine builders exporting to Europe. |
| Strategic Partnership for Mechatronic Solutions | Offers complete, pre-integrated systems, minimizing end-user integration complexity. |
| AI/ML Algorithm Integration | Enables predictive maintenance and self-tuning, improving system uptime for end-users. |
| Localized Manufacturing Capacity Expansion | Mitigates supply chain bottlenecks for critical parts like high-resolution encoders. |
Research Approach
Operator-level perspectives from plant managers, automation engineers, procurement leads, and R&D directors anchored the qualitative base for this study. Primary interviews combined with extensive secondary validation from industry association reports and engineering journals informed market insights. Bottom-up and top-down triangulation ensured data consistency across various segmentation dimensions.
Sensitivity analysis informed the projection of market trajectories across the analysis window. The analytical framework modeled growth across product type, technology, application, end-user, and specific precision requirements. Compound annual growth rates derived from historical trends and projected technology adoption rates. Key forecast inputs included semiconductor capital expenditure and industrial robot shipments.
Decision-makers should treat outputs as directional under current geopolitical stability assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Revision becomes warranted when significant trade tensions or critical component supply disruptions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Drilling Automation Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Europe Industrial Embedded Systems Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Industrial Automation Software Market