
 Middle East and Africa Medical Automation Market | 2026-2036
Middle East and Africa Medical Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Medical Automation Market Foresight
CE marking under the EU Medical Device Regulation is rotating as the de facto quality threshold for equipment entering African and Middle Eastern procurement channels. Siemens Healthineers leverages its imaging installed base to anchor automation retrofit contracts across Gulf hospital networks. GE Healthcare competes through localized service infrastructure that sustains uptime guarantees for robotic surgical systems in South Africa.
Medical automation encompasses electromechanical systems, software-controlled devices, and sensor networks that execute diagnostic, therapeutic, or logistical functions with minimal human intervention, typically operating within ISO 13485 quality management parameters and IEC 60601 electrical safety standards. Robotic surgical systems command premium positioning due to capital intensity and specialized training requirements, while intelligent imaging solutions extend into AI-based systems through embedded algorithmic analysis. Automated medication dispensing occupies a mature margin pool in hospital pharmacy retrofit programs across the region.
South Africa's Health Products Regulatory Authority and Saudi Arabia's SFDA enforce divergent registration pathways that fragment market access timelines for multinational suppliers. The UAE's Ministry of Health and Prevention operates accelerated approval tracks for AI-based systems that demonstrate interoperability with existing electronic health record platforms. Stakeholders must weigh regulatory divergence against the concentration of purchasing power in Gulf sovereign health systems.
Market Dynamics
Hospital procurement officers across the Gulf Cooperation Council are consolidating vendor relationships under long-term automation service contracts that bundle equipment, software, and training into unified agreements.
Growth Catalysts
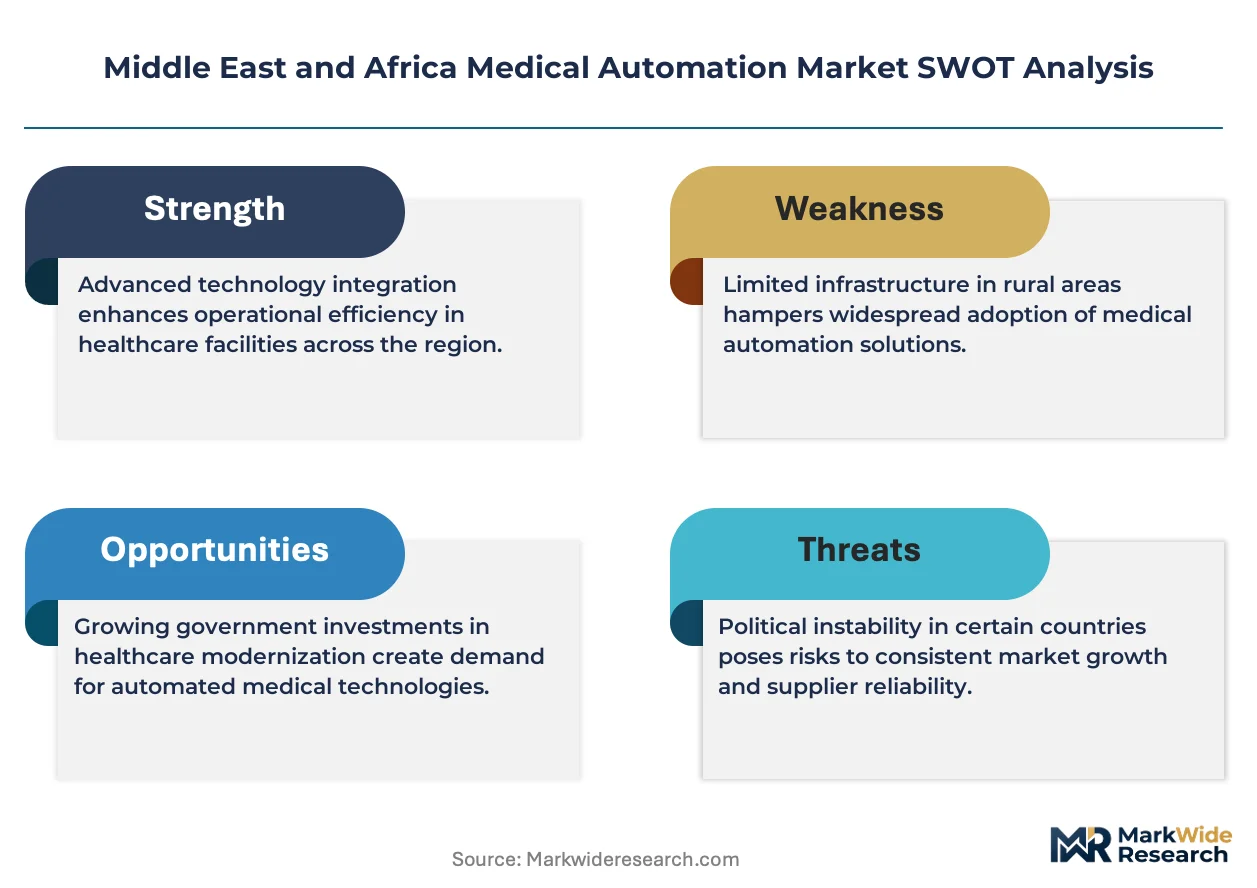
- SFDA Quality Benchmarking:Saudi Arabia's tightened registration requirements for imported automation equipment are filtering out substandard suppliers and elevating trust in certified systems across the kingdom's hospital networks.
- AI Interoperability Mandates:The UAE Ministry of Health and Prevention operates accelerated approval tracks for intelligent systems that demonstrate seamless integration with existing electronic health record platforms, compressing time-to-deployment.
- Robotic Surgical Adoption:South African academic medical centers are expanding robotic surgical programs as training pipelines mature and capital financing structures adapt to multi-year utilization models.
Market Restraints
- Capital Intensity Barriers:Robotic surgical systems require substantial upfront investment and specialized infrastructure that limits adoption to sovereign-funded hospital networks and elite private chains.
- Regulatory Divergence:South Africa's Health Products Regulatory Authority and Saudi Arabia's SFDA enforce non-harmonized registration pathways that fragment market access timelines and inflate compliance costs for multinational suppliers.
- Technical Skill Scarcity:Biomedical engineering talent capable of maintaining complex electromechanical systems remains concentrated in Johannesburg, Dubai, and Riyadh, leaving secondary cities underserved.
Strategic Opportunities
- Pharmacy Automation Retrofit:Automated medication dispensing systems present expansion potential across Egypt's public hospital network where manual inventory management creates persistent safety risks.
- Intelligent Imaging Convergence:Embedded algorithmic analysis is penetrating diagnostic radiology workflows as CE-marked AI modules gain acceptance under Gulf procurement frameworks.
- Service Contract Unbundling:Independent service organizations are capturing maintenance revenue from legacy imaging installations by offering uptime guarantees that compete with original manufacturer service tiers.
Industry Challenges
- Biomedical Engineering Talent Gap:Training programs for robotic surgical system technicians lag equipment deployment rates across the Gulf states, creating operational bottlenecks during system downtime events.
- ISO 13485 Certification Timelines:Quality management system audits for new market entrants frequently extend beyond projected schedules, delaying revenue recognition and straining working capital.
- Legacy System Integration Complexity:Automated dispensing units and robotic surgical platforms must interface with heterogeneous hospital information systems that lack standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Medical Automation Market |
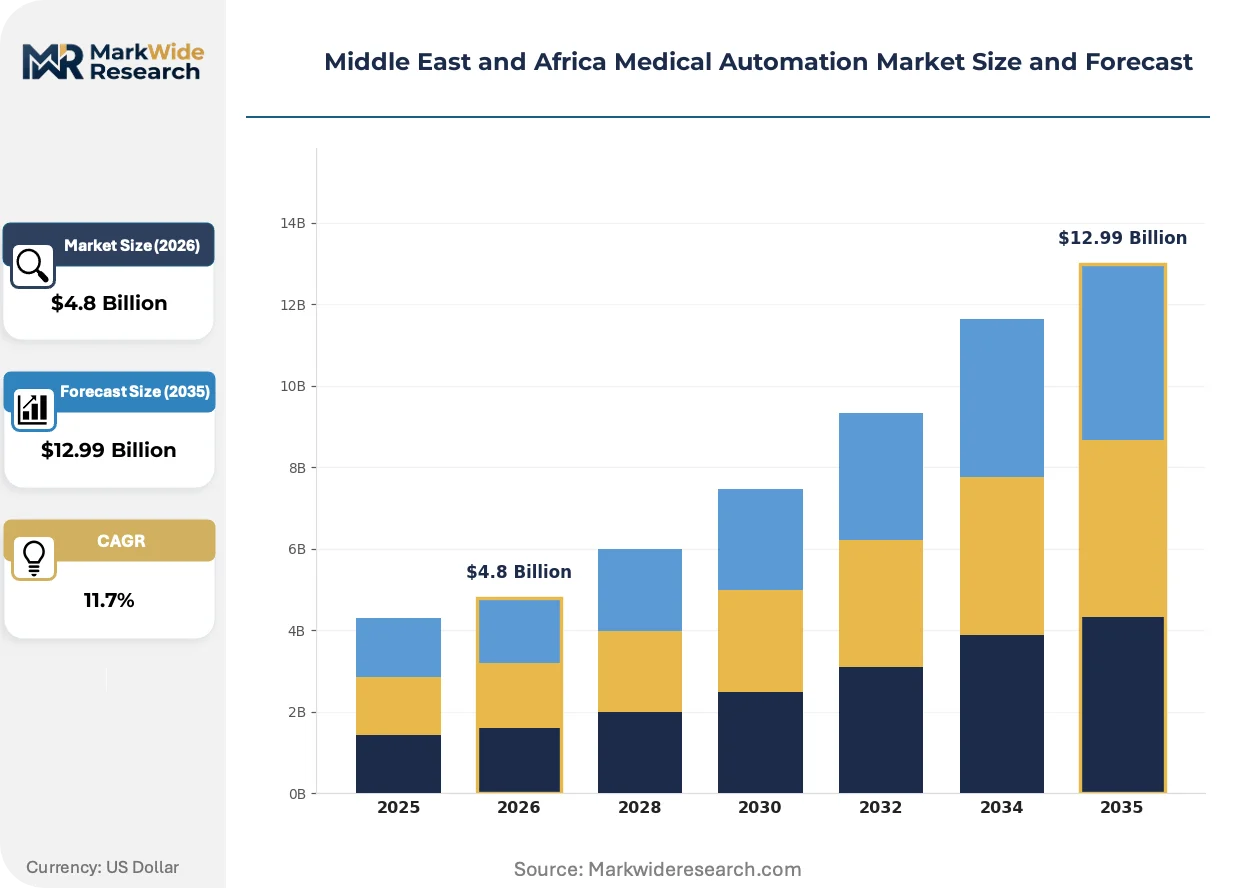
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgical Systems, Automated Medication Dispensing, Patient Monitoring Systems, Intelligent Imaging Solutions Technology: AI-Based Systems, Cloud Computing, IoT Solutions, Machine Learning Algorithms End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Rehabilitation Facilities Application: Clinical Workflows, Surgical Procedures, Diagnostic Processes, Patient Safety Management |
| Companies Covered | GE Healthcare, Stryker Corporation, Intuitive Surgical, Medtronic, Koninklijke Philips, Siemens Healthineers, BD, Boston Scientific, Omnicell, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Medical Automation Market Shifts & Advancements
Electromechanical automation is penetrating clinical workflows through three concurrent vectors: algorithmic enhancement of diagnostic imaging, robotic augmentation of surgical precision, and sensor-driven optimization of pharmaceutical logistics.
Embedded AI analysis modules are supplanting conventional image interpretation workflows in radiology departments. Siemens Healthineers and GE Healthcare are retrofitting existing imaging fleets with algorithmic overlays that flag anomalies for clinician review. This capability compression is reducing mean-time-to-diagnosis for critical pathologies while extending equipment economic life.
CE marking under the EU Medical Device Regulation is rotating as the de facto quality threshold for equipment entering African and Middle Eastern procurement channels. Gulf sovereign health systems now specify MDR compliance in tender documents, effectively harmonizing import standards with European benchmarks. Smaller African markets are following this precedent, consolidating supplier qualification around established certification pathways.
Service unbundling is fragmenting traditional equipment-vendor relationships. Independent biomedical engineering firms in South Africa and the UAE are capturing maintenance contracts for robotic surgical systems by offering response-time guarantees that match or exceed manufacturer service levels. This channel disintermediation is most visible in Dubai's private hospital sector, where procurement officers prioritize operational expenditure flexibility over capital bundling.
Middle East and Africa Medical Automation Market Segmentation
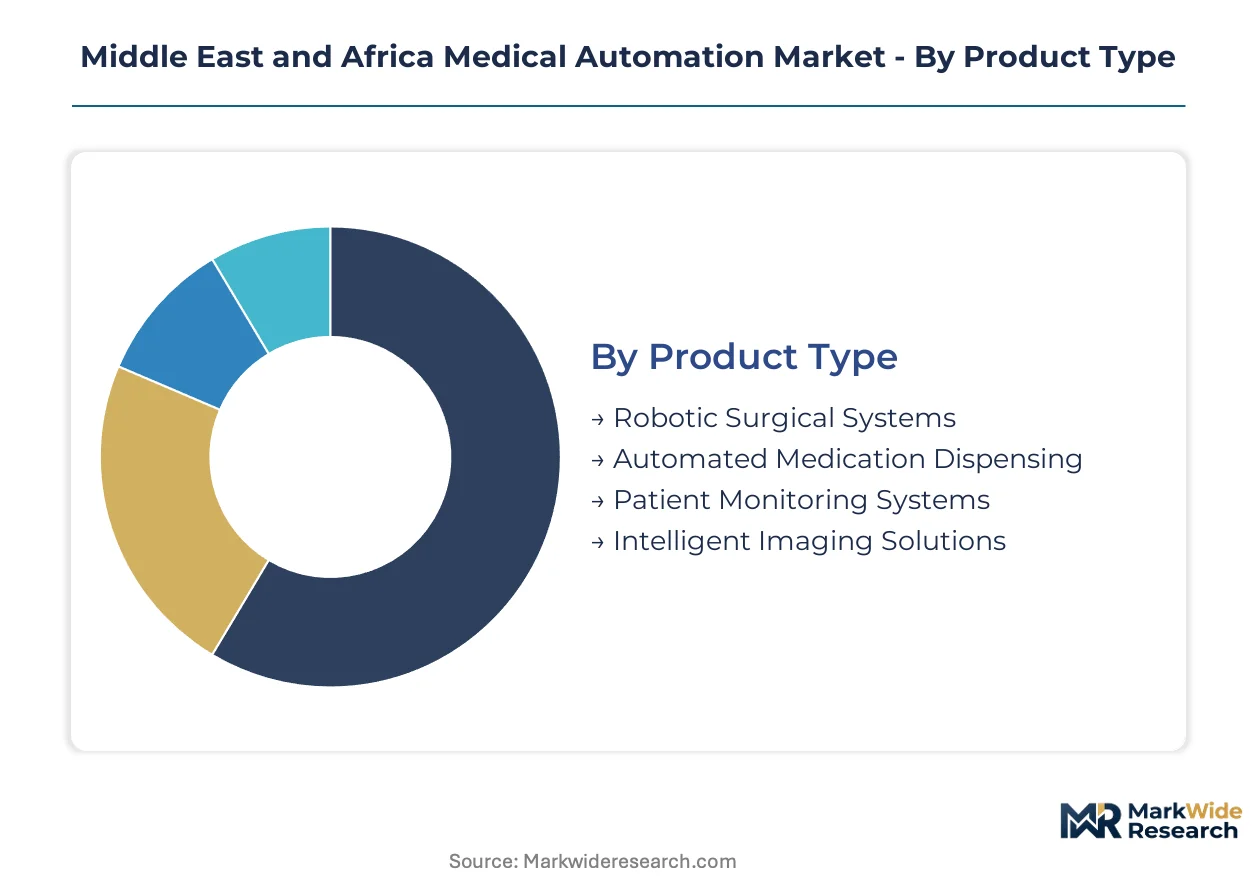
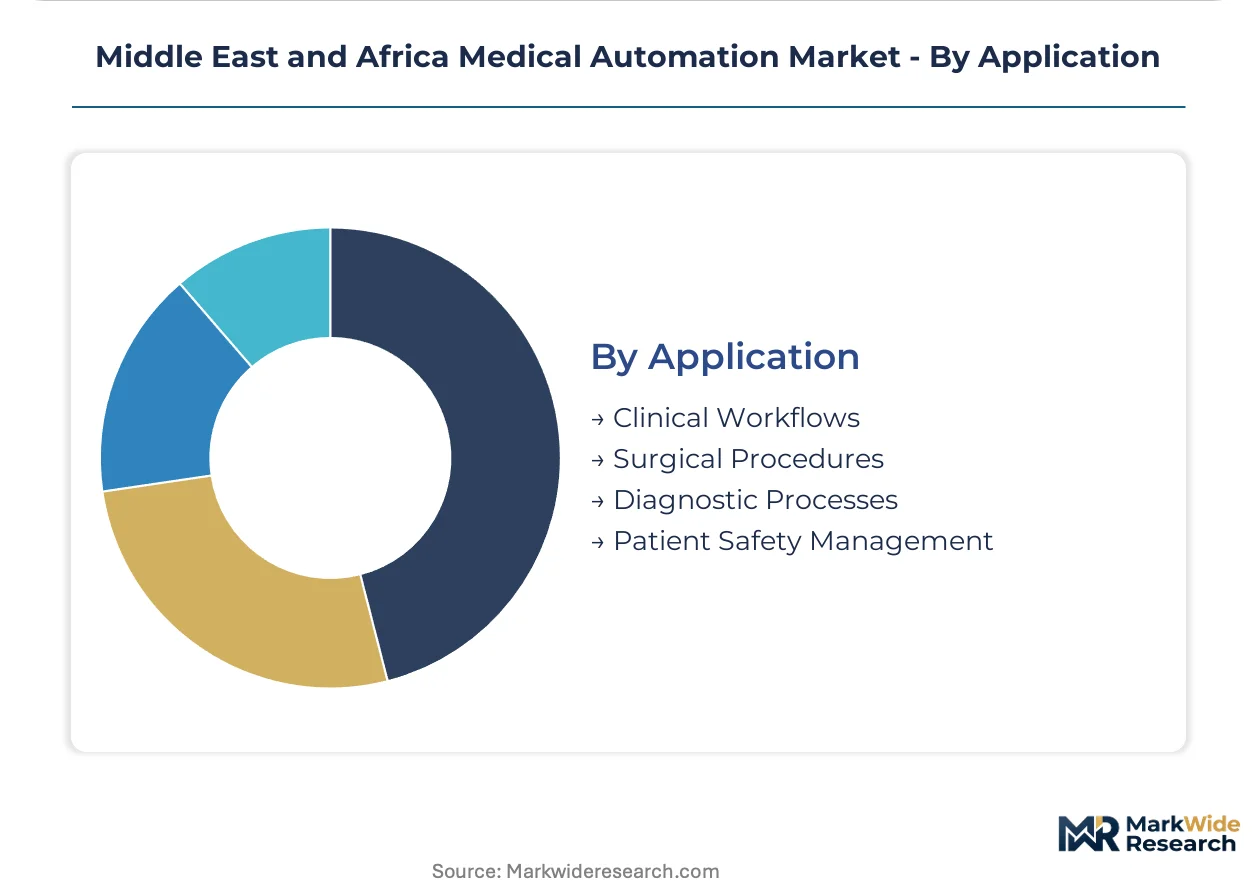
Medical automation procurement across the Middle East and Africa fragments across four intersecting dimensions. Product type and technology choices determine capital allocation, while end-user configuration and application scope shape deployment velocity within sovereign health systems.
Product Type:
SFDA quality benchmarks in Saudi Arabia and MOHAP interoperability mandates in the UAE are elevating certification requirements differentially across equipment categories.
- Robotic Surgical Systems:Electromechanical platforms execute minimally invasive procedures with sub-millimeter precision under surgeon supervision. Demand concentrates in South African academic medical centers and Gulf sovereign hospital networks where capital financing structures accommodate multi-year utilization models. Training pipeline maturity determines deployment velocity.
- Intelligent Imaging Solutions:Embedded algorithmic analysis modules retrofit existing radiology fleets with anomaly detection capabilities. Dubai's health authority digitization program and Saudi diagnostic network upgrades are absorbing CE-marked AI modules that interface with electronic health record platforms. Mean-time-to-diagnosis compression drives procurement decisions.
- Automated Medication Dispensing:Pharmacy retrofit programs across Egypt's public hospital network address manual inventory safety risks through barcode verification and automated cabinet systems.
- Patient Monitoring Systems:Sensor networks track vital signs and physiological parameters with minimal clinician intervention, penetrating ICU and step-down units across the region.
Robotic surgical systems handle the majority of capital throughput; intelligent imaging solutions are expanding most quickly on share.
Technology:
Cost tier stratification separates capital-intensive embedded systems from subscription-accessible cloud architectures.
- AI-Based Systems:Algorithmic modules embedded within diagnostic and therapeutic workflows require specialized training datasets and regulatory validation. UAE accelerated approval tracks favor systems demonstrating EHR interoperability.
- Machine Learning Algorithms:Pattern recognition capabilities improve with data volume, concentrating development resources in Johannesburg and Dubai where hospital network scale supports model refinement. Saudi SFDA registration timelines extend for algorithmic medical devices lacking predicate approvals.
- Cloud Computing:Remote data processing and storage architectures reduce on-premise infrastructure requirements for secondary city deployments.
- IoT Solutions:Sensor networks connect dispersed medical devices through standardized communication protocols, enabling centralized monitoring across hospital campuses.
AI-based systems absorb the dominant share of R&D investment; machine learning algorithms are climbing the fastest on deployment volume.
End User:
Customer type determines procurement channel access and service contract structure across the region.
- Hospitals:Sovereign-funded networks in Saudi Arabia, UAE, and South Africa consolidate vendor relationships under long-term automation service contracts bundling equipment, software, and training. Procurement officers prioritize uptime guarantees and localized biomedical engineering support.
- Ambulatory Surgery Centers:Day-procedure facilities in Dubai's private sector and South African metropolitan areas adopt robotic surgical platforms through operational expenditure models that substitute for capital intensity barriers.
- Diagnostic Laboratories:Centralized testing facilities deploy intelligent imaging and automated sample handling to manage throughput volume.
- Rehabilitation Facilities:Long-term care and physical therapy centers integrate patient monitoring and therapeutic automation for extended treatment protocols.
Hospitals command the preponderance of installed base; ambulatory surgery centers are gaining share fastest on procedure volume migration.
Application:
Maturity differentiation separates established diagnostic automation from emerging patient safety management protocols.
- Surgical Procedures:Robotic augmentation of operative precision requires specialized infrastructure and training pipelines that limit adoption to elite institutions. South African academic centers and Gulf sovereign networks anchor regional deployment.
- Clinical Workflows:Digitization of administrative and care coordination processes spans Dubai Health Authority's public hospital network and comparable initiatives across Riyadh and Johannesburg.
- Diagnostic Processes:Algorithmic enhancement of radiology and pathology interpretation compresses reporting timelines while extending equipment economic life.
- Patient Safety Management:Automated dispensing verification and monitoring alert systems address medication error reduction priorities in Egyptian and Saudi public health initiatives.
Surgical procedures anchor premium equipment revenue; patient safety management is expanding most quickly on regulatory pressure and liability exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port in Dubai anchors the Gulf's medical equipment import corridor, channeling automation systems into Saudi Arabia, Qatar, and Bahrain through bonded warehousing and rapid customs clearance infrastructure.
Saudi Arabia
Sovereign hospital networks in Riyadh and Jeddah deploy robotic surgical platforms under Vision 2030 health transformation mandates. The SFDA enforces tightened registration pathways for imported automation equipment, filtering supplier pools through enhanced quality benchmarks. The King Faisal Specialist Hospital in Riyadh anchors the kingdom's largest robotic surgery training consortium.
United Arab Emirates
Dubai Health Authority's public hospital digitization program absorbs intelligent imaging solutions and automated medication dispensing systems. MOHAP operates accelerated approval tracks for AI-based systems demonstrating EHR interoperability. The Dubai Science Park cluster concentrates regional headquarters for Siemens Healthineers and GE Healthcare service operations.
South Africa
Academic medical centers in Johannesburg and Cape Town expand robotic surgical programs as training pipelines mature. The Health Products Regulatory Authority enforces registration timelines that diverge from Gulf frameworks, fragmenting multinational market access. The Wits Health Consortium in Johannesburg anchors the continent's densest biomedical engineering talent pool.
Egypt
Public hospital pharmacy retrofit programs address medication safety risks through automated dispensing verification systems. The country's national pharmaceutical regulator harmonizes import standards with CE marking requirements under EU MDR precedent. Cairo's Qasr El Eyni Hospital anchors the largest public sector automation deployment in North Africa.
Middle East and Africa Medical Automation Market Competitive Landscape
Listed leaders compete with private specialists across capital financing and service contract structures. Siemens Healthineers and GE Healthcare anchor consolidated positions through imaging installed bases that generate retrofit automation revenue. Three archetypes dominate: diversified health technology conglomerates, robotic surgical pure-plays, and independent service organizations. Competitive moves concentrate on long-term service bundling and localized biomedical engineering capacity expansion.
Within the diversified health technology tier, Siemens Healthineers and GE Healthcare exemplify archetypes leveraging legacy imaging footprints to anchor automation retrofit contracts across Gulf hospital networks. Stryker Corporation occupies a position representing the surgical automation pure-play model, competing through specialized capital equipment and training infrastructure.
| Leading Market Players |
|---|
| GE Healthcare |
| Stryker Corporation |
| Intuitive Surgical |
| Medtronic |
| Koninklijke Philips |
| Siemens Healthineers |
| BD |
| Boston Scientific |
| Omnicell |
| Others |
Supply & Pricing Matrix
Installed base scale in diagnostic imaging anchors procurement leverage for Gulf hospital networks, compressing price floors for automation retrofits while concentrating supplier bargaining power among Siemens Healthineers and GE Healthcare service operations in Dubai Science Park.
Pricing Analysis
Certification level creates the primary spread between premium CE-marked systems and economy-tier alternatives lacking MDR compliance. Three-tier pricing structure across premium, standard, and economy levels bundles equipment, software, and training under long-term service contracts for sovereign-funded networks. Price differentiation reflects ISO 13485 audit depth and localized biomedical engineering support density. Cost compression in the standard tier intensifies as independent service organizations in Johannesburg and Dubai match manufacturer uptime guarantees. Ambulatory surgery centers in South African metropolitan areas exhibit highest price sensitivity due to operational expenditure constraints, while Saudi sovereign networks prioritize certification grade over unit economics.
Supply Chain Analysis
Strategic stockpiling of critical electromechanical components dominates inventory strategy for robotic surgical platforms, contrasting with just-in-time preferences for consumable automation modules. Manufacturing concentration rests on Germany, the United States, and Japan for precision surgical robotics, while intelligent imaging assemblies source from China, South Korea, and the Netherlands. Supply chain vulnerability centers on single-source dependencies for specialized servo motors and optical sensors. Distribution runs through Jebel Ali Port bonded warehousing into Saudi Arabia, Qatar, and Bahrain, with Johannesburg anchoring southern African logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical automation across the Middle East and Africa sits in early-cycle expansion, with SFDA quality benchmarking and UAE AI interoperability mandates accelerating sovereign hospital procurement beyond historical replacement rates.
For Market Incumbents: Fortify service contract bundling by expanding localized biomedical engineering capacity in Riyadh and Johannesburg, countering independent service organization disintermediation. Deepen backward integration into algorithmic module development to capture intelligent imaging retrofit revenue as CE-marked AI penetrates Gulf radiology workflows. Prioritize ISO 13485 certification maintenance to sustain SFDA registration advantages against emerging entrants.
For New Entrants and Emerging Players: Maintenance response-time gaps in secondary Egyptian and Nigerian cities present white-space entry points where manufacturer service tiers underperform. Pharmacy automation retrofit across Egypt's public hospital network offers lowest competitive density for automated dispensing verification systems. Pursue partnership-based go-to-market models with regional distributors holding existing GPO relationships in Dubai and Riyadh.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent service organizations with robotic surgical maintenance capabilities and algorithmic medical device pure-plays holding UAE MOHAP accelerated approvals. Long-term viability hinges on EHR interoperability certification and training pipeline scalability. Watch SFDA registration timeline compression as inflection signal for regulatory barrier reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance unlocks Gulf procurement channels where tender documents specify European benchmarks. |
| Hospital System Partnership | Long-term service contracts with Saudi sovereign networks bundle equipment, software, and training into unified agreements. |
| Software Companion Development | AI modules embedded in existing imaging fleets extend equipment economic life and generate recurring revenue. |
| Biomedical Engineering Training | Technician pipeline investments in Johannesburg and Riyadh address operational bottlenecks during system downtime events. |
| Reimbursement Strategy | Alignment with UAE MOHAP interoperability mandates accelerates approval tracks for EHR-integrated systems. |
Research Methodology
Desk research of hospital procurement databases, GPO contracts, and SFDA registration filings preceded structured interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary fieldwork across Dubai, Riyadh, Johannesburg, and Cairo captured automation deployment timelines and service contract structures. Secondary validation drew from CE marking registries, MOHAP approval databases, and customs import records. Bottom-up equipment unit economics and top-down sovereign health expenditure triangulation anchored market sizing.
Variance decomposition across product type, technology tier, end-user configuration, and application scope shaped the analytical framework over the projection horizon. CAGRs derived from segment-level penetration curves and replacement cycle analysis. Modeled inputs included SFDA registration velocity, training pipeline maturation rates, and EHR interoperability certification timelines.
Underlying assumptions cover sovereign health budget continuity and CE marking acceptance persistence, with deviation risk concentrated in regulatory divergence between South Africa's HPRA and Gulf frameworks. Revision becomes warranted when AI interoperability mandate adoption crosses threshold penetration in secondary city hospital networks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Modular Automation and Services Market
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
North America Smart Factory Market