
 Mining Automation Systems Market | 2026-2036
Mining Automation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Automation Systems Market Insights
Capability gaps between tier-one fleet suppliers and mid-tier integrators is collapsing as open-architecture platforms commoditize core autonomous navigation stacks. Caterpillar leverages its proprietary MineStar ecosystem to sustain premium positioning across integrated command centers. Komatsu Ltd. anchors its competitive stance through in-house production of both autonomous haul trucks and the underlying fleet management software layer.
Mining automation systems encompass integrated hardware-software platforms that enable semi-autonomous or fully autonomous operation of extraction, haulage, and processing equipment through sensor fusion, real-time positioning, and centralized control architectures. These systems typically integrate GPS guidance achieving sub-10 centimeter accuracy, LiDAR obstacle detection arrays, and edge computing nodes to process telemetry locally before uplink to surface control rooms, primarily serving to reduce personnel exposure to hazardous conditions while optimizing equipment utilization rates. Autonomous vehicles dominate current capital deployment as miners prioritize haulage fleet replacement over peripheral system upgrades. Fleet management software represents the fastest-expanding margin pool as recurring software licensing displaces one-time hardware sales.
FAA regulations governing unmanned aerial systems deployed for open-pit surveying and EPA emissions standards for diesel-electric hybrid powertrains shape product certification requirements and procurement eligibility. OSHA mine safety standards mandate operator proximity detection and collision avoidance capabilities, directly driving sensor system specifications. Stakeholders must monitor how interoperability standards between competing automation platforms evolve before committing to single-vendor architectures.
Market Dynamics
Labor shortages across Australia's Pilbara iron ore belt are forcing underground operators to accelerate autonomous fleet deployments faster than equipment replacement cycles would otherwise dictate. This pressure is compressing supplier lead times and collapsing the traditional boundary between tier-one fleet OEMs and mid-tier system integrators.
Growth Catalysts
- OSHA proximity mandates:US mine safety standards now require collision avoidance and operator detection systems, compelling surface and underground operations to upgrade sensor arrays ahead of scheduled capital cycles.
- Edge computing architectures:Real-time telemetry processing at the equipment level reduces latency for autonomous haulage decisions, enabling centralized command centers to manage larger fleet densities per operator.
- Western Australia labor scarcity:Chronic shortages of heavy equipment operators in the Pilbara region are pushing iron ore majors toward full autonomous conversion of haul truck fleets.
Market Restraints
- LiDAR sensor supply concentration:Production of automotive-grade LiDAR arrays for mining applications clusters among a handful of East Asian component suppliers, creating vulnerability to allocation constraints.
- Proprietary fleet protocols:Caterpillar's MineStar and Komatsu's proprietary command architectures lock buyers into single-vendor ecosystems, limiting interoperability and second-source options.
- Diesel-electric hybrid certification:EPA emissions compliance for hybrid powertrains in underground equipment extends development timelines and raises non-recurring engineering costs for OEMs.
Strategic Opportunities
- Queensland metallurgical coal:Underground longwall operations in Australia's Bowen Basin remain underpenetrated by autonomous shuttle car systems relative to Western Australian surface haulage.
- Open-architecture middleware:Software layers that translate between competing fleet management protocols are creating white space for independent integrators to bridge OEM silos.
- FAA Part 107 expansion:Regulatory clarity for beyond-visual-line-of-sight drone operations is accelerating unmanned aerial system adoption for open-pit surveying and blast pattern verification.
Industry Challenges
- Mine-site connectivity infrastructure:Reliable fiber and LTE coverage across vast pit footprints remains uneven, forcing operators to deploy expensive private network overlays before autonomous systems can achieve designed uptime.
- Legacy equipment retrofit complexity:Older haul truck fleets lack the CAN bus architectures and power budgets required for sensor fusion upgrades, fragmenting fleet standardization.
- Control room operator retraining:Transitioning from in-cab to remote fleet supervision demands new competencies in multi-vehicle telemetry interpretation and exception handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Automation Systems Market |
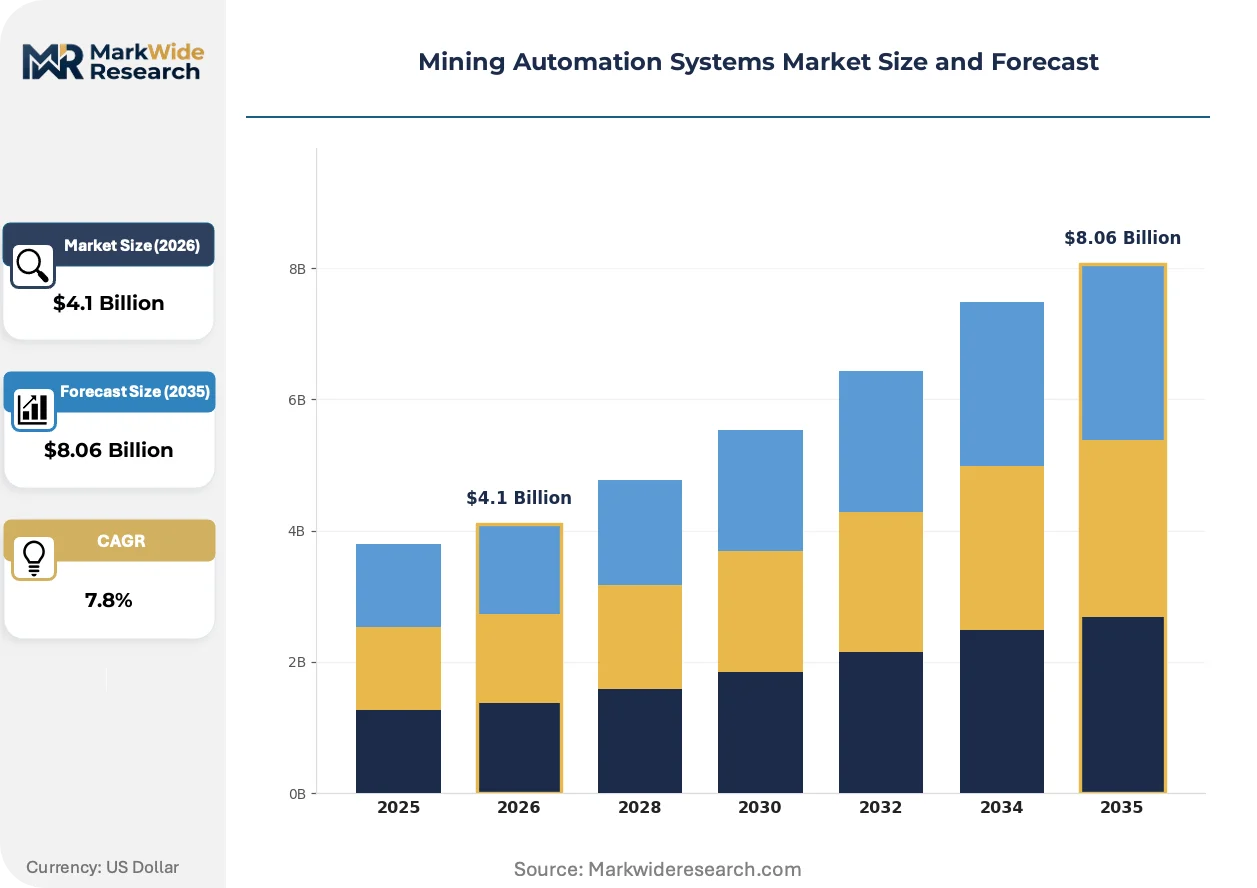
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Vehicles, Remote Operation Stations, Sensor Systems, Communication Networks, Fleet Management Software Technology: GPS Guidance, Lidar, Radar Systems, Machine Learning Algorithms, Edge Computing, 5G Connectivity Application: Surface Mining, Underground Mining, Mineral Processing, Equipment Monitoring, Safety Management End User: Metal Extractors, Coal Producers, Quarry Operators, Mineral Refiners, Earthworks Contractors |
| Companies Covered | Caterpillar, Komatsu Ltd., Sandvik AB, Epiroc AB, Hexagon AB, Rockwell Automation, Atlas Copco AB, Autonomous Solutions Inc., Rio Tinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Automation Systems Market Trends and Innovations
Autonomous navigation stacks are fragmenting into modular, interchangeable components, eroding the historical advantage of vertically integrated fleet suppliers. This decomposition is reshaping competitive boundaries across hardware, software, and integration services.
Sensor fusion architectures for autonomous haulage are decomposing into discrete, replaceable subsystems. Underground operators in Chile's copper belt are piloting third-party perception modules that interface with OEM vehicle controllers. This modularity is compressing switching costs and enabling mixed-fleet deployments that were technically infeasible five years ago.
Australia's national resources regulator is tightening mandatory incident reporting thresholds for autonomous equipment malfunctions. The policy is forcing operators to upgrade telemetry logging granularity and extend data retention periods. Western Australian iron ore producers are responding by consolidating vendor relationships to simplify audit trails.
Equipment-as-a-service contracting is displacing traditional capital purchase models for autonomous fleets. Mining majors in Brazil's Carajás iron ore district are negotiating availability-based payments tied to tonnage moved rather than asset ownership. This shift transfers utilization risk to OEMs and accelerates refresh cycles in high-volume operations.
Mining Automation Systems Market Segmentation
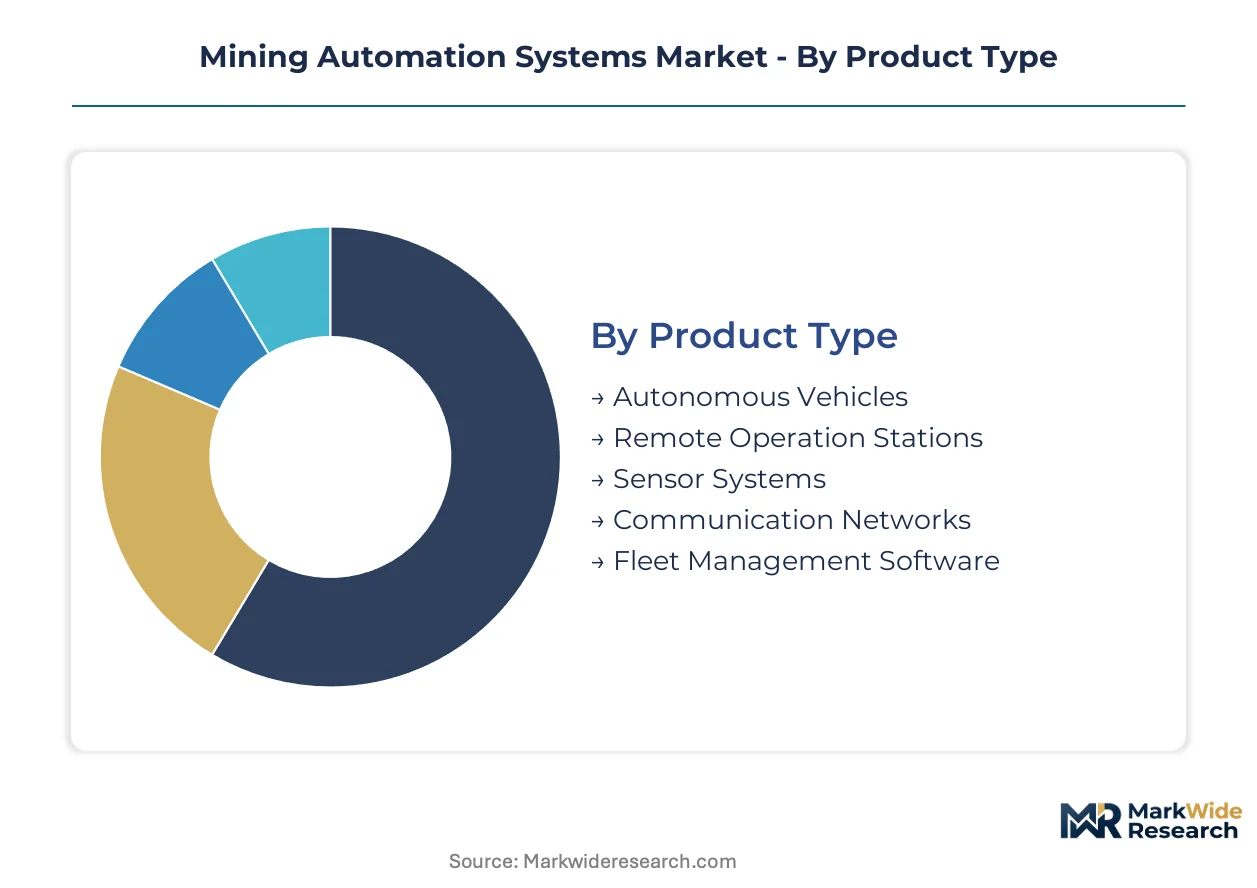
Segmentation in mining automation systems reveals where capital deployment concentrates versus where margin expansion accelerates. Product architecture and technology choices determine vendor lock-in intensity, while application context shapes interoperability requirements.
Product Type:
Margin pools concentrate heavily in software layers and integrated vehicle platforms, with commoditization pressure mounting on discrete hardware components.
- Fleet Management Software:Recurring licensing models generate superior lifetime value versus one-time hardware sales. Western Australia's Pilbara iron ore majors are consolidating vendor relationships to simplify audit trails under tightened reporting mandates.
- Autonomous Vehicles:Haul trucks dominate current capital deployment as miners prioritize fleet replacement over peripheral upgrades. Chronic operator shortages across Australia's Pilbara are forcing conversion timelines faster than equipment replacement cycles would dictate.
- Remote Operation Stations:Centralized command centers consolidate supervision of dispersed fleets.
- Sensor Systems:OSHA proximity mandates are compelling surface and underground operations to upgrade arrays ahead of scheduled capital cycles.
- Communication Networks:Private LTE overlays address coverage gaps across vast pit footprints before autonomous systems achieve designed uptime.
The dominant share belongs to Autonomous Vehicles, while Fleet Management Software is expanding most quickly through recurring revenue displacement of hardware sales.
Technology:
Cost tier stratification separates proven positioning technologies from emerging AI and connectivity layers still seeking production validation.
- Machine Learning Algorithms:Perception and path-planning modules are fragmenting into replaceable subsystems, compressing switching costs. Underground operators in Chile's copper belt pilot third-party perception modules interfacing with OEM vehicle controllers.
- Lidar:Automotive-grade array production clusters among East Asian component suppliers, creating allocation vulnerability. EPA emissions compliance timelines for hybrid powertrains extend development cycles for OEMs integrating these sensors.
- GPS Guidance:Sub-10 centimeter accuracy remains standard for surface haulage positioning.
- Radar Systems:All-weather obstacle detection complements optical sensors in dust-heavy environments.
- Edge Computing:Real-time telemetry processing at equipment level reduces latency for autonomous decisions.
- 5G Connectivity:Ultra-reliable low-latency links enable centralized command centers to manage larger fleet densities per operator.
GPS Guidance retains the installed base lead, though Machine Learning Algorithms are climbing the fastest as modular architectures erode integrated supplier advantages.
Application:
Volume concentration favors surface operations with standardized haulage patterns, while underground complexity sustains premium pricing for specialized systems.
- Surface Mining:Autonomous haulage conversion concentrates in Western Australia's Pilbara iron ore belt where labor scarcity and flat terrain enable full fleet automation. Brazil's Carajás district is shifting toward equipment-as-a-service contracting tied to tonnage moved.
- Underground Mining:Longwall operations in Australia's Bowen Basin remain underpenetrated by autonomous shuttle car systems relative to surface haulage. Chile's copper belt pilots are validating third-party perception module integration with OEM controllers.
- Mineral Processing:Continuous operation environments favor fixed automation over mobile fleet systems.
- Equipment Monitoring:Predictive maintenance layers leverage edge computing architectures for uptime optimization.
- Safety Management:OSHA standards mandate operator proximity detection and collision avoidance capabilities.
Surface Mining commands the dominant share, yet Underground Mining is gaining share fastest as modularity unlocks mixed-fleet deployments previously infeasible.
End User:
Customer type determines procurement sophistication, with integrated majors driving standardization while fragmented contractors sustain integration service demand.
- Metal Extractors:Iron ore and copper majors consolidate vendor relationships to simplify compliance audit trails. Australia's national resources regulator is tightening mandatory incident reporting thresholds for autonomous equipment malfunctions.
- Coal Producers:Metallurgical coal operations in Queensland's Bowen Basin present white space for autonomous shuttle car penetration.
- Quarry Operators:Smaller scale limits autonomous fleet deployment to partial automation solutions.
- Mineral Refiners:Processing-focused operations prioritize fixed automation over mobile fleet systems.
- Earthworks Contractors:Project-based contracting sustains demand for retrofit solutions and integration services.
Metal Extractors hold the dominant share, while Coal Producers are closing the gap fastest as underground longwall automation penetrates Queensland's metallurgical coal sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in mining automation systems favor technology-exporting nations supplying mineral-rich importing markets. Australia and Chile dominate autonomous equipment adoption, while Germany and Japan anchor precision component manufacturing. Brazil and South Africa concentrate as emerging deployment theaters for integrated systems.
Australia
Western Australia's Pilbara iron ore belt drives autonomous haul truck conversion at unprecedented velocity. TGA-aligned safety mandates from the national resources regulator compress deployment timelines beyond standard replacement cycles. Perth-based command centers now supervise mixed-fleet operations spanning BHP and Rio Tinto tenements.
Chile
Underground copper operations in the Atacama Desert validate third-party perception modules interfacing with OEM controllers. Chile's mining regulator enforces stricter autonomous incident reporting thresholds under revised subterranean safety codes. Antofagasta and Calama host concentrated pilot programs for modular navigation stacks.
Brazil
Carajás iron ore producers negotiate equipment-as-a-service contracts tied to tonnage performance rather than asset ownership. ANVISA-equivalent mining safety protocols govern diesel-electric hybrid certification timelines for underground deployment. Pará state's northern mining corridor attracts fleet management software investment from international integrators.
Germany
Precision LiDAR and sensor fusion component manufacturing clusters around Stuttgart and Munich industrial corridors. REACH-compliant material standards shape export eligibility for mining-grade optical arrays. Bavarian automation specialists supply perception hardware to Australian and Chilean deployment sites.
Japan
Meti-sponsored R&D consortia advance edge computing architectures for subterranean telemetry processing. JIS certification requirements govern interoperability standards for autonomous vehicle controllers. Tokyo-Osaka industrial corridors concentrate fleet management software development for Asian mining markets.
Mining Automation Systems Market Competitive Landscape
Concentration sits with integrated fleet OEMs commanding proprietary command architectures that lock buyers into single-vendor ecosystems. Tier-one suppliers with captive vehicle production and software layers extract premium positioning through bundled availability contracts. Mid-tier integrators exploit open-architecture middleware to bridge OEM silos and capture mixed-fleet deployment opportunities. Strategic moves center on backward integration into sensor component supply and geographic expansion through equipment-as-a-service contracting models.
Among diversified industrial conglomerates, Caterpillar and Komatsu Ltd. exemplify vertically integrated archetypes spanning autonomous vehicle production through fleet management software layers. Sandvik AB occupies a specialized position in underground drilling and loading automation. These three anchors represent distinct competitive postures: bundled ecosystem control, dual hardware-software production, and subterranean application focus respectively.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu Ltd. |
| Sandvik AB |
| Epiroc AB |
| Hexagon AB |
| Rockwell Automation |
| Atlas Copco AB |
| Autonomous Solutions Inc. |
| Rio Tinto |
| Others |
Pricing and Supply Chain Analysis
Automotive-grade LiDAR arrays replacing mechanical scanning units in mining haulage systems simultaneously relocates component sourcing toward East Asian manufacturing clusters and compresses pricing premiums for perception hardware tiers. This substitution dynamic redistributes value capture from integrated OEMs toward specialized sensor suppliers while flattening cost curves for mid-tier fleet integrators.
Pricing Analysis
The customization-premium spread in mining automation systems spans configured-to-order autonomous navigation stacks against standard fleet management software licenses. Equipment-as-a-service contracts tied to tonnage performance displace capital purchase models among Brazilian iron ore majors, transferring utilization risk to OEMs. Pricing stratifies across premium bundled ecosystems from Caterpillar and Komatsu, standard middleware-based integrations, and economy retrofit solutions for legacy haul fleets. Cost compression in sensor hardware intensifies as automotive-grade LiDAR oversupply bleeds into industrial allocations, though proprietary command protocols sustain premium capture for vertically integrated suppliers. Quarry operators and earthworks contractors exhibit highest price sensitivity, while Pilbara iron ore majors prioritize availability guarantees over unit economics.
Supply Chain Analysis
Inbound logistics costs from East Asian component ports through Australian bulk terminals constrain just-in-time sensor deployments across Western Australian mine sites. Automotive-grade LiDAR production clusters in China, South Korea, and Japan, with edge computing silicon drawing from Taiwanese foundry capacity and German precision optics. Single-source vulnerability concentrates in solid-state LiDAR emitters and high-temperature ruggedized processors qualified for underground deployment. Distribution runs through OEM captive service networks for tier-one fleet suppliers, while independent integrators leverage regional automation specialists for installation and commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mining automation systems constitute a high-growth disruption propelled by TGA-aligned safety mandates from Australia's national resources regulator compressing deployment timelines beyond standard equipment replacement cycles.
For Market Incumbents: Fortify proprietary command architectures through backward integration into edge computing silicon and perception hardware supply. Deepen captive production of sensor fusion modules to neutralize third-party perception module threats from Chilean copper belt pilots. Expand equipment-as-a-service contracting capabilities to capture recurring revenue streams and lock in long-term fleet relationships.
For New Entrants and Emerging Players: Anchor in Queensland's Bowen Basin metallurgical coal sector, where underground longwall automation penetration lags Western Australian surface haulage. Target open-architecture middleware development bridging Caterpillar MineStar and Komatsu proprietary protocols. Pursue direct contracting with mid-tier coal producers seeking mixed-fleet interoperability without single-vendor lock-in.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automation software specialists holding FAA Part 107 drone operation certifications and open-pit surveying deployment track records. Five-to-ten year viability hinges on regulatory clarity for beyond-visual-line-of-sight operations and interoperability standard adoption. Monitor OSHA proximity mandate enforcement intensity as inflection indicator for sensor system upgrade cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Open-Architecture Middleware Development | Bridges Caterpillar and Komatsu protocols, enabling mixed-fleet deployments for Bowen Basin coal operators. |
| Equipment-as-a-Service Contracting | Transfers utilization risk to OEMs and accelerates refresh cycles in Carajás iron ore operations. |
| Edge Computing Silicon Backward Integration | Reduces latency for autonomous haulage decisions and secures supply against allocation constraints. |
| FAA Part 107 Certification Expansion | Unlocks beyond-visual-line-of-sight drone adoption for blast pattern verification in open-pit mines. |
| Private LTE Network Deployment | Addresses coverage gaps across vast Pilbara pit footprints before autonomous systems achieve designed uptime. |
Research Methodology
The analysis maps autonomous vehicle platforms, fleet management software layers, sensor systems, and communication networks, each validated through mine operations directors, automation engineering leads, OEM procurement teams, and aftermarket service heads. Primary fieldwork combined structured interviews with secondary validation against SEC filings from diversified industrial conglomerates, TGA incident reporting databases, FAA UAS operational waivers, and customs records for LiDAR array trade flows. Bottom-up equipment deployment tallies triangulated against top-down mining capital expenditure surveys.
Consistency checks validated volume and value outputs against external benchmarks including autonomous haul truck fleet counts across Pilbara operations, software licensing disclosure patterns in OEM financial statements, and sensor system upgrade cycles driven by OSHA proximity mandates. Segmentation dimensions spanned product architecture, technology layer, application context, and end-user procurement sophistication. CAGRs derived from equipment replacement cycle compression analysis and recurring revenue displacement ratios in fleet management software.
Decision-makers should treat outputs as directional under assumptions of sustained labor scarcity in Western Australia and continued TGA regulatory tightening; material deviation in autonomous incident reporting thresholds or LiDAR supply allocation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Agricultural Automation Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Multi-Axis Motion Controller Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Drilling Automation Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Hardware in the Loop Market