
 Pick and Place Machines Market | 2026-2036
Pick and Place Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pick and Place Machines Market Analytics
The gap between high-speed surface-mount assembly and flexible robotic handling is narrowing as SCARA and delta architectures absorb semiconductor packaging tasks once reserved for dedicated chip shooters. Panasonic Corporation leverages its legacy in precision motion control to anchor premium electronics lines across East Asian facilities. Yamaha Motor Co., Ltd. competes through compact modular designs that sustain deployment density in crowded factory floors. JUKI Corporation specializes in hybrid platforms that navigate the boundary between rigid automation and collaborative robotics.
Pick and place machines are robotic systems engineered to transfer discrete components between fixed positions with repeatability tolerances often below 0.02 millimetre, serving primarily to automate material handling in high-throughput manufacturing environments. SCARA robots dominate electronics assembly lines where planar precision and vertical rigidity command premium positioning, while delta robots lead in food and beverage sorting applications where multi-axis speed outranks absolute accuracy. Vision systems technology is deepening its integration across all product categories as machine-learning-enabled inspection replaces mechanical fixturing.
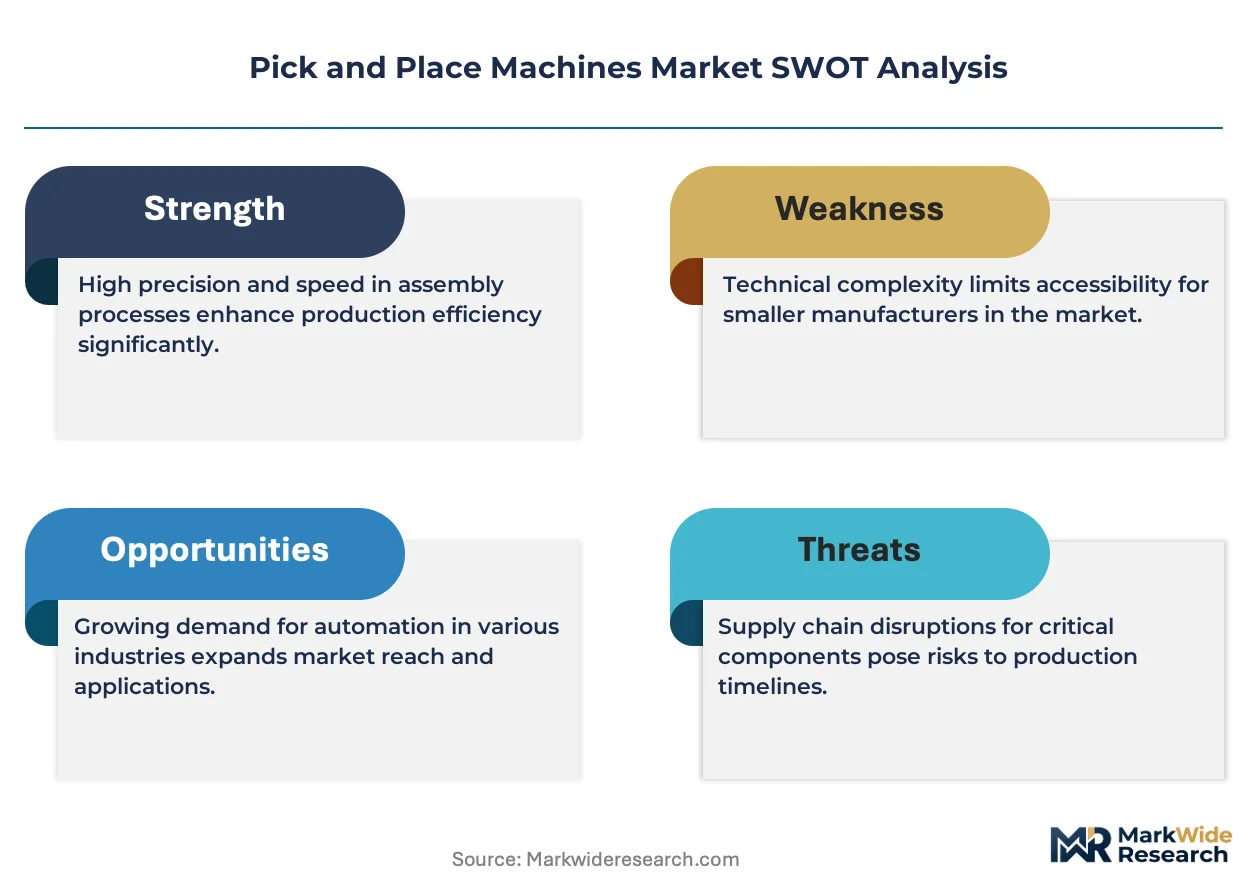
The EU Machinery Directive and CE marking framework shape European procurement by mandating functional safety validations and documented risk assessments before market entry. China's SAMR enforces GB standards for industrial robot electromagnetic compatibility and operational safety that manufacturers must satisfy for domestic sales. Japan's METI coordinates national robot strategies that subsidize SME automation upgrades, directly expanding addressable demand. Stakeholders must weigh whether to prioritize speed specifications for consumer electronics contracts or flexibility ratings for automotive assembly programs with shorter product lifecycles.
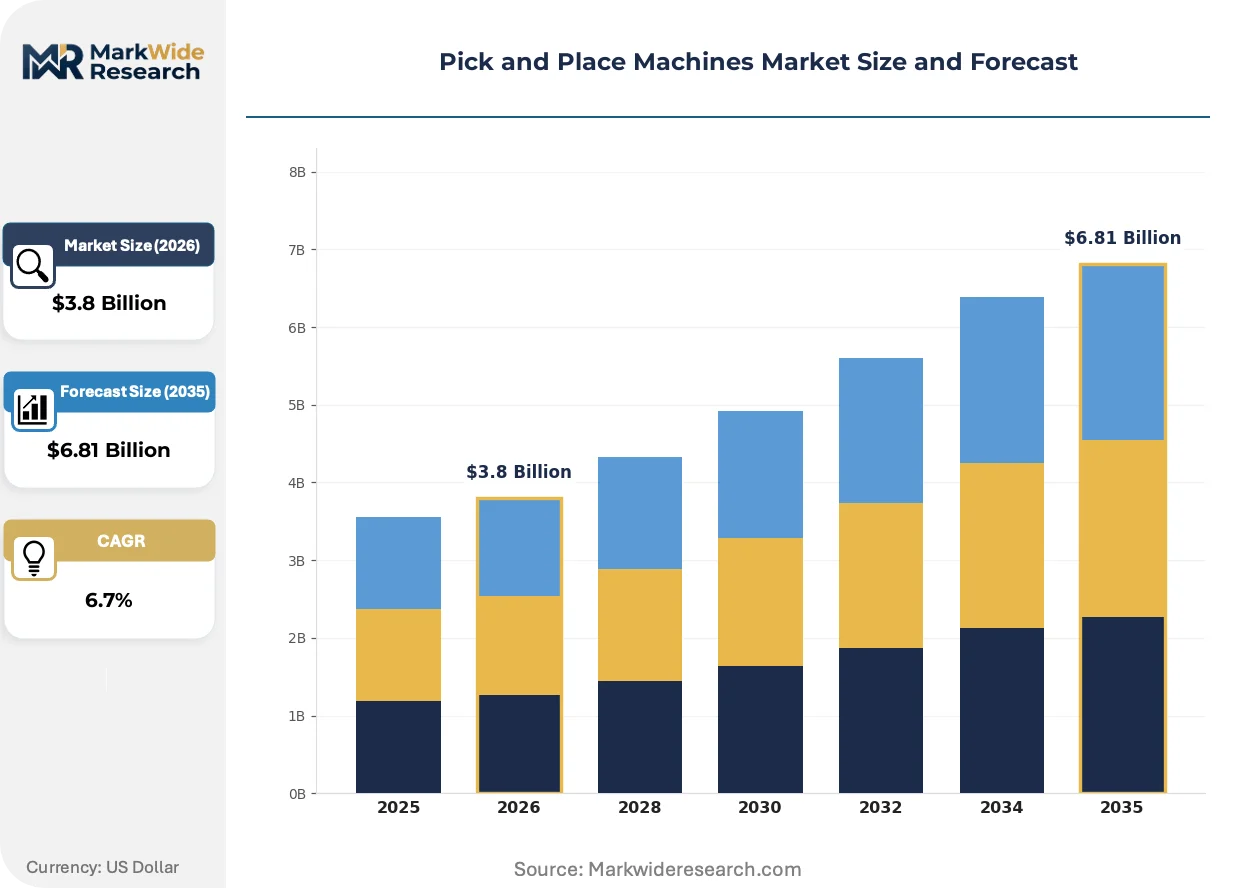
Market Dynamics
Component miniaturization below 01005 metric dimensions is compressing placement tolerances and forcing machine architectures toward linear motor stages and active vibration damping. This precision escalation is redistributing competitive advantage toward suppliers with captive motion-control competencies.
Growth Catalysts
- CE marking compliance mandates:The EU Machinery Directive's 2023 updates require documented functional safety validations for collaborative pick-and-place installations, accelerating replacement cycles in European electronics facilities.
- Semiconductor packaging densification:Fan-out wafer-level packaging demands sub-10-micron placement accuracy that legacy chip shooters cannot sustain, pulling demand toward multi-axis SCARA platforms.
- Vietnam electronics corridor expansion:Contract manufacturers are relocating final assembly from coastal China to northern Vietnamese industrial zones, driving greenfield machine procurement.
Market Restraints
- Linear encoder supply concentration:High-resolution glass-scale encoders for sub-micron feedback depend on Japanese and German component suppliers, exposing lead-time vulnerability.
- Rare-earth magnet cost volatility:Neodymium-iron-boron permanent magnets in direct-drive motors face price swings tied to Chinese export quota policies.
- Mechanical fixture obsolescence:Vision-guided placement is eliminating dedicated mechanical tooling for product changeovers, stranding capital in legacy hardware.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for mobile phone and component manufacturing are creating first-mover advantage for machine vendors establishing local service infrastructure.
- Battery cell stacking automation:Lithium-ion electrode and separator placement in gigafactories applies pick-and-place precision to electrochemical assembly, opening a parallel demand vertical.
- Vision-AI convergence:Deep-learning defect detection integrated into placement heads enables real-time quality gates that reduce downstream rework.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of precision motion systems requires cross-trained personnel fluent in servo tuning, optics alignment, and PLC diagnostics, a profile in short supply across manufacturing hubs.
- CE certification timeline compression:Third-party notified body queues for Machinery Directive conformity assessment now extend 14-20 weeks, delaying European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pick and Place Machines Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, Delta Robots, SCARA Robots, Cartesian Robots End User: Electronics Manufacturing, Food & Beverage, Automotive Assembly, Consumer Goods Technology: Vision Systems, Force Sensing, AI Integration, PLC Control Application: Packing, Sorting, Assembly, Loading |
| Companies Covered | Fuji Machine Manufacturing Co., Ltd., Panasonic Corporation, Yamaha Motor Co., Ltd., JUKI Corporation, Hanwha Corporation, ASM Assembly Systems, Mycronic AB, Europlacer Group, DDM Novastar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pick and Place Machines Market Evolving Landscape
Machine architectures are converging around software-defined motion profiles that decouple hardware kinematics from process programming. This abstraction layer is collapsing the traditional boundary between dedicated SMT placement and flexible robotic handling.
Linear motor direct-drive stages are migrating from high-end semiconductor backend equipment toward mid-tier electronics assembly platforms. EMS providers in South Korea and Taiwan are adopting these frictionless motion systems to sustain throughput without mechanical wear degradation. The shift is compressing maintenance intervals from quarterly to annual cycles while enabling acceleration profiles that belt-driven axes cannot match.
China's SAMR enforcement of updated GB/T industrial robot electromagnetic compatibility standards is forcing firmware redesigns for machines sold domestically. The regulations mandate radiated emission limits that legacy controller architectures fail to meet without shielding retrofits. European and Japanese vendors are responding by pre-certifying new controller generations to dual CE-GB compliance, treating China as a non-negotiable design constraint.
Contract manufacturers are consolidating machine procurement under fleet-management agreements that bundle hardware, software licenses, and predictive maintenance. This servitization displaces traditional capital purchase models in automotive electronics programs where product lifecycles compress below 18 months. The transition is most advanced in German and Czech automotive supplier parks, where total-cost-of-ownership contracts now dominate tender evaluations.
Pick and Place Machines Market Segmentation
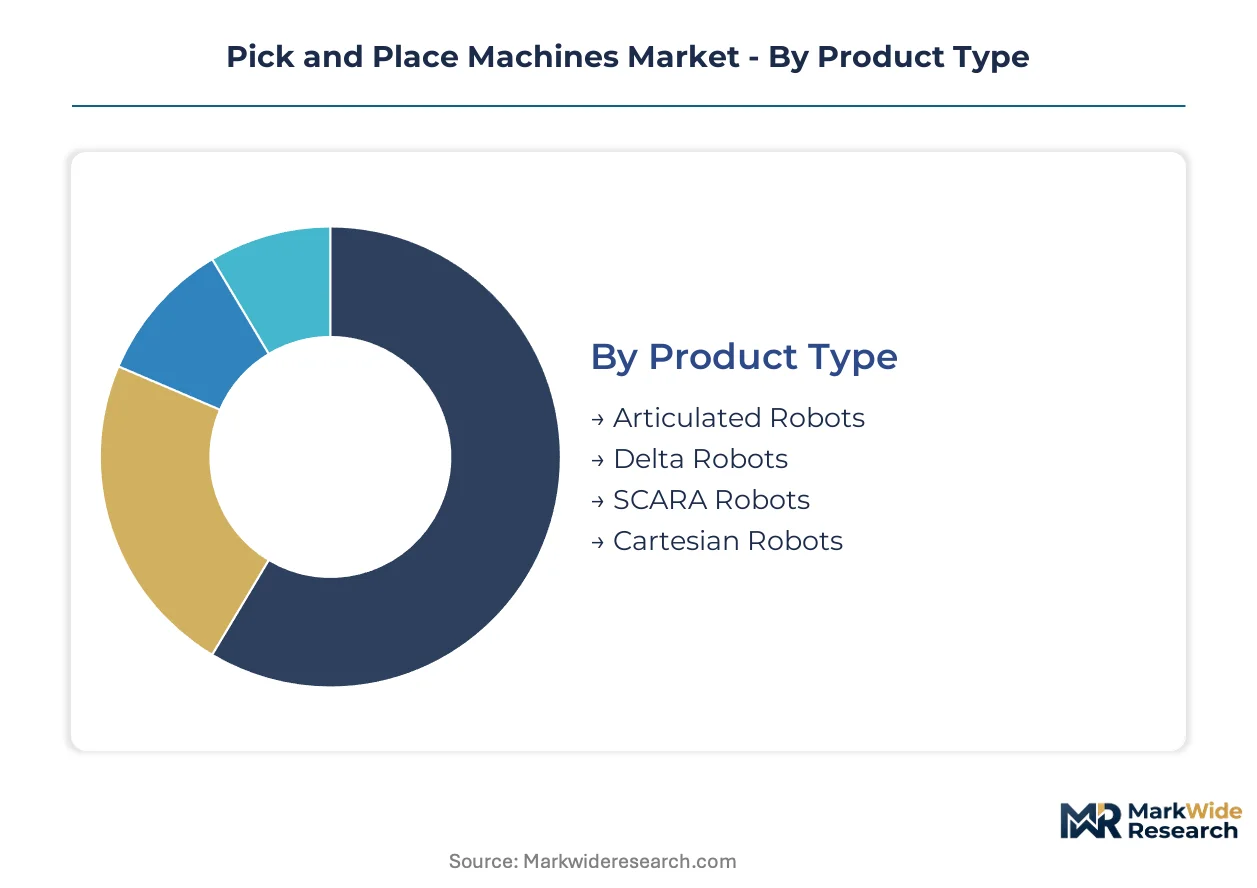
Segmentation in pick and place machines separates capital deployment patterns from operational flexibility requirements. Procurement cycles vary dramatically across robot architectures and end-use verticals, with electronics contracts demanding 18-month refresh rates while food processing installations stretch toward seven-year horizons.
Product Type:
Cycle times compress fastest in delta configurations where parallel kinematics enable 300+ picks per minute, while articulated platforms absorb the longest validation periods for automotive safety-critical applications.
- Delta Robots:Parallel-arm architectures achieve sub-50-millisecond cycle times through lightweight carbon-fiber linkages and fixed-base motor placement. Electronics sorting facilities in Vietnam and South Korea deploy these for chip testing and tray handling where throughput trumps reach envelope. Force-limited variants now penetrate collaborative food packaging lines previously blocked by caging requirements.
- SCARA Robots:Selective Compliance Articulated Robot Arm designs combine planar flexibility with vertical rigidity through harmonic drive joints. Semiconductor backend operations in Taiwan and Japan specify these for die bonding and flip-chip placement where Z-axis deflection must stay below 5 microns. The cylindrical work envelope suits densely packed SMT lines where floor space commands premium pricing.
- Articulated Robots:Six-axis serial kinematics deliver the largest reachable workspace and payload capacity among pick and place categories. Automotive battery module assembly in Germany and the United States deploys these for heavy cell stacking operations.
- Cartesian Robots:Gantry-mounted linear axis systems provide deterministic positioning at the lowest mechanical complexity. Bulk material handling in Chinese consumer goods factories favors these for cost-sensitive palletizing tasks.
SCARA robots anchor the volume base while delta configurations gain share at the steepest rate in electronics contract manufacturing.
End User:
Margin structures diverge sharply across verticals, with semiconductor packaging commanding 40-60% equipment gross margins while food processing procurement squeezes vendors toward 15-20%.
- Electronics Manufacturing:Surface-mount technology lines drive the most demanding precision specifications, with 01005 metric component handling requiring vision-guided placement below 30-micron repeatability. Taiwanese and Vietnamese EMS providers are consolidating procurement under fleet-management contracts that bundle predictive maintenance.
- Automotive Assembly:Electric vehicle battery production applies pick and place precision to electrode stacking and separator insertion in gigafactories. German and Czech automotive supplier parks now specify total-cost-of-ownership contracts rather than capital purchase models.
- Food & Beverage:Hygienic design requirements dominate procurement, with IP69K washdown ratings and stainless steel construction adding 25-35% cost premiums over standard industrial variants. Primary demand concentrates in dairy processing and ready-meal packaging.
- Consumer Goods:High-mix, low-volume production favors reconfigurable platforms with quick-change end effectors. Personal care and cosmetics packaging lines in France and Italy drive European demand.
Electronics manufacturing captures the dominant revenue share while automotive assembly expands most quickly on battery cell automation.
Technology:
Supply concentration clusters around vision system providers, with German and Japanese component suppliers controlling high-resolution encoder and lens assembly markets.
- Vision Systems:Machine-learning-enabled cameras now handle fiducial recognition, defect detection, and dynamic path correction without mechanical fixturing. South Korean EMS providers are deploying these for real-time quality gates that eliminate downstream rework stations.
- AI Integration:Deep learning models trained on placement defect databases enable predictive maintenance and autonomous parameter tuning. These systems reduce setup times for product changeovers from hours to minutes.
- Force Sensing:Six-axis torque sensors enable delicate component handling and human-robot collaboration without safety barriers. Medical device assembly in Switzerland and Germany specifies these for implantable component placement.
- PLC Control:Traditional ladder-logic architectures persist in brownfield installations where interoperability with legacy factory networks takes priority over advanced motion capabilities.
Vision systems constitute the installed technology base while AI integration climbs the fastest as firmware updates retrofit existing hardware.
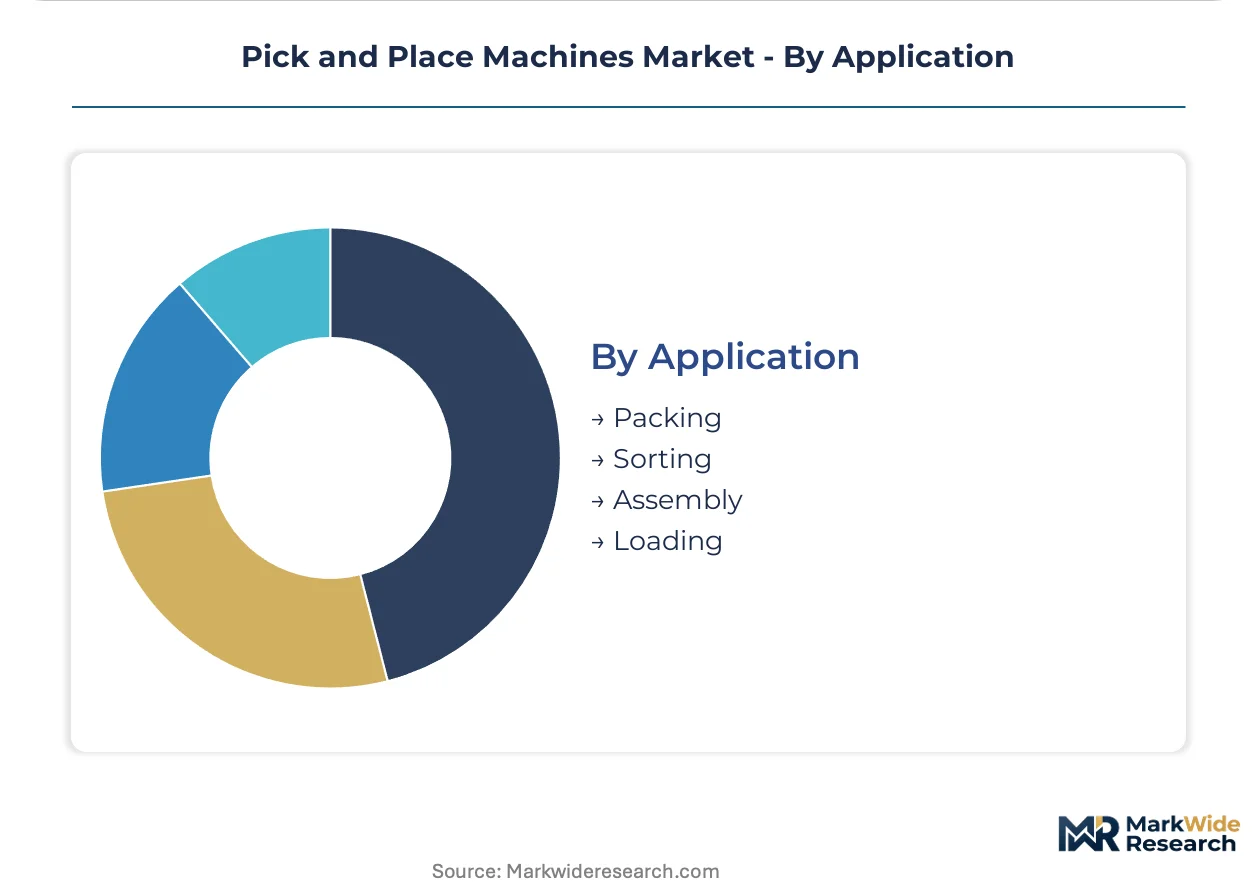
Application:
Customer type stratification separates high-volume OEMs with captive engineering teams from contract manufacturers dependent on vendor integration support.
- Assembly:Precision component mating operations demand the tightest tolerances and most sophisticated force-control feedback. Semiconductor packaging and medical device manufacturing concentrate demand here.
- Sorting:High-speed classification by weight, vision, or spectral signature drives delta robot adoption in logistics and food processing. E-commerce fulfillment centers in the United States and Germany are expanding these installations.
- Packing:End-of-line case packing and palletizing favors Cartesian and articulated platforms with extended reach envelopes. Consumer goods factories in China and Mexico absorb the largest volume.
- Loading:Machine tending and press-to-press transfer operations require robust payload capacity and repeatable positioning. Metal forming and plastics injection molding supply the primary demand.
Assembly commands the premium pricing tier while sorting applications scale most rapidly on e-commerce logistics investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision equipment flows into Vietnamese electronics corridors as contract manufacturers relocate final assembly capacity from coastal China to northern industrial zones around Hanoi and Bac Ninh.
China
Domestic EMS providers in Shenzhen and Dongguan are upgrading surface-mount lines to handle 01005 metric components for consumer electronics contracts. SAMR enforces updated GB/T electromagnetic compatibility standards that require firmware redesigns for controller architectures. The Yangtze River Delta cluster around Shanghai absorbs the largest share of new SCARA deployments for semiconductor backend operations.
Germany
Automotive supplier parks in Bavaria and Baden-Württemberg specify total-cost-of-ownership contracts for battery cell stacking automation in electric vehicle gigafactories. CE marking compliance under the EU Machinery Directive mandates functional safety validations with 14-20 week third-party assessment timelines. The Stuttgart industrial corridor concentrates demand for articulated platforms in heavy payload battery module assembly.
Vietnam
Contract manufacturers are establishing greenfield SMT facilities in northern provinces to serve smartphone and laptop assembly contracts migrating from China. The Ministry of Industry and Trade coordinates investment incentives for electronics manufacturing zones. Bac Ninh and Vinh Phuc provinces host the densest concentration of new pick and place machine installations.
United States
E-commerce fulfillment centers in Texas and California are expanding delta robot installations for high-speed parcel sorting and tray handling operations. OSHA maintains workplace safety standards for collaborative robotic installations that influence procurement specifications. The Dallas-Fort Worth logistics corridor drives regional demand for vision-guided sorting systems.
South Korea
EMS providers in Gyeonggi Province are consolidating procurement under fleet-management agreements that bundle predictive maintenance with hardware deployment. METI-coordinated automation subsidies in neighboring Japan create competitive pressure for domestic upgrade cycles. The Suwon-Incheon manufacturing belt leads adoption of linear motor direct-drive stages for frictionless high-throughput assembly.
Pick and Place Machines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Japanese and European vendors anchor premium electronics lines through captive motion-control competencies, while modular specialists penetrate mid-tier contract manufacturing. Three archetypes dominate: precision-motion incumbents with semiconductor heritage, compact-platform specialists optimizing floor-space constraints, and hybrid-system integrators bridging rigid automation with collaborative robotics. Competitive moves concentrate on servitization bundling and firmware pre-certification to dual compliance regimes.
Within the precision-motion tier, Fuji Machine Manufacturing Co., Ltd. and Panasonic Corporation exemplify Japanese incumbents with legacy positioning in East Asian electronics facilities. Yamaha Motor Co., Ltd. occupies a compact-modular position that sustains deployment density in space-constrained factory environments. JUKI Corporation represents the hybrid-architecture approach, navigating boundaries between traditional automation and collaborative robotic systems.
| Leading Market Players |
|---|
| Fuji Machine Manufacturing Co., Ltd. |
| Panasonic Corporation |
| Yamaha Motor Co., Ltd. |
| JUKI Corporation |
| Hanwha Corporation |
| ASM Assembly Systems |
| Mycronic AB |
| Europlacer Group |
| DDM Novastar |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight volatility transmits directly into landed cost spreads for European electronics manufacturers sourcing precision motion components from East Asian foundries. This logistics tension amplifies the pricing power held by Japanese and German encoder suppliers while forcing contract manufacturers to absorb margin compression or pass through to automotive OEMs.
Pricing Analysis
Next-generation linear motor direct-drive platforms command 40-60% premiums over belt-driven legacy systems, while mid-tier SCARA configurations face price erosion from Chinese domestic competition. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade precision from food-handling durability tiers. Cost compression in standard-tier electronics assembly is intensifying because Vietnamese contract manufacturers consolidate procurement under fleet-management contracts. Automotive battery assembly programs exhibit the lowest price sensitivity due to total-cost-of-ownership contracting, while consumer goods packaging lines in China remain highly sensitive to per-unit capital expenditure.
Supply Chain Analysis
Rare-earth magnet feedstock for direct-drive motors draws primarily from Chinese separation facilities, with secondary refining concentrated in Japan and Germany. High-resolution glass-scale encoders, harmonic drive gears, and machine-vision lens assemblies constitute critical component dependencies. Single-source vulnerability in linear encoder supply exposes lead-time risk for sub-micron positioning systems. Distribution runs through OEM-direct channels for premium semiconductor equipment, while contract manufacturers in Vietnam and India source through regional distributor networks with localized service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors who control captive motion-control competencies, yet mechatronics technician scarcity constrains maintenance scalability across manufacturing hubs. This capability gap favors suppliers with predictive maintenance infrastructure and training academy investments.
For Market Incumbents: Insulate premium positioning by deepening backward integration into linear motor and encoder production, reducing exposure to Japanese component lead times. Accelerate firmware pre-certification to dual CE-GB compliance before SAMR enforcement windows tighten. Defend against modular Chinese competitors by embedding AI-driven vision systems that raise switching costs for EMS fleet contracts. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized electronics manufacturing zones where local service infrastructure remains underdeveloped. Target mid-tier automotive battery assembly with Cartesian platforms optimized for electrode stacking precision at 30% cost reduction versus articulated alternatives. Pursue servitization partnerships with regional distributors to overcome capital purchase resistance among SME contract manufacturers. For Investors and Strategic Acquirers: CE marking timeline compression reshapes the acquisition landscape toward pre-certified controller architectures that bypass 14-20 week third-party queues. Five-to-ten year viability hinges on software-defined motion abstraction layers that decouple hardware from process programming. Monitor linear encoder supply concentration as an inflection signal—disruption events would accelerate captive production investments and reshape vendor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Pre-Certification to Dual CE-GB Compliance | SAMR electromagnetic compatibility enforcement in China eliminates non-compliant legacy controllers from domestic sales channels. |
| Predictive Maintenance Infrastructure Deployment | Fleet-management contracts in German automotive supplier parks now mandate uptime guarantees and remote diagnostics capability. |
| Linear Motor Direct-Drive Stage Integration | South Korean EMS providers adopt frictionless motion systems to compress maintenance intervals from quarterly to annual cycles. |
| Vision-AI Convergence in Placement Heads | Deep-learning defect detection enables real-time quality gates that eliminate downstream rework stations in Vietnamese SMT lines. |
| Regional Service Academy Establishment | India's PLI scheme creates first-mover advantage for vendors training local mechatronics technicians to support electronics manufacturing zones. |
Research Methodology
The analysis maps SCARA, delta, articulated, and Cartesian robot architectures, each validated through plant engineers at Taiwanese EMS providers, maintenance directors at German automotive supplier parks, procurement leads at Vietnamese contract manufacturers, and aftermarket service heads at Japanese precision equipment vendors. Primary interview findings triangulate against customs records for precision motion component trade flows, SEC filings from listed automation suppliers, SAMR and METI regulatory disclosure databases, and IHS Markit electronics manufacturing capacity trackers. Bottom-up installation counts across 15 country-level manufacturing clusters reconcile with top-down equipment spending estimates from national industrial automation associations.
Assumptions hold fixed the current regulatory enforcement trajectory for CE marking and GB/T electromagnetic compatibility standards, while varying semiconductor packaging densification rates and battery gigafactory buildout timelines across the projection horizon. Segmentation dimensions include robot kinematic architecture, end-use vertical precision requirements, vision system integration depth, and regional manufacturing cluster maturity. CAGRs derive from installed base depreciation curves and greenfield capacity announcements. Forecast inputs incorporate rare-earth magnet price volatility bands and linear encoder supply lead-time scenarios.
Sensitivities concentrate around SAMR enforcement acceleration, Vietnam electronics corridor labor cost inflation, and linear encoder supply disruption events. Cross-checking against SEMI equipment spending surveys and national robotics association shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
Drilling Automation Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Electric Linear Actuator Market