
 Industrial Automation Products Market | 2026-2036
Industrial Automation Products Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Automation Products Market Analysis
Software-defined maintenance subscriptions is recalibrating how automation vendors monetize hardware deployments. Siemens AG leverages its digital twin ecosystem to lock in recurring revenue from plant operators. Rockwell Automation Inc. anchors its North American position through embedded analytics contracts that extend hardware replacement cycles.
Industrial automation products encompass electromechanical and software systems that execute, monitor, and optimize manufacturing and process operations with response times measured in milliseconds and precision tolerances reaching micrometer scales. These systems enable continuous production flows, defect reduction, and labor substitution across heavy and discrete manufacturing environments. Controllers and robotics currently command the deepest margin pools, while IoT-enabled sensor networks represent the fastest-expanding technology layer as edge computing architectures proliferate. Process control applications in pharmaceuticals and food processing sustain premium pricing due to validation requirements and hygienic design standards.
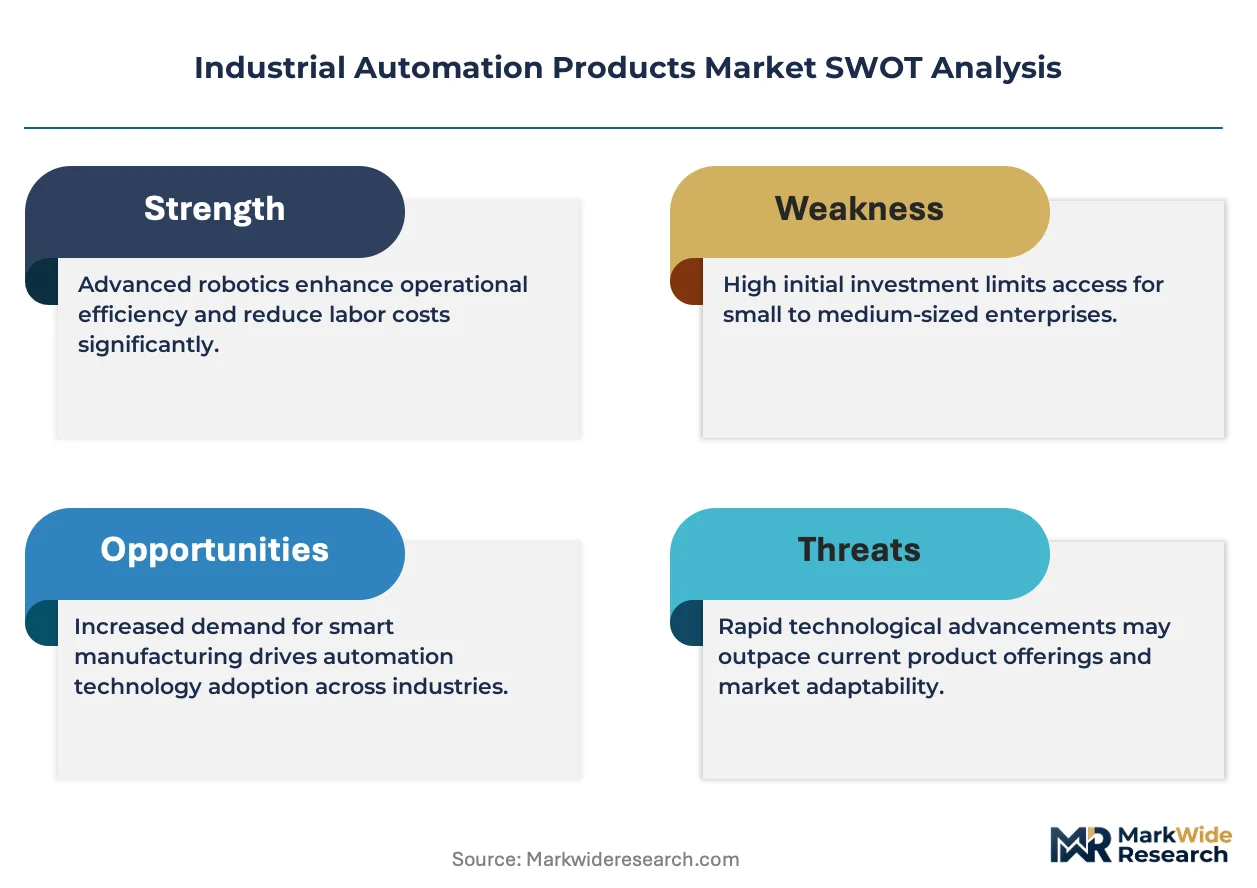
The EU AI Act and IEC 61508 functional safety standards are reshaping product certification pathways for autonomous systems sold into European process industries. FDA validation guidelines for automated pharmaceutical manufacturing equipment create parallel compliance obligations in the United States. NHTSA and OSHA frameworks further govern robotic safety in automotive and general industrial settings. Stakeholders must track divergence between regional AI liability regimes and functional safety mandates to avoid stranded product development cycles.
Market Dynamics
Software-defined maintenance subscriptions are recalibrating how automation vendors monetize hardware deployments, locking plant operators into recurring revenue streams that extend hardware replacement cycles and deepen vendor switching costs.
Growth Catalysts
- EU AI Act compliance mandates:European factories face tightening conformity requirements for autonomous decision-making systems, forcing controller and sensor upgrades across process industries.
- Automotive OEM robotics expansion:Collaborative robotics deployment on assembly floors accelerates demand for precision actuators and safety-rated controllers.
- German industrial belt concentration:Machine-tool density around Stuttgart and Munich sustains premium uptake of high-precision sensors and distributed control systems.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motors and precision servo systems depend on concentrated upstream processing, exposing robotics and motion control to input volatility.
- IEC 61508 certification timelines:Functional safety validation for autonomous systems extends product development cycles and delays revenue recognition for safety-critical controllers.
- Edge computing skill scarcity:IT-OT convergence requires hybrid competencies that outpace workforce development, constraining deployment velocity of integrated automation architectures.
Strategic Opportunities
- Pharmaceutical validation equipment:FDA validation guidelines for automated manufacturing create parallel compliance obligations that sustain premium pricing for hygienic-design controllers and batch management systems.
- Food processing hygienic automation:Clean-in-place requirements and allergen control protocols drive replacement demand for stainless-steel robotics and washdown-rated sensors.
- Digital twin convergence:Physics simulation and real-time operational data unification enables predictive maintenance contracts that transform capital equipment into recurring revenue streams.
Industry Challenges
- Legacy PLC integration complexity:Brownfield facilities operate decades-old control systems that resist seamless connectivity with modern IoT sensor networks and cloud analytics platforms.
- Cross-functional talent gaps:Mechatronics engineers who bridge mechanical design, embedded software, and network security remain scarce relative to deployment demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Automation Products Market |
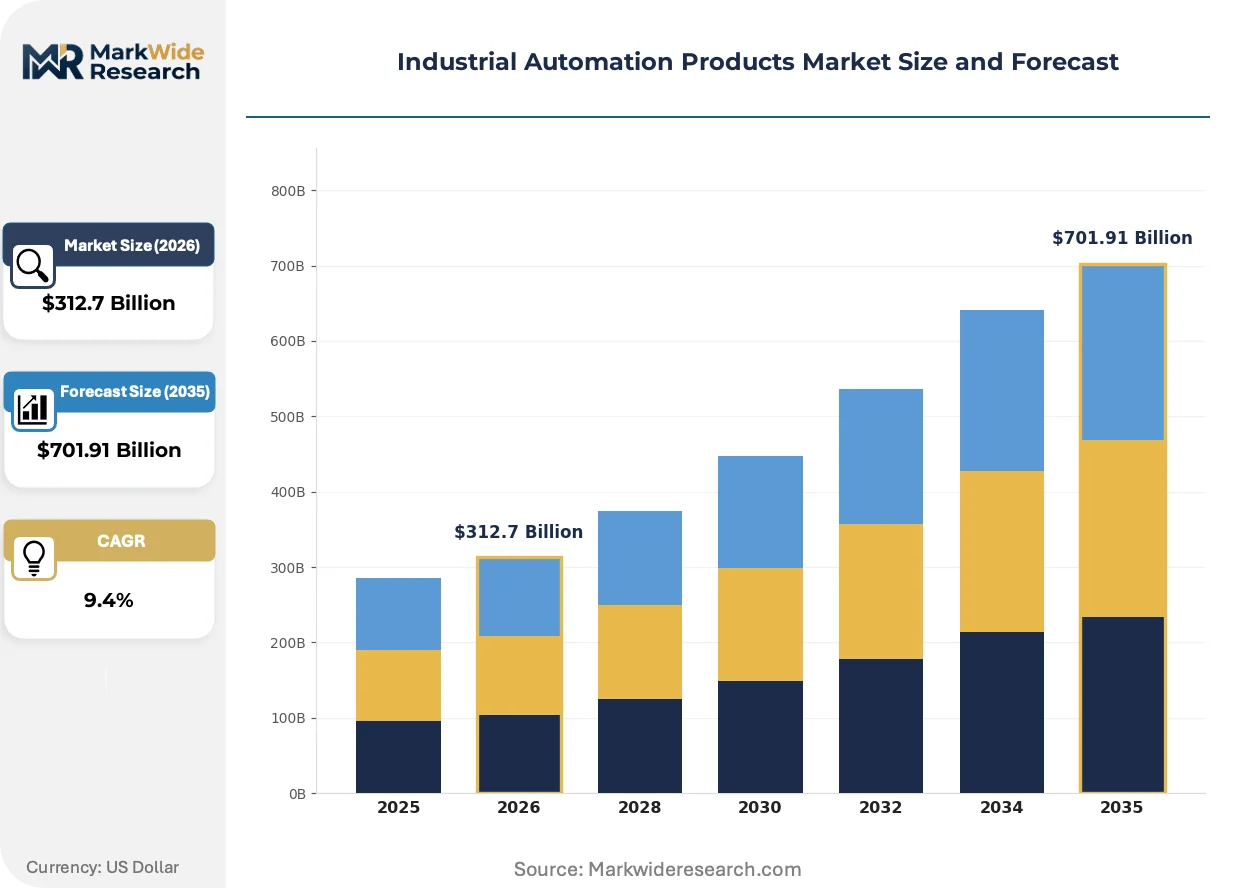
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $701.91 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Controllers, Actuators, Robotics Technology: PLC, SCADA, DCS, IoT Application: Manufacturing, Process Control, Assembly, Material Handling End User: Automotive OEMs, Food & Beverage, Pharmaceuticals, Electronics |
| Companies Covered | ABB Ltd., Siemens AG, Rockwell Automation Inc., Schneider Electric SE, Emerson Electric Co., Honeywell International Inc., Mitsubishi Electric Corporation, Omron Corporation, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Automation Products Market Emerging Trajectories
Edge-native architectures are compressing response latencies from milliseconds to microseconds while fragmenting traditional hierarchical control topologies. This shift demands reconfigured hardware portfolios and new partnership models between automation vendors and silicon suppliers.
Time-sensitive networking over standard Ethernet is unifying deterministic control traffic and best-effort IT data on shared infrastructure. Automotive battery manufacturers in South Korea and Germany deploy single-cable architectures that eliminate redundant wiring harnesses. This convergence is collapsing the traditional separation between plant-floor control networks and enterprise systems, forcing vendors to defend proprietary fieldbus territories.
OSHA robotic safety frameworks and NHTSA autonomous equipment guidelines are tightening collision-avoidance and force-limiting requirements for collaborative installations. Manufacturers must now certify systems against multiple jurisdictional standards simultaneously. Small and mid-sized metalworking shops in the US Midwest delay robot purchases pending clarity on liability allocation between integrators and end-users.
Subscription-based performance contracts are displacing perpetual software licenses and break-fix maintenance agreements. German automotive suppliers now specify uptime guarantees rather than equipment specifications in procurement tenders. This shift concentrates risk with automation vendors while rewarding predictive analytics capabilities over hardware durability.
Industrial Automation Products Market Segmentation
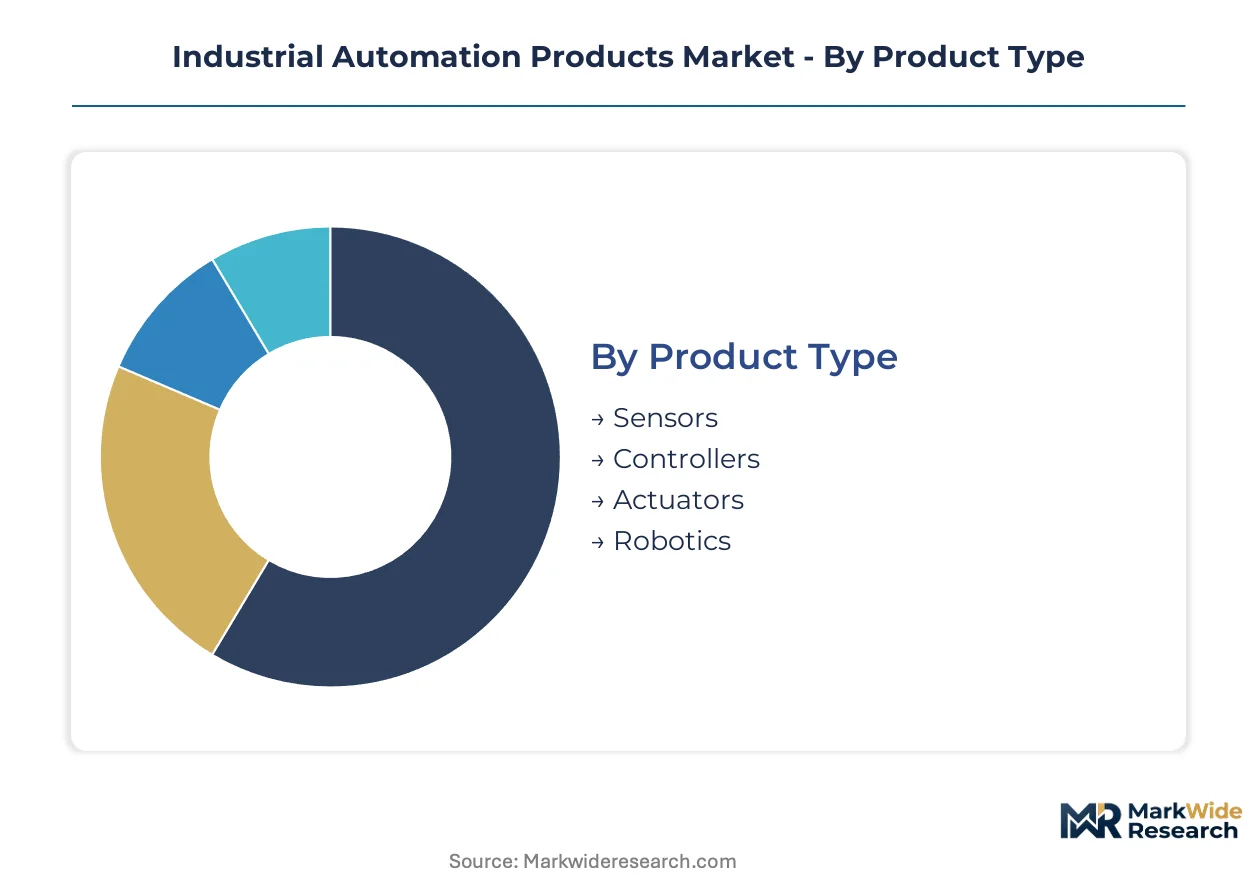
Segmentation in industrial automation products reveals how purchasing criteria diverge across technical sophistication levels, regulatory exposure, and operational scale. Buyers in automotive OEMs prioritize cycle-time precision and safety certification depth, while pharmaceutical operators weight validation documentation and hygienic design above raw throughput metrics.
Product Type:
Cost tier separates commodity sensing from premium motion control, with procurement budgets clustering around precision requirements and replacement cycle expectations.
- Sensors:Photoelectric, proximity, and vision systems detect position, presence, and quality deviations with micron-level accuracy. Demand concentrates in Germany's machine-tool belt around Stuttgart, where high sensor density supports predictive maintenance contracts and minimizes unplanned downtime in automotive stamping operations.
- Controllers:PLCs, PACs, and industrial PCs execute logic sequences with deterministic cycle times measured in milliseconds. Automotive OEMs in South Korea specify these for battery assembly lines, driven by IEC 61508 functional safety mandates and the need for synchronized multi-axis coordination.
- Actuators:Electric, pneumatic, and hydraulic motion devices convert control signals into mechanical force. Precision servo actuators command premium positioning in semiconductor fabrication.
- Robotics:Articulated arms, SCARA systems, and collaborative cobots perform repetitive or hazardous tasks. Collaborative variants face OSHA and NHTSA safety certification requirements in US installations.
Volume sits with sensors; growth tilts toward robotics.
Technology:
Application maturity distinguishes legacy control architectures from edge-native platforms, with brownfield constraints preserving incumbent systems while greenfield sites adopt converged infrastructure.
- PLC:Programmable logic controllers remain the workhorse for discrete manufacturing, executing ladder logic with hardened reliability. Food and beverage processors in the US Midwest retain these for washdown environments, constrained by legacy integration complexity and limited IT-OT bridge compatibility.
- SCADA:Supervisory control and data acquisition systems provide centralized visualization across distributed assets. Water treatment utilities and oil refineries deploy these for wide-area monitoring.
- DCS:Distributed control systems dominate continuous process industries with integrated loop control and alarm management. Pharmaceutical batch reactors depend on these for FDA validation compliance.
- IoT:Edge-enabled sensor networks and cloud-connected analytics platforms expand fastest, collapsing data silos between plant floors and enterprise systems.
Installed base concentrates in PLC and DCS; expansion concentrates in IoT.
Application:
Margin structure varies by validation burden and precision requirement, with regulated process applications sustaining premium pricing against commoditized material handling.
- Manufacturing:Discrete production lines for automotive, electronics, and consumer goods demand high-speed synchronization and rapid changeover capability. Electronics contract manufacturers in Taiwan and South Korea drive uptake of compact controllers and high-speed pick-and-place robotics.
- Process Control:Continuous operations in chemicals, pharmaceuticals, and energy require closed-loop stability and exhaustive documentation. EU AI Act compliance is forcing controller upgrades in European chemical plants.
- Assembly:Precision joining, fastening, and inspection operations favor collaborative robotics with force-limiting safety features.
- Material Handling:Conveyance, sorting, and warehousing applications prioritize throughput economics over precision, with AGVs and AMRs gaining deployment in e-commerce fulfillment.
Revenue clusters in manufacturing; steepest expansion trajectory emerges in process control.
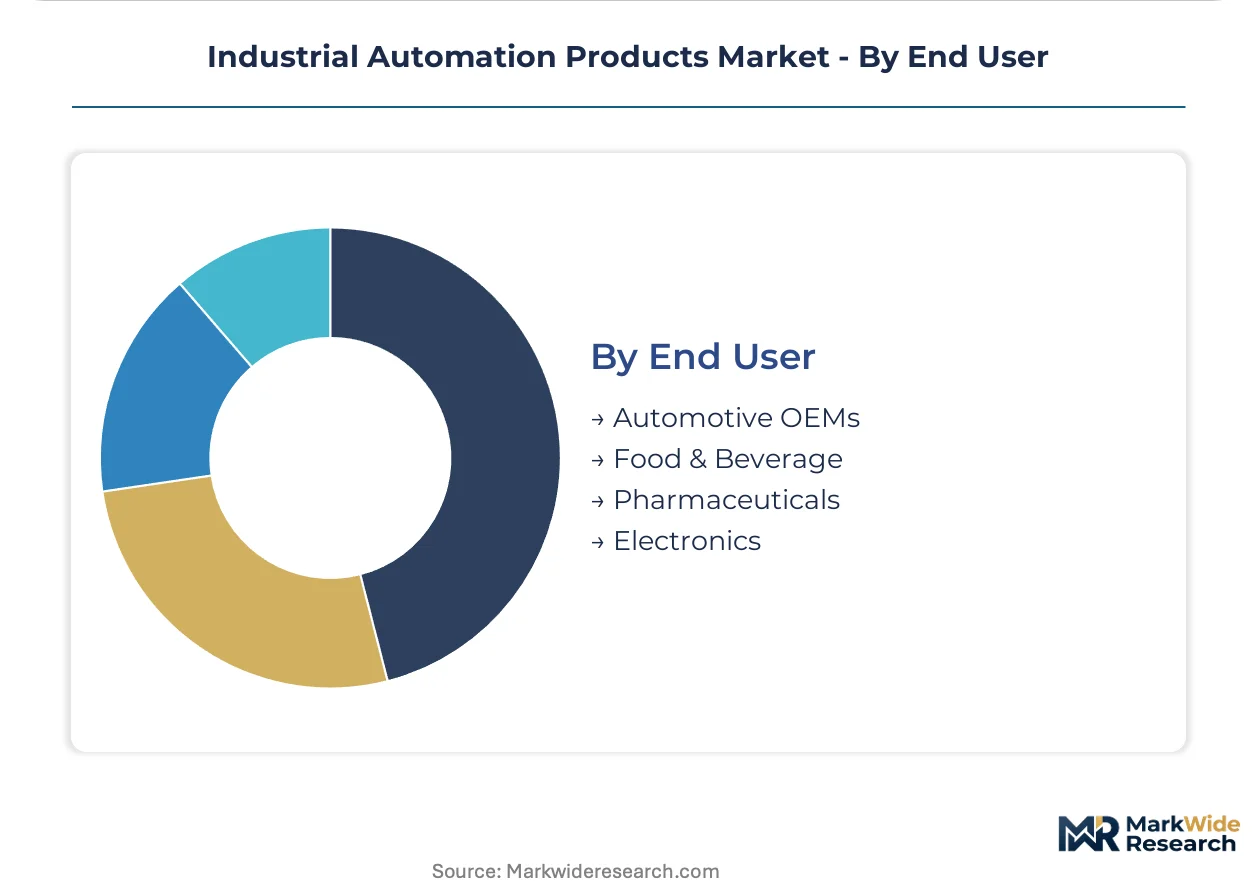
End User:
Procurement sophistication separates specification-driven OEMs from compliance-heavy regulated industries, with contract structures and vendor relationships diverging accordingly.
- Automotive OEMs:Vehicle manufacturers specify collaborative robotics and precision actuators for final assembly, driven by model-mix flexibility requirements and ergonomic injury reduction targets. German suppliers now negotiate uptime guarantees rather than equipment specifications.
- Food & Beverage:Clean-in-place requirements and allergen control protocols demand stainless-steel robotics and washdown-rated sensors. FDA validation guidelines constrain controller selection in US dairy processing.
- Pharmaceuticals:Batch consistency and contamination prevention sustain premium pricing for hygienic-design controllers and validated batch management systems.
- Electronics:Miniaturization trends and cleanroom requirements drive demand for precision motion control and particulate-resistant enclosures.
Spend concentrates with automotive OEMs; contract value expands fastest in pharmaceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and Japan, while consumption growth tilts toward China and the United States. Regulatory divergence across these markets is fragmenting certification pathways for autonomous systems.
United States
Automotive OEMs in Michigan and Ohio deploy collaborative robotics for ergonomic assembly operations. OSHA robotic safety frameworks tighten collision-avoidance requirements for installations. Detroit's stamping plants sustain demand for precision sensors and force-limiting actuators.
Germany
Machine-tool density around Stuttgart and Munich drives premium uptake of distributed control systems and high-precision sensors. EU AI Act compliance mandates force controller upgrades across process industries. Bavaria's automotive suppliers negotiate uptime guarantees rather than equipment specifications in procurement tenders.
China
Electronics contract manufacturers in the Yangtze River Delta and Pearl River Delta absorb compact controllers and high-speed pick-and-place robotics. MIIT standards govern industrial internet platform interoperability. Shenzhen's battery assembly lines specify synchronized multi-axis coordination systems.
Japan
Semiconductor fabricators in Kyushu and Chubu demand precision servo actuators with micrometer positioning tolerance. METI policies promote smart factory adoption through subsidy programs. Nagoya's automotive component suppliers integrate edge-native architectures for microsecond response latencies.
South Korea
Battery manufacturers deploy single-cable Time-Sensitive Networking architectures that eliminate redundant wiring harnesses. MFDS validation requirements constrain pharmaceutical automation equipment selection. Ulsan's petrochemical complexes sustain demand for distributed control systems with integrated loop control.
Industrial Automation Products Market Vendor Landscape
Top-tier vendors anchor the premium controller and robotics segment, while mid-tier specialists occupy niche sensing and actuation categories. The vendor base stratifies across three tiers: diversified industrial conglomerates with full-stack portfolios, regional automation specialists with deep vertical expertise, and emerging IoT-native platform providers. Competitive positioning hinges on digital twin ecosystem breadth and predictive maintenance contract penetration. M&A activity targets edge computing software assets, while strategic partnerships between automation vendors and silicon suppliers reconfigure hardware procurement channels.
Among European-based industrial conglomerates, Siemens AG and ABB Ltd. exemplify the diversified full-stack archetype, anchoring premium positioning through recurring revenue models and digital twin convergence. Rockwell Automation Inc. represents the North American specialist tier, embedding analytics capabilities that extend hardware replacement cycles and deepen customer switching costs. These three entities collectively illustrate how vendor strategies diverge between ecosystem lock-in and vertical expertise deepening.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Rockwell Automation Inc. |
| Schneider Electric SE |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| Omron Corporation |
| Yokogawa Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Mechatronics engineers concentrated in Germany's Stuttgart-Munich corridor command wage premiums that compress pricing-tier spreads between premium controllers and standard PLCs, forcing vendors to absorb labor-cost differentials through software bundling rather than hardware markups.
Pricing Analysis
Margin tightening in safety-certified controllers reflects IEC 61508 validation timelines that extend product development cycles and defer revenue recognition. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from washdown-rated food equipment and commodity sensors. Price differentiation hinges on certification depth and after-sales service bundling. Automotive OEMs in South Korea exhibit lowest price sensitivity due to uptime guarantee procurement models, while US Midwest metalworking shops delay purchases pending liability clarity.
Supply Chain Analysis
Refurbishment flows for legacy PLCs from brownfield US facilities create secondary supply channels that undercut new controller pricing in price-sensitive segments. Permanent magnet motors draw from concentrated rare earth processing in China, with precision servo systems sourcing wound components from Japan and Germany. Single-source vulnerability in neodymium supply exposes robotics and motion control to input volatility. Distribution runs through authorized system integrators who bundle hardware with commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial automation vendors are racing to capture upstream software assets and downstream service revenue as hardware margins compress, with predictive maintenance subscriptions emerging as the decisive vertical-integration lever.
For Market Incumbents: To counter IoT-native platform providers eroding the middleware layer, Siemens AG and ABB Ltd. should deepen digital twin ecosystem lock-in through embedded analytics contracts that extend hardware replacement cycles. Backward integration into edge computing silicon partnerships reconfigures procurement channels and defends proprietary fieldbus territories against Time-Sensitive Networking commoditization.
For New Entrants and Emerging Players: Small and mid-sized US Midwest metalworking shops awaiting OSHA liability clarity represent an underserved buyer archetype with pent-up collaborative robotics demand. Clean-in-place stainless-steel robotics for regional dairy processors offer a penetrable entry point with lower certification barriers than pharmaceutical validation equipment. Go-to-market execution should emphasize robot-as-a-service models that transfer liability risk from end-users.
For Investors and Strategic Acquirers: Re-rating potential sits with edge-native software specialists given EU AI Act compliance mandates forcing controller upgrades across European process industries. Long-term viability favors targets with predictive maintenance contract penetration exceeding hardware replacement cycle extension capabilities. Monitor NHTSA autonomous equipment guideline finalization as inflection signal for US collaborative robotics liability allocation clarity.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Ecosystem Expansion | Physics simulation unification with real-time operational data transforms capital equipment into recurring revenue streams for plant operators. |
| Edge Computing Software Acquisition | M&A targeting microsecond-latency architectures compresses response times and fragments traditional hierarchical control topologies. |
| Predictive Maintenance Contract Scaling | Uptime guarantee procurement models in German automotive supply chains concentrate risk with vendors while rewarding analytics capabilities. |
| Time-Sensitive Networking Partnership | Single-cable Ethernet architectures eliminate redundant wiring harnesses for South Korean battery manufacturers deploying converged infrastructure. |
| Functional Safety Certification Investment | IEC 61508 validation depth defends premium positioning in European process industries facing EU AI Act compliance mandates. |
Methodological Framework
Independent corroboration across plant engineers at German automotive suppliers, maintenance directors at US food processors, and procurement leads at South Korean battery manufacturers underwrites the qualitative findings. Secondary validation draws from SEC 10-K filings, customs and trade data, and IEC standard documentation. Bottom-up triangulation of controller shipment data with top-down industrial capital expenditure estimates anchors market sizing.
Comparable-period anchoring to historical automation investment cycles across the projection horizon ensures forecast consistency with machinery replacement patterns. Segmentation modeling spans product type, technology architecture, application intensity, and end-user procurement sophistication. CAGRs derive from installed base expansion rates and replacement cycle compression. Forecast inputs incorporate MIIT interoperability standards and METI smart factory subsidy program uptake.
Revisions become necessary when rare earth export restrictions materialize or when EU AI Act enforcement timelines accelerate beyond process industry upgrade capacity. Practitioners should monitor OSHA collaborative robotics liability rulings and MFDS pharmaceutical validation requirement changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Palletizing Systems Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Modular Automation and Services Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
Grippers Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Industrial Human-Machine Interface Market