
 Industrial Automation Software Market | 2026-2036
Industrial Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Automation Software Market Intelligence
The convergence of operational technology (OT) and information technology (IT) is rewriting how industrial processes are managed and optimized. Siemens leverages its comprehensive digital enterprise suite to bridge this gap for large-scale manufacturers. Rockwell Automation specializes in factory automation and control systems, integrating its software with its hardware base. ABB competes with a strong portfolio in robotics and process automation software for energy and process industries.
Industrial automation software comprises a suite of applications designed to control, monitor, and optimize industrial processes, from individual machines to entire plants. These systems execute logic on Programmable Logic Controllers (PLCs) and visualize real-time operational data for human operators. Within solution offerings, Supervisory Control and Data Acquisition (SCADA) systems remain foundational, while Manufacturing Execution Systems (MES) are critical for discrete manufacturers. Predictive maintenance applications, driven by AI integration, represent the fastest-growing area.
Cybersecurity standards, particularly the IEC 62443 series, are shaping software development and network architecture for industrial control systems. Concurrently, regulations like the EU's Corporate Sustainability Reporting Directive (CSRD) and safety mandates from bodies such as the US Occupational Safety and Health Administration (OSHA) drive demand for data logging and reporting capabilities. The key decision for end-users is how to adopt open, interoperable platforms without increasing vulnerability to cyber threats.
Market Dynamics
The imperative to integrate artificial intelligence and machine learning for predictive analytics into legacy operational technology is the central structural force shaping the market. This pressure redefines software architecture, moving beyond process control to data-driven operational optimization and autonomy.
Growth Catalysts
- Policy-Driven Upgrades:China's industrial upgrade policies, including its "Made in China 2025" framework, mandate the adoption of advanced automation and MES software to enhance domestic manufacturing competitiveness and supply chain resilience.
- Digital Twin Adoption:Semiconductor fabricators are deploying digital twin technology to simulate and optimize complex production processes, demanding sophisticated software platforms that can model and analyze vast datasets for yield improvement.
- Predictive Maintenance Demand:Asset-heavy sectors like oil and gas and power generation require predictive maintenance applications to minimize costly unplanned downtime, driving investment in AI-enabled monitoring and analytics software.
Market Restraints
- High Implementation Costs:The substantial capital investment required to replace or upgrade legacy control systems and integrate modern software platforms acts as a significant barrier for operators of brownfield facilities.
- Proprietary System Lock-in:Many existing industrial environments rely on proprietary hardware and communication protocols from single vendors, creating significant technical and financial hurdles to adopting open, interoperable software solutions.
- Cybersecurity Concerns:Fear of increased exposure to cyberattacks slows the full convergence of IT and OT networks, with many operators hesitant to connect critical control systems to enterprise or cloud networks despite potential efficiency gains.
Strategic Opportunities
- SaaS for SMEs:Developing subscription-based or Software-as-a-Service (SaaS) offerings provides a path to serve small and medium-sized manufacturers who lack the capital for large, upfront perpetual license fees.
- Sustainability Reporting Modules:The EU's Corporate Sustainability Reporting Directive (CSRD) creates a clear opportunity for software modules that automate the collection, logging, and reporting of energy, water, and emissions data.
- Emerging Market Greenfield Projects:New manufacturing hubs in Southeast Asia, particularly Vietnam and Thailand, offer greenfield opportunities to implement entire factory software stacks without the constraints of legacy infrastructure.
Industry Challenges
- Talent Scarcity:A persistent shortage of engineers and data scientists with hybrid expertise in both operational technology (e.g., PLC programming, SCADA) and modern IT disciplines (e.g., cloud computing, AI) constrains implementation.
- Legacy System Integration:Integrating advanced analytics and AI applications with decades-old, often poorly documented, industrial control systems is a complex, costly, and high-risk task that can threaten operational stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Automation Software Market |
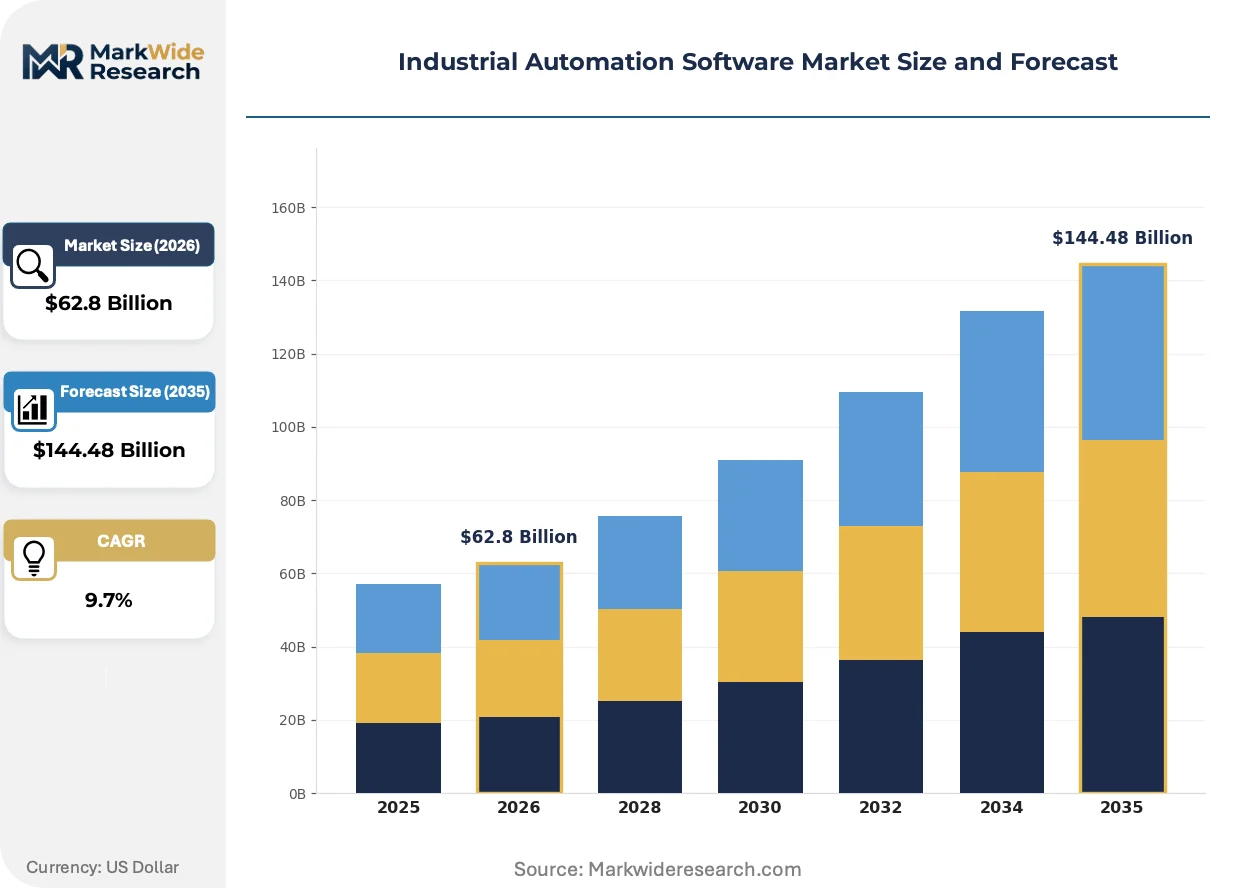
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $144.48 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Solution Offering: SCADA, MES, PLC Programming, HMI, DCS, Asset Management Application: Process Control, Factory Automation, Quality Management, Supply Chain Optimization, Predictive Maintenance End User: Discrete Manufacturers, Process Industries, Energy Suppliers, Tier-1 Suppliers, Semiconductor Fabricators |
| Companies Covered | Mitsubishi Electric, Automation Anywhere, Siemens, IBM, Cognex, ABB, UiPath, AutoStore, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Automation Software Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental shift from software focused purely on control and visualization to platforms built for data aggregation and intelligent decision support. This transition prioritizes interoperability, advanced analytics, and new service delivery models.
Edge computing is transforming data processing architectures for industrial automation. This technology embeds computational and analytical capabilities directly onto or near factory floor devices like controllers and gateways. Discrete manufacturers adopt edge solutions for real-time applications such as robotic control and machine vision that demand minimal latency. The architecture is migrating from a dependency on centralized cloud processing for immediate operational decisions to a more resilient, distributed intelligence model.
Cybersecurity standardization under the IEC 62443 series is becoming a non-negotiable baseline for software development and system design. This framework provides detailed requirements for securing industrial automation and control systems through a defense-in-depth strategy. Asset owners in critical infrastructure sectors like energy and water treatment are now mandating compliance, forcing vendors and system integrators to redesign network architectures and build security features directly into their software products.
Subscription-based software licensing is steadily displacing traditional perpetual license sales. End-users are increasingly opting for opex-based models that provide greater financial flexibility and ensure continuous access to the latest software updates and security patches. This disrupts the business models of traditional system integrators and value-added resellers who historically relied on large, one-time project revenues. The shift is most pronounced in North American and European manufacturing sectors.
Industrial Automation Software Market Segmentation
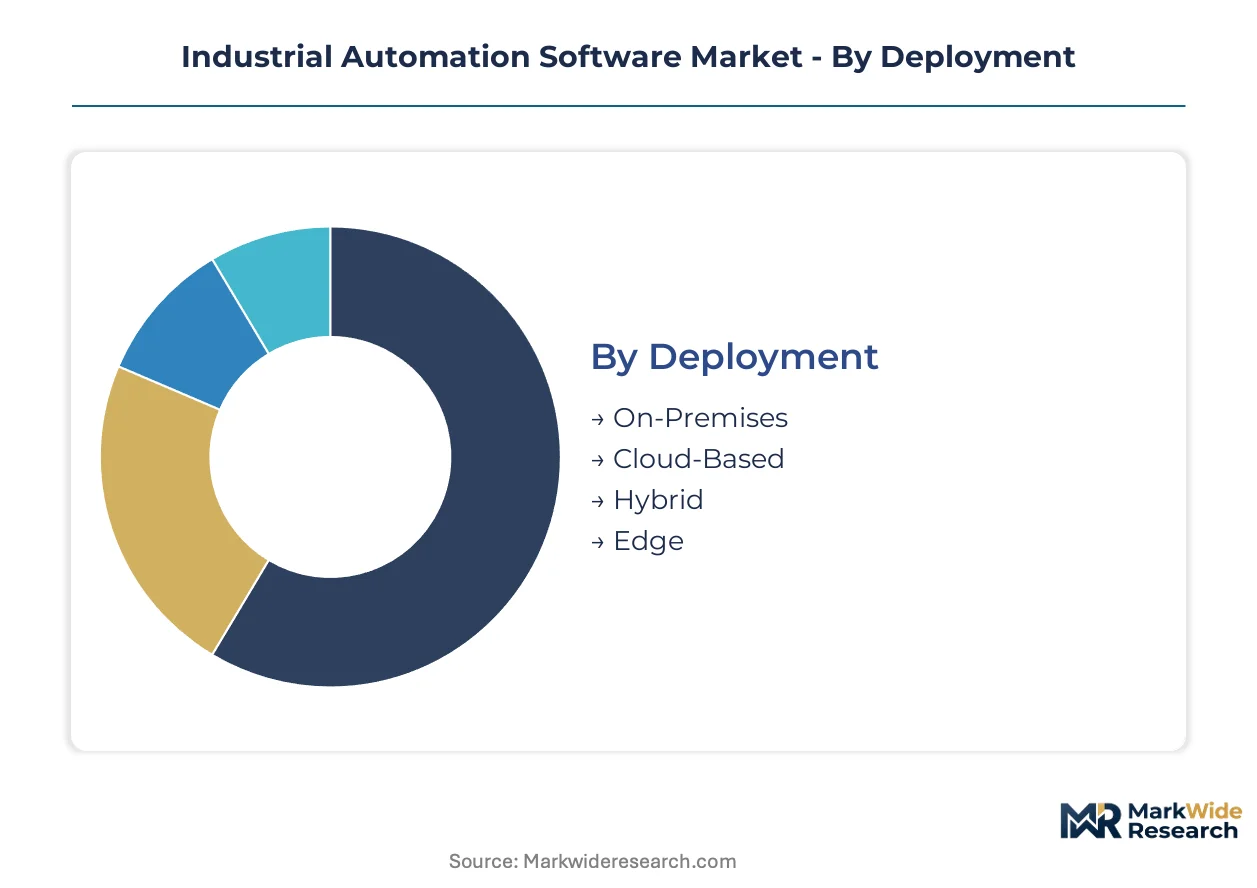
Understanding the Industrial Automation Software market through segmentation clarifies the diverse needs driving its expansion. Different deployment models, solution offerings, applications, and end-user profiles reveal distinct value propositions and competitive battlegrounds. This granular view assists stakeholders in identifying areas for strategic focus and investment.
Deployment:
The after-sales-service intensity varies significantly across different deployment models, influencing long-term operational costs and vendor relationships. Software delivered through various architectures impacts system resilience and data accessibility for industrial operations.
- On-Premises:Software is installed and run directly on a company's own servers and infrastructure, offering maximum control over data and security. This model often requires substantial upfront capital investment and dedicated IT personnel for maintenance.
- Cloud-Based:Industrial automation software is hosted on remote servers and accessed via the internet, reducing local infrastructure requirements. Demand concentrates in manufacturing sectors seeking scalability and remote monitoring capabilities without heavy capital expenditure in IT hardware.
- Hybrid:This model combines elements of both on-premises and cloud deployments, allowing sensitive data to remain local while leveraging cloud resources for analytics or scalability. Organizations balance security with flexibility using this approach.
- Edge:Computational and analytical capabilities are embedded directly onto or near factory floor devices, processing data closer to its source. Discrete manufacturers adopt edge solutions for real-time applications requiring minimal latency, such as robotic control.
On-Premises holds the largest share; momentum sits with Edge.
Solution Offering:
Application flexibility is a key differentiator among industrial automation software offerings, enabling adaptation to diverse operational requirements and industry-specific challenges. Each solution addresses distinct layers of the industrial control hierarchy, from machine-level programming to enterprise-wide optimization.
- SCADA:Supervisory Control and Data Acquisition systems provide real-time monitoring and control of industrial processes across large geographical areas or entire plants. These foundational systems are critical in sectors like energy and water treatment, where continuous oversight is essential for operational stability.
- MES:Manufacturing Execution Systems manage and monitor work-in-progress on the factory floor, optimizing production flow from order release to finished goods. Discrete manufacturers rely on MES for tracking, scheduling, and quality control to meet production targets.
- PLC Programming:This involves developing logic for Programmable Logic Controllers, which are digital computers used for automation of electromechanical processes. PLC programming is fundamental for controlling individual machines and sequences in industrial settings.
- HMI:Human-Machine Interface software provides a graphical user interface for operators to interact with and monitor industrial control systems. HMIs visualize operational data and allow for direct control of machinery.
- DCS:Distributed Control Systems manage complex, continuous process operations in industries such as chemicals and oil and gas. DCS offers centralized control over distributed control elements.
- Asset Management:Software designed to track, maintain, and optimize the performance of physical assets throughout their lifecycle, often incorporating predictive analytics. Asset-heavy sectors like power generation require these applications to minimize costly unplanned downtime.
SCADA solutions form the market's bedrock, while Asset Management applications are expanding most quickly.
Application:
The operational impact of industrial automation software applications spans from direct machine control to strategic enterprise-level optimization. Each application targets specific pain points within industrial processes, aiming to enhance efficiency, reduce costs, or improve product quality.
- Process Control:This application involves using software to regulate and manage continuous industrial processes, ensuring stability and efficiency in operations. Industries like petrochemicals and pharmaceuticals depend on precise process control to maintain product consistency.
- Factory Automation:Software in this application streamlines and automates manufacturing tasks and workflows across an entire facility, integrating various machines and systems. Discrete manufacturers leverage factory automation to increase throughput and reduce manual intervention.
- Quality Management:Applications focused on monitoring, analyzing, and improving product quality throughout the manufacturing process, often integrating with MES and SCADA systems. These tools help ensure compliance with industry standards and reduce defects.
- Supply Chain Optimization:Software that integrates industrial operations with broader supply chain planning and execution, improving logistics, inventory management, and material flow. This application enhances overall supply chain resilience and responsiveness.
- Predictive Maintenance:AI-driven software that analyzes real-time asset data to forecast equipment failures before they occur, enabling proactive maintenance scheduling. Asset-intensive industries like oil and gas are deploying these applications to minimize unplanned downtime.
Predictive Maintenance applications are experiencing the steepest expansion trajectory, complementing the established presence of Process Control.
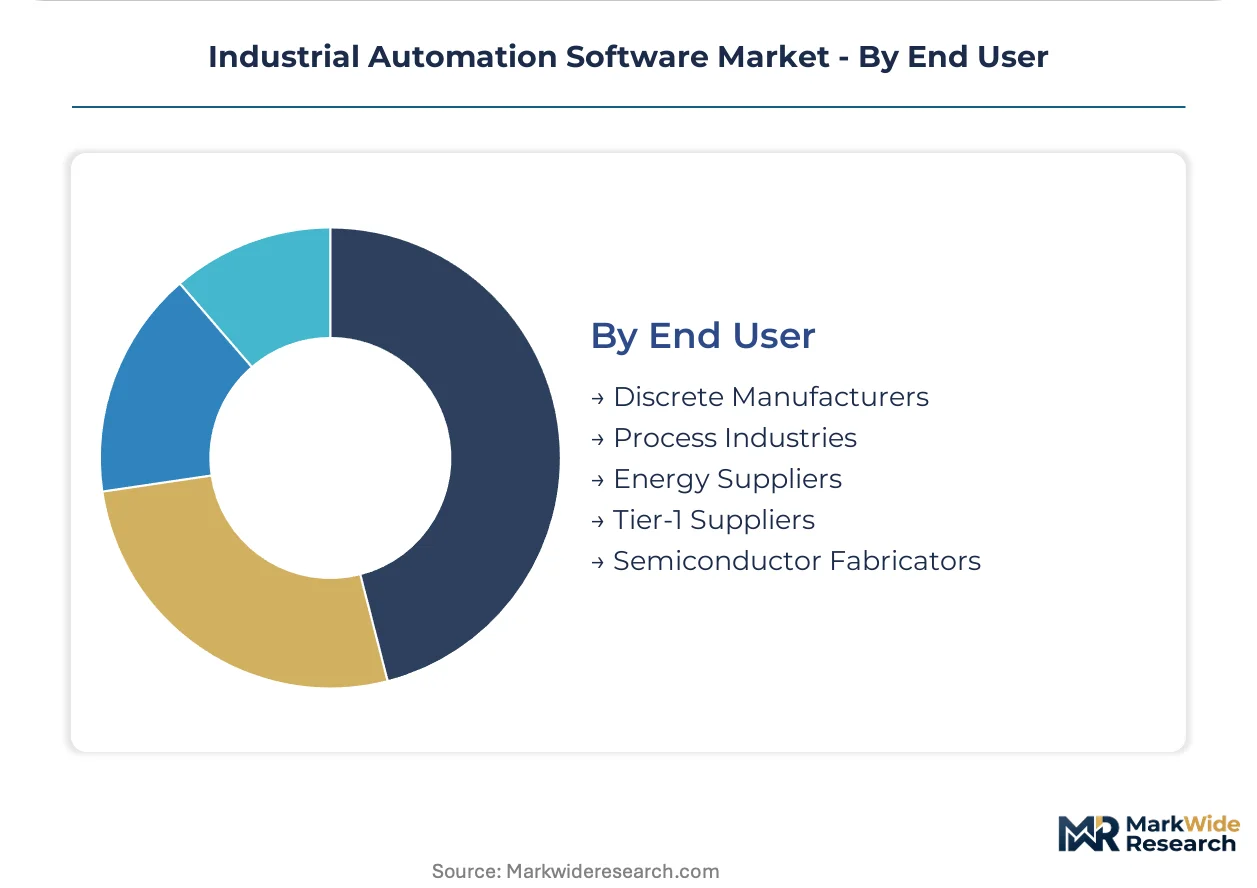
End User:
The investment scale and technological sophistication required for industrial automation software vary significantly across different end-user segments. Each industry vertical possesses unique operational characteristics and regulatory landscapes that influence their adoption patterns and specific software requirements.
- Discrete Manufacturers:These manufacturers produce distinct, individual units or products, relying on software for assembly, machining, and packaging operations. The automotive and electronics industries are prime examples, requiring precise control and rapid changeovers.
- Process Industries:This segment includes industries that produce goods in bulk or continuous flow, such as chemicals, food and beverage, and pharmaceuticals. They require software for managing continuous processes, batch control, and quality consistency.
- Energy Suppliers:Companies involved in the generation, transmission, and distribution of electricity, oil, and gas utilize automation software for grid management, pipeline monitoring, and power plant control. Cybersecurity standards are particularly critical in this sector.
- Tier-1 Suppliers:These are direct suppliers to original equipment manufacturers (OEMs), particularly prevalent in the automotive and aerospace industries. They implement automation software to meet stringent production quotas and quality standards for their OEM partners.
- Semiconductor Fabricators:Facilities that manufacture integrated circuits and microchips, demanding extremely high precision and yield optimization from their automation software. These fabricators are rapidly adopting digital twin technology to simulate and optimize complex production processes.
Discrete Manufacturers represent a foundational end-user segment, with Semiconductor Fabricators demonstrating strong investment in advanced solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for industrial automation software concentrates among discrete manufacturers and semiconductor fabricators seeking enhanced operational efficiency and yield improvements. These sophisticated end-users drive investment in advanced platforms across key industrial economies. Policy support and technological innovation further shape regional adoption patterns.
China
China's industrial upgrade policies, including "Made in China 2025," mandate advanced automation and MES software adoption to enhance domestic manufacturing. The Ministry of Industry and Information Technology (MIIT) promotes digital transformation across key sectors. Manufacturing hubs in the Yangtze River Delta actively deploy smart factory solutions for competitive advantage.
United States
US manufacturers prioritize industrial automation software for supply chain resilience and labor cost optimization. The National Institute of Standards and Technology (NIST) supports cybersecurity frameworks for industrial control systems. Silicon Valley and the Midwest industrial belt drive innovation and adoption in areas like predictive maintenance and digital twins.
Germany
German industry leads in Industry 4.0 initiatives, fostering strong demand for integrated automation software and advanced analytics. The German Federal Ministry for Economic Affairs and Climate Action (BMWK) champions digitalization projects. Bavaria's automotive and machinery sectors demonstrate high adoption of MES and PLC programming solutions.
Japan
Japanese manufacturers leverage automation software for high-precision manufacturing and robotics integration to address labor shortages. The Ministry of Economy, Trade and Industry (METI) promotes smart manufacturing initiatives. Industrial clusters in the Kanto region, including Tokyo, are early adopters of edge computing for real-time control.
India
India's emerging manufacturing sector drives demand for industrial automation software, particularly for new greenfield projects and capacity expansion. The Production-Linked Incentive (PLI) schemes encourage domestic manufacturing, fostering software adoption. Major industrial corridors like the Delhi-Mumbai Industrial Corridor see significant investment in factory automation.
Industrial Automation Software Market Key Industry Players
Channel-controlling players compete with product-specialist players across the industrial automation software market. The market exhibits a tiered structure, with established diversified industrial conglomerates alongside focused software vendors. Strategic partnerships and portfolio diversification represent dominant competitive moves for market participants.
Siemens AG, a German multinational conglomerate, exemplifies a diversified player offering a comprehensive digital enterprise suite. Rockwell Automation, a US-based company, occupies a strong position in factory automation and control systems, integrating software with its hardware base. ABB Ltd., a Swiss-Swedish multinational, represents a significant player in robotics and process automation software for heavy industries.
| Leading Market Players |
|---|
| Mitsubishi Electric |
| Automation Anywhere |
| Siemens |
| IBM |
| Cognex |
| ABB |
| UiPath |
| AutoStore |
| Rockwell Automation |
| Others |
Cost & Logistics Intelligence
Single-source dependency on specialized hardware components determines both pricing tier spreads and the supply chain shape for industrial automation software. This dependency creates specific vulnerabilities for end-users seeking highly customized solutions.
Pricing Analysis
Cost-plus contract patterns with indexation to semiconductor and skilled labor costs dominate large-scale industrial software implementations. Subscription-based SaaS models offer more flexible pricing for smaller deployments, while project-based fees apply to complex system integrations. Price differentiation stems from the level of customization required and the depth of after-sales support. Pricing pressure stems from the increasing availability of open-source components and the need for interoperability. Discrete manufacturers show the highest price sensitivity for foundational software, while semiconductor fabricators prioritize value over upfront cost.
Supply Chain Analysis
The contract-manufacturing concentration for underlying hardware, particularly in Taiwan and South Korea, anchors the industrial automation software supply chain. Software development talent pools in the United States, Germany, and India are critical dependencies. Key components include specialized microcontrollers and industrial-grade network equipment. Cybersecurity vulnerabilities represent a significant structural risk, particularly for systems connected to enterprise networks. Distribution runs through a hybrid model, combining direct sales from major vendors with extensive networks of system integrators and value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial automation software represents a significant service-attach opportunity, with predictive maintenance applications expanding faster than traditional hardware sales.
For Market Incumbents:
Pre-empt emerging threats from open-source platforms by investing in interoperability standards and API development. Consolidate market share through strategic acquisitions of specialized AI and edge computing firms, extending the digital enterprise suite. Leverage channel control to offer integrated hardware-software-service bundles. The increasing demand for sustainability reporting modules presents a clear lever for new recurring revenue streams.
For New Entrants and Emerging Players:
Build out SaaS offerings tailored to small and medium-sized enterprises (SMEs) in emerging manufacturing hubs like Vietnam. Target the underpenetrated market for sustainability reporting modules, leveraging the EU's Corporate Sustainability Reporting Directive (CSRD) as a go-to-market angle. Focus on developing niche solutions for specific industrial applications, such as quality management in specialized discrete manufacturing sectors, to gain initial traction.
For Investors and Strategic Acquirers:
The EU's CSRD directive reshapes the acquisition landscape, favoring software companies with robust data logging and reporting capabilities. Long-term viability over the next 5-10 years centers on platforms that can seamlessly integrate IT and OT data for operational intelligence. Target mid-sized software vendors specializing in AI-driven predictive maintenance or digital twin technology. The signal to watch is the acceleration of cloud adoption in historically on-premises industrial environments.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-enabled Predictive Maintenance Platforms | Minimizes costly unplanned downtime for asset-heavy industries like oil and gas. |
| Expand SaaS Offerings for SMEs | Addresses the capital expenditure constraints of smaller manufacturers in North America. |
| Invest in IEC 62443 Compliance Tools | Establishes a non-negotiable baseline for securing critical infrastructure systems. |
| Acquire Digital Twin Technology Specialists | Accelerates simulation and optimization for semiconductor fabricators seeking yield improvements. |
| Form Strategic Partnerships with Cloud Providers | Enhances scalability and remote monitoring capabilities for industrial operations. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation. Our team engaged with CTOs, plant managers, IT procurement officers, and system integrators across diverse industrial sectors. This primary intelligence was cross-referenced with secondary sources, including SEC filings from public companies, industrial association reports, and government industrial policy documents from China, the US, and Germany.
Forecast inputs considered market dynamics, technological trends, and regulatory shifts across the analysis window. The analytical framework modeled growth trajectories by deployment model, solution offering, application, and end-user segment, with a specific focus on integration complexity. Compound Annual Growth Rates were derived from historical data analysis and projected future adoption rates, incorporating factors such as industrial CAPEX cycles and digital transformation spending patterns.
Sensitivities concentrate around geopolitical tensions and the pace of talent development in hybrid IT/OT skillsets. Forecasts reflect assumptions documented regarding continued industrial digitalization and policy support for advanced manufacturing. Quarterly review of industrial investment trends and cybersecurity incident reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Linear Actuator Market
Industrial Automation
Global Mining Automation Consumption Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Drilling Automation Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Global SCADA Market
Industrial Automation
Factory Automation Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Industrial Embedded Systems Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Pick and Place Machines Market