
 Smart Elevator Automation System Market | 2026-2036
Smart Elevator Automation System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Elevator Automation System Market Outlook
Edge-to-cloud architecture convergence is narrowing the gap between on-premise elevator controllers and centralized building management platforms. Otis Worldwide Corporation leverages its digital-native elevator portfolio to anchor connectivity standards across North American commercial portfolios. KONE Corporation sustains R&D intensity in predictive maintenance algorithms, while Schindler Group competes through channel control in European hospital and hotel verticals.
Smart elevator automation systems integrate sensor networks, programmable logic controllers, and real-time analytics to manage vertical transportation with target response times under thirty seconds during peak demand cycles. These systems serve commercial and residential structures by optimizing traffic flow, reducing energy consumption, and enabling condition-based maintenance. Passenger elevators dominate installed base value, while IoT Solutions and AI Algorithms represent the fastest-expanding technology layers as building operators prioritize predictive uptime over reactive service models. Remote Monitoring capabilities now sit at the margin pool center, converting one-time modernization revenue into recurring service contracts across aging elevator fleets.
China's SAMR enforces GB standards for elevator safety and network-connected device cybersecurity, while India's BIS mandates electromagnetic compatibility certification for automated control systems. The EU AI Act and Machinery Directive collectively shape product design requirements for algorithm-driven destination dispatch systems in European installations. Stakeholders must monitor how fragmented national certification timelines affect platform standardization strategies and supplier qualification costs across multi-country building portfolios.
Market Dynamics
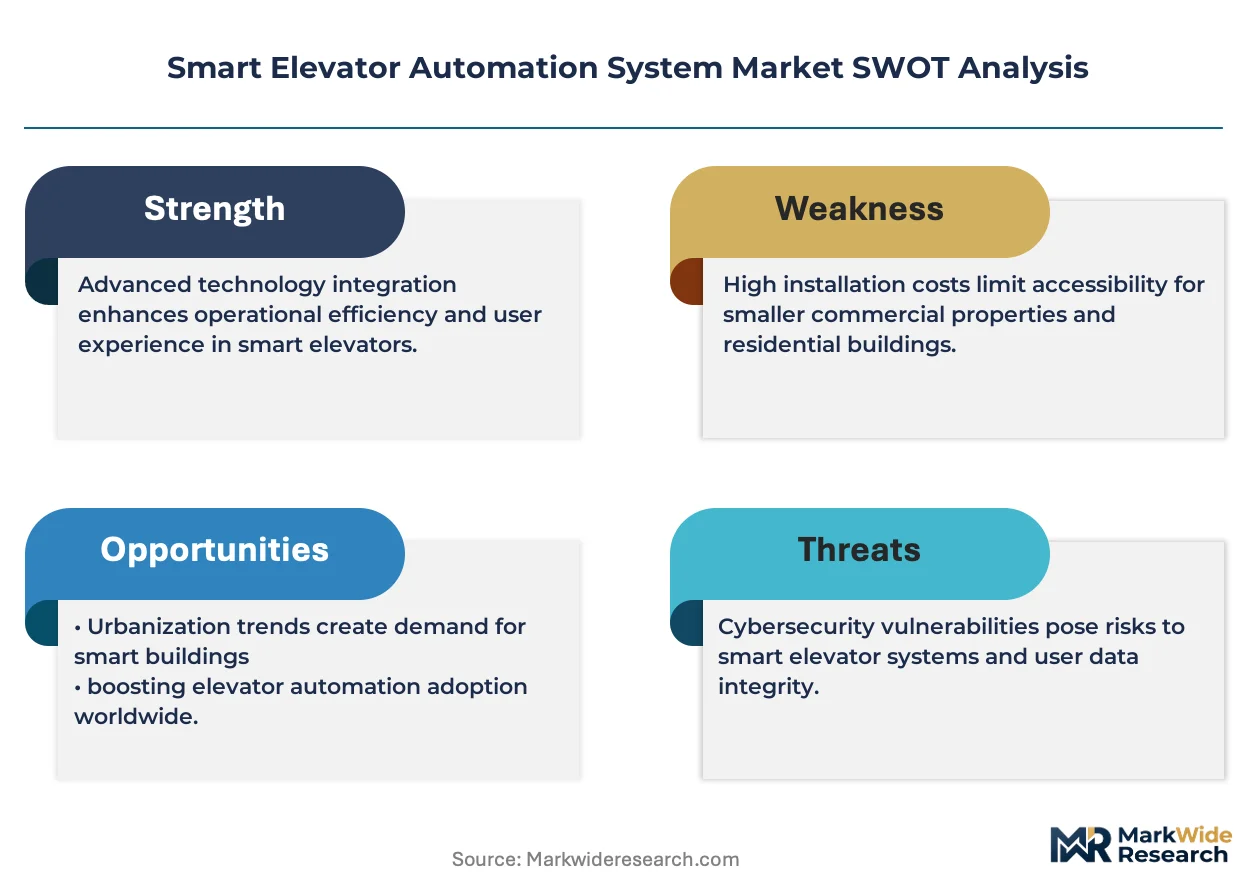
The Smart Elevator Automation System Market is experiencing structural compression as building operators prioritize predictive uptime over reactive service models, converting one-time modernization revenue into recurring service contracts across aging elevator fleets.
Growth Catalysts
- Destination dispatch algorithms:AI-driven traffic management reduces average wait times below thirty seconds during peak cycles in high-rise commercial towers across Mumbai and Shanghai.
- China's GB standards:SAMR-enforced cybersecurity and energy efficiency mandates accelerate replacement cycles in network-connected elevator installations.
- Hospital infrastructure expansion:India's metropolitan construction clusters generate concentrated demand for patient-transport elevator systems with infection-control protocols.
Market Restraints
- Semiconductor input volatility:Programmable logic controller and sensor module costs fluctuate with foundry capacity constraints in East Asian supply nodes.
- EU AI Act compliance friction:Algorithmic transparency requirements for destination dispatch systems extend product qualification timelines for European installations.
- Electromechanical substitution:Hydraulic elevator systems retain cost advantages in low-rise commercial retrofits below six stories.
Strategic Opportunities
- Edge-to-cloud convergence:On-premise elevator controllers integrating with centralized building management platforms open white space in mixed-use developments.
- Remote monitoring unbundling:IoT-enabled condition-based maintenance contracts create recurring revenue streams from India's aging installed base.
- India's PLI scheme:Domestic manufacturing incentives for automated control systems reduce import dependency for electromagnetic compatibility-certified components.
Industry Challenges
- Embedded systems engineering talent:Shortages of firmware developers with real-time operating system expertise constrain R&D velocity for predictive maintenance algorithms.
- Legacy controller integration:Protocol translation between proprietary 1990s-era elevator networks and open IoT architectures requires custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Elevator Automation System Market |
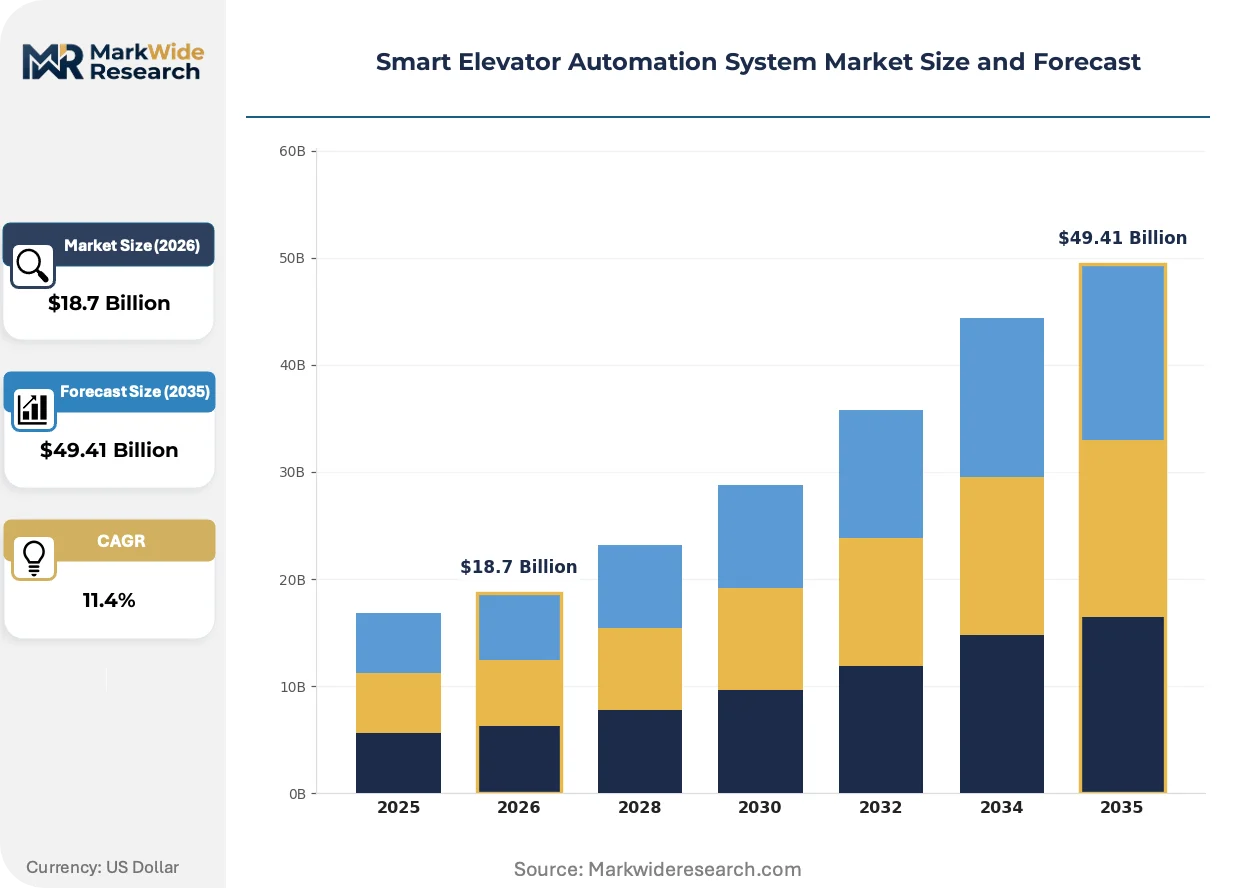
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Elevators, Freight Elevators, Home Elevators, Service Elevators Technology: IoT Solutions, Machine Learning, AI Algorithms, Remote Monitoring End User: Commercial Buildings, Residential Complexes, Hospitals, Hotels Service Type: Installation, Maintenance, Modernization, Consulting |
| Companies Covered | Otis Worldwide Corporation, KONE Corporation, Schindler Group, TK Elevator, Mitsubishi Electric Corporation, Hitachi Ltd., Fujitec Co. Ltd., Thyssenkrupp AG, Hyundai Elevator Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Elevator Automation System Market Strategic Shifts
Sensor fusion architectures and machine learning inference at the edge are compressing response latency in traffic management systems. These shifts are reconfiguring how building operators contract for vertical transportation services.
Machine vision-based passenger counting is migrating from centralized cloud processing to edge-deployed inference engines. High-rise residential developers in Singapore and Dubai are specifying these systems to optimize cab allocation during morning egress peaks. This migration from cloud to edge is reducing bandwidth costs and enabling sub-100-millisecond dispatch decisions.
The EU AI Act and Machinery Directive collectively impose conformity assessment obligations on algorithmic elevator dispatch systems. Manufacturers must document training data provenance and decision explainability for installations across Germany, France, and Italy. European hospital and hotel verticals are responding by pre-qualifying suppliers with established notified body relationships.
Facility managers are unbundling maintenance contracts from original equipment procurement, selecting third-party remote monitoring providers for multi-vendor elevator fleets. This pattern disrupts traditional captive service arrangements in North American commercial portfolios. The shift is most visible in Class A office buildings seeking to standardize analytics dashboards across Otis, KONE, and Schindler installations.
Smart Elevator Automation System Market Segmentation
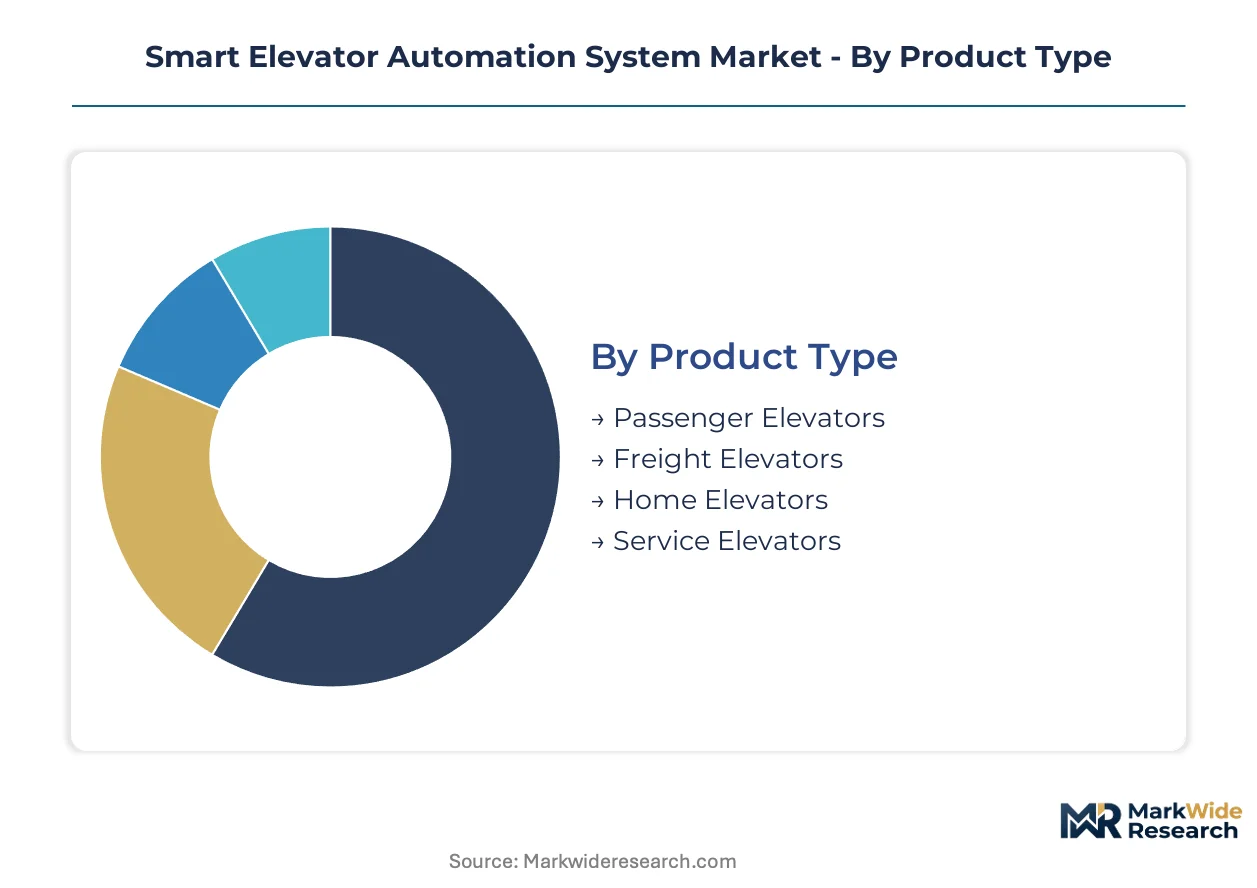
Smart elevator automation systems fragment across four structural dimensions that determine procurement patterns and margin architecture. Product type governs installed base economics, while technology layers dictate recurring revenue potential. End-user verticals impose distinct compliance and performance specifications. Service type stratification separates capital expenditure from operational expenditure flows.
Product Type:
Application context determines load capacity, speed ratings, and control system complexity across vertical transportation equipment.
- Passenger Elevators:High-speed traction systems with destination dispatch controllers dominate high-rise commercial towers in Mumbai and Shanghai. Building operators prioritize sub-thirty-second response times during morning egress peaks.
- Freight Elevators:Heavy-duty platforms with reinforced cab structures and precision leveling sensors serve manufacturing facilities and logistics hubs. China's tightening GB energy efficiency standards accelerate controller replacement cycles in network-connected freight installations.
- Home Elevators:Compact hydraulic or traction units with simplified control interfaces address aging-in-place demographics and multi-generational residential construction.
- Service Elevators:Dumbwaiters and material transport systems with restricted access protocols support restaurant, retail, and healthcare back-of-house operations.
Passenger elevators command the established base. The steepest expansion runs through home elevators.
Technology:
Technology layers stratify by data processing location and algorithmic sophistication, reshaping supplier margin pools.
- IoT Solutions:Sensor networks and connectivity modules enabling real-time status transmission to centralized building management platforms. India's metropolitan construction clusters generate concentrated demand for electromagnetic compatibility-certified IoT controllers under BIS mandates.
- Machine Learning:Edge-deployed inference engines compressing traffic pattern recognition latency below one hundred milliseconds. High-rise residential developers in Singapore and Dubai specify these systems for morning egress optimization.
- AI Algorithms:Predictive maintenance models forecasting component failure probability from vibration and temperature signatures.
- Remote Monitoring:Cloud-based condition assessment converting one-time modernization revenue into recurring service contracts across aging elevator fleets.
Remote monitoring commands the established base. The steepest expansion runs through machine learning.
End User:
Customer type imposes divergent performance specifications, regulatory burdens, and contracting mechanisms on system suppliers.
- Commercial Buildings:Class A office towers and mixed-use developments requiring destination dispatch systems with API integration to centralized building management platforms. Facility managers unbundle maintenance contracts from original equipment procurement to standardize analytics dashboards across multi-vendor fleets.
- Hospitals:Patient-transport elevators with infection-control protocols, stretcher accommodation, and priority override systems. India's metropolitan construction clusters drive concentrated procurement for electromagnetic compatibility-certified control systems.
- Residential Complexes:High-rise towers with traffic management optimized for morning egress and evening ingress patterns.
- Hotels:Destination dispatch systems with VIP priority queuing and integration with property management systems for guest floor access control.
Commercial buildings command the established base. The steepest expansion runs through hospitals.
Service Type:
Revenue model architecture separates capital-intensive project delivery from recurring operational expenditure streams.
- Installation:New construction and greenfield deployment of complete elevator systems with integrated automation controllers. China's SAMR-enforced cybersecurity mandates for network-connected devices extend commissioning timelines and documentation requirements.
- Modernization:Controller and drive system upgrades to legacy installations, often requiring protocol translation between proprietary 1990s-era networks and open IoT architectures.
- Maintenance:Preventive and corrective service contracts covering mechanical and electrical subsystem upkeep.
- Consulting:Traffic analysis, energy optimization studies, and compliance advisory for building portfolio standardization.
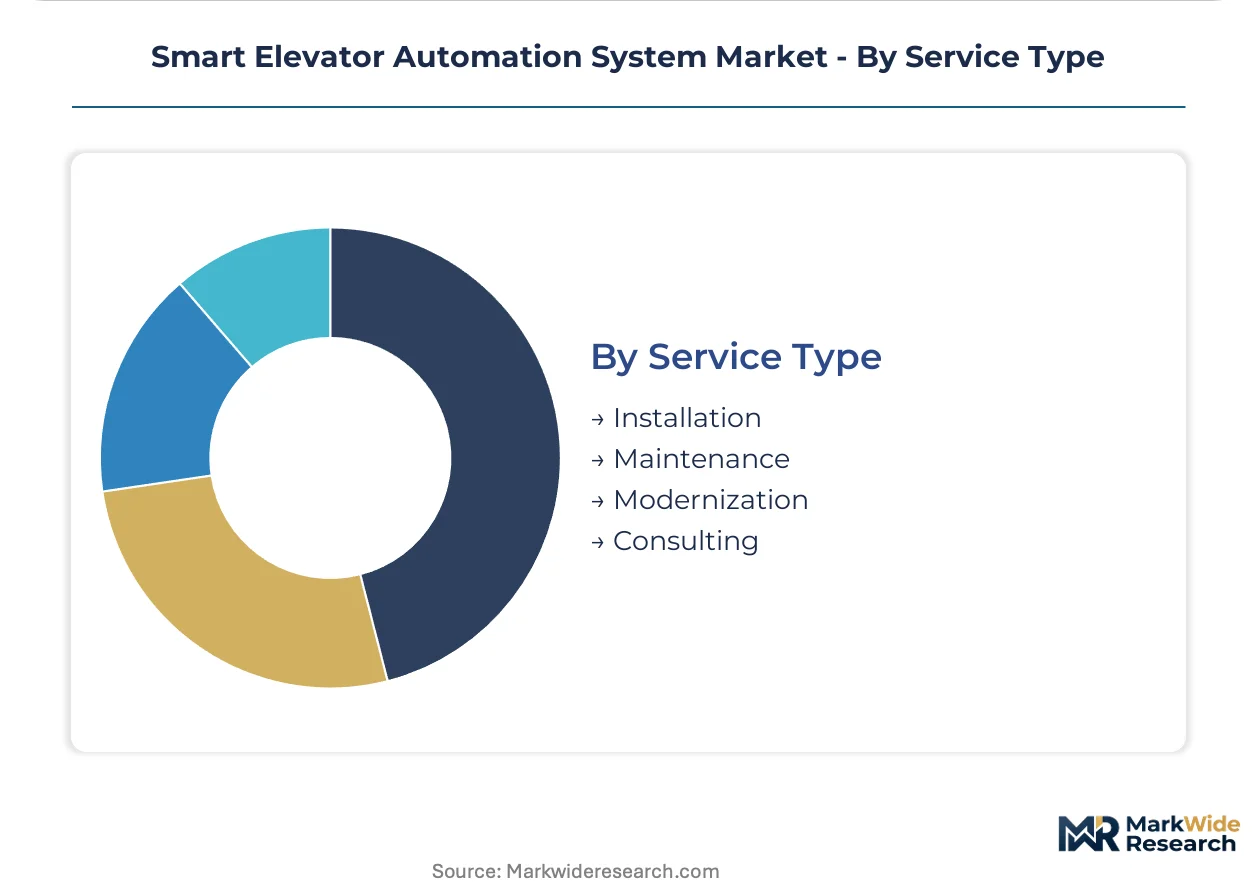
Maintenance commands the established base. The steepest expansion runs through modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German elevator component manufacturers export precision drive systems to high-rise construction projects across the Gulf Cooperation Council corridor. This trade flow channels European engineering standards into Middle Eastern commercial tower developments.
United States
Class A office building retrofits in Manhattan and Chicago drive demand for destination dispatch modernization. The country's national elevator safety regulator enforces ASME A17.1 standards for networked control systems. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate procurement for mixed-use developments integrating smart building management platforms.
China
Urban corridor high-rise residential towers in Shenzhen and Hangzhou require AI-driven traffic management systems. SAMR enforces GB standards for elevator cybersecurity and energy efficiency in network-connected installations. The Yangtze River Delta manufacturing cluster produces programmable logic controllers for domestic and Southeast Asian export markets.
India
Metropolitan hospital infrastructure expansion in Mumbai and Bangalore generates concentrated demand for patient-transport elevator systems. BIS mandates electromagnetic compatibility certification for automated control systems under national technical regulations. The Delhi-NCR construction cluster intensifies procurement for high-rise residential towers with morning egress optimization protocols.
Germany
European hospital and hotel verticals in Berlin and Munich pre-qualify suppliers for algorithmic dispatch systems. The EU AI Act and Machinery Directive impose conformity assessment obligations on destination dispatch installations. The Baden-Württemberg industrial corridor anchors precision manufacturing for elevator drive and control components.
Japan
Aging building stock in Tokyo and Osaka accelerates controller replacement cycles for predictive maintenance integration. METI oversees national standards for elevator energy efficiency and seismic safety in automated systems. The Nagoya manufacturing cluster specializes in sensor fusion architectures for edge-deployed traffic management.
Smart Elevator Automation System Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented national installation markets. The vendor base stratifies into three tiers: integrated multinationals with captive service networks, regional specialists with vertical expertise, and component suppliers licensing control technology. Dominant competitive moves include strategic partnerships between elevator OEMs and building automation platform providers, plus geographic expansion through local distributor acquisition in high-growth Asian corridors.
Among integrated multinational corporations, Otis Worldwide Corporation, KONE Corporation, and Schindler Group exemplify the channel-control archetype through established service network density. These entities occupy positions where recurring maintenance contract flows offset capital-intensive installation cycles. Each anchors connectivity standards within its primary regional stronghold while competing for modernization contracts in multi-vendor building portfolios.
| Leading Market Players |
|---|
| Otis Worldwide Corporation |
| KONE Corporation |
| Schindler Group |
| TK Elevator |
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Fujitec Co. Ltd. |
| Thyssenkrupp AG |
| Hyundai Elevator Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
East Asian programmable logic controller foundries concentrate upstream supply for elevator automation systems, anchoring margin pools in predictive maintenance software layers and recurring service contract streams. This concentration transfers pricing power toward controller-integrated OEMs while squeezing standalone component suppliers.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate controller procurement between elevator OEMs and East Asian foundry partners. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in standard-tier controllers is intensifying because foundry capacity constraints elevate input volatility. Hospital and hotel verticals exhibit lowest price sensitivity due to compliance mandates, while mid-rise residential developers in India demonstrate highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for elevator automation component flows. Manufacturing concentrates in China, South Korea, and Germany for programmable logic controllers, sensor modules, and precision drive systems respectively. Raw material dependencies span rare earth magnets, silicon wafers, and copper windings. Single-source vulnerability persists for edge-computing chipsets with real-time operating system certification. Distribution runs through captive OEM service networks and third-party building automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as building operators convert one-time modernization revenue into recurring predictive maintenance contracts. AI-driven destination dispatch penetration in high-rise commercial towers accelerates replacement demand beyond traditional equipment lifecycles.
For Market Incumbents: Harden predictive maintenance algorithm portfolios against emerging cloud-native elevator analytics entrants by deepening firmware development capabilities in edge-computing architectures. Secure channel control through multi-year remote monitoring contracts that protocol-lock legacy controller integrations. Invest in notified body relationships for EU AI Act conformity assessment acceleration. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point for IoT-enabled controller retrofits lacking incumbent service entanglement. India's aging installed base under BIS electromagnetic compatibility mandates offers second-mover advantage for domestic manufacturing plays. Lead with API-first building management platform integration rather than hardware-centric positioning. For Investors and Strategic Acquirers: Capital is best deployed toward edge-computing specialists with real-time operating system expertise and established hospital vertical relationships. Long-term viability hinges on recurring revenue ratio expansion and software margin accretion. Watch for inflection when facility manager unbundling of maintenance contracts crosses fifty percent penetration in Class A office portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Platform Integration | Unifies elevator controllers with building management systems across mixed-use developments in Dallas-Fort Worth. |
| Predictive Maintenance Algorithm Development | Compresses component failure forecasting latency for KONE Corporation's North American service contracts. |
| Notified Body Relationship Establishment | Accelerates EU AI Act conformity assessment timelines for destination dispatch installations in German hospitals. |
| Domestic Manufacturing Scale-Up | Captures India's PLI scheme incentives for electromagnetic compatibility-certified control system production. |
| Third-Party Remote Monitoring Unbundling | Disrupts Otis and Schindler captive service arrangements in Manhattan Class A office retrofits. |
Study Parameters
Operator-level perspectives from facility managers, elevator maintenance directors, building automation integrators, and hospital biomedical engineers anchored the qualitative base. Primary interview insights combined with secondary validation from SAMR GB standard filings, BIS certification databases, EU Machinery Directive implementation guidance, and SEC 10-K equipment manufacturer disclosures. Bottom-up installed base modeling and top-down construction spend triangulation cross-checked volume assumptions.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, technology layer, end-user vertical, and service model. CAGRs derived from equipment replacement cycle analysis, regulatory mandate acceleration effects, and software penetration curve modeling. Forecast inputs incorporated hospital infrastructure construction permits, high-rise residential tower completions, and edge-computing chipset availability.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate investment, semiconductor foundry capacity expansion, and construction labor availability would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Machine Automation Controllers Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market