
 Modular High-Bay Solutions Market | 2026-2036
Modular High-Bay Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Modular High-Bay Solutions Market Insights
ISO 9001 and ENEC certification cycles are rotating vendor eligibility across European procurement channels, raising barriers for unqualified suppliers. Signify leverages its vertical manufacturing footprint in LED modules to sustain pricing power in warehouse retrofits. Zumtobel Group anchors its position through Austrian engineering centers that specialize in glare-controlled optics for high-rack aisles. Eaton competes on integrated power distribution, extending its offer from luminaires into building-level energy management.
Modular high-bay solutions are engineered lighting and structural systems designed for vertical storage environments exceeding twelve meters in clearance, typically incorporating heat-dissipating aluminum housings, precision beam angles, and plug-in electrical connectors for scalable deployment. Their primary purpose is to deliver uniform illuminance across narrow aisle widths while minimizing energy load per pallet position. Pre-engineered modules currently dominate volume sales due to shorter lead times and standardized mounting compatibility, though custom modular units capture superior margins in cold storage applications where IP ratings and thermal management requirements exceed off-the-shelf capabilities. Sensor automation within the technology dimension is expanding fastest as logistics operators mandate occupancy-based dimming to reduce kilowatt-hour intensity.
FERC efficiency standards and OSHA illumination guidelines in the United States shape minimum lux levels and emergency lighting coverage for distribution centers, while the EU Ecodesign Directive and F-Gas Regulation constrain refrigerant-linked lighting installations in European cold chain facilities. Compliance with these frameworks determines market access and influences specification decisions by facility engineering teams. Stakeholders must monitor evolving carbon disclosure rules and local utility rebate structures to align product roadmaps with purchaser procurement scorecards.
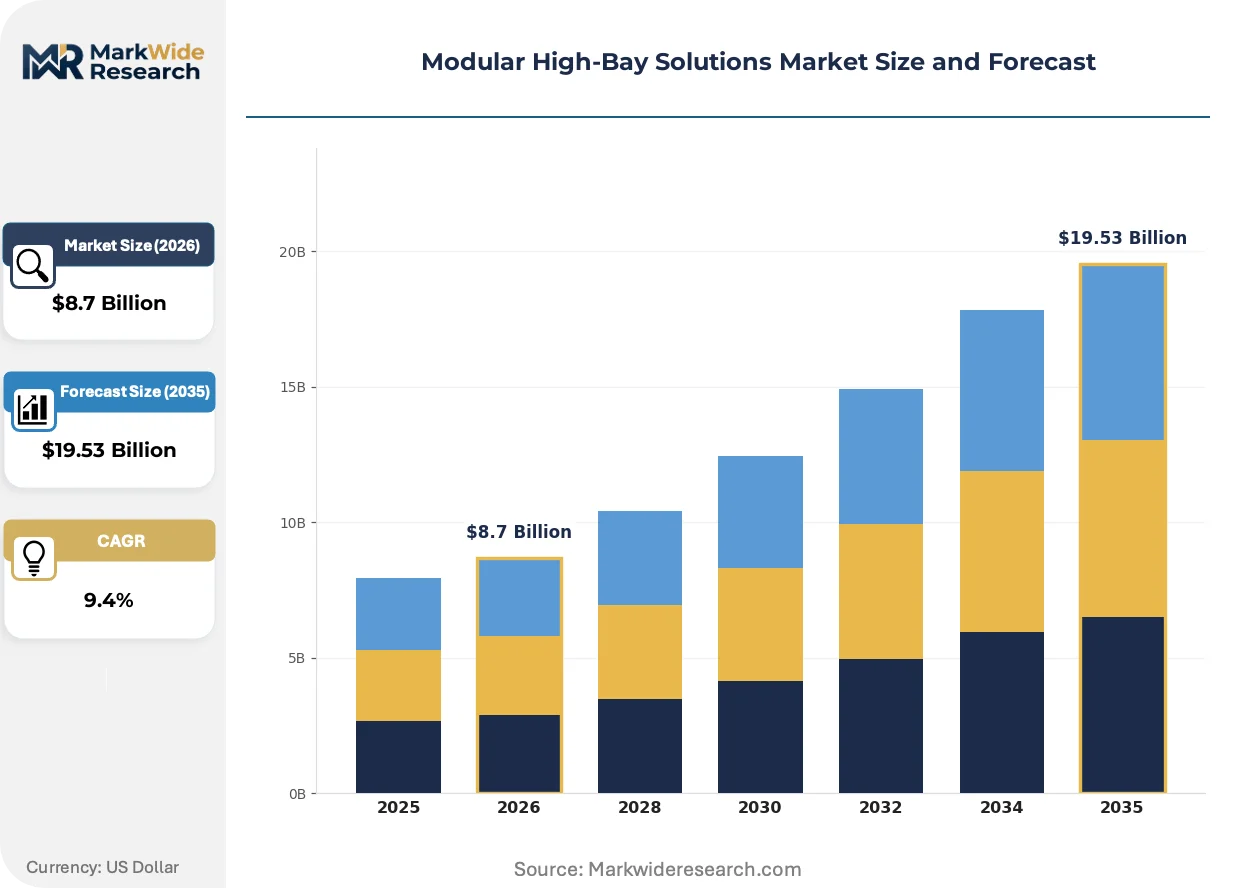
Market Dynamics
Sensor-integrated occupancy dimming is compressing payback periods for warehouse retrofits, shifting specification authority from facility managers to corporate energy procurement teams.
Growth Catalysts
- EU Ecodesign Directive:Tightening luminaire efficiency thresholds in Germany and France are accelerating LED module replacements across cold chain facilities.
- Texas logistics corridor:E-commerce fulfillment hubs in Dallas-Fort Worth and Houston are driving demand for pre-engineered high-bay modules with standardized mounting.
- Occupancy-based controls:Wireless sensor networks enable aisle-specific dimming that cuts kilowatt-hour intensity per pallet position in narrow-rack environments.
Market Restraints
- Aluminum housing costs:Heat-dissipating extrusion prices fluctuate with LME spot markets, pressuring margins on volume pre-engineered units.
- ENEC certification cycles:European vendor eligibility rotates on three-year intervals, locking unqualified suppliers out of public procurement channels.
- Refrigerant-linked constraints:F-Gas Regulation limits lighting installation options in European cold storage, restricting product configurability.
Strategic Opportunities
- Southeast US corridor:Georgia and South Carolina distribution hubs remain underpenetrated for integrated power distribution systems.
- Sensor-luminaire convergence:Bluetooth mesh and daylight harvesting algorithms create bundled specification opportunities with building automation vendors.
- Utility rebate structures:Local demand-response programs in Texas and California subsidize smart high-bay deployments above baseline efficiency codes.
Industry Challenges
- Optical engineering talent:Glare-controlled beam angle design for twelve-meter clearances requires specialized Austrian and German engineering center expertise.
- Legacy electrical infrastructure:Plug-in connector retrofits face integration friction with existing conduit systems in facilities built before 2010.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular High-Bay Solutions Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Modular Units, Pre-engineered Modules, Retrofit Kits, Integrated Control Systems Technology: LED Lighting, Sensor Automation, Wireless Communication, Energy Harvesting Application: Warehouse Storage, Cold Storage, Manufacturing Plants, Distribution Centers End User: Logistics Providers, Food Processing Plants, Textile Manufacturers, Electronics Assemblers |
| Companies Covered | Acuity Brands, Signify, Zumtobel Group, Eaton, Trilux, Fagerhult, Legrand, Cree Lighting, Hubbell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular High-Bay Solutions Market Trends and Innovations
Digital control layers are displacing standalone luminaire specifications, compressing the traditional split between lighting and building management procurement.
LED driver electronics is miniaturizing thermal management components into aluminum housings that previously required separate heat sinks. Third-party logistics operators in the Southeast United States are specifying these compact modules for rapid aisle reconfiguration. The technology is miniaturizing footprint constraints in narrow high-rack environments, enabling denser sensor placement per square meter.
OSHA illumination guidelines are tightening minimum lux enforcement in distribution centers, triggering emergency lighting coverage upgrades. Facility engineering teams must document compliance across egress paths and vertical storage zones. Cold storage operators in Texas and California face the steepest retrofit timelines due to simultaneous FERC efficiency audits.
Energy-as-a-service contracts are unbundling capital expenditure from lighting procurement, shifting risk to equipment financiers. Large e-commerce fulfillment operators now lease luminaire performance rather than owning assets. This model concentrates fastest in the Dallas-Fort Worth corridor where utility-backed demand-response agreements reduce operational risk.
Modular High-Bay Solutions Market Segmentation
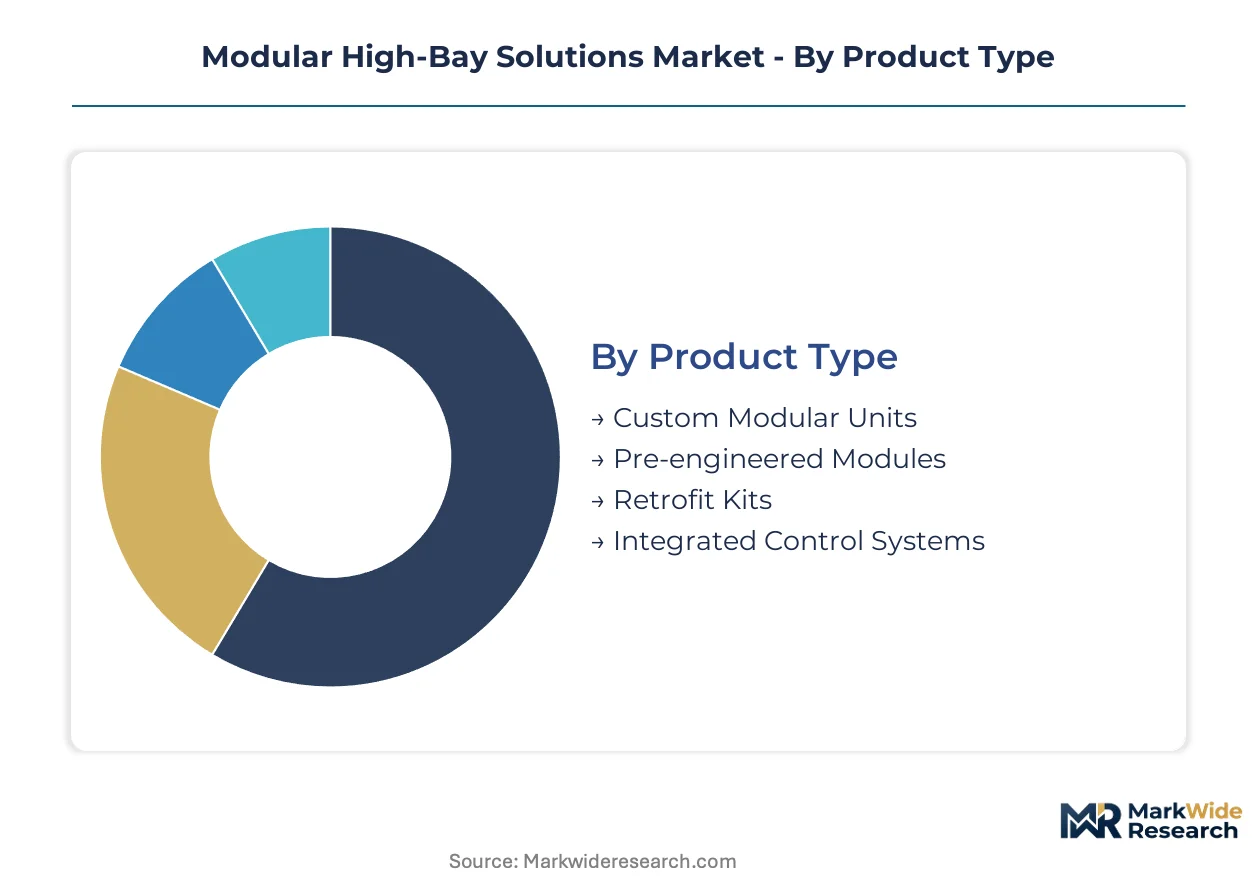
Segmentation in modular high-bay solutions reveals how specification authority shifts between facility engineering teams and corporate procurement based on product configurability. Understanding these divides illuminates where margin compression and premium capture occur across the value chain.
Product Type:
Pre-engineered modules face the most intense substitution pressure from integrated control bundles that collapse lighting and automation into single procurement decisions.
- Pre-engineered Modules:Standardized aluminum housings with plug-in electrical connectors ship on compressed lead times for rapid aisle deployment. Demand concentrates across Texas logistics corridors where Dallas-Fort Worth fulfillment hubs prioritize mounting compatibility over customization.
- Custom Modular Units:Engineered-to-order systems with specialized IP ratings and thermal management for sub-zero environments command superior margins. Cold storage operators in Germany and France specify these units where F-Gas Regulation constrains refrigerant-linked installation options.
- Retrofit Kits:Adapter packages bridge legacy conduit infrastructure with modern LED drivers.
- Integrated Control Systems:Bundled luminaire-sensor packages with building automation protocols.
Pre-engineered modules retain volume leadership; integrated control systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates commodity LED emitters from sensor-laden premium configurations that utility rebate programs disproportionately reward.
- Sensor Automation:Wireless occupancy networks with aisle-specific dimming algorithms cut kilowatt-hour intensity per pallet position. Southeast US distribution hubs specify these systems where local demand-response programs subsidize smart deployments above baseline codes.
- LED Lighting:Heat-dissipating aluminum extrusions with precision beam angles dominate retrofit specifications. Warehouse operators in Georgia and South Carolina prioritize these modules for twelve-meter clearance environments where OSHA minimum lux enforcement has tightened.
- Wireless Communication:Bluetooth mesh protocols enabling centralized dimming control.
- Energy Harvesting:Photovoltaic-integrated drivers reducing grid dependency in edge facilities.
LED lighting retains volume leadership; sensor automation holds the steepest expansion curve.
Application:
Volume concentration in e-commerce fulfillment is pulling specification standards upward from cold storage's historically specialized requirements.
- Warehouse Storage:Narrow-aisle rack systems requiring uniform illuminance across vertical storage zones. Third-party logistics operators in the Southeast United States drive specification for rapid aisle reconfiguration capabilities.
- Distribution Centers:High-velocity fulfillment environments with emergency lighting coverage mandates across egress paths. Texas and California facilities face simultaneous FERC efficiency audits and OSHA enforcement actions.
- Cold Storage:Sub-zero rated luminaires with enhanced thermal management for refrigerated facilities.
- Manufacturing Plants:Process lighting integrated with production line safety systems.
Warehouse storage retains volume leadership; distribution centers hold the steepest expansion curve.
End User:
Procurement centralization varies sharply between fragmented food processing and consolidated logistics providers with energy-as-a-service contract capacity.
- Logistics Providers:National operators leasing luminaire performance rather than owning assets. The Dallas-Fort Worth corridor concentrates these contracts where utility-backed demand-response agreements reduce operational risk.
- Food Processing Plants:Cold chain operators requiring IP-rated enclosures with washdown compatibility. German and French facilities navigate EU Ecodesign Directive efficiency thresholds alongside national energy efficiency codes.
- Textile Manufacturers:Dust-resistant housings for fiber handling environments with color rendering requirements.
- Electronics Assemblers:Static-controlled lighting for cleanroom component production.
Logistics providers retain volume leadership; food processing plants hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility rebate structures and national energy efficiency codes are concentrating procurement authority in corporate energy teams across major logistics corridors. Facility engineering specifications increasingly defer to centralized procurement scorecards that prioritize demand-response program eligibility over standalone luminaire performance.
United States
FERC efficiency standards and OSHA illumination guidelines mandate minimum lux levels across distribution center egress paths. The Dallas-Fort Worth and Houston logistics corridors drive specification for pre-engineered high-bay modules with standardized mounting compatibility. Georgia and South Carolina distribution hubs remain underpenetrated for integrated power distribution systems.
Germany
The EU Ecodesign Directive tightens luminaire efficiency thresholds for industrial installations. National energy efficiency codes in Germany accelerate LED module replacements across cold chain facilities. Engineering centers in Bavaria and North Rhine-Westphalia specialize in glare-controlled optics for twelve-meter clearance environments.
France
ANSM and national energy efficiency regulators enforce performance thresholds for industrial luminaires in logistics facilities. The EU Green Deal carbon disclosure requirements shape procurement decisions by facility engineering teams. Cold storage operators in the Île-de-France and Hauts-de-France regions navigate F-Gas Regulation constraints on refrigerant-linked lighting installations.
China
MIIT efficiency standards and dual carbon goals drive LED adoption in high-bay warehouse applications. GB standards for industrial lighting establish minimum performance benchmarks for domestic and export markets. Yangtze River Delta logistics hubs specify compact thermal management modules for rapid aisle reconfiguration.
United Kingdom
Building Regulations Part L and commercial energy efficiency codes tighten operational carbon limits for industrial facilities. The Midlands and North England distribution corridors concentrate retrofit demand as legacy facilities face simultaneous efficiency audits. London-area corporate procurement teams centralize specification authority for national logistics networks.
Modular High-Bay Solutions Market Competitive Landscape
Listed leaders compete with private specialists across technology integration and geographic coverage dimensions. The vendor base stratifies into three tiers: diversified electrical conglomerates with building automation portfolios, lighting specialists with vertical control over LED module production, and regional fabricators serving single-country procurement channels. Two strategic archetypes dominate competitive positioning: scale-driven suppliers bundling luminaires with energy management software, and engineering-focused specialists capturing premium margins in cold storage applications. M&A activity concentrates on sensor-luminaire convergence capabilities, while capacity expansion targets aluminum extrusion and driver electronics integration.
Among diversified electrical conglomerates, Signify and Eaton exemplify scale-driven positioning through in-house LED module production and integrated power distribution offers respectively. Zumtobel Group occupies a specialist tier anchored by Austrian engineering center expertise in glare-controlled optics for narrow-rack aisles. These three companies represent contrasting competitive vectors: captive supply chain control, building-level energy management extension, and precision optical engineering specialization.
| Leading Market Players |
|---|
| Acuity Brands |
| Signify |
| Zumtobel Group |
| Eaton |
| Trilux |
| Fagerhult |
| Legrand |
| Cree Lighting |
| Hubbell |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with aluminum extrusion suppliers lock in heat-dissipating housing access while anchoring price visibility for pre-engineered module manufacturers serving Texas logistics corridors. These contracts insulate vendors from LME spot volatility that otherwise compresses margins on volume shipments to Dallas-Fort Worth fulfillment hubs.
Pricing Analysis
Certification level creates the primary spread between ENEC-qualified premium tiers and uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ENEC rotation cycles, ISO 9001 compliance status, and bundled sensor automation. Cost compression in standard tiers intensifies because aluminum housing prices fluctuate with commodity markets. Third-party logistics operators in Georgia and South Carolina exhibit highest price sensitivity, while cold storage operators in Germany accept premium positioning for F-Gas-compliant custom configurations.
Supply Chain Analysis
Yangtze River Delta LED driver manufacturing underwrites component availability for compact thermal management modules. China, Germany, and Austria anchor supply for precision optics, aluminum extrusions, and glare-controlled engineering respectively. The chain draws from Taiwanese semiconductor foundries for wireless sensor chipsets. Single-source vulnerability concentrates in Austrian engineering center talent for twelve-meter clearance beam angle design. Distribution runs through electrical distributor networks with specification influence held by building automation vendors bundling luminaire-sensor packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
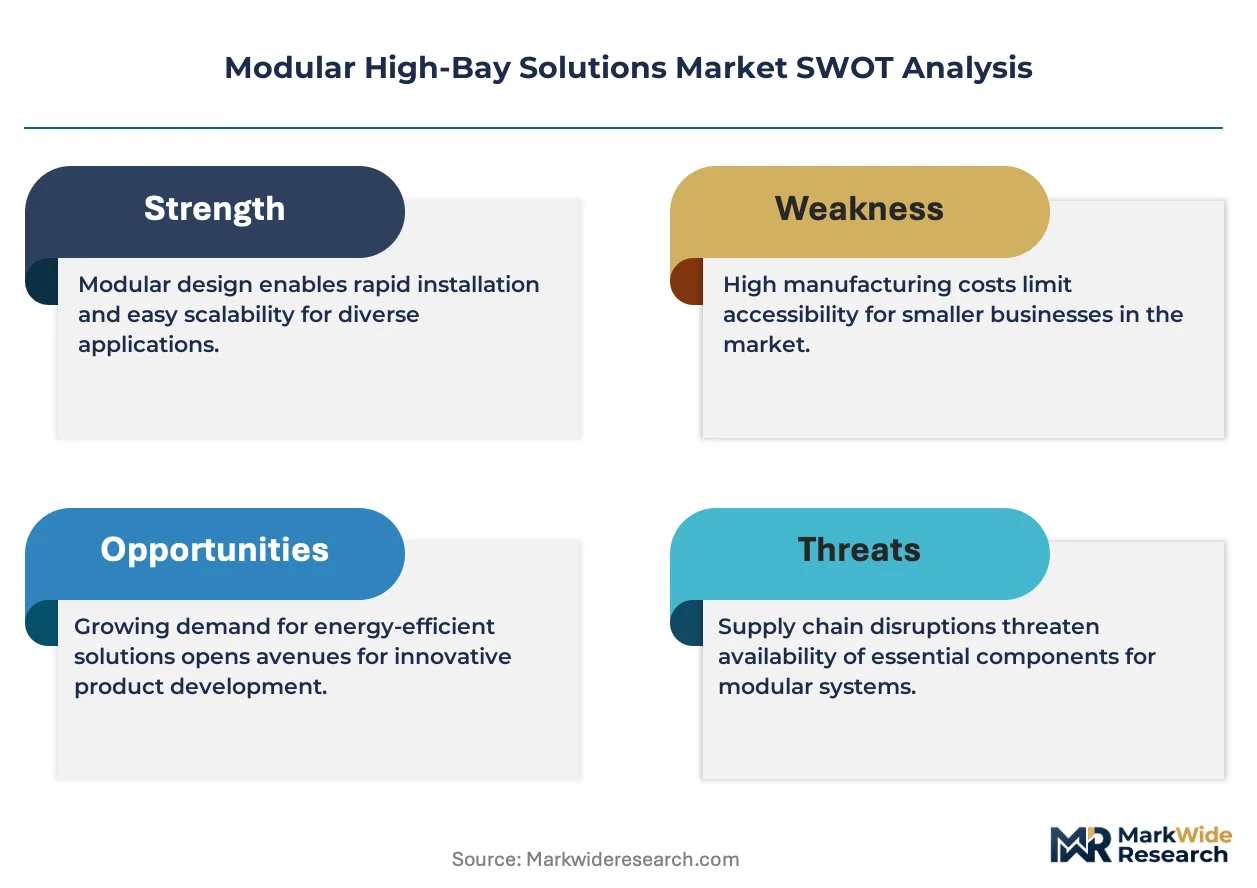
Integrated building management platforms threaten standalone luminaire vendors by collapsing procurement decisions into single automation bundles. Incumbents must defend against this substitution by anchoring specification authority before corporate energy teams centralize purchasing.
For Market Incumbents: Secure ENEC certification renewal cycles ahead of three-year rotation deadlines to maintain European public procurement eligibility. Deepen backward integration into LED driver electronics to compress thermal management footprints and match compact module specifications from Yangtze River Delta competitors. Channel control through electrical distributor exclusivity agreements defends position against sensor-luminaire convergence plays by building automation vendors.
For New Entrants and Emerging Players: Fast-track UL certification for Texas utility rebate program eligibility unlocks immediate specification access in the Dallas-Fort Worth corridor. Target Georgia and South Carolina distribution hubs where integrated power distribution systems remain underpenetrated. Lead with energy-as-a-service contract structures that shift capital burden to equipment financiers, mirroring procurement shifts among national logistics operators.
For Investors and Strategic Acquirers: Capital is best deployed toward sensor-luminaire convergence specialists with Bluetooth mesh capabilities and existing building automation protocol integration. Long-term viability hinges on digital control layer displacement of standalone specifications. Watch for inflection when corporate energy procurement teams in Southeast US corridors mandate occupancy-based dimming as baseline requirement rather than upgrade option.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Luminaire Convergence | Bluetooth mesh integration captures specification authority from standalone lighting vendors in Texas corridors. |
| Backward Integration into LED Drivers | In-house thermal management electronics compress footprints for narrow-aisle configurations in Southeast hubs. |
| ENEC Certification Fast-Track | Accelerated compliance cycles unlock European public procurement channels before three-year rotation deadlines. |
| Energy-as-a-Service Contract Launch | Performance-based leasing aligns with Dallas-Fort Worth logistics operator preference for asset-light procurement. |
| Austrian Engineering Center Acquisition | Glare-controlled optics expertise defends premium positioning in twelve-meter clearance cold storage applications. |
Research Methodology
The analysis maps pre-engineered modules, custom modular units, retrofit kits, and integrated control systems, each validated through facility engineering directors, corporate energy procurement managers, electrical distributor specification specialists, and building automation vendor product teams. Primary interviews with these stakeholders combined with secondary validation against FERC efficiency standard filings, OSHA illumination guideline updates, EU Ecodesign Directive threshold revisions, and utility demand-response program documentation. Bottom-up shipment data triangulates against top-down construction spending on logistics facilities across the analysis window.
Consistency checks validated volume and value outputs against aluminum extrusion import data, LED module trade flows, and cold storage construction permits. Segmentation dimensions modeled include product configurability tier, technology integration level, application environment, and end-user procurement centralization. CAGRs derived from installed base turnover rates, retrofit cycle timing, and new build specification trends. Industry-specific inputs incorporate F-Gas Regulation compliance cost burdens and Texas utility rebate structure evolution.
Underlying assumptions cover stable LME aluminum pricing, ENEC certification cycle continuity, and OSHA enforcement intensity, with deviation risk concentrated in commodity price spikes and regulatory threshold acceleration. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Conveyor-Free Sortation Modules Market
Industrial Automation
India Industrial Automation Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
Factory Automation Market