
 Europe Industrial Embedded Systems Market | 2026-2036
Europe Industrial Embedded Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Embedded Systems Market Insights
CE marking under the EU Machinery Directive is redrawing competitive boundaries for industrial embedded suppliers in Europe. Infineon Technologies leverages its Dresden fabrication complex to sustain captive silicon supply for automotive-grade microcontrollers. NXP Semiconductors N.V. anchors its European position through specialized security-certified portfolios serving industrial IoT gateways. STMicroelectronics N.V. dominates the Mediterranean basin with vertically integrated manufacturing from Catania to Grenoble.
Industrial embedded systems integrate dedicated computing hardware with real-time operating firmware to execute deterministic control functions in manufacturing environments, typically operating within sub-millisecond latency thresholds and temperature ranges from minus 40 to 85 degrees Celsius. Microcontrollers command the largest product volume share due to their cost-optimized integration of processor core, memory, and peripherals on single die architectures. Real-time operating systems represent the fastest-expanding technology layer as European OEMs prioritize deterministic scheduling for safety-critical robotics and process control deployments.
The EU Cyber Resilience Act and REACH chemical compliance frameworks are elevating certification costs while restricting hazardous substance use in embedded hardware substrates. ECHA substance restrictions are forcing reformulation of solder alloys and PCB laminates across European supply chains. Stakeholders must monitor harmonized standards evolution under the EU AI Act as machine learning inference migrates onto edge devices in automated production lines.
Market Dynamics
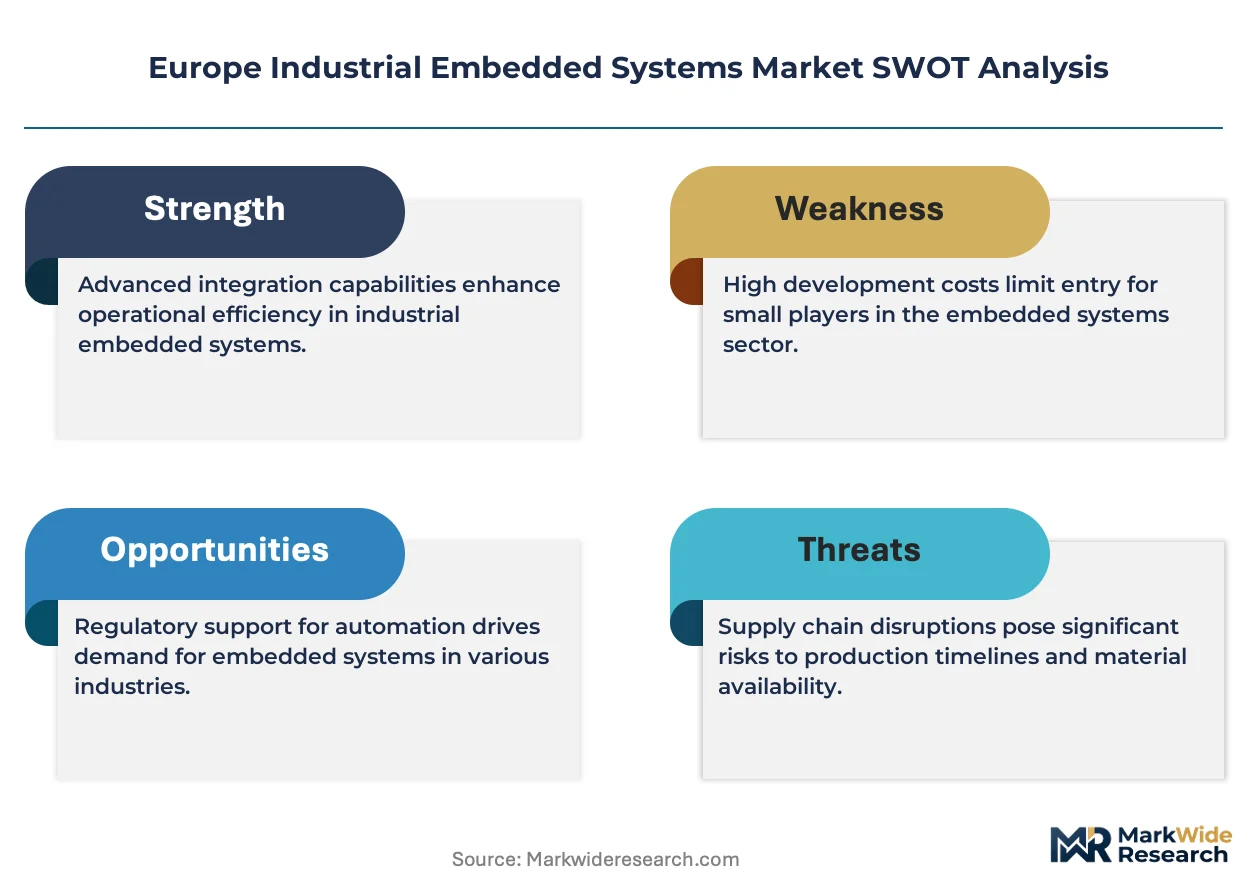
CE marking requirements under the EU Machinery Directive are forcing embedded suppliers to redesign hardware architectures for deterministic safety compliance, while the EU Cyber Resilience Act mandates security-by-design integration from silicon to firmware layers.
Growth Catalysts
- Electric powertrain controllers:German automotive OEMs are expanding embedded procurement for motor control units and battery management systems as production lines pivot from internal combustion.
- EU Cyber Resilience Act:Mandated security-by-design requirements across connected industrial devices are creating mandatory replacement cycles for legacy controllers lacking hardware root-of-trust capabilities.
- Ruhr industrial cluster:Concentrated demand from steel, chemicals, and heavy machinery producers in Germany's industrial heartland is pulling specialized real-time embedded solutions.
Market Restraints
- Silicon supply concentration:Advanced microcontroller fabrication remains captive to a handful of European foundries, exposing buyers to allocation risk during capacity constraints.
- ECHA substance restrictions:REACH-mandated reformulation of solder alloys and PCB laminates is elevating material costs and qualifying timelines for hardware substrates.
- Technical limitation:Sub-millisecond deterministic latency requirements in safety-critical robotics exceed the capabilities of general-purpose processor architectures without specialized co-processor integration.
Strategic Opportunities
- Bavarian automation corridor:Underpenetrated small-to-mid-size machine builders in southern Germany present white space for modular embedded platforms with pre-certified safety stacks.
- EU AI Act harmonization:Emerging standards for machine learning inference on edge devices create first-mover advantage for suppliers offering documented algorithmic transparency and audit trails.
- Real-time operating systems:Convergence of time-sensitive networking with deterministic scheduling is opening new application layers in process control and collaborative robotics.
Industry Challenges
- Functional safety engineering:Scarce talent pools for IEC 61508 and ISO 13849 certification expertise are extending product development timelines and inflating compensation costs.
- Multi-standard compliance:Simultaneous navigation of CE marking, REACH substance restrictions, and emerging EU AI Act requirements demands dedicated regulatory affairs infrastructure that mid-size suppliers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Embedded Systems Market |
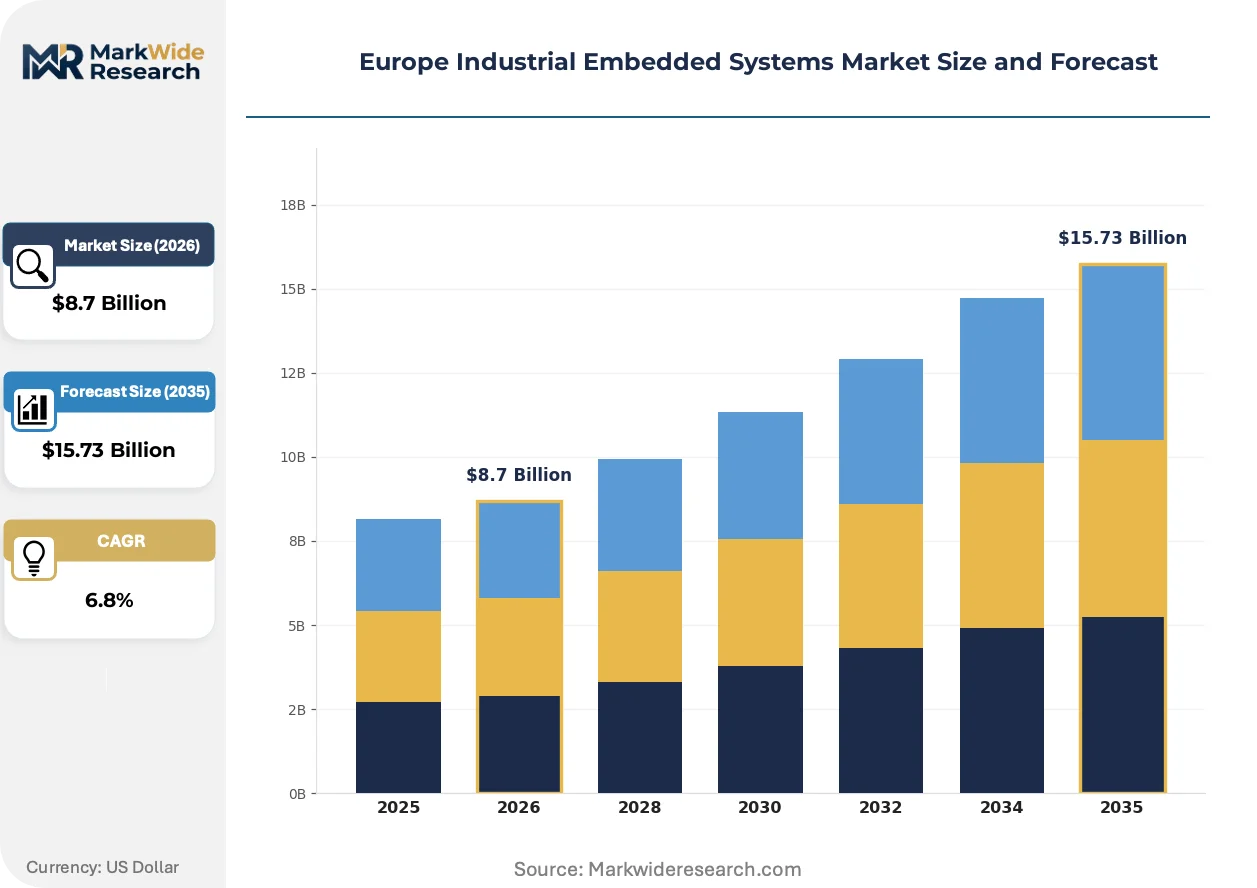
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Digital Signal Processors, Microcontrollers, System on Chip End User: Manufacturing, Automotive, Aerospace, Telecommunications Technology: Embedded Software, Real-Time Operating Systems, Hardware, Communications Protocols Application: Process Control, Machine Automation, Robotics, Energy Management |
| Companies Covered | Infineon Technologies, Texas Instruments Inc., NXP Semiconductors N.V., Renesas Electronics Corporation, Advantech Co. Ltd., Intel Corporation, STMicroelectronics N.V., Microchip Technology Inc., Qualcomm Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Embedded Systems Market Trends and Innovations
Deterministic edge computing architectures are displacing centralized control topologies across European manufacturing floors, while regulatory mandates accelerate hardware refresh cycles and buyer procurement models favor pre-integrated platform solutions over component sourcing.
Time-sensitive networking over standard Ethernet is displacing proprietary fieldbus protocols in industrial embedded deployments. Automotive and machine tool builders in Stuttgart and Munich are adopting TSN-enabled controllers at pace. This convergence is displacing decades-old PROFIBUS and CAN infrastructure, compressing supplier margins on legacy protocol stacks while rewarding early TSN certifiers.
REACH chemical compliance is forcing systematic reformulation of embedded hardware substrates across European supply chains. ECHA restrictions on lead and halogenated flame retardants are disqualifying incumbent PCB laminates and solder alloys. Industrial IoT gateway manufacturers in France and Italy are responding fastest, accelerating qualification of alternative metallurgy and bio-based laminates ahead of enforcement windows.
Machine builders are consolidating vendor relationships around platform suppliers offering pre-certified safety and security stacks. German automotive tier-1s now specify embedded controllers with integrated CE marking documentation and hardware root-of-trust, displacing historical component-level procurement. This concentration is most visible in Bavaria, where mid-size automation OEMs are reducing qualified supplier lists from dozens to single-digit platform partnerships.
Europe Industrial Embedded Systems Market Segmentation
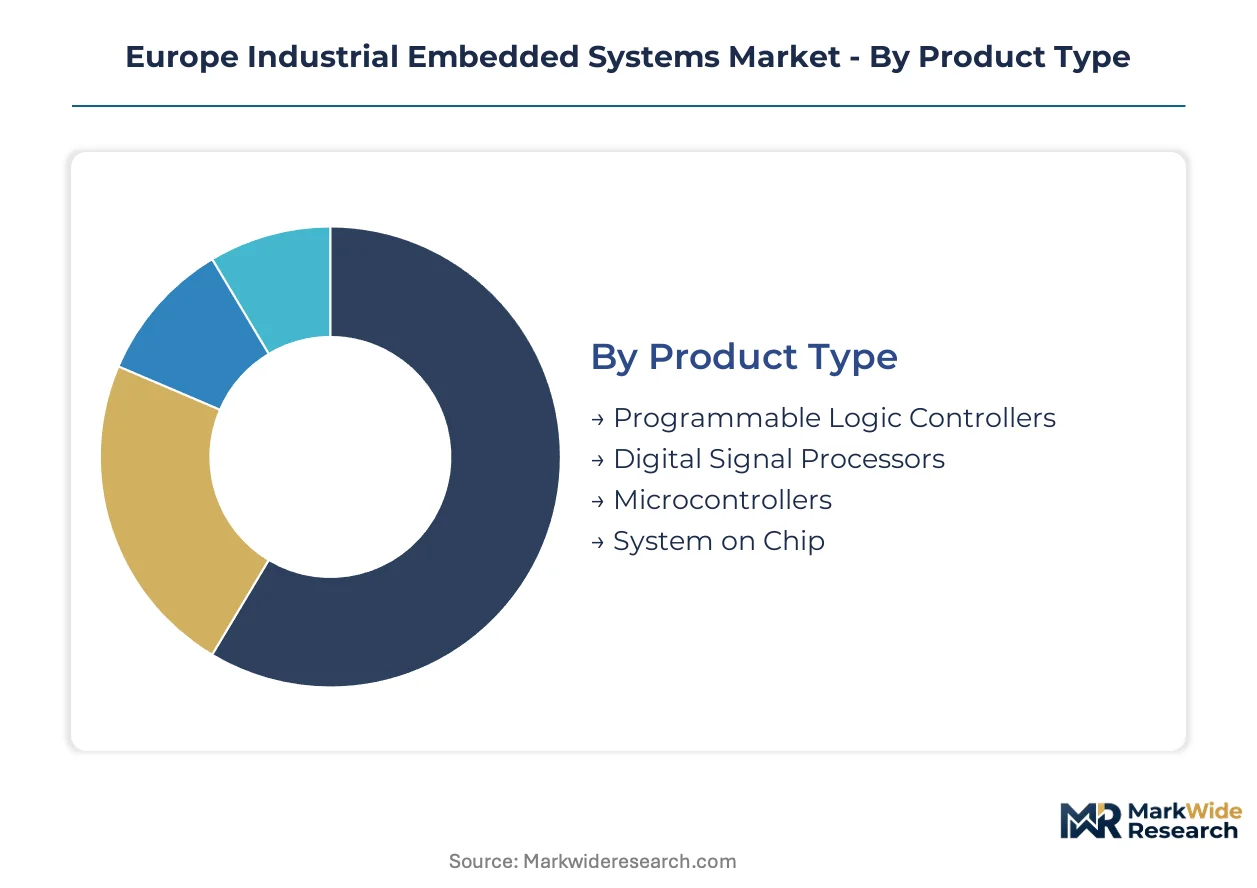
Segmentation in Europe's industrial embedded systems market reveals divergent sourcing patterns across product architectures and end-use verticals. German automotive OEMs and Ruhr-based heavy industry drive distinct procurement specifications that reshape supplier priorities across each category.
Product Type:
Microcontroller demand concentrates in domestic German supply chains serving automotive tier-1s, while System on Chip procurement pulls heavily from export-oriented Mediterranean manufacturing hubs.
- Microcontrollers:Single-die architectures integrate processor cores, memory arrays, and peripheral interfaces at cost-optimized price points. Demand clusters in Stuttgart and Munich automotive corridors where motor control units and battery management systems require deterministic execution within strict thermal envelopes.
- System on Chip:Heterogeneous integration of CPU, GPU, neural accelerators, and security enclaves enables edge AI inference for industrial IoT gateways. French and Italian gateway manufacturers in Grenoble and Milan are accelerating adoption ahead of EU AI Act harmonization deadlines.
- Programmable Logic Controllers:Modular rack-mounted controllers dominate legacy process installations across Belgium's chemical corridor.
- Digital Signal Processors:Specialized floating-point architectures serve vibration analysis and predictive maintenance in Nordic pulp and paper mills.
Microcontrollers command the established base. The steepest expansion runs through System on Chip.
End User:
Cost tier stratification separates safety-certified automotive deployments from price-sensitive manufacturing automation, with aerospace representing premium-margin custom engineering.
- Automotive:Functional safety requirements under ISO 26262 mandate lockstep processor cores and hardware memory protection. German OEMs in Wolfsburg and Ingolstadt specify embedded controllers with integrated CE marking documentation and hardware root-of-trust capabilities.
- Manufacturing:Discrete automation and process control applications span food processing in the Netherlands to steel rolling in Duisburg. Machine builders prioritize deterministic latency over compute density, favoring real-time operating systems on modest microcontrollers.
- Aerospace:DO-178C software certification and extended temperature qualification drive extended development timelines for flight control and avionics subsystems.
- Telecommunications:5G baseband processing and edge computing nodes pull high-throughput signal processing into industrial embedded form factors.
Manufacturing absorbs the highest unit volumes. Automotive generates the steepest revenue per unit.
Technology:
Application maturity separates decades-proven hardware architectures from rapidly evolving software stacks where certification lag creates competitive friction.
- Real-Time Operating Systems:Deterministic scheduling kernels with sub-microsecond context switching enable safety-critical robotics and synchronous motion control. Stuttgart machine tool builders are adopting TSN-enabled RTOS distributions at pace, displacing legacy proprietary kernels.
- Embedded Software:Firmware stacks integrate hardware abstraction layers, communication stacks, and safety monitors. Bavarian automation OEMs now require pre-certified software components to compress qualification timelines.
- Hardware:PCB substrates and solder interconnects face REACH-mandated reformulation of alloys and laminates.
- Communications Protocols:Time-sensitive networking over standard Ethernet is displacing PROFIBUS and CAN infrastructure across European factory floors.
Hardware commands the established installed base. Real-Time Operating Systems are climbing the fastest.
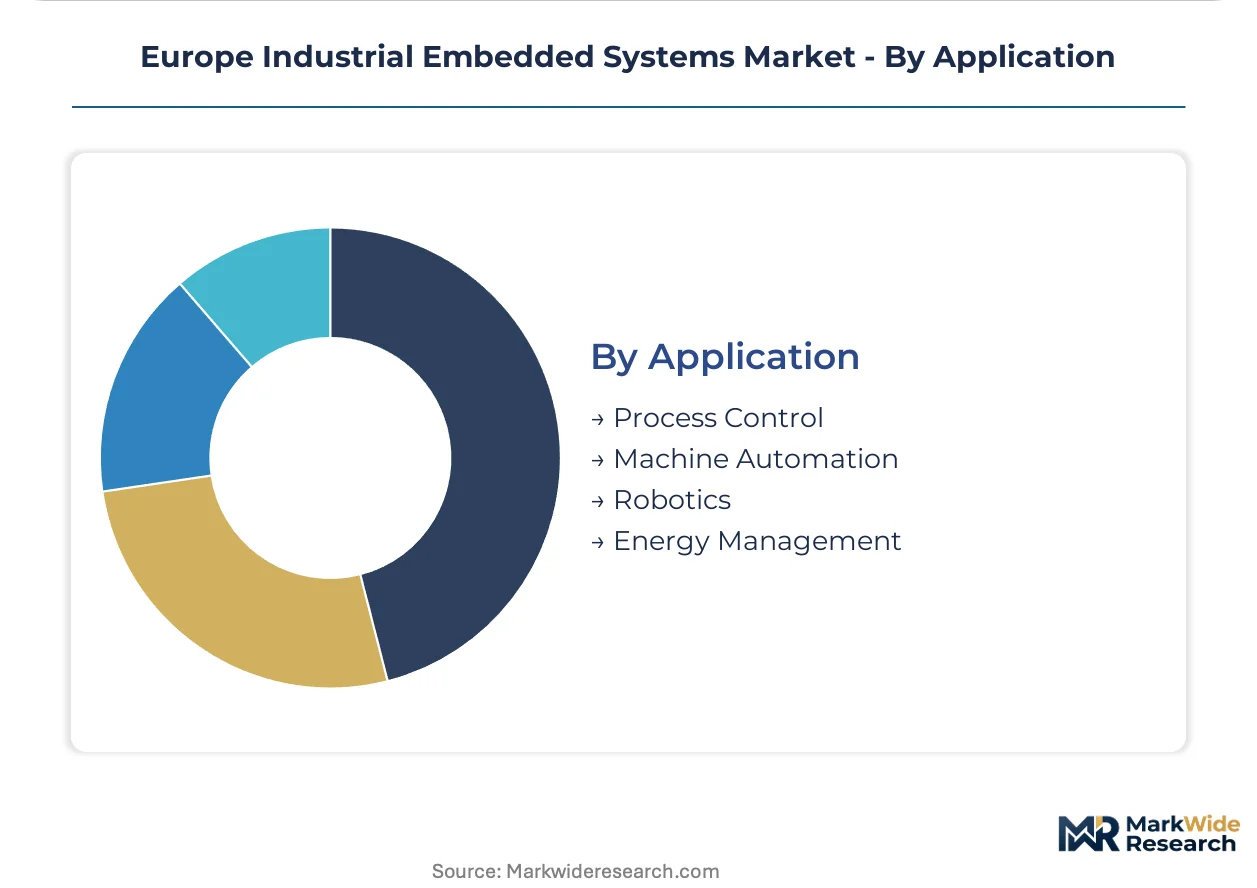
Application:
Volume concentration in process industries contrasts with robotics growth acceleration, while energy management emerges from efficiency mandates.
- Process Control:Distributed control systems for chemical, pharmaceutical, and food processing require 24/7 availability with SIL-rated reliability. Rotterdam and Antwerp petrochemical complexes sustain demand for hardened controllers with redundant power architectures.
- Robotics:Collaborative robot arms and autonomous mobile platforms demand sensor fusion, trajectory planning, and safety monitoring on unified embedded platforms. Danish and Swedish robot OEMs are consolidating supplier relationships around pre-integrated safety stacks.
- Machine Automation:CNC systems and packaging machinery in northern Italy favor modular embedded platforms with field-replaceable I/O modules.
- Energy Management:Grid-tied inverters and building automation controllers integrate power measurement with cloud connectivity for demand response programs.
Process Control retains the deepest installed base. Robotics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Ruhr-based heavy industry anchor procurement volume, while Mediterranean gateway manufacturers and Nordic robotics clusters pull specialized embedded architectures. Buyers concentrate in three corridor types: automotive engineering belts, legacy process industry basins, and emerging automation hubs seeking pre-certified platform solutions.
Germany
Stuttgart and Munich automotive corridors drive demand for ISO 26262-certified motor control units and battery management systems as production pivots from combustion engines. The EU Cyber Resilience Act mandates hardware root-of-trust integration for connected industrial devices sold into German manufacturing. Bavarian automation OEMs are consolidating supplier relationships around single-digit platform partnerships with pre-integrated safety stacks.
France
Grenoble-based industrial IoT gateway manufacturers accelerate System on Chip adoption for edge AI inference ahead of EU AI Act harmonization deadlines. ECHA REACH restrictions on halogenated flame retardants are forcing PCB laminate reformulation across French supply chains. The Auvergne-Rhône-Alpes cluster hosts specialized embedded security certification expertise serving aerospace and nuclear applications.
Italy
Milan and Turin machine builders favor modular embedded platforms with field-replaceable I/O modules for CNC and packaging machinery. CE marking requirements under the EU Machinery Directive compress qualification timelines for Italian automation exports. Northern Italy's packaging machinery corridor is adopting time-sensitive networking controllers to displace legacy fieldbus infrastructure.
Netherlands
Rotterdam and Antwerp petrochemical complexes sustain demand for SIL-rated distributed control systems with redundant power architectures. The EU Green Deal carbon border adjustments are pulling energy management embedded controllers into Dutch process industries. Eindhoven's high-tech systems cluster supplies specialized real-time operating systems for semiconductor manufacturing equipment.
Sweden
Danish and Swedish robot OEMs consolidate supplier relationships around pre-integrated safety stacks for collaborative robot arms and autonomous mobile platforms. Nordic pulp and paper mills deploy specialized digital signal processors for vibration analysis and predictive maintenance. Stockholm's automation engineering talent pool supports deterministic scheduling kernel development for safety-critical robotics applications.
Europe Industrial Embedded Systems Market Competitive Landscape
Player mix skews toward diversified semiconductor conglomerates with captive European fabrication, supplemented by specialized industrial computing platforms and regional automation integrators. Three archetypes dominate: vertically integrated silicon suppliers with in-house microcontroller production, modular platform vendors offering pre-certified safety and security stacks, and application-specific system integrators serving single verticals. Competitive moves concentrate on strategic partnerships for TSN certification acceleration and portfolio diversification into edge AI inference hardware.
Within the diversified semiconductor tier, Infineon Technologies, NXP Semiconductors N.V., and STMicroelectronics N.V. represent the captive-fabrication archetype sustaining automotive-grade supply security. Infineon anchors German demand through its Dresden manufacturing complex. NXP occupies a position serving security-certified industrial IoT gateway portfolios. STMicroelectronics exemplifies Mediterranean-basin vertical integration from Catania to Grenoble. These three entities sit within the premium tier where functional safety certification and hardware root-of-trust capabilities determine competitive access.
| Leading Market Players |
|---|
| Infineon Technologies |
| Texas Instruments Inc. |
| NXP Semiconductors N.V. |
| Renesas Electronics Corporation |
| Advantech Co. Ltd. |
| Intel Corporation |
| STMicroelectronics N.V. |
| Microchip Technology Inc. |
| Qualcomm Incorporated |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with German automotive OEMs lock in silicon allocation from Dresden and Catania fabs while fixing price visibility against raw wafer indexation clauses. These arrangements insulate tier-1 suppliers from spot market volatility in microcontroller die pricing while committing buyers to minimum offtake volumes through the projection horizon.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-indexed copper and gold bonding wire adjustments dominate microcontroller procurement in Stuttgart automotive corridors. Three-tier pricing structure across ASIL-D certified, ASIL-B intermediate, and uncertified economy controllers separates German OEMs from Italian packaging machinery builders and Dutch food processors. Pricing pressure stems from REACH-mandated solder alloy reformulation elevating material costs. Italian machine builders exhibit highest price sensitivity, while aerospace integrators in Grenoble absorb premium certification tiers without volume negotiation.
Supply Chain Analysis
Germany and France anchor captive microcontroller fabrication through Infineon's Dresden complex and STMicroelectronics' Grenoble-Catania axis. Silicon wafers, rare-earth packaging ceramics, and halogen-free PCB laminates constitute critical input dependencies. Single-source vulnerability concentrates in advanced automotive-grade node capacity at European foundries. Distribution runs through authorized distributors serving tier-1 automotive suppliers and direct OEM contracts for high-volume machine builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards suppliers possessing IEC 61508 functional safety engineering depth and pre-certified hardware-software stacks, assets scarcer than fabrication capacity. Procurement consolidation around platform vendors reflects buyer willingness to pay premium pricing for integrated compliance documentation.
For Market Incumbents: Compound certification moats by accelerating TSN-enabled real-time operating system roadmaps ahead of EU harmonization deadlines. Deepen backward integration into security enclave IP to displace emerging fabless competitors lacking hardware root-of-trust capabilities. Lock Bavarian automation OEMs into multi-year platform partnerships before REACH enforcement windows elevate rival qualification costs. For New Entrants and Emerging Players: Differentiate on modular embedded platforms with pre-integrated CE marking documentation targeting underpenetrated mid-size machine builders in northern Italy. White space concentrates in collaborative robotics safety stacks where Danish and Swedish OEMs consolidate supplier relationships. Pursue direct engagement with Eindhoven's high-tech systems cluster for semiconductor manufacturing equipment real-time operating system opportunities. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated European semiconductor specialists with captive automotive-grade fabrication and security-certified portfolio breadth. Long-term viability hinges on sustained allocation priority from German automotive OEMs through electrification transition. Monitor EU AI Act harmonization timeline acceleration as inflection signal for edge AI inference hardware demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| TSN Certification Acceleration | Stuttgart machine tool builders displace legacy PROFIBUS infrastructure ahead of competitor qualification. |
| Security Enclave Integration | Hardware root-of-trust capabilities satisfy EU Cyber Resilience Act mandates for connected industrial devices. |
| REACH-Compliant Substrate Qualification | Alternative solder alloys and bio-based laminates preempt ECHA enforcement windows. |
| Pre-Certified Platform Partnerships | Bavarian automation OEMs reduce supplier lists from dozens to single-digit qualified vendors. |
| Edge AI Inference Hardware Development | Grenoble gateway manufacturers accelerate System on Chip adoption ahead of EU AI Act deadlines. |
Research Methodology
A spread of perspectives from embedded systems procurement directors at German automotive OEMs, functional safety engineering leads, industrial IoT gateway manufacturers, real-time operating system vendors, and ECHA regulatory affairs specialists converged on the working assumptions. Primary interview intelligence triangulated against customs data for microcontroller die imports, SEC filings from listed semiconductor suppliers, EU harmonized standards evolution tracking, and REACH substance restriction implementation timelines. Bottom-up demand modeling across automotive, manufacturing, and aerospace verticals validated against top-down European industrial automation capex surveys.
Segmentation dimensions modeled span product architecture, end-use vertical, technology layer, and application intensity across the analysis window. CAGRs derive from unit shipment trajectories by microcontroller die size and value-per-unit expansion from security certification premiums. Forecast inputs incorporate EU Cyber Resilience Act implementation phasing, electric powertrain controller procurement ramps from Wolfsburg and Ingolstadt, and time-sensitive networking protocol displacement curves.
The analysis sits within stated boundaries; outcomes outside sustained German automotive production volumes, ECHA enforcement adherence timelines, or EU AI Act harmonization schedules would require recalibration. Forecasts reflect documented assumptions regarding silicon foundry allocation priority and functional safety engineering talent availability. Recalibration cycles align with material shifts in regulatory enforcement windows and automotive platform electrification roadmaps.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Port Equipment Automation Market
Industrial Automation
United States Factory Automation and Industrial Controls Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
North America Machine Control System Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Factory Automation Market
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Pick and Place Machines Market