
 Software-Defined Machine Market | 2026-2036
Software-Defined Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Software-Defined Machine Market Analytics
Telecommunications is rebalancing as the fastest-growing end-use vertical for software-defined machines, displacing traditional manufacturing-centric deployment. Schneider Electric leverages its energy management heritage to anchor edge-control architectures in industrial settings. Siemens sustains deep R&D intensity across virtualization layers for factory automation. Intellectsoft competes through specialized containerized solutions that simplify legacy equipment retrofitting.
Software-defined machines decouple control logic from fixed hardware through programmable virtualization layers, enabling real-time reconfiguration of mechanical systems via API-driven commands. These systems typically operate on sub-10 millisecond latency thresholds to maintain safety-critical synchronization between digital instructions and physical actuators. Containerized Solutions and Hybrid Systems capture the strongest margin pools as end users prioritize portable workloads that traverse on-premises and edge environments. Control Software remains the largest revenue category but faces compression as customers bundle it with AI Integration technology stacks rather than purchasing standalone licenses.
The EU AI Act imposes conformity requirements on autonomous decision-making in industrial equipment, while FDA software validation guidelines shape medical device manufacturers' procurement criteria for programmable machinery. Germany's KBA and Japan's METI each enforce functional safety standards that determine market access for software-defined control systems in automotive and precision sectors. Stakeholders must monitor how regulatory divergence between European risk-based AI classifications and American performance-based standards fragments certification costs across supply chains.
Market Dynamics
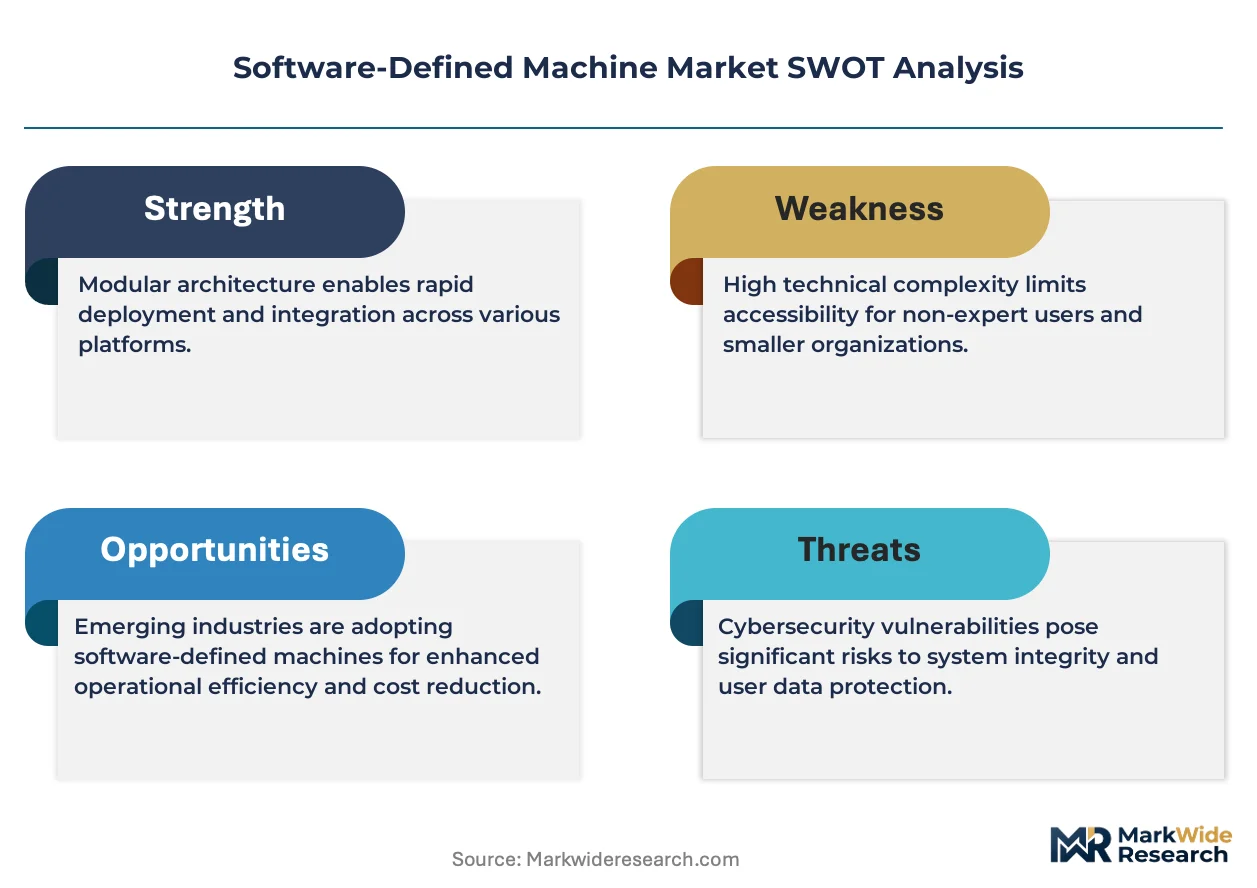
Containerized control systems are decoupling machine logic from fixed hardware, forcing vendors to rebuild revenue models around portable software workloads rather than perpetual equipment sales.
Growth Catalysts
- EU AI Act conformity requirements:Industrial equipment manufacturers must embed auditable decision-making trails into autonomous control systems, creating mandatory upgrade cycles for legacy installations.
- Automotive precision engineering clusters:Germany's KBA functional safety standards are accelerating validation protocols for software-defined production lines in battery assembly and powertrain manufacturing.
- Sub-10 millisecond latency thresholds:Edge computing architectures now synchronize digital instructions with physical actuators in real time, enabling safety-critical reconfiguration of mechanical systems via API commands.
Market Restraints
- Specialized engineering talent scarcity:Control software development requires rare expertise spanning virtualization layers, functional safety certification, and real-time operating systems.
- Semiconductor supply concentration:Industrial-grade processors for deterministic control face allocation constraints from concentrated foundry capacity in East Asian manufacturing hubs.
- FDA software validation timelines:Medical device manufacturers face 18-36 month certification cycles for programmable machinery, compressing procurement flexibility and delaying deployment.
Strategic Opportunities
- Telecommunications infrastructure modernization:5G network operators are deploying software-defined machines for automated cell site maintenance and remote diagnostics, displacing traditional manufacturing-centric adoption.
- Japan METI carbon neutrality mandates:Functional safety standards for energy-efficient control systems are creating procurement preferences for virtualization-based automation in precision engineering.
- Digital twin convergence:Physics-based simulation environments are merging with live control systems, enabling predictive reconfiguration of production lines before physical deployment.
Industry Challenges
- Legacy equipment retrofit complexity:Brownfield installations require custom gateway architectures to translate proprietary fieldbus protocols into containerized control environments.
- Cross-jurisdictional certification fragmentation:Divergent risk-based AI classifications in Europe and performance-based standards in the United States multiply compliance costs for multinational equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software-Defined Machine Market |
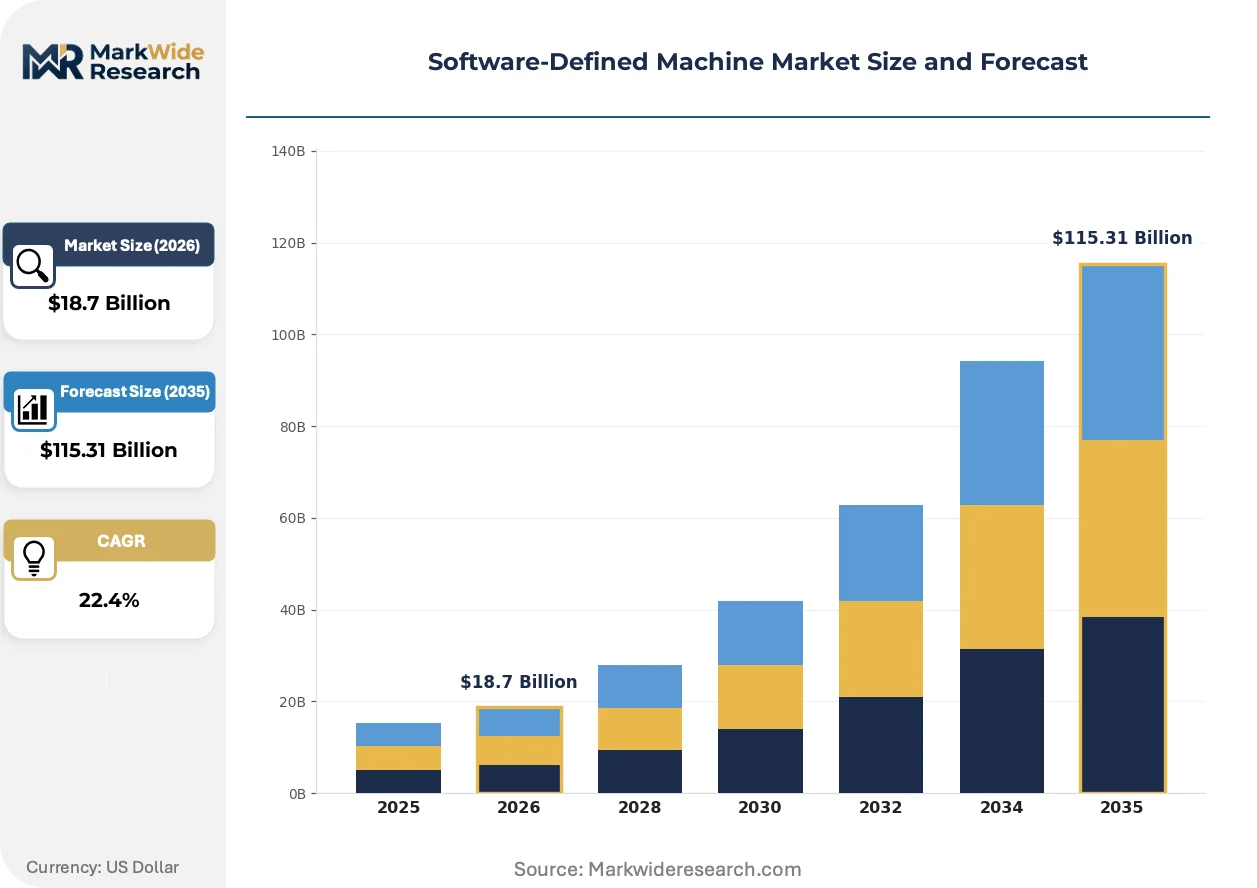
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Machines, Containerized Solutions, Control Software, Hybrid Systems End User: Manufacturing, Logistics, Telecommunications, Aerospace Deployment: On-Premises, Cloud-Based, Edge Computing, Hybrid Cloud Technology: AI Integration, Automated Management, Virtualization, Network Function Virtualization |
| Companies Covered | Webisoft, Markovate, Schneider Electric, SumatoSoft, Intellectsoft, Siemens, Scopic, Simform, Classic Informatics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software-Defined Machine Market Evolving Landscape
Real-time virtualization is collapsing the boundary between software development and mechanical operation, enabling continuous deployment pipelines for industrial control systems previously locked to hardware release cycles.
Containerized control software is converging with hardware abstraction layers to standardize how programmable logic executes across heterogeneous machine architectures. Automotive manufacturers in Stuttgart and Wolfsburg are piloting these stacks for assembly line reconfiguration measured in hours rather than weeks. This convergence is compressing vendor lock-in duration and fragmenting market share among specialized virtualization providers.
The EU AI Act risk classification framework is mandating conformity assessments for autonomous decision-making in industrial equipment. Machinery producers must now document training data provenance and decision audit trails for high-risk applications. Medical device and automotive sectors face the steepest compliance burdens, with procurement teams rewriting supplier qualification criteria to exclude non-conforming control architectures.
Buying organizations are unbundling software licenses from hardware procurement, treating control systems as subscription workloads rather than capital assets. German automotive OEMs and Japanese precision engineering groups are leading this shift, pressuring vendors to separate perpetual equipment margins from recurring software revenue. Equipment financiers in these markets are restructuring lease terms to accommodate usage-based billing for programmable automation.
Software-Defined Machine Market Segmentation
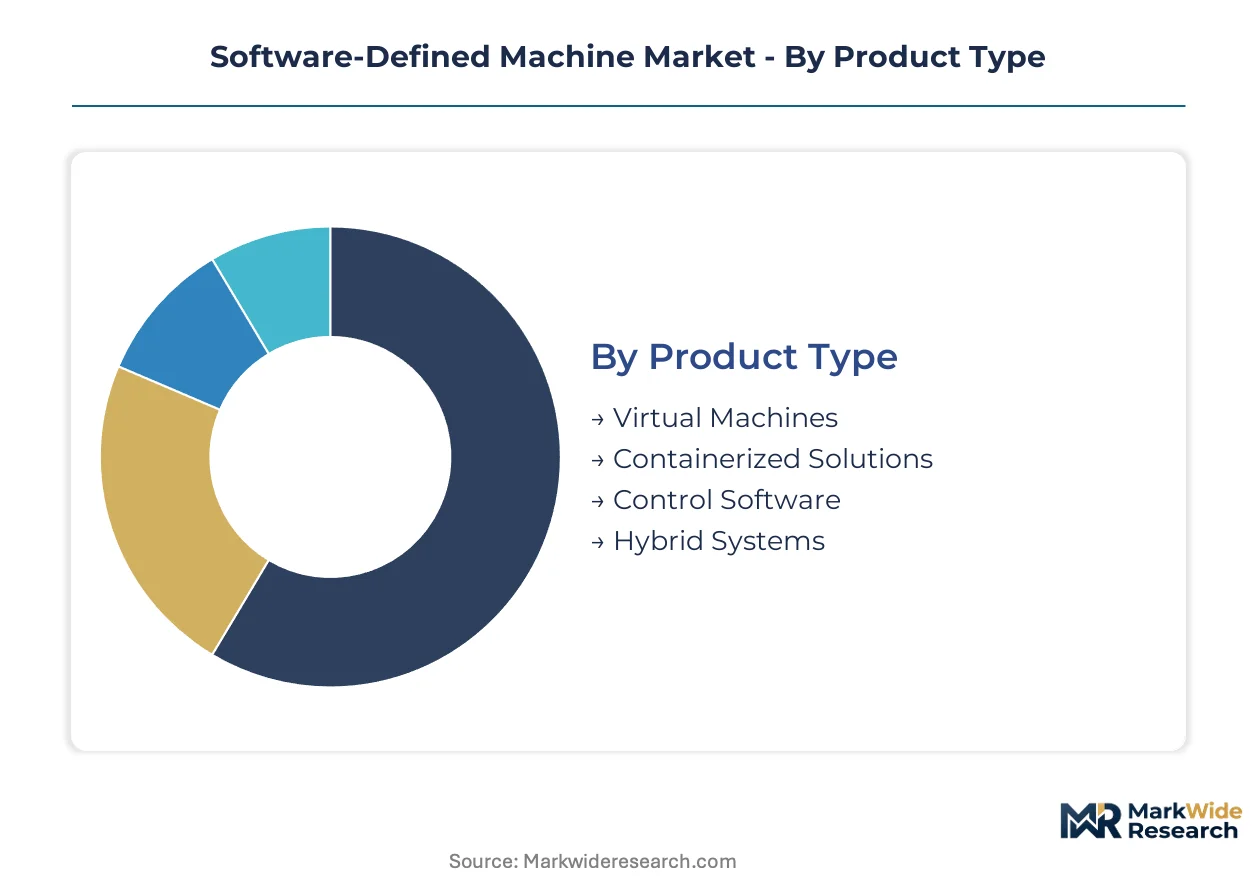
Software-defined machines fragment across multiple technical axes that determine procurement patterns and margin structures. Buyers prioritize deployment flexibility and latency performance when selecting between virtualization architectures. Each segmentation layer reveals distinct competitive dynamics between incumbent industrial vendors and specialized software providers.
Product Type:
Virtualization architecture determines how control logic executes across hardware substrates, shaping both technical capabilities and commercial terms for end users.
- Virtual Machines:Full-stack emulation environments isolate operating systems from underlying hardware through hypervisor abstraction. Automotive battery assembly lines in Stuttgart deploy these for legacy PLC migration, though boot latency limits real-time reconfiguration scenarios.
- Containerized Solutions:Lightweight runtime environments package control applications with dependencies for portable execution across edge and cloud nodes. Telecommunications operators favor these for 5G cell site automation, where sub-10 millisecond synchronization demands deterministic container orchestration.
- Control Software:Standalone programmable logic platforms decouple motion control from fixed hardware configurations. German precision engineering clusters bundle these with hardware procurement under traditional capital expenditure models.
- Hybrid Systems:Architectures blending virtual machine isolation with containerized workload portability span heterogeneous machine fleets. Japanese automotive OEMs pilot these for powertrain lines requiring both legacy compatibility and modern API interfaces.
Mature deployment sits with Control Software. Newer deployment is concentrated in Containerized Solutions.
End User:
Application context dictates latency requirements, safety certification burdens, and integration complexity for software-defined control implementations.
- Manufacturing:Discrete and process automation environments deploy software-defined architectures for assembly line reconfiguration. FDA software validation guidelines compress procurement flexibility for medical device manufacturers, while EU AI Act conformity requirements reshape supplier qualification criteria for autonomous equipment.
- Logistics:Warehouse automation and material handling systems utilize API-driven machine control for dynamic routing optimization. E-commerce fulfillment networks in the United States drive demand for rapid redeployment capabilities across seasonal volume fluctuations.
- Telecommunications:Network infrastructure operators automate physical infrastructure through software-defined remote diagnostics. 5G deployment acceleration in Japan and Germany displaces traditional manufacturing-centric adoption patterns for control virtualization.
- Aerospace:Safety-critical manufacturing and maintenance operations impose stringent functional safety standards on programmable automation. FAA certification timelines for flight-critical systems extend procurement cycles compared to industrial applications.
Volume concentration remains with Manufacturing. Steepest expansion trajectory belongs to Telecommunications.
Deployment:
Infrastructure location determines data sovereignty exposure, latency performance, and operational technology integration depth for control system implementations.
- On-Premises:Control systems execute within facility-bound compute infrastructure, maintaining deterministic performance for safety-critical mechanical synchronization. German automotive OEMs retain these deployments for powertrain assembly where network interruption risks exceed cloud migration benefits.
- Cloud-Based:Centralized compute resources host control logic with elastic scaling for non-deterministic workloads. Predictive maintenance analytics and digital twin simulation dominate this deployment mode where sub-second latency tolerance exists.
- Edge Computing:Distributed nodes position compute resources proximal to physical actuators, achieving sub-10 millisecond synchronization thresholds. Telecommunications cell site maintenance and precision engineering applications in Japan favor this architecture for real-time reconfiguration.
- Hybrid Cloud:Workload portability spans on-premises, edge, and cloud infrastructure according to latency and sovereignty requirements. Multi-national equipment vendors leverage these deployments to navigate divergent EU and United States regulatory frameworks.
Established infrastructure favors On-Premises. Investment flows concentrate in Edge Computing.
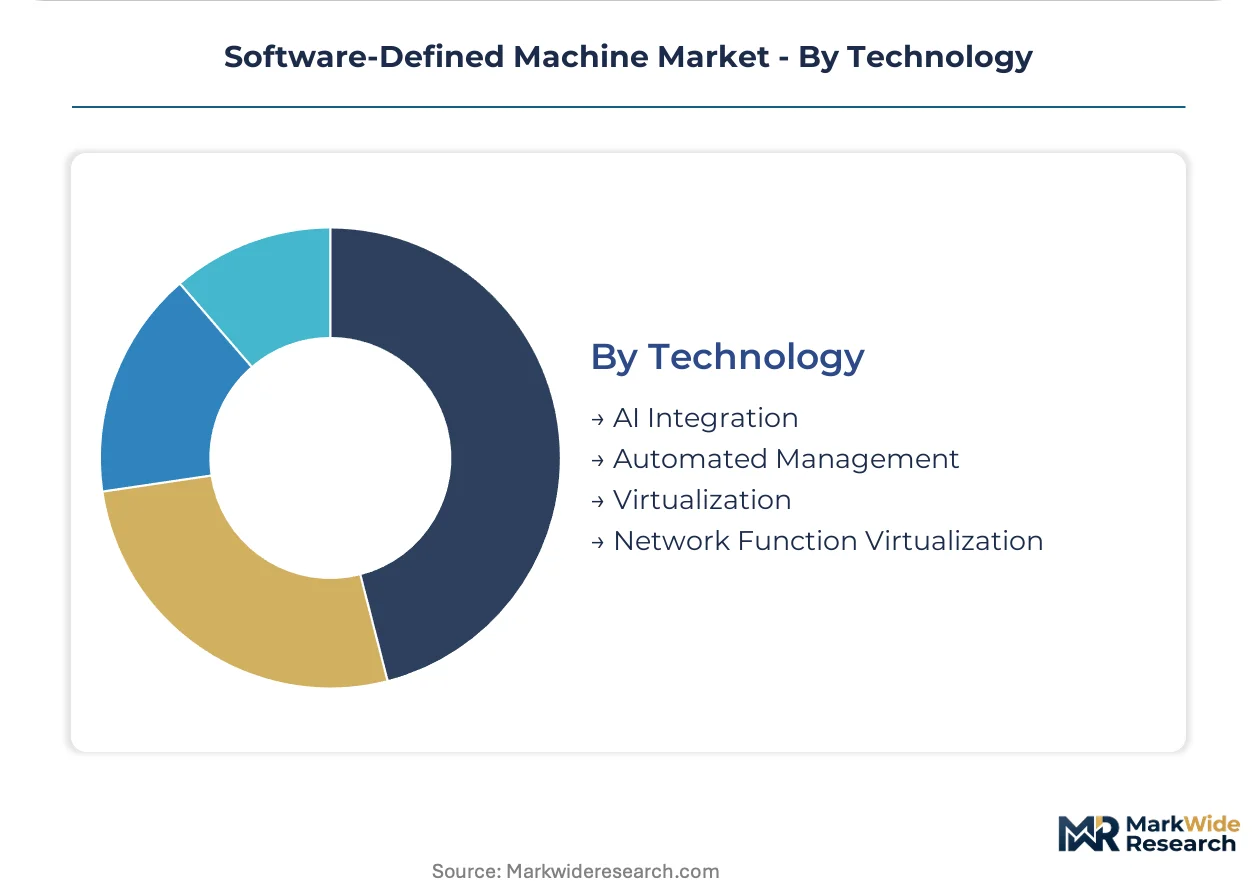
Technology:
Functional layer specialization determines how software abstraction translates into mechanical action, with distinct talent requirements and vendor ecosystems for each approach.
- AI Integration:Machine learning inference engines embed autonomous decision-making into control loops, triggering EU AI Act conformity assessments for high-risk industrial applications. Medical device manufacturers face steepest documentation burdens for training data provenance and audit trails.
- Automated Management:Policy-driven orchestration platforms provision and reconfigure machine resources without manual intervention. Logistics networks utilize these for dynamic capacity allocation across distributed fulfillment nodes.
- Virtualization:Hardware abstraction layers decouple control software from specific processor architectures, enabling portable workload execution. Containerized control convergence with these layers standardizes programmable logic across heterogeneous machine fleets.
- Network Function Virtualization:Telecommunications-specific control plane virtualization automates radio access network and core infrastructure management. 5G operators deploy these for automated cell site diagnostics and remote maintenance procedures.
Foundation technology resides with Virtualization. Capability expansion is accelerating fastest in AI Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Stuttgart, Wolfsburg, and Munich concentrate software-defined machine deployment through tax incentives tied to Industry 4.0 modernization. These zones attract precision engineering clusters seeking programmable automation infrastructure.
Germany
Automotive battery assembly and powertrain manufacturing drive demand for containerized control systems. KBA functional safety standards mandate validation protocols for autonomous production lines. Stuttgart and Wolfsburg clusters pilot sub-10 millisecond latency architectures for real-time line reconfiguration.
United States
Telecommunications infrastructure modernization and logistics automation propel software-defined machine adoption. FDA software validation guidelines compress procurement timelines for medical device manufacturers deploying programmable machinery. E-commerce fulfillment networks in the Midwest and Southeast deploy API-driven control for seasonal capacity fluctuations.
Japan
METI carbon neutrality mandates create procurement preferences for energy-efficient virtualization-based automation. Functional safety standards for precision engineering equipment determine market access for foreign control system vendors. Nagoya and Osaka industrial corridors lead powertrain line modernization with hybrid cloud deployments.
China
MIIT industrial internet policies accelerate domestic substitution in programmable automation control layers. GB standards for functional safety shape certification requirements for autonomous manufacturing equipment. Yangtze River Delta manufacturing hubs integrate edge computing nodes for real-time mechanical synchronization.
South Korea
Seoul Capital Area semiconductor and display manufacturing clusters demand deterministic control virtualization for sub-millisecond process synchronization. MFDS medical device regulations influence procurement criteria for programmable diagnostic equipment. Busan-Ulsan automotive component suppliers retrofit legacy lines with containerized control gateways.
Software-Defined Machine Market Competitive Landscape
Top-tier vendors anchor premium virtualization layers, while mid-tier specialists compete on legacy retrofit integration. The vendor base stratifies across three tiers: industrial conglomerates with energy management heritage, specialized containerization providers, and software development consultancies. Two strategic archetypes dominate: full-stack platform vendors and niche retrofit specialists. Competitive moves concentrate on strategic partnerships for edge-control architectures and portfolio diversification into AI integration layers.
Within the industrial heritage tier, Schneider Electric and Siemens occupy positions defined by energy management and factory automation lineages respectively. Intellectsoft represents the specialized containerization archetype, anchoring solutions for brownfield equipment modernization. These three entities exemplify how vendor positioning fragments across virtualization depth, hardware abstraction capability, and legacy protocol translation expertise.
| Leading Market Players |
|---|
| Webisoft |
| Markovate |
| Schneider Electric |
| SumatoSoft |
| Intellectsoft |
| Siemens |
| Scopic |
| Simform |
| Classic Informatics |
| Others |
Value Network & Pricing Analysis
Industrial-grade processor procurement costs cascade through three pricing tiers as virtualization software vendors bundle hardware abstraction layers with containerized control subscriptions. Semiconductor foundry allocation constraints in Taiwan and South Korea amplify lead-time premiums for deterministic real-time controllers serving German automotive and Japanese precision engineering clusters.
Pricing Analysis
Lead-time compression commands substantial premiums in software-defined machine procurement, with spot inventory availability triggering discounts of material magnitude against contracted subscription tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EU AI Act conformity and FDA software validation tiers anchor the premium band, while uncertified containerized solutions populate the economy tier. Pricing pressure stems from buyer unbundling of software licenses from hardware capital expenditure, with German automotive OEMs and Japanese precision engineering groups driving subscription-model adoption. Logistics networks exhibit highest price sensitivity due to seasonal volume fluctuation demands, whereas medical device manufacturers accept premium tiers to compress FDA validation timelines.
Supply Chain Analysis
Freight cost volatility from East Asian manufacturing hubs to European automotive clusters and North American telecommunications infrastructure sites compresses margin structures for containerized control system vendors. Supply concentration centers on Taiwan, South Korea, and China for industrial-grade processors with deterministic real-time capabilities. Raw material dependencies span silicon wafers, advanced packaging substrates, and rare earth elements for high-performance computing modules. Single-source vulnerability concentrates in advanced node semiconductor fabrication, where foundry capacity allocation determines control system delivery schedules. Distribution runs through direct OEM partnerships for large-scale manufacturing deployments, with systems integrators and channel partners serving mid-tier logistics and telecommunications operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized control architectures are displacing fixed-function PLCs across manufacturing and telecommunications infrastructure, creating a technology-transition phase where virtualization layer expertise determines competitive survival.
For Market Incumbents: Anchor defensive positioning through backward integration into edge computing hardware and captive development of functional safety certification pipelines. Threat substitution from specialized containerization providers like Intellectsoft fragments traditional equipment vendor lock-in duration. Priority levers include KBA and METI pre-certification investments for autonomous control systems, plus channel control consolidation in Stuttgart and Nagoya industrial corridors. For New Entrants and Emerging Players: Cloud-native distribution channels offer lowest-friction entry paths for containerized control software targeting brownfield retrofit demand. White-space concentrates in telecommunications 5G cell site automation and logistics warehouse API-driven reconfiguration, where incumbent industrial vendors lack software-native go-to-market velocity. Target Japanese precision engineering SMEs with hybrid cloud deployment models that navigate METI carbon neutrality procurement preferences. For Investors and Strategic Acquirers: FDA software validation guideline revisions are the leading indicator that medical device software-defined machine demand will inflect toward compliant control architectures. Long-term viability favors acquisition targets with vertical specialization in functional safety documentation and training data provenance systems. Signal to monitor: EU AI Act high-risk classification expansion into additional industrial equipment categories.| Strategic Initiative | Industry Significance |
|---|---|
| Containerized Control Platform Launch | Telecommunications operators in Germany and Japan deploy sub-10 millisecond orchestration for 5G cell site automation. |
| Functional Safety Certification Investment | KBA and FDA validation pipelines unlock procurement access in automotive battery assembly and medical device manufacturing. |
| Edge Computing Hardware Integration | Schneider Electric and Siemens anchor energy management heritage into distributed control node architectures. |
| Legacy Protocol Gateway Development | Brownfield retrofit demand in Busan-Ulsan automotive corridors requires proprietary fieldbus translation expertise. |
| AI Integration Layer Acquisition | EU AI Act conformity requirements mandate auditable decision-trail capabilities for high-risk industrial applications. |
Research Methodology
Independent corroboration across control systems engineering executives, telecommunications infrastructure procurement officers, and industrial automation channel partners underwrites the qualitative findings in this study. Primary fieldwork encompassed plant engineers at German automotive OEMs, platform architects at Japanese precision engineering groups, and integration specialists serving logistics networks. Secondary validation drew from SEC filings of industrial conglomerates, MIIT industrial internet policy disclosures, and EU AI Act implementation guidance documents. Bottom-up deployment modeling across virtualization architectures triangulates against top-down market sizing from equipment vendor revenue disclosures.
Rate-of-change decomposition separates volume expansion in telecommunications infrastructure from value migration toward AI Integration technology stacks across the projection horizon. Segmentation dimensions modeled include virtualization architecture type, end-use vertical, deployment infrastructure location, and functional safety certification tier. CAGRs derive from weighted scenario analysis across regulatory implementation timelines and semiconductor supply allocation trajectories. Industry-specific inputs encompass KBA validation protocol durations, FDA software certification cycle lengths, and METI carbon neutrality procurement preference adoption curves.
The model holds under sustained EU AI Act enforcement and stable East Asian semiconductor supply; deviation in tariff escalation or foundry capacity reallocation would shift deployment timelines. Forecasts reflect documented assumptions regarding regulatory convergence patterns and buyer unbundling velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Automotive Operating Systems Market
Software & Services
Software Market
Software & Services
Global Coworking Space Management Software Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Kennel Management Software Market
Software & Services
Applicant Tracking System (ATS) Market
Software & Services
Multivariate Testing Software Market
Software & Services
Application Virtualization Market
Software & Services
Labor Management Software Market
Software & Services
Recruitment Software Market
Software & Services
Global Pension Administration Software Market
Software & Services
Global Product Information Management (PIM) Software Market
Software & Services
Full Screen Website Screenshot Software Market
Software & Services
Server Software Market
Software & Services
POS Software Market