
 Monoethylene Glycol (MEG) Market | 2026-2036
Monoethylene Glycol (MEG) Market Size, Share, and Industry Trends Forecast 2026-2036
Monoethylene Glycol (MEG) Market Intelligence
Qualification against stringent standards like the United States Pharmacopeia (USP) for pharmaceutical-grade MEG is reorganizing the high-purity segment. SABIC leverages its massive scale in petrochemical production to influence commodity-grade pricing. China Petroleum & Chemical Corporation dominates supply within the crucial Chinese market. BASF SE differentiates through its portfolio of specialty chemical derivatives and sustainable MEG offerings.
Monoethylene glycol is a simple diol with the chemical formula C2H6O2, produced primarily via the hydration of ethylene oxide. Its primary industrial function is as a monomer, which polymerizes with terephthalic acid to form polyethylene terephthalate (PET). Polyester Grade MEG constitutes the largest product segment, directly supplying the PET value chain. While PET applications command the majority of volume, the Antifreeze & Coolants application provides a stable, albeit more mature, demand stream.
The European Union's REACH regulation imposes strict registration and evaluation requirements on MEG importers and manufacturers. In parallel, China's GB standards for chemical purity and US EPA rules for industrial chemicals govern market access and product handling protocols. Navigating the divergent regional sustainability mandates for bio-based versus fossil-fuel-derived MEG will define future investment decisions.
Market Dynamics
The central dynamic shaping the Monoethylene Glycol market is the structural tension between massive, low-cost commodity production concentrated in China and the growing demand for high-purity, sustainably-sourced MEG driven by brand owner commitments and stringent regulations in Western markets.
Growth Catalysts
- PET Fiber Demand:Sustained consumption from the textile industry for polyester fiber production, particularly in Asia's manufacturing hubs, remains the primary volume driver for the Polyester Grade MEG segment.
- Chinese Capacity Expansion:Focused investments in new production facilities within China's Zhejiang and Jiangsu provinces create localized economies of scale, supporting downstream polyester and PET resin industries in the region.
- Bio-Based Feedstock Viability:Policies promoting circular economy principles, especially in Europe, are accelerating research and investment into commercial-scale bio-MEG, creating a premium market segment for renewable chemicals.
Market Restraints
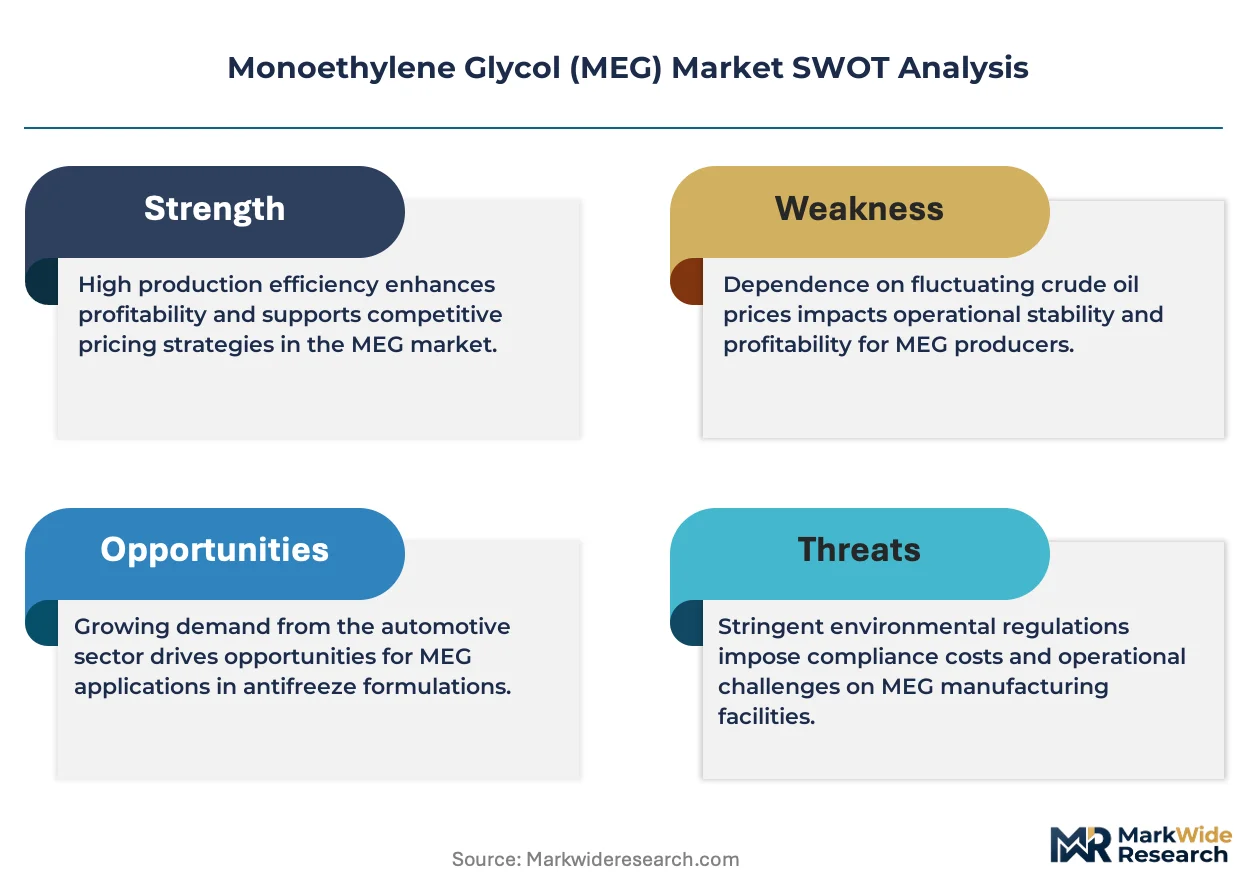
- Feedstock Price Volatility:The market's profitability is directly tied to the fluctuating price of ethylene and ethylene oxide, which are subject to geopolitical instability and oil price movements, creating cost uncertainty.
- Geographic Supply Concentration:An over-reliance on production from a few key provinces in China exposes the global supply chain to risks from localized logistical disruptions, policy changes, or trade disputes.
- Threat from rPET:Increasing collection and recycling of PET bottles, driven by regulation and consumer preference, reduces the demand for virgin MEG by creating a closed-loop supply of recycled PET (rPET).
Strategic Opportunities
- High-Purity Pharmaceutical Grades:Developing and qualifying MEG against stringent standards like the United States Pharmacopeia (USP) opens niche, high-margin opportunities in pharmaceutical excipients and medical device applications.
- Advanced Bio-MEG Processes:Innovating production routes using second-generation, non-food feedstocks like agricultural waste or cellulosic biomass can unlock new sustainable value chains and meet corporate ESG goals.
- Carbon Capture Integration:Retrofitting existing fossil-fuel-based MEG plants with carbon capture, utilization, and storage (CCUS) technology presents an opportunity to produce lower-carbon products that can be certified under frameworks like ISCC PLUS.
Industry Challenges
- Capital Intensive Projects:Constructing new, world-scale ethylene oxide and MEG production facilities, whether fossil-based or bio-based, requires immense capital investment and long project timelines, posing a significant barrier to entry.
- Regulatory Compliance Burden:Navigating the divergent and complex requirements of chemical control laws, such as the EU's REACH regulation and China's GB standards, demands significant technical and administrative resources.
- Supply Chain Traceability:Proving the origin and certified attributes of bio-based or recycled-content MEG requires robust, auditable chain-of-custody models, adding complexity and cost to logistics and distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monoethylene Glycol (MEG) Market |
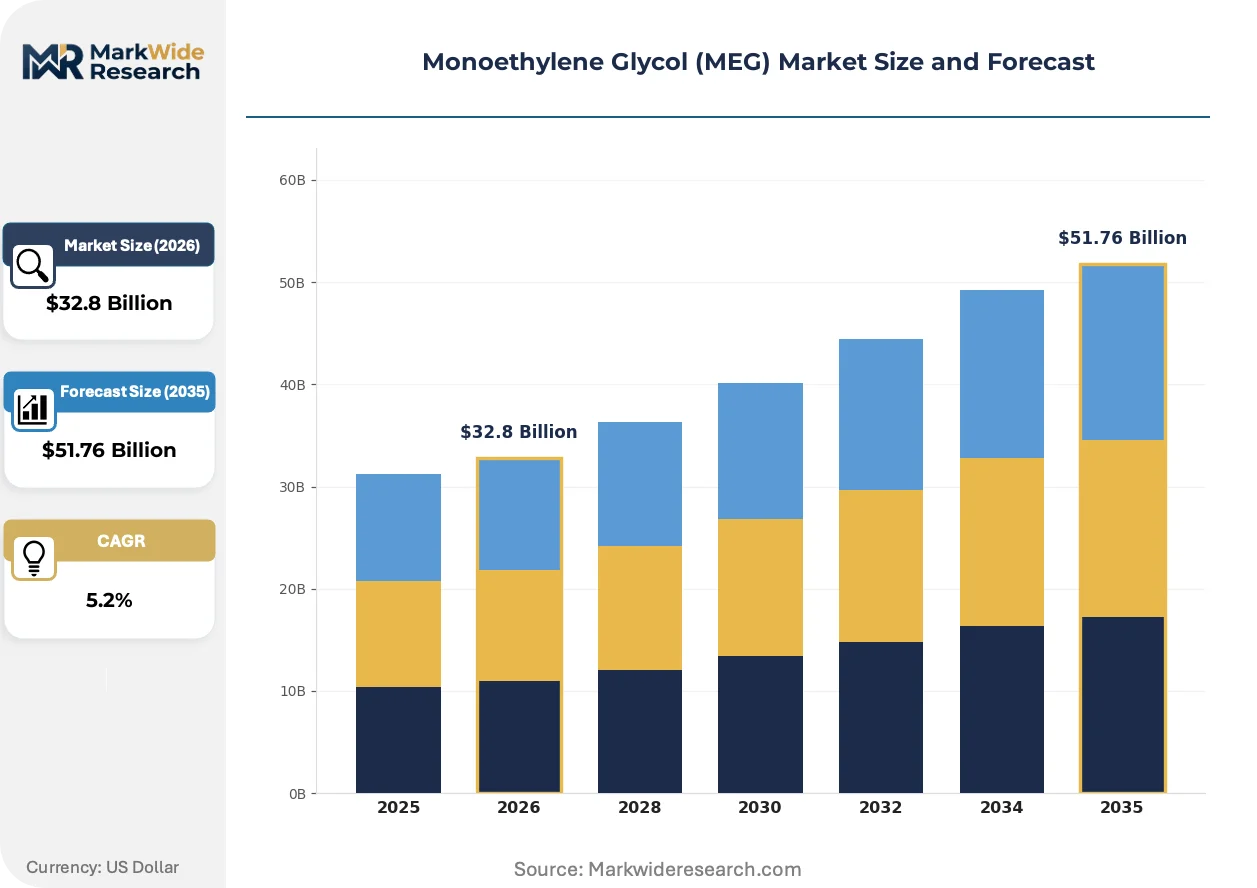
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $51.76 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Grade, Industrial Grade, Food Grade, Pharmaceutical Grade Application: Polyethylene Terephthalate, Antifreeze & Coolants, Humectants, Solvents End User Industry: Textile Manufacturing, Automotive Components, Personal Care, Chemical Processing Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Tankers |
| Companies Covered | SABIC, Lotte Chemical Corporation, BASF SE, Formosa Plastics Corporation, China Petroleum & Chemical Corporation, LyondellBasell Industries Holdings B.V., Shell plc, ExxonMobil Corporation, MEGlobal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monoethylene Glycol (MEG) Market Strategic Shifts & Innovations
The market is bifurcating between large-scale commodity operations and specialized production focused on sustainability and purity. This split is driven by a combination of technological advancements in bio-manufacturing and tightening environmental regulations that are forcing a re-evaluation of traditional supply chains.
Bio-based MEG, derived from renewable feedstocks like bio-ethanol, offers a chemically identical but lower-carbon alternative to its fossil-fuel counterpart. Consumer-facing brands in the packaging and textile sectors are increasingly specifying this material to meet their corporate sustainability targets. This adoption trend is supplanting conventional MEG in premium applications where a green credential commands a price premium and validates marketing claims.
China's national "dual carbon" policy framework is compelling significant operational changes for domestic chemical producers. The policy mandates greater energy efficiency and lower emissions, directly impacting the energy-intensive MEG production process. The polyester and antifreeze segments are most affected, as producers must now invest in plant upgrades to comply with stricter GB standards and national environmental targets to maintain market access.
A notable shift in purchasing behavior is emerging among large-volume buyers, who are now incorporating sustainability metrics into their procurement decisions. This disrupts the traditional price-first commodity model, replacing it with a more nuanced evaluation that includes life-cycle analysis and third-party certifications for bio-based or recycled content. This trend is most visible in the European food-contact PET and high-performance textile sectors.
Monoethylene Glycol (MEG) Market Segmentation
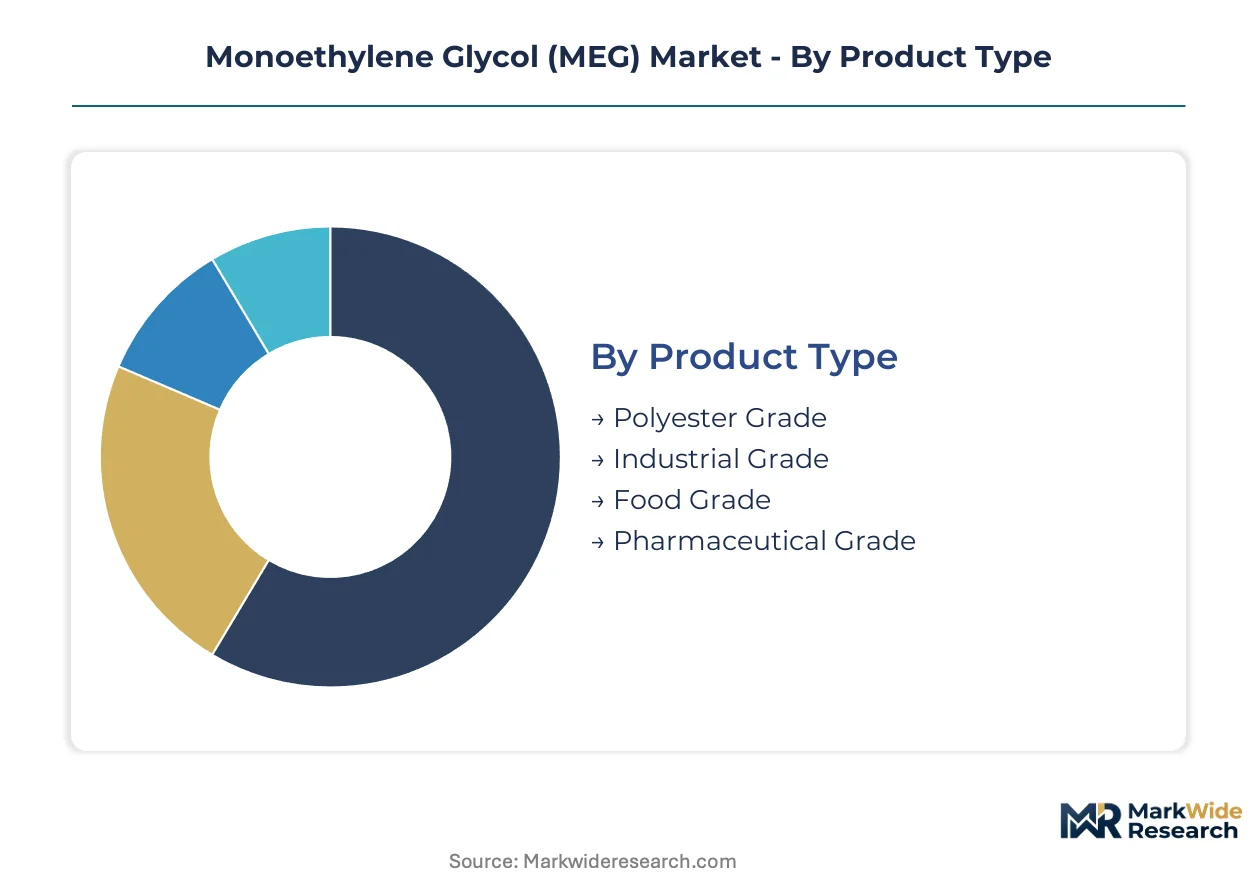
Understanding the Monoethylene Glycol market requires a granular view of its varied product forms and end-use pathways. Segmentation illuminates how different grades and applications cater to distinct industry requirements. This analysis reveals the specific demand drivers and regulatory influences shaping each market niche.
Product Type:
The distribution channels for Monoethylene Glycol vary significantly based on its purity and intended application, influencing how product types reach end-users.
- Polyester Grade:This grade serves as the primary monomer for polyethylene terephthalate (PET) synthesis, characterized by stringent purity specifications for polymerization. Demand from Asia's textile manufacturing hubs for polyester fiber remains the largest volume driver, supporting downstream industries.
- Pharmaceutical Grade:This highly purified MEG meets pharmacopeial standards like USP or EP, ensuring minimal impurities for sensitive applications. Niche opportunities in pharmaceutical excipients and medical device formulations are expanding, driven by strict regulatory compliance and patient safety requirements.
- Industrial Grade:This standard purity MEG finds widespread use in various industrial processes, including heat transfer fluids and chemical intermediates.
- Food Grade:This specialized MEG adheres to strict food contact regulations for applications such as food packaging and certain processing aids.
Polyester Grade dominates the installed base for MEG production. Pharmaceutical Grade is where expansion concentrates due to high-value applications.
Application:
MEG applications exhibit a range of cost sensitivities, from high-volume commodity uses to specialized functions demanding premium pricing.
- Polyethylene Terephthalate:MEG polymerizes with terephthalic acid to form PET, a versatile plastic used in fibers, films, and bottles. Sustained consumption for PET fiber production in textile manufacturing drives the largest volume, particularly in regions like China.
- Antifreeze & Coolants:MEG is a primary component in antifreeze formulations due to its low freezing point and high boiling point, protecting engines from extreme temperatures. This application provides a stable, mature demand stream, particularly in automotive and industrial sectors globally.
- Humectants:MEG functions as a hygroscopic agent, maintaining moisture in products like cosmetics and certain industrial formulations.
- Solvents:MEG's solvency properties make it useful in various chemical processes, including paints, coatings, and specialized cleaning agents.
PET applications command the overwhelming majority of MEG volume. The Humectants segment is expanding most quickly, driven by new product development.
End User Industry:
The volume requirements for MEG vary significantly across end-user industries, influencing procurement strategies and supply chain scale.
- Textile Manufacturing:This industry consumes MEG primarily for producing polyester fibers, a key component in apparel and home furnishings. Asia's manufacturing hubs drive substantial demand, linking directly to global consumer goods markets.
- Chemical Processing:MEG serves as a chemical intermediate in the production of various derivatives, including polyester resins, plasticizers, and solvents. This sector features diverse applications, ranging from construction materials to specialized industrial chemicals.
- Automotive Components:MEG is crucial for antifreeze and coolant formulations, protecting vehicle engines and other system components.
- Personal Care:This sector utilizes MEG as a humectant and solvent in cosmetics, lotions, and other personal hygiene products.
Textile manufacturing represents the largest end-user industry for MEG. The Personal Care sector exhibits significant growth potential for specialized MEG grades.
Packaging Type:
The choice of packaging type for MEG directly correlates with supply chain concentration and logistical efficiencies for different volume requirements.
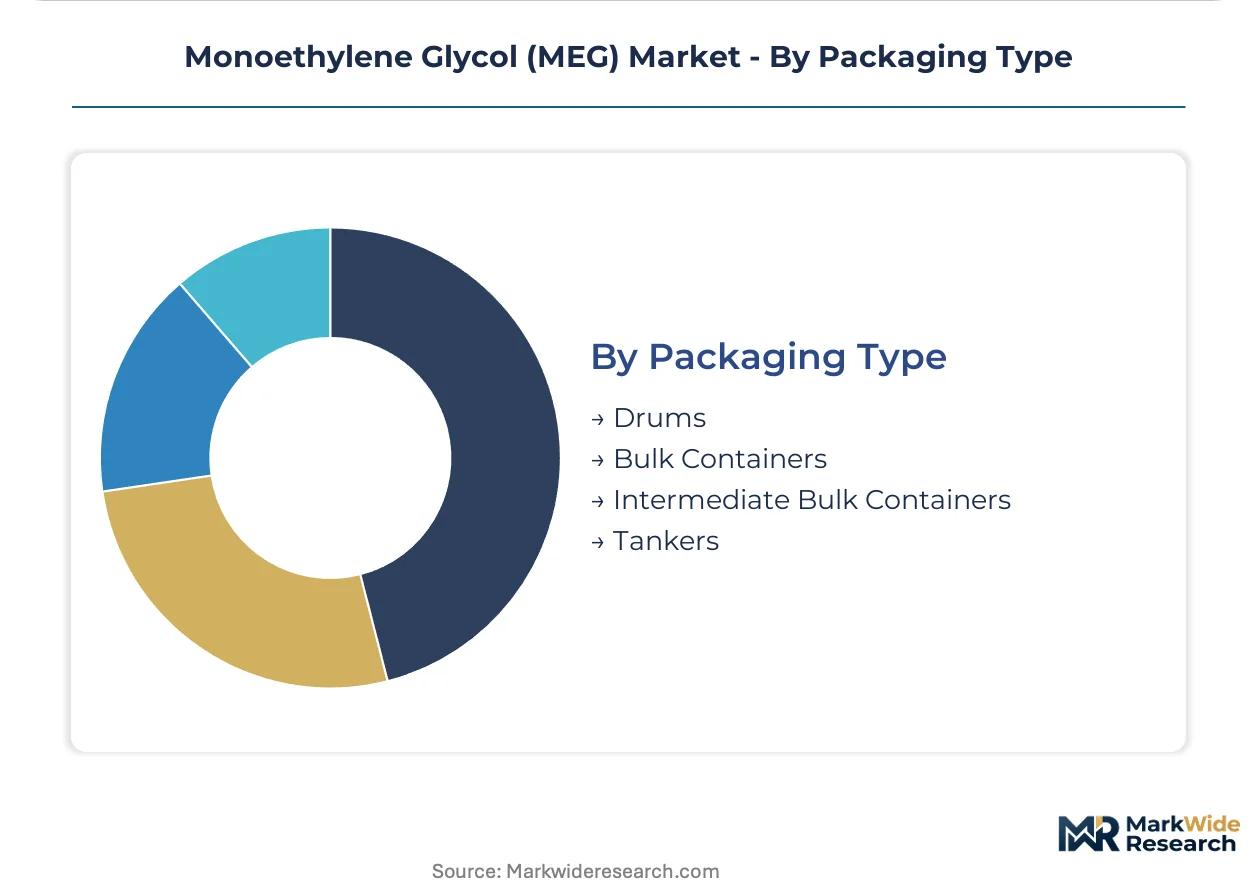
- Bulk Containers:These large-volume containers, such as ISO tanks or railcars, facilitate efficient transport of commodity-grade MEG for industrial customers. This packaging type is essential for large-scale chemical processing plants and regional distribution hubs.
- Tankers:Ocean-going tankers enable the intercontinental shipment of massive volumes of MEG, primarily from major production centers to distant consumption markets. This method underpins global trade flows and large-scale petrochemical supply.
- Drums:Standard 200-liter drums offer flexibility for smaller industrial users and specialty chemical distributors requiring manageable quantities.
- Intermediate Bulk Containers:IBCs provide a mid-range volume solution, balancing bulk efficiency with easier handling than full tankers for diverse industrial applications.
Bulk Containers are the most common packaging type for regional MEG distribution. Tankers are critical for international trade routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policies promoting circular economy principles in Europe and national "dual carbon" frameworks in China are reshaping regional Monoethylene Glycol markets. These directives prioritize sustainable production and consumption, influencing investment decisions and market access across key geographies. Regulatory mandates for chemical purity and environmental performance also drive localized demand for specific MEG grades.
China
Sustained consumption from the textile industry for polyester fiber production drives significant MEG demand in China. The national "dual carbon" policy framework compels domestic chemical producers to invest in plant upgrades for energy efficiency. Focused investments in new production facilities within Zhejiang and Jiangsu provinces create localized economies of scale for downstream industries.
United States
The United States Pharmacopeia (USP) standards for pharmaceutical-grade MEG create niche, high-margin opportunities for specialized producers. US EPA rules for industrial chemicals govern market access and product handling protocols for all MEG types. Chemical processing hubs along the Gulf Coast concentrate production and distribution for various industrial applications.
Germany
The European Union's REACH regulation imposes strict registration and evaluation requirements on MEG importers and manufacturers in Germany. Policies promoting bio-based feedstock viability accelerate research and investment into commercial-scale bio-MEG. The Rhine-Ruhr region, a major chemical cluster, sees significant activity in specialty chemical derivatives and sustainable MEG offerings.
India
Consumption from the textile industry for polyester fiber production remains a primary volume driver for MEG in India. National initiatives promoting domestic manufacturing and infrastructure development support demand for industrial-grade MEG. Industrial corridors like Gujarat and Maharashtra are expanding their petrochemical capacities to meet this growing requirement.
Saudi Arabia
Massive scale in petrochemical production influences commodity-grade MEG pricing and supply from Saudi Arabia. The Kingdom's diversification strategies support investments in downstream chemical industries. Jubail Industrial City, a major petrochemical hub, serves as a significant export base for bulk MEG to global markets.
Monoethylene Glycol (MEG) Market Key Industry Players
Player mix skews toward large-scale commodity producers alongside specialized chemical companies focused on high-purity and sustainable offerings. The market structure exhibits a clear bifurcation between those prioritizing volume and cost efficiency and those differentiating through product attributes. Strategic archetypes include integrated petrochemical giants, specialty chemical innovators, and regional commodity suppliers. Capacity expansion, particularly in Asia, and portfolio diversification into bio-based solutions are dominant competitive moves.
At the scale-driven end, SABIC exemplifies massive petrochemical production influencing global commodity pricing. China Petroleum & Chemical Corporation dominates supply within the crucial Chinese market, anchoring regional distribution. BASF SE occupies a position in specialty chemical derivatives and sustainable MEG offerings, differentiating its portfolio for premium applications.
| Leading Market Players |
|---|
| SABIC |
| Lotte Chemical Corporation |
| BASF SE |
| Formosa Plastics Corporation |
| China Petroleum & Chemical Corporation |
| LyondellBasell Industries Holdings B.V. |
| Shell plc |
| ExxonMobil Corporation |
| MEGlobal |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements, particularly for commodity-grade MEG, lock in both supply access and price visibility for large-volume buyers.
Pricing Analysis
Cost-plus contracts, often indexed to ethylene prices, establish a baseline for Monoethylene Glycol. Price differentiation stems from purity specifications, such as USP or EP certification for pharmaceutical grades, and volume scale for industrial buyers. Pricing pressure intensifies due to fluctuating ethylene and ethylene oxide feedstock costs. Buyers in the polyester grade segment exhibit the highest price sensitivity, while pharmaceutical and specialty chemical formulators are less sensitive to price fluctuations.
Supply Chain Analysis
China, with its massive MEG production capacity in Zhejiang and Jiangsu provinces, anchors global supply. The industry draws from key raw materials like ethylene and ethylene oxide, primarily sourced from large petrochemical complexes. Geographic concentration in China exposes the global supply chain to risks from localized logistical disruptions or policy changes. International distribution relies heavily on ocean-going tankers for bulk transport, complemented by bulk containers and IBCs for regional and specialty deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Monoethylene Glycol market requires a robust substitution defense as recycled PET (rPET) increasingly displaces virgin MEG demand.
For Market Incumbents: Shield market share by investing in advanced bio-MEG production processes and securing long-term feedstock contracts for conventional MEG. Consolidate capacity in strategic regions like China's Zhejiang province to leverage economies of scale and control costs against rPET competition. Prioritize certification investments for high-purity grades, such as USP, to access premium pharmaceutical and medical device markets.
For New Entrants and Emerging Players: Unmet demand for highly purified pharmaceutical-grade MEG presents a significant entry point for specialized players. Target the European premium packaging and textile sectors with certified bio-MEG offerings, leveraging stringent sustainability mandates. A go-to-market angle focused on robust supply chain traceability and ESG compliance can differentiate new players in these niche segments.
For Investors and Strategic Acquirers: The Monoethylene Glycol market sits at a bifurcating phase that favors agile specialty chemical innovators over pure commodity players. Focus on acquiring companies with proprietary bio-MEG technologies or established market positions in high-purity pharmaceutical grades. A signal to watch is the acceleration of regulatory mandates for carbon footprint disclosure, which will drive demand for sustainable MEG solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Supports growing polyester fiber production in Asian textile manufacturing hubs. |
| Green Manufacturing Transition | Meets corporate sustainability targets and aligns with tightening environmental regulations. |
| Long-term Supply Agreement | Secures stable feedstock supply for MEG producers amid price volatility. |
| Certification Investment | Unlocks high-margin opportunities in pharmaceutical and food-contact applications. |
| Joint Venture for Bio-MEG | Accelerates commercialization of renewable chemical production routes using novel feedstocks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews to capture nuanced market perspectives. This involved engagement with plant managers, procurement leads in textile and automotive sectors, R&D directors in specialty chemicals, and regulatory compliance officers. Secondary validation drew from customs data, ACC and Cefic reports, SEC 10-K filings, EU REACH documents, and China GB standards, triangulating bottom-up and top-down insights.
Across the analysis window, the forecast framework integrates granular segmentation across product type, application, end-user industry, and regional production capacity. Compound annual growth rates were derived from historical data analysis and projected market drivers, considering the influence of ethylene/ethylene oxide prices and sustained PET fiber demand from textile manufacturing as key inputs.
Underlying assumptions cover stable geopolitical conditions and predictable regulatory evolution, with deviation risk concentrated in ethylene price volatility or accelerated bio-MEG adoption. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Foundry Coke Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
Di-Isobutylene Market
Bulk Chemicals
Global Chlorinated Paraffin Wax Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market