
 Zinc Acetate Market | 2026-2036
Zinc Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Acetate Market Intelligence
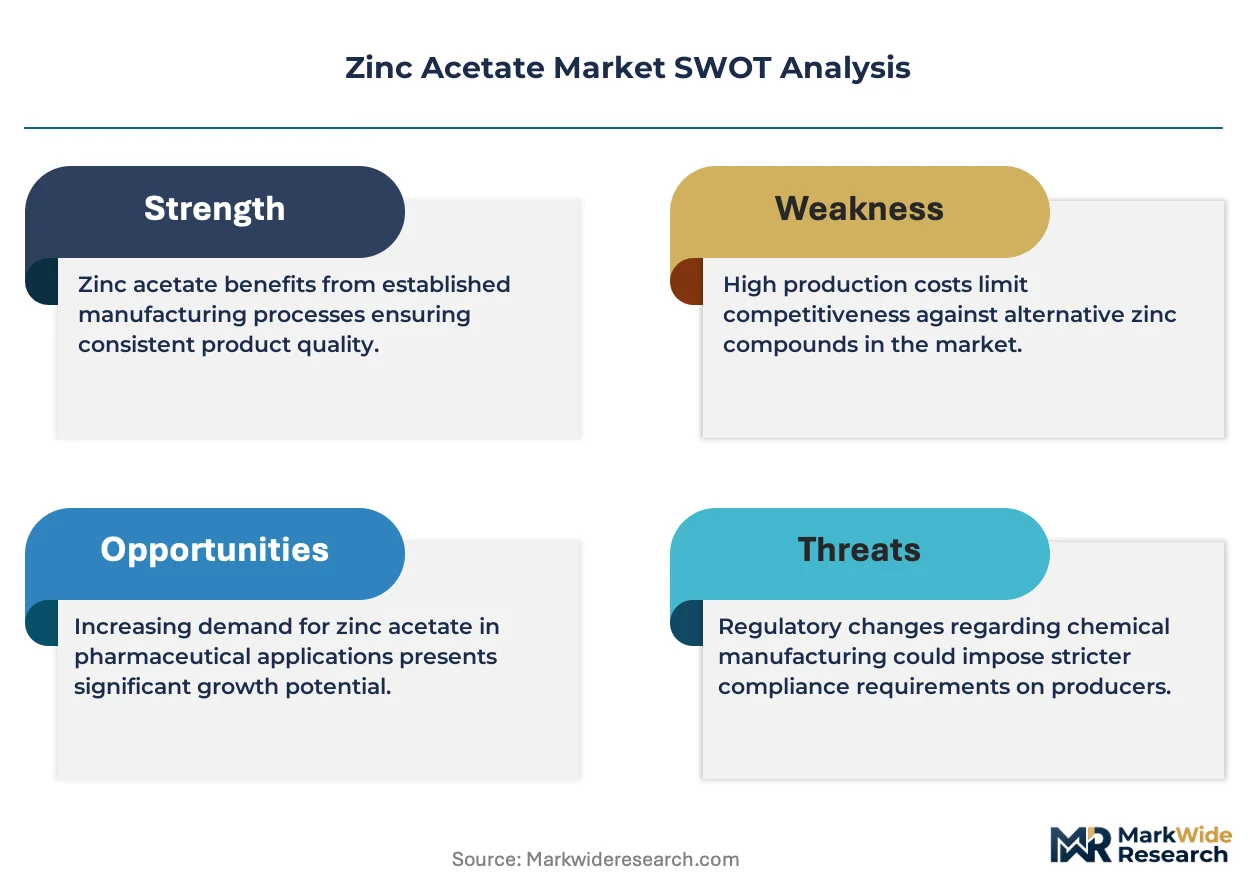
The increasing reliance on contract manufacturing agreements is reshaping competitive positioning for companies without large-scale production assets. This model allows newer entrants to focus on formulation and marketing. In contrast, established producers like Jost Chemical Co. leverage extensive in-house manufacturing to control quality and cost. Merck KGaA specializes in high-purity grades for pharmaceutical applications, while Fengchen Group Co. Ltd. anchors a significant portion of Asian supply.
Zinc acetate is a salt compound with the formula Zn(CH3COO)2, typically supplied as a white crystalline solid in its stable dihydrate form. Its primary function is to deliver zinc ions for therapeutic and nutritional purposes, including the management of Wilson's disease and common zinc deficiency. The zinc acetate dihydrate product type dominates the market due to its superior stability and solubility characteristics. Demand from the pharmaceuticals and dietary supplements applications constitutes the largest share, with pharmaceutical companies being principal end users for high-purity grades.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) dictate purity standards for pharmaceutical-grade material. In China, the NMPA enforces similar stringent quality controls for active pharmaceutical ingredients. Compliance with Good Manufacturing Practices (GMP) and pharmacopeia monographs is mandatory for market access in these key healthcare applications. Navigating the divergent requirements for food supplement versus pharmaceutical grades across geographies remains a central strategic consideration.
Market Dynamics
The market's central dynamic is the divergence between high-purity pharmaceutical grades and volume-driven dietary supplement grades. This split influences everything from manufacturing asset investment and GMP compliance costs to supply chain configuration and regulatory navigation across different economic blocs.
Growth Catalysts
- Nutritional Awareness:Global health initiatives from organizations like the WHO are increasing awareness of zinc deficiency, directly stimulating demand for zinc acetate in fortified foods and dietary supplements, particularly in developing nations.
- Pharmaceutical Applications:Established therapeutic uses, such as the management of Wilson's disease under frameworks established by the EMA and FDA, provide a stable, high-value demand segment for pharmaceutical-grade material.
- Chinese Supplement Market:China's expanding nutritional supplements industry, supported by government health policies and enforced by NMPA quality standards, creates a significant and growing consumption hub for zinc acetate.
Market Restraints
- Raw Material Volatility:Price fluctuations for high-purity acetic acid and zinc oxide, the primary feedstocks for synthesis, can compress margins for manufacturers who lack long-term supply contracts or backward integration.
- Substitution Risk:In the dietary supplement sector, zinc acetate competes with other organic zinc salts like zinc gluconate and citrate, which offer different bioavailability profiles and cost structures to formulators.
- Regulatory Complexity:The high cost and complexity of securing and maintaining separate GMP certifications for pharmaceutical versus food-grade production lines across the US, EU, and Asia create significant barriers to entry.
Strategic Opportunities
- Novel Formulations:Developing advanced delivery systems, such as chelated or enteric-coated zinc acetate, offers a pathway to differentiate products in the crowded premium supplement market by improving bioavailability and patient tolerance.
- Emerging Applications:Ongoing research into the antiviral properties of zinc ions presents an opportunity for zinc acetate in new therapeutic areas, including topical treatments and over-the-counter cold remedies.
- Geographic Expansion:Targeting markets in Southeast Asia and Latin America, where rising disposable incomes and growing health consciousness are creating new demand for nutritional supplements that is currently underserved by local production.
Industry Challenges
- Pharmacopeia Harmonization:Producers targeting global exports face the operational challenge of conforming to divergent purity and testing requirements specified in the US Pharmacopeia (USP), European Pharmacopoeia (EP), and others.
- Capital-Intensive Production:Establishing manufacturing facilities that comply with the stringent cGMP standards required for active pharmaceutical ingredient (API) production demands significant upfront capital investment and lengthy validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Acetate Market |
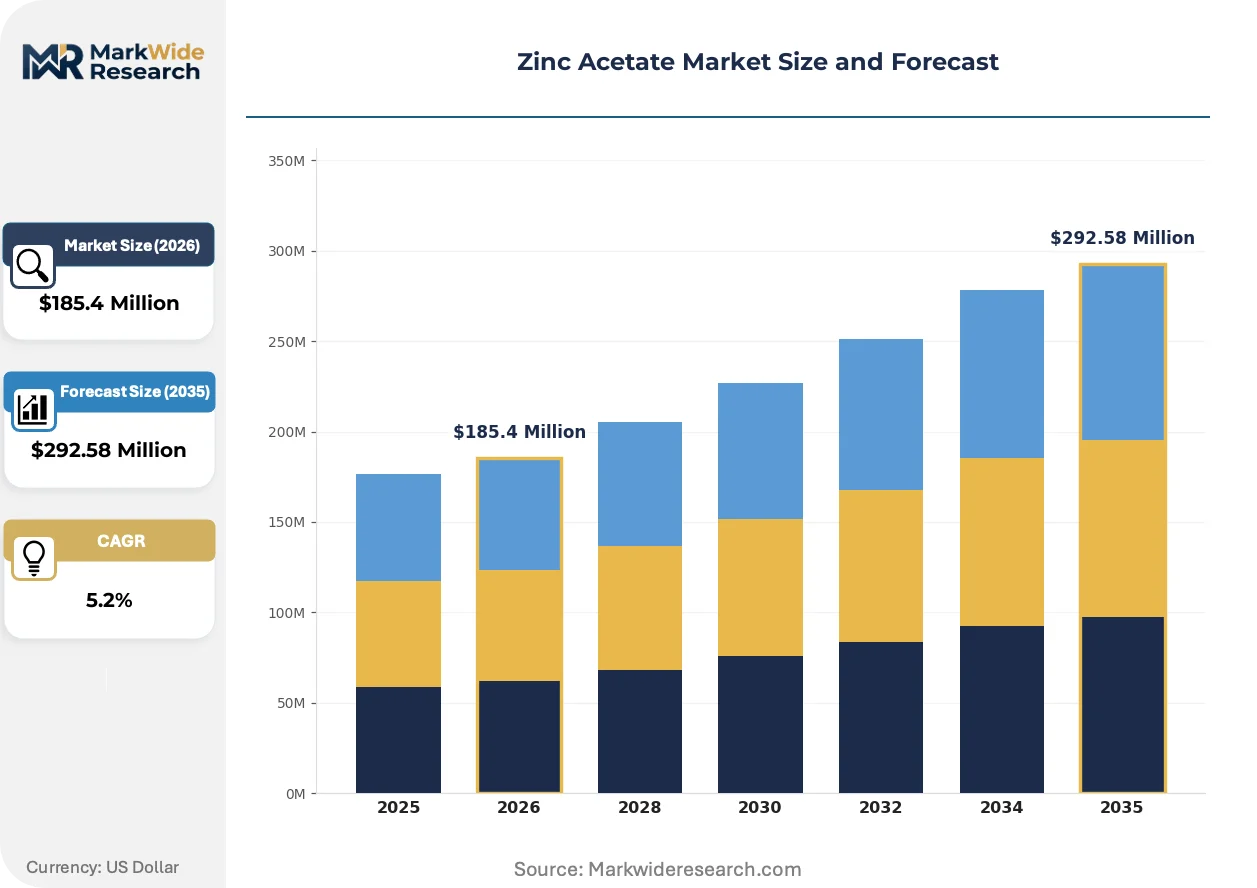
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $292.58 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc Acetate Dihydrate, Zinc Acetate Anhydrous, Zinc Acetate Oral Solution, Zinc Acetate Tablets Application: Dietary Supplements, Pharmaceuticals, Crop Protection, Animal Nutrition End User: Healthcare Providers, Pharmaceutical Companies, Agricultural Sector, Nutritional Supplements Industry Packaging Type: Bulk Bags, Bottles, Sachets, Drums |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Jost Chemical Co., TIB Chemicals AG, Fengchen Group Co. Ltd., GFS Chemicals Inc., Celtic Chemicals, Niacet Corporation, Zinc Nacional S.A. de C.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Acetate Market Strategic Shifts & Innovations
Technical and commercial specialization is segmenting the zinc acetate market. Producers are increasingly aligning their operations with either high-purity, regulation-intensive pharmaceutical applications or high-volume, cost-sensitive nutritional supplement segments, using distinct process technologies and go-to-market strategies.
Process analytical technology (PAT) is being integrated into crystallization and purification steps to ensure consistent quality. Pharmaceutical manufacturers are the primary adopters, using these tools for real-time monitoring of critical process parameters. This technology is virtualizing quality assurance, shifting the focus from lagging end-product testing to proactive, in-process control that reduces batch failures and accelerates material release.
European Medicines Agency (EMA) enforcement of ICH Q3D guidelines for elemental impurities is a major regulatory driver. The guideline mandates strict limits and risk assessments for metal contaminants in all active pharmaceutical ingredients sold in the EU. Consequently, producers of pharmaceutical-grade zinc acetate are investing in advanced analytical capabilities and tightening control over their raw material supply chains to ensure compliance.
A notable behavioral shift is the rise of specification-driven sourcing by contract development and manufacturing organizations (CDMOs). These large-scale operators are moving away from standard catalog products and demanding custom particle sizes, densities, and solubility profiles directly from manufacturers. This trend is most visible in the North American supplement market, where brand owners use CDMOs to achieve product differentiation.
Zinc Acetate Market Segmentation
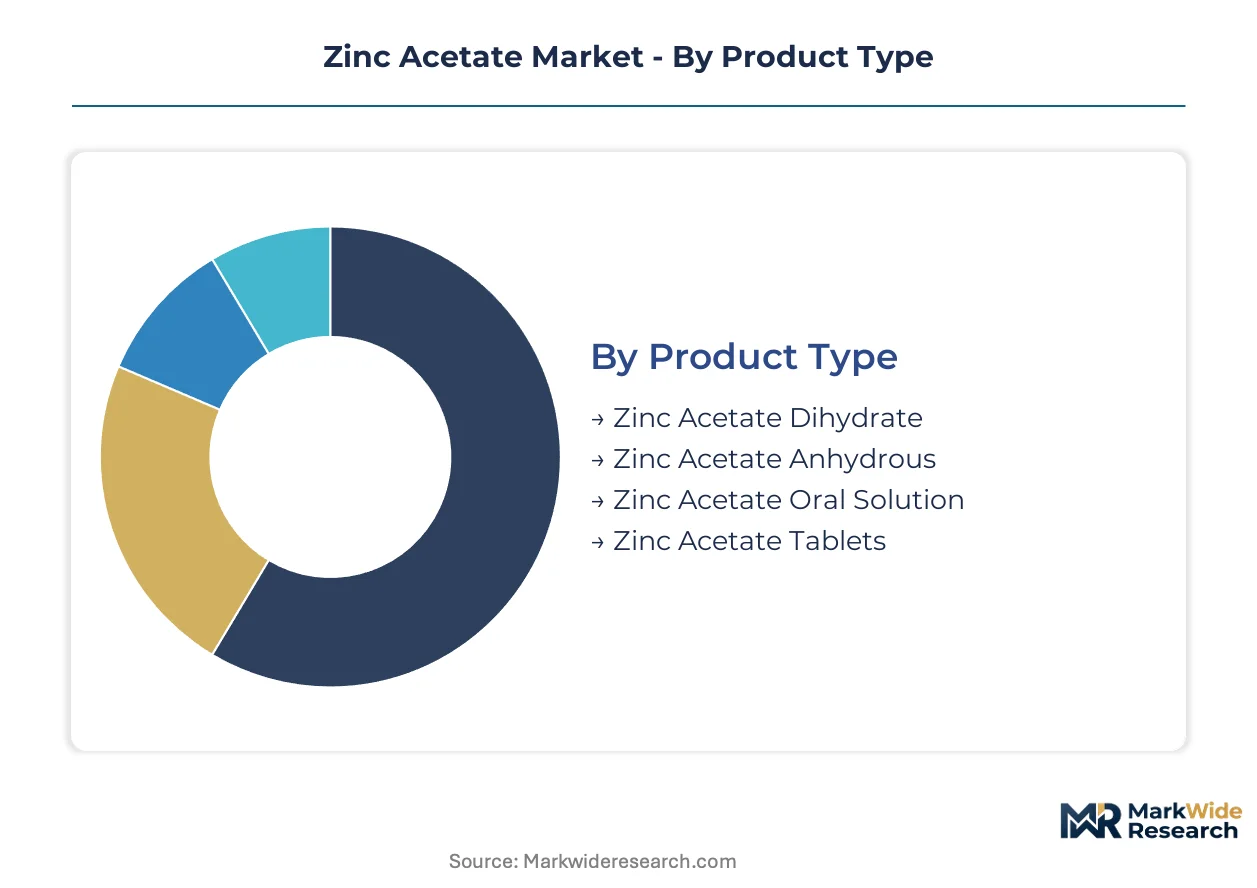
The Zinc Acetate market exhibits distinct segmentation, driven by varying purity requirements, end-user applications, and logistical considerations. Understanding these segments is crucial for manufacturers to align production capabilities with specific market demands, from high-value pharmaceutical grades to volume-driven nutritional supplements.
Product Type:
The product type segmentation highlights the different forms of zinc acetate available, each with unique stability and delivery characteristics, influencing their turnover rates in the supply chain.
- Zinc Acetate Dihydrate:This stable, white crystalline solid is the most prevalent form due to its superior solubility and handling properties. Demand is concentrated in pharmaceutical manufacturing and high-end dietary supplements, particularly in markets regulated by the US FDA and European Medicines Agency.
- Zinc Acetate Tablets:These pre-dosed, convenient solid dosage forms are designed for direct consumer use, offering ease of administration. Retail channels and over-the-counter supplement brands drive demand for this format, which sees faster inventory turnover due to consumer purchasing cycles.
- Zinc Acetate Anhydrous:This form lacks water molecules, making it suitable for specialized applications where moisture sensitivity is a concern.
- Zinc Acetate Oral Solution:A liquid formulation offering easier ingestion, often preferred for pediatric applications or patients with swallowing difficulties.
Zinc Acetate Dihydrate anchors the volume base while Zinc Acetate Tablets gain share at the steepest rate due to direct consumer accessibility.
Application:
Application segments delineate where zinc acetate is ultimately consumed, reflecting diverse purity standards and consumption volumes across industries.
- Dietary Supplements:Zinc acetate is a key ingredient in supplements addressing zinc deficiencies, driven by global nutritional awareness campaigns. Expanding markets like China's nutritional supplements industry contribute significantly to this volume-driven segment.
- Pharmaceuticals:This application involves high-purity zinc acetate for therapeutic uses, such as managing Wilson's disease, under strict regulatory frameworks from the EMA and US FDA. Pharmaceutical companies are principal end users for these specialized grades.
- Crop Protection:Zinc acetate serves as a micronutrient in agriculture, enhancing plant health and improving crop yields.
- Animal Nutrition:Used as an essential trace mineral additive in animal feed formulations to support livestock health and growth.
The largest consumption volume for zinc acetate resides in Dietary Supplements, while Pharmaceuticals represent the highest-value application due to stringent quality requirements.
End User:
End-user categories define the primary purchasers and processors of zinc acetate, illustrating varied procurement practices and regulatory compliance needs.
- Pharmaceutical Companies:These entities procure pharmaceutical-grade zinc acetate as an active pharmaceutical ingredient (API) for drug manufacturing. Compliance with Good Manufacturing Practices (GMP) and pharmacopeia monographs mandated by regulators like the NMPA is non-negotiable.
- Nutritional Supplements Industry:This sector utilizes zinc acetate in various formulations for health and wellness products, catering to a broad consumer base. Demand is particularly robust in developing nations where health consciousness is rising.
- Healthcare Providers:Medical professionals administer zinc acetate for specific therapeutic treatments, particularly for conditions like Wilson's disease.
- Agricultural Sector:Farmers and agricultural chemical manufacturers use zinc acetate for fortifying crops and animal feed.
Regulatory intensity significantly shapes procurement patterns for Pharmaceutical Companies, whereas the Nutritional Supplements Industry prioritizes formulation flexibility and cost-effectiveness.
Packaging Type:
Packaging types reflect the scale of distribution and end-use, influencing logistics, handling, and ultimately the unit cost of zinc acetate.
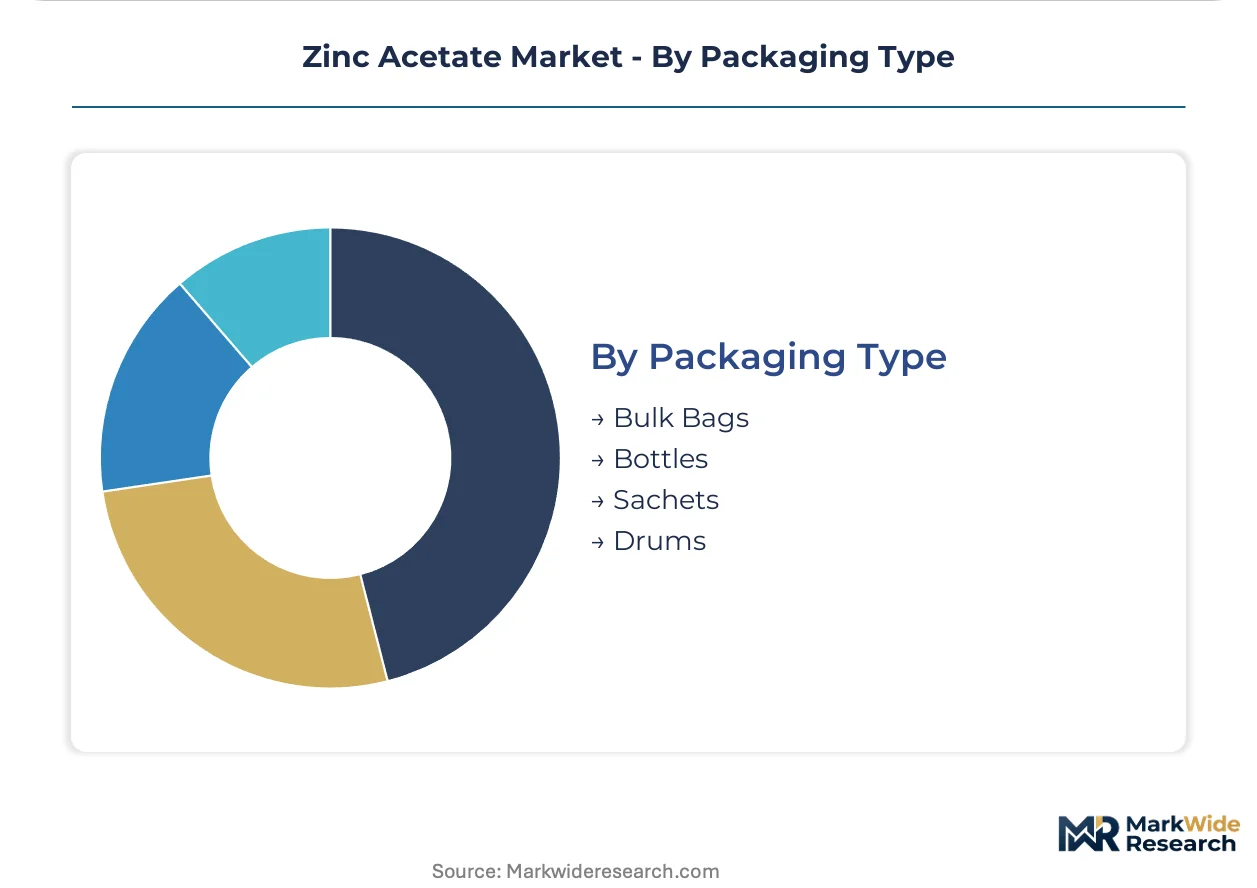
- Bulk Bags:These large-capacity containers are primarily used for industrial-scale shipments to manufacturers and large-volume processors. They offer cost efficiencies for high-volume procurement in sectors like agriculture and large supplement producers.
- Bottles:Typically used for consumer-ready products in the dietary supplement and over-the-counter medicine markets. This packaging type emphasizes convenience and shelf appeal for retail distribution.
- Drums:Intermediate-sized containers used for transporting and storing moderate quantities of zinc acetate for various industrial applications.
- Sachets:Small, single-serving packets often used for specialized or unit-dose nutritional supplements, targeting individual consumers.
High-volume industrial applications primarily rely on Bulk Bags, while Bottles solutions cater directly to consumer markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government health policies and incentives for nutritional well-being are driving regional demand for zinc acetate, particularly in areas with rising health consciousness. The market exhibits varied consumption patterns influenced by regulatory landscapes and the maturity of pharmaceutical and dietary supplement industries across different economic blocs.
United States
Demand for zinc acetate in the United States is spurred by a robust dietary supplements market and established pharmaceutical applications. The US FDA mandates stringent purity standards for pharmaceutical-grade materials, influencing production and supply chains. Significant research and development in novel formulations occur in biopharmaceutical clusters such as Boston and San Francisco.
China
China's expanding nutritional supplements industry creates a substantial consumption hub for zinc acetate. The NMPA enforces strict quality controls for active pharmaceutical ingredients, supporting high-purity material demand. Key manufacturing and distribution centers for health products are concentrated in the Yangtze River Delta region.
Germany
Germany's pharmaceutical sector drives a stable, high-value demand for pharmaceutical-grade zinc acetate, adhering to European Medicines Agency (EMA) guidelines. Strict elemental impurity limits under ICH Q3D further shape material specifications. Major chemical and pharmaceutical production facilities are located in regions like Hesse and North Rhine-Westphalia.
India
The Indian market for zinc acetate is experiencing growth due to increasing health awareness and a developing dietary supplements sector. The CDSCO regulates pharmaceutical products, ensuring compliance for therapeutic uses. Pharmaceutical manufacturing hubs in states such as Maharashtra and Gujarat are key consumers.
Brazil
Brazil's rising disposable incomes and growing health consciousness contribute to an expanding market for nutritional supplements containing zinc acetate. ANVISA oversees regulatory compliance for health products, impacting market access. The Southeast region, including São Paulo, serves as a primary center for pharmaceutical and supplement production.
Zinc Acetate Market Key Industry Players
Channel-controlling players compete with product-specialist players across the zinc acetate market, segmenting the competitive landscape. The market structure is tiered, with highly specialized manufacturers focusing on high-purity pharmaceutical grades and volume-driven producers serving the dietary supplement sector. Key strategic archetypes include integrated chemical suppliers, pharmaceutical ingredient specialists, and regional volume producers. Competitive moves often involve capacity expansion to meet volume demand or strategic partnerships for market access.
Pharmaceutical ingredient specialists like Merck KGaA exemplify the focus on high-purity grades for regulated applications. Jost Chemical Co. represents a North American manufacturer leveraging extensive in-house capabilities for quality and cost control. Fengchen Group Co. Ltd., a Chinese chemical company, anchors a significant portion of Asian supply, demonstrating scale-driven production for both pharmaceutical and nutritional segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Jost Chemical Co. |
| TIB Chemicals AG |
| Fengchen Group Co. Ltd. |
| GFS Chemicals Inc. |
| Celtic Chemicals |
| Niacet Corporation |
| Zinc Nacional S.A. de C.V. |
| Others |
Cost & Logistics Intelligence
Commodity volatility for key feedstocks determines both pricing tier spreads and supply chain shape across the zinc acetate market. Price fluctuations for acetic acid and zinc oxide directly impact manufacturing costs for both high-purity pharmaceutical grades and volume-driven dietary supplement materials. This dynamic influences investment in backward integration and supply contract strategies.
Pricing Analysis
Certification level (GMP, pharmacopeia) creates the primary spread in zinc acetate pricing. The market operates on a hybrid model, combining contract-based long-term offtake agreements for large pharmaceutical buyers with per-unit transactional pricing for smaller formulators. Price differentiation stems from quality grade, regulatory compliance, and volume scale. Cost compression in dietary supplement grades is intensifying due to competition from alternative zinc salts. The nutritional supplements industry exhibits the highest price sensitivity, while pharmaceutical companies prioritize purity and consistency over cost.
Supply Chain Analysis
Upstream feedstock availability significantly influences the zinc acetate supply chain. Geographic supply concentration for raw materials like high-purity acetic acid and zinc oxide centers in regions including China and the United States. The supply chain relies heavily on these primary inputs, creating a structural risk from raw material volatility. Distribution runs through direct sales to large pharmaceutical and supplement manufacturers, complemented by a network of chemical distributors serving smaller formulators and industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The zinc acetate market represents a high-growth opportunity, driven by increasing nutritional awareness and stringent NMPA quality standards in key regions.
For Market Incumbents: Entrench market position by investing in advanced purification technologies to meet evolving pharmacopeia standards. Pursue backward integration into key raw materials to mitigate margin pressure from feedstock volatility. Expand manufacturing capacity in high-demand regions like China to counter substitution risk from alternative zinc forms. Focus R&D on developing novel delivery systems for premium supplement applications.
For New Entrants and Emerging Players: Establish a beachhead in underserved geographic markets like Southeast Asia and Latin America, where rising disposable incomes drive demand. Target the premium supplement segment with differentiated offerings, such as chelated or enteric-coated zinc acetate, to improve bioavailability. Leverage contract manufacturing agreements to focus on formulation innovation and marketing without heavy capital investment in production assets.
For Investors and Strategic Acquirers: EMA enforcement of ICH Q3D guidelines for elemental impurities reshapes the acquisition landscape toward specialized producers. The market offers sustained demand for health applications over the next decade. Identify acquisition targets among manufacturers with robust GMP certifications and established supply chains for pharmaceutical-grade zinc acetate. The signal to watch is the increasing regulatory scrutiny on raw material purity across all major markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Addresses growing demand in China's nutritional supplements industry. |
| Advanced Purification Technology Investment | Ensures compliance with stringent US FDA and EMA pharmaceutical standards. |
| Long-term Supply Agreements for Raw Materials | Mitigates margin compression from acetic acid and zinc oxide volatility. |
| Novel Formulation R&D | Differentiates products in the premium dietary supplement market. |
| Geographic Market Entry in Southeast Asia | Capitalizes on rising health consciousness and underserved local production. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary validation anchors the qualitative findings. This involved discussions with pharmaceutical R&D directors, nutritional supplement formulators, procurement managers, and regulatory affairs specialists. Secondary data sources included US FDA filings, EMA guidance documents, NMPA regulations, and relevant trade association reports, triangulated through both bottom-up and top-down approaches.
The calibration approach integrated quantitative models with qualitative insights to project market dynamics across the analysis window. Segmentation dimensions modeled included product type, application, end user, packaging type, and regional regulatory framework. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected growth drivers. Key forecast inputs included raw material price forecasts and demographic shifts impacting global health awareness.
Macroeconomic conditions sit as an overlay; deviation in global economic growth or healthcare spending would shift the trajectory. Forecasts reflect assumptions documented regarding regulatory stability and technological advancements. Cross-checking against World Health Organization (WHO) health reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
North America Potassium Permanganate Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
Global Sodium Lactate Market