
 Global GABA Market | 2026-2036
Global GABA Market Size, Share, and Industry Trends Forecast 2026-2036
Global GABA Market Foresight
Modular dosing formats are restructuring how supplement brands configure GABA offerings for end consumers. Shanghai Richen leverages its synthetic production base to compete on cost-sensitive powder contracts. Kyowa Hakko dominates pharma-grade fermentation-derived supply through decades of Japanese regulatory alignment. Pharma Foods International differentiates via functional food & beverage integration partnerships across Asia-Pacific markets.
Gamma-aminobutyric acid (GABA) is a non-proteinogenic amino acid neurotransmitter, typically supplied at 98-99% purity for pharmaceutical applications and 20-80% concentration for food-grade formulations, manufactured through L-glutamic acid decarboxylation via microbial fermentation or chemical synthesis. Its primary commercial purpose centers on anxiolytic and sleep-support claims in dietary supplements, plus blood-pressure modulation in functional foods. Powder formulations lead volume due to bulk manufacturing flexibility, while fermentation-derived GABA captures premium positioning as clean-label demand intensifies among beverage producers. Sports nutrition brands represent the fastest-growing end-user channel, though pharmaceutical companies still anchor margin pools through clinical-grade specifications.
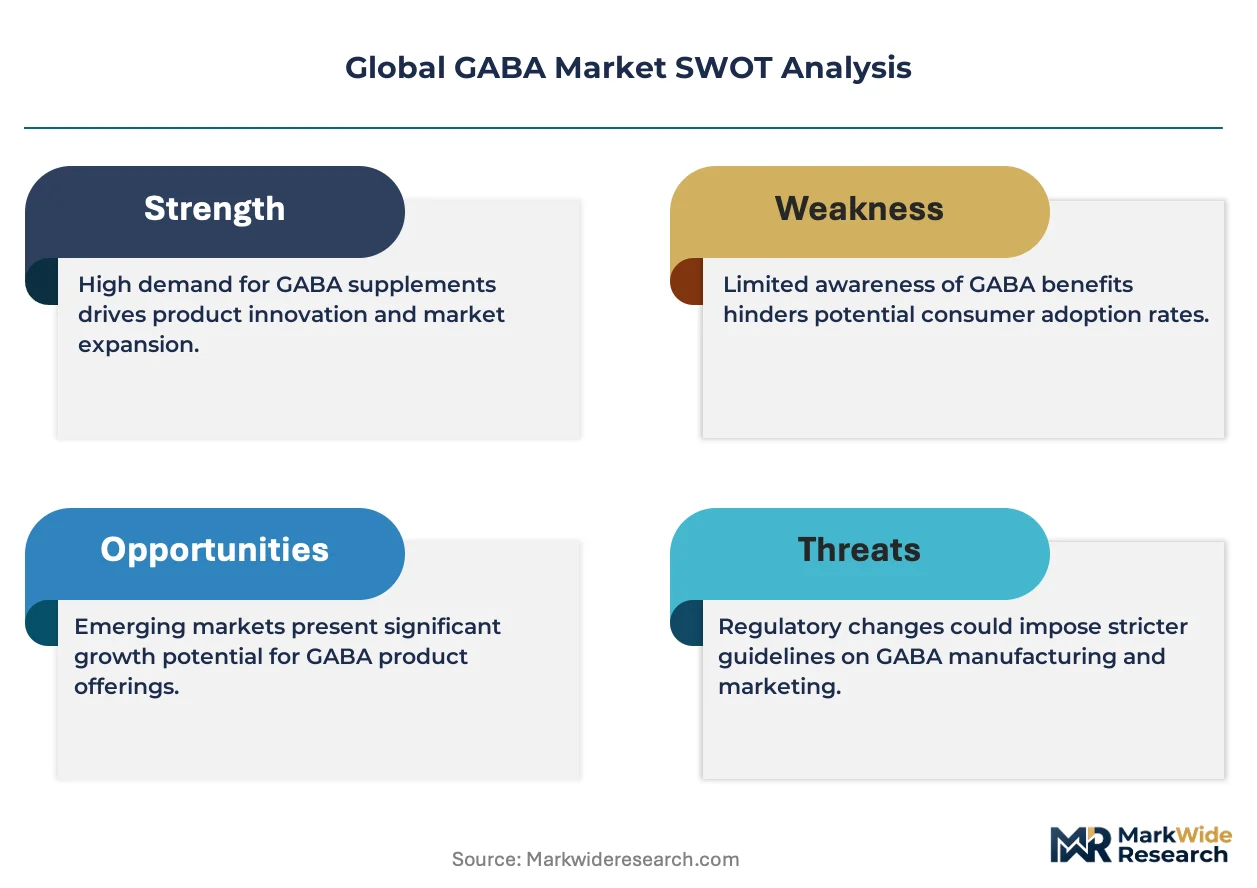
FDA dietary supplement regulations under DSHEA shape GABA labeling and structure-function claim boundaries in the United States, while Japan's Ministry of Health, Labour and Welfare maintains distinct FOSHU approval pathways for blood-pressure reduction claims. EFSA's ongoing evaluation of GABA health claims in Europe creates uncertainty for supplement manufacturers seeking cross-border market access. Stakeholders must monitor regulatory divergence between fermentation-derived and synthetic sourcing classifications, as this distinction increasingly determines channel eligibility and pricing power across major consumer markets.
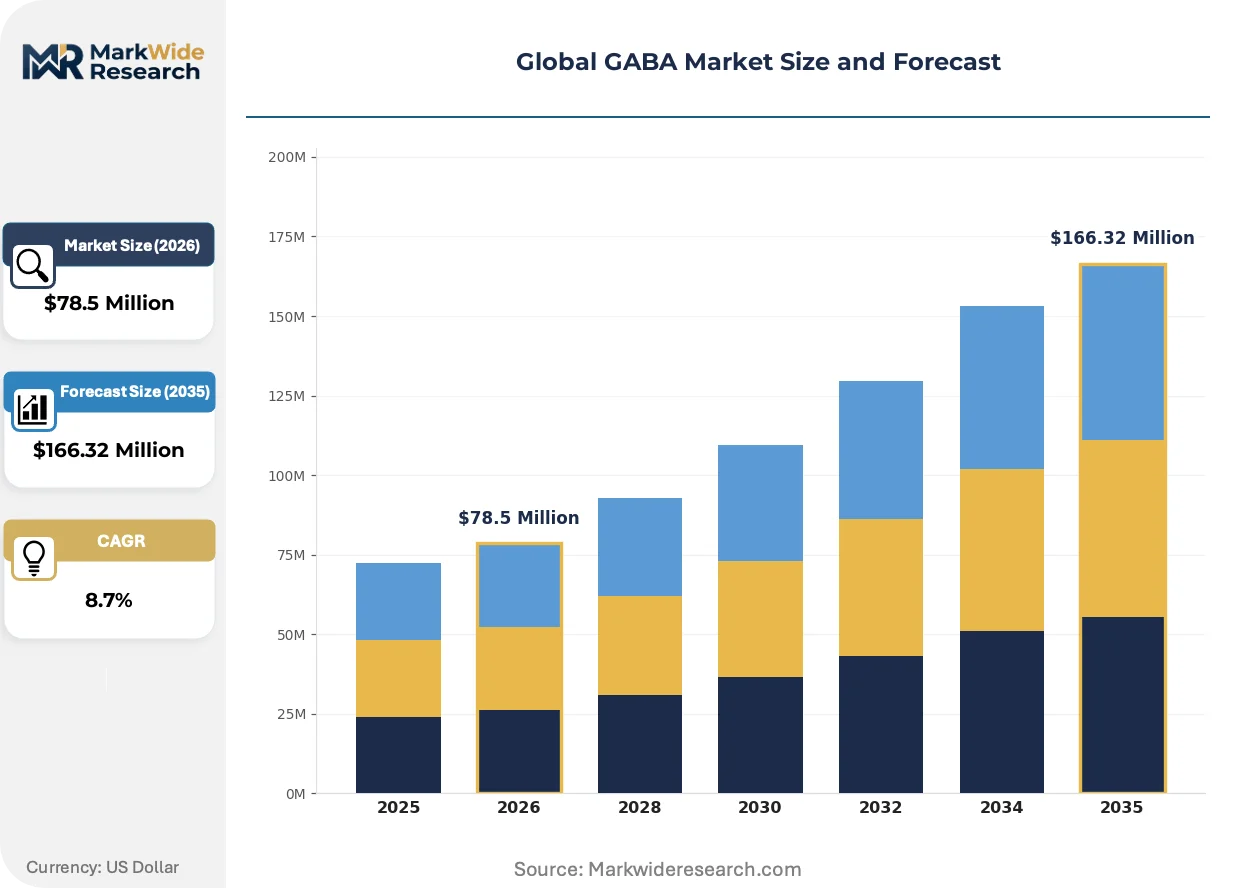
Market Dynamics
Fermentation-derived production methods are displacing synthetic chemical routes across GABA supply chains, driven by clean-label certification requirements from beverage and supplement brands seeking FDA dietary supplement compliance and Japan FOSHU eligibility.
Growth Catalysts
- DSHEA Structure-Function Claims:FDA dietary supplement guidelines permit anxiolytic and sleep-support labeling without pharmaceutical approval, expanding formulation flexibility for US brands.
- Clean-Label Fermentation:Microbial fermentation using L-glutamic acid decarboxylase satisfies consumer preference for naturally derived ingredients in functional beverages.
- Sports Nutrition Channel:Pre-workout and recovery supplement brands are incorporating GABA for purported growth hormone modulation effects.
Market Restraints
- L-Glutamic Acid Feedstock Volatility:Corn-derived glucose prices fluctuate with agricultural commodity cycles, compressing fermentation margins.
- Japanese Supply Concentration:Pharma-grade fermentation capacity clusters with heritage suppliers, creating procurement bottlenecks for new market entrants.
- EFSA Health Claim Uncertainty:Pending European Food Safety Authority evaluations block blood-pressure reduction marketing in EU member states.
Strategic Opportunities
- India Functional Food Penetration:FSSAI regulatory pathways for novel food ingredients remain underdeveloped relative to supplement frameworks.
- Precision Fermentation Convergence:Synthetic biology tools combined with traditional microbial strains enable titers exceeding conventional batch processes.
- Direct-to-Consumer Subscription:Sleep-focused wellness platforms bypass retail markup structures for powdered GABA formulations.
Industry Challenges
- Pharma-Grade Certification Timelines:Current Good Manufacturing Practice validation for active pharmaceutical ingredient status requires 18-24 month qualification periods.
- Cross-Border Labeling Fragmentation:Divergent structure-function claim permissibility between FDA, EFSA, and Japan's Ministry of Health, Labour and Welfare forces SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global GABA Market |
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $166.32 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tablets, Liquid Concentrate, Effervescent Tablets Application: Dietary Supplements, Functional Food & Beverages, Pharmaceuticals, Sports Nutrition, Animal Feed End User: Supplement Manufacturers, Pharmaceutical Companies, Beverage Producers, Animal Nutrition Firms, Sports Nutrition Brands Formulation Type: Natural Extracts, Synthetic, Fermentation-derived, Enzymatic Synthesis, Bioengineered |
| Companies Covered | Shanghai Richen, Zhejiang Tianrui Chemical, Pharma Foods International, Tianjin Shijitianlong Biotech, Taizhou Xinyou Pharmaceutical & Chemical, Kyowa Hakko, Guangdong Luckerkong Biotech, Ningxiang Jiayuan Biology Technology, Zhejiang Yiwan Biolabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global GABA Market Shifts & Advancements
Bioprocess intensification and regulatory geography fragmentation are reshaping competitive positioning in GABA manufacturing, with production technology choices now predetermining market access eligibility rather than merely cost structure.
Continuous fermentation systems with real-time metabolite monitoring are electrifying productivity benchmarks for pharmaceutical-grade GABA output. Contract manufacturers serving Japanese functional food brands have adopted these systems to maintain Kyowa Hakko-competitive purity specifications. The technology is compressing batch-to-batch variability to sub-2% coefficient of variation, enabling just-in-time supply contracts previously impossible with traditional fed-batch methods.
Japan's Ministry of Health, Labour and Welfare revised FOSHU notification procedures in 2023, streamlining blood-pressure reduction claim approvals for fermented GABA ingredients. The policy shift accelerates time-to-market for domestic suppliers while maintaining synthetic-source exclusion criteria. European manufacturers lacking fermentation-derived supply chains face effective market exclusion from Japan's functional food channel.
Direct-to-consumer sleep supplement brands are consolidating procurement around single-source fermentation suppliers with transparent strain documentation. Amazon-native wellness companies now require batch-level certificates of analysis as standard contract terms, displacing traditional distributor-mediated purchasing. This pattern concentrates most visibly in the United States, where DSHEA-compliant structure-function claims permit marketing flexibility unavailable in regulated pharmaceutical channels.
Global GABA Market Segmentation
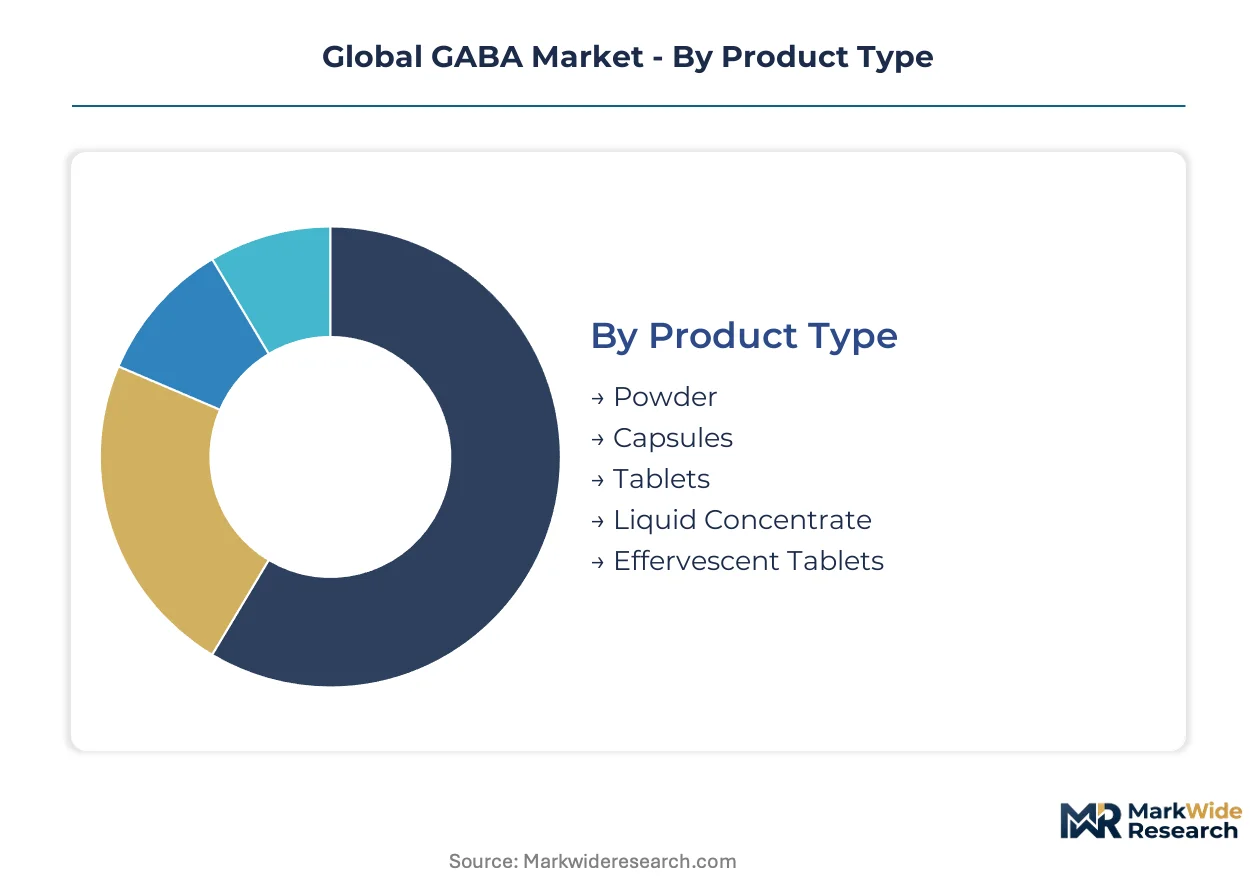
Segment boundaries in GABA commerce trace regulatory approval pathways more than chemical properties. Certification requirements for FOSHU eligibility, FDA structure-function claims, and EFSA health claim evaluations create divergent margin structures across otherwise similar product configurations.
Product Type:
Powder formats carry minimal certification overhead for bulk ingredient trade, while finished dosage forms trigger layered compliance obligations across FDA, Japan's Ministry of Health, Labour and Welfare, and EFSA jurisdictions.
- Powder:Bulk material supplied at 98-99% purity for pharmaceutical compounding or 20-80% concentration for food-grade blending. Demand clusters with US contract manufacturers seeking DSHEA-compliant formulation flexibility for sleep and stress supplement lines.
- Capsules:Pre-measured unit doses with gelatin or vegetable shells requiring stability testing and dissolution profile documentation. Sports nutrition brands in the United States favor this format for pre-workout stack integration, driving procurement from fermentation-certified suppliers.
- Tablets:Compressed dosage forms with excipient matrices demanding hardness and friability validation. Direct-to-consumer wellness platforms specify tablet formats for subscription sleep products.
- Liquid Concentrate:Aqueous solutions for beverage fortification requiring microbial stability and taste masking. Functional drink producers in Japan specify this format for FOSHU blood-pressure claim eligibility.
- Effervescent Tablets:Rapid-dissolution formats with carbonate-acid reaction systems. European supplement brands pursue this configuration pending EFSA claim clarity.
Leading the category by volume: Powder. Growing fastest: Capsules.
Application:
End-use destination determines which regulatory gatekeeper—FDA, EFSA, or Japan's Ministry of Health, Labour and Welfare—controls market access and permissible claim language.
- Dietary Supplements:DSHEA-governed products with structure-function claims for anxiolytic and sleep support. US brands dominate procurement, with Amazon-native companies requiring batch-level certificates of analysis.
- Functional Food & Beverages:Japan FOSHU pathway products with blood-pressure reduction claims. Fermentation-derived sourcing is mandatory; synthetic routes face categorical exclusion.
- Pharmaceuticals:Active pharmaceutical ingredient status requiring current Good Manufacturing Practice validation and 18-24 month qualification timelines. Kyowa Hakko anchors supply through decades of Japanese regulatory alignment.
- Sports Nutrition:Pre-workout and recovery formulations with growth hormone modulation positioning. This segment climbs fastest as fitness brands expand ingredient portfolios beyond caffeine and creatine.
- Animal Feed:Pet calming products and livestock stress management applications. Regulatory pathways remain underdeveloped relative to human supplement frameworks.
Volume leader: Dietary Supplements. Steepest expansion trajectory: Sports Nutrition.
End User:
Customer type shapes procurement sophistication, from commodity powder tenders to strain-documentation requirements for direct-to-consumer brands.
- Supplement Manufacturers:Contract formulators serving multiple brand clients with private-label production. These buyers prioritize fermentation-derived supply for clean-label positioning.
- Pharmaceutical Companies:Clinical-grade specification holders with extended vendor qualification protocols. Japanese heritage suppliers capture this tier through pharma-grade fermentation capacity.
- Beverage Producers:Functional drink brands requiring taste-neutral, water-soluble GABA with FOSHU eligibility. Japan's regulatory alignment favors domestic fermentation supply.
- Animal Nutrition Firms:Pet supplement and livestock feed compounders with less stringent purity requirements than human applications.
- Sports Nutrition Brands:Pre-workout and recovery product specialists with fastest-growing demand profiles. These buyers favor single-source fermentation suppliers with transparent strain documentation.
Category dominance by procurement volume: Supplement Manufacturers. Gaining share fastest: Sports Nutrition Brands.
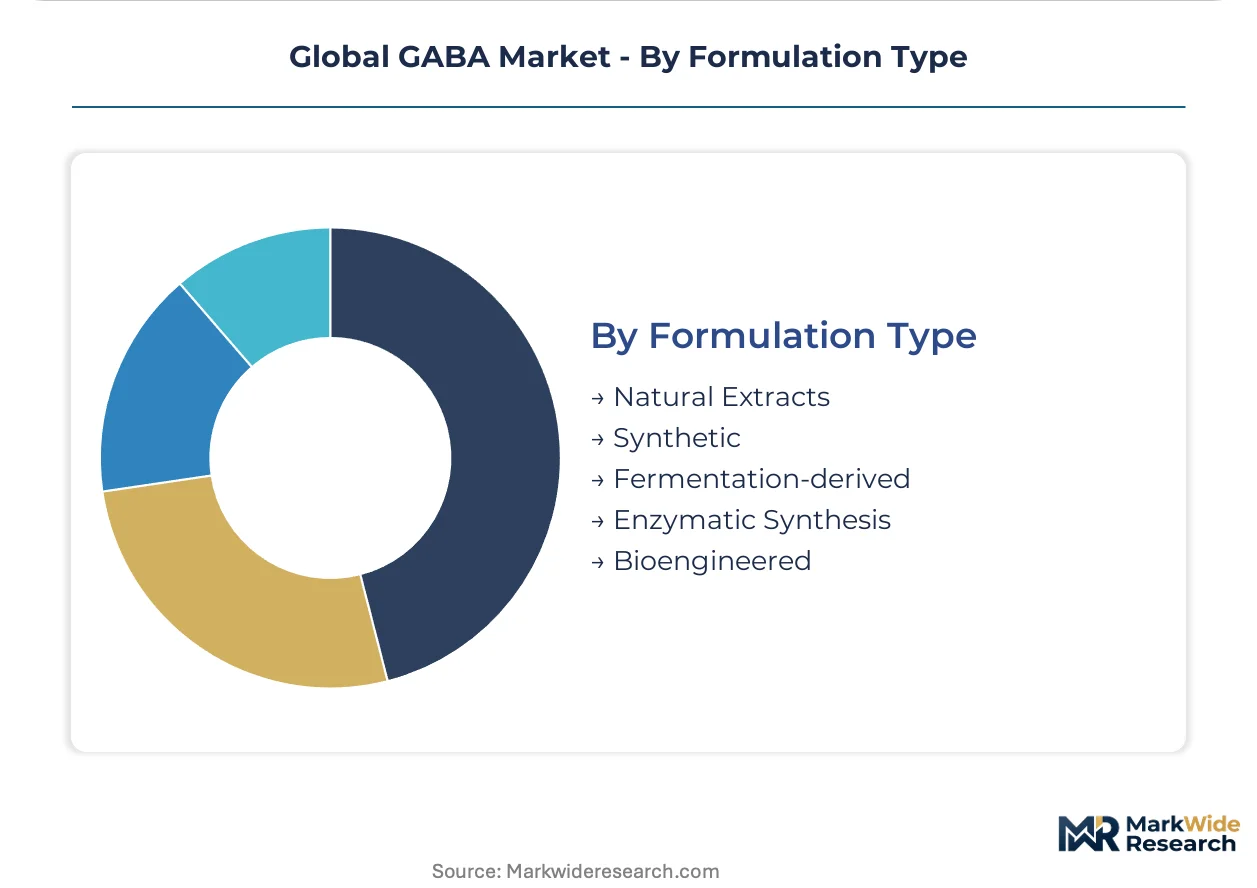
Formulation Type:
Production technology choice now predetermines channel eligibility rather than merely cost structure, with fermentation routes commanding premium positioning.
- Fermentation-derived:Microbial conversion of L-glutamic acid via decarboxylase enzymes, satisfying clean-label demand and FOSHU requirements. Shanghai Richen and Kyowa Hakko compete across cost-sensitive and premium tiers respectively.
- Synthetic:Chemical synthesis routes facing displacement as beverage and supplement brands reject non-natural sourcing. Remains viable for industrial and animal feed applications with less stringent label requirements.
- Natural Extracts:Isolation from germinated rice and other botanical sources with limited commercial scale. Niche positioning for ultra-premium wellness brands.
- Enzymatic Synthesis:Cell-free biocatalytic approaches with emerging productivity benchmarks. Precision fermentation convergence may reshape this category.
- Bioengineered:Synthetic biology-enhanced strains with titers exceeding conventional batch processes. Early-stage adoption among contract manufacturers seeking Kyowa Hakko-competitive purity.
Volume concentration: Fermentation-derived. Expanding most quickly: Bioengineered.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province's chemical industrial parks and Japan's Kanto pharmaceutical corridor concentrate GABA fermentation capacity through targeted tax incentives and bonded zone status for biotech exports.
United States
DSHEA-compliant supplement brands drive powder and capsule procurement from contract manufacturers clustered in Utah and California. FDA structure-function claim flexibility permits sleep-support marketing without pharmaceutical pathways. Greater Los Angeles hosts direct-to-consumer wellness platforms requiring batch-level certificates of analysis.
Japan
FOSHU blood-pressure reduction claims anchor functional food demand for liquid concentrate formats. Ministry of Health, Labour and Welfare maintains synthetic-source exclusion criteria for fermented ingredient eligibility. Kyowa Hakko's Kanto region fermentation facilities supply pharma-grade specifications to domestic beverage producers.
China
Cost-sensitive powder contracts concentrate with synthetic producers in Zhejiang and Jiangsu chemical parks. NMPA novel food ingredient pathways lag supplement frameworks, constraining functional beverage penetration. Shanghai contract manufacturers serve export markets seeking fermentation-derived clean-label positioning.
Germany
EFSA health claim uncertainty blocks blood-pressure reduction marketing, forcing supplement brands toward generic anxiolytic positioning. EMA pharmaceutical-grade pathways attract clinical-grade GABA imports for compounding pharmacies. Bavaria's nutraceutical clusters specialize in effervescent tablet formats pending regulatory clarity.
India
FSSAI novel food approval timelines lag dietary supplement frameworks, limiting functional food channel development. CDSCO pharmaceutical pathways attract fermentation-derived imports for clinical trials. Maharashtra contract manufacturers blend imported powder for private-label sleep supplement exports.
Global GABA Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fermentation and synthetic production routes. Market structure tilts toward supply-side concentration at the pharma-grade tier and fragmentation in commodity powder segments. Three archetypes dominate: Japanese heritage fermentation houses, Chinese synthetic chemical producers, and Asia-Pacific functional food integrators. Capacity expansion and clean-label certification partnerships constitute the dominant competitive moves.
Among Japanese heritage suppliers, Kyowa Hakko occupies a position exemplifying pharma-grade fermentation alignment with FOSHU regulatory pathways. Shanghai Richen and Zhejiang Tianrui Chemical represent the cost-driven synthetic tier serving powder contract markets. Pharma Foods International anchors the functional food integration archetype across Asia-Pacific beverage partnerships.
| Leading Market Players |
|---|
| Shanghai Richen |
| Zhejiang Tianrui Chemical |
| Pharma Foods International |
| Tianjin Shijitianlong Biotech |
| Taizhou Xinyou Pharmaceutical & Chemical |
| Kyowa Hakko |
| Guangdong Luckerkong Biotech |
| Ningxiang Jiayuan Biology Technology |
| Zhejiang Yiwan Biolabs |
| Others |
Supply & Pricing Matrix
L-glutamic acid feedstock costs cascade through GABA manufacturing tiers, with corn-derived glucose volatility compressing fermentation margins for mid-tier suppliers while pharma-grade producers in Japan defend premium positioning through FOSHU-aligned certification premiums.
Pricing Analysis
Margin tightening in standard-grade powder reflects synthetic route displacement as beverage brands reject non-fermentation sourcing. Three-tier pricing structure across pharma-grade, food-grade, and feed-grade levels separates Kyowa Hakko's FOSHU-certified premiums from Zhejiang chemical park commodity contracts. Cost-down pressure on synthetic producers accelerates because clean-label procurement policies now mandate strain documentation. Sports nutrition brands show least price sensitivity, prioritizing single-source fermentation suppliers with transparent batch records over lowest-bid powder tenders.
Supply Chain Analysis
Direct-to-manufacturer channels handle bulk pharmaceutical and functional food procurement, bypassing distributor markups for fermentation-derived supply. Production gravity centers on Japan's Kanto corridor for pharma-grade output and China's Zhejiang chemical parks for synthetic powder. Corn-derived glucose, specialized microbial strains, and gelatin capsule shells constitute critical input dependencies. Single-source vulnerability concentrates with heritage Japanese fermentation houses controlling FOSHU-eligible supply. Distribution runs through bonded biotech export zones for Asia-Pacific functional beverage integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into L-glutamic acid production and captive fermentation capacity represents the dominant vertical-integration race, with procurement security now outweighing pure manufacturing cost optimization.
For Market Incumbents: Anticipate synthetic route obsolescence by locking multi-year corn glucose supply contracts and accelerating precision fermentation R&D to match Kyowa Hakko purity benchmarks. Defend position by securing FOSHU pre-notification approvals ahead of Japan's Ministry of Health, Labour and Welfare regulatory revisions. Channel control through direct-to-consumer wellness platform partnerships offers margin protection against distributor disintermediation. For New Entrants and Emerging Players: The premium-to-economy tier price gap in Indian functional food channels offers white-space entry before FSSAI novel food pathways mature. Target sports nutrition brands in the United States with subscription-format powder supply, as these buyers prioritize strain transparency over legacy supplier relationships. Pursue contract manufacturing partnerships with Utah-based supplement formulators seeking fermentation-derived alternatives to synthetic sourcing. For Investors and Strategic Acquirers: CDSCO clinical trial approvals for fermentation-derived GABA in India are the leading indicator that pharmaceutical-grade demand will shift from import-dependent to domestic-sourced supply. Position for five-to-ten year horizon consolidation around precision fermentation specialists with titers exceeding conventional batch benchmarks. Watch for FSSAI regulatory clarity as the inflection signal for functional food channel penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Synthetic biology-enhanced strains enable Kyowa Hakko-competitive purity without heritage facility investment. |
| FOSHU Pre-Notification Filing | Japan's Ministry of Health, Labour and Welfare approval unlocks blood-pressure claim eligibility for beverage producers. |
| Backward Integration into Feedstock | Captive corn glucose supply insulates fermentation margins from agricultural commodity cycles. |
| Direct-to-Consumer Channel Launch | Subscription sleep platforms bypass retail markup and capture batch-level certificate premiums. |
| CDSCO Clinical Trial Partnership | Indian pharmaceutical pathway validation opens API status procurement from domestic contract manufacturers. |
Research Methodology
Multi-period observation of FOSHU approval timelines, DSHEA structure-function claim filings, and fermentation capacity expansion announcements anchored the trend analysis, supplemented by interviews with supplement formulators, pharmaceutical procurement managers, functional beverage R&D directors, and fermentation process engineers. Secondary validation drew from FDA dietary supplement notifications, Japan's Ministry of Health, Labour and Welfare FOSHU databases, EFSA health claim evaluations, and customs trade records. Bottom-up procurement pattern analysis triangulated against top-down production capacity estimates.
Segment-weighting across formulation type, application destination, and end-user procurement sophistication drove the analytical framework. Modeled dimensions included pharma-grade versus food-grade purity tiers, FOSHU-eligible versus non-eligible sourcing routes, and direct-to-consumer versus distributor-mediated channel structures. CAGRs were derived from production capacity buildout trajectories and end-use demand elasticity across the projection horizon. Corn price volatility assumptions and regulatory approval probability weights informed scenario boundaries.
Inputs from FDA notification databases and Japan's Ministry of Health, Labour and Welfare filing records were available through the study window; gaps in real-time EFSA evaluation timelines introduce uncertainty bands for European market penetration assumptions. Forecasts reflect documented assumptions regarding clean-label sourcing momentum and fermentation technology adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Global Acrolein Market
Bulk Chemicals
Mexico Calcium Carbonate Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Global Nitrite Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Propionic Anhydride Market