
 Foundry Coke Market | 2026-2036
Foundry Coke Market Size, Share, and Industry Trends Forecast 2026-2036
Foundry Coke Market Analysis
China's coking corridor is fragmenting as overcapacity pressures collide with environmental enforcement. SunCoke Energy sustains its technology leadership through heat-recovery coking systems that lower emissions intensity. ArcelorMittal anchors European supply through captive coke ovens tied to its blast furnace network. China Risun Group Limited dominates domestic merchant sales by leveraging vertical integration from coal mining to coke export.
Foundry coke is a high-carbon, low-ash metallurgical fuel produced by destructive distillation of bituminous coal in slot-type or beehive ovens, typically yielding carbon content above 89% and ash below 10% to ensure thermal stability in cupola furnaces. Its primary purpose is to melt pig iron and maintain carbon levels in gray and ductile iron casting operations. Metallurgical coke occupies the largest revenue pool across product types due to its ubiquity in integrated steelmaking, while foundry-grade material commands premium pricing from specialized cupola operators requiring larger lump sizes and superior crushing strength. Automotive OEMs represent the fastest-growing end-user channel as lightweighting drives demand for complex ductile iron components.
EPA enforcement under the Clean Air Act shapes US coke oven emissions standards, while China's MEE imposes capacity置换 ratios that constrain new builds. REACH and the EU Green Deal carbon border adjustments threaten import competitiveness for non-European suppliers. Stakeholders must monitor regulatory divergence between carbon-intensive production hubs and import-dependent consuming regions to calibrate long-term asset positioning.

Market Dynamics
Heat-recovery coking technology is fragmenting competitive positioning by allowing smaller operators to meet EU Green Deal emissions thresholds without the capital intensity of traditional slot ovens.
Growth Catalysts
- EU Green Deal carbon border adjustments:European foundries face escalating costs for imported coke, incentivizing domestic capacity expansion and technology upgrades.
- Automotive lightweighting mandates:OEMs require complex ductile iron components for powertrain and chassis applications, sustaining cupola furnace operations.
- Shandong province coking clusters:Proximity to integrated steelworks generates feedstock and logistics efficiencies for foundry-grade material.
Market Restraints
- Bituminous coal price volatility:Input cost swings compress merchant coke margins and destabilize long-term supply contracts.
- China MEE capacity置换 ratios:Environmental regulators mandate replacement capacity ratios that block new coke oven construction in oversupplied regions.
- Electric arc furnace substitution:Scrap-based steelmaking reduces metallurgical coke demand, indirectly pressuring foundry-grade pricing.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for component manufacturing expand addressable foundry demand.
- Heat-recovery and dry quenching convergence:Combined systems capture waste heat and eliminate wet quenching emissions, opening premium pricing tiers.
- Direct-to-foundry digital procurement platforms:B2B marketplaces displace traditional trader intermediaries in spot purchasing.
Industry Challenges
- Coke oven battery rebuild cycles:Refractory deterioration demands 25-30 year capital-intensive rebuilds that strain balance sheets.
- Emissions compliance skill scarcity:Operators lack expertise in continuous emissions monitoring systems required by EPA and MEE enforcement.
- ISO 50001 energy management certification:Documentation burdens delay customer qualification timelines for export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foundry Coke Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallurgical Coke, Foundry Coke, Beverage Coke, Nut Coke Use Case: Iron Casting, Steel Production, Feral Alloys, Sintering Operations Application: Metalworking, Automotive Manufacturing, Construction Materials, Chemical Processes End User: Automotive OEMs, Foundries, Steel Mills, Industrial Plants |
| Companies Covered | ArcelorMittal, China Risun Group Limited, Drummond Company, SunCoke Energy, Nippon Coke and Engineering, Shandong Coking Group, ABC Coke, OKK Koksovny, Italiana Coke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foundry Coke Market Emerging Trajectories
Technology substitution and regulatory stringency are compressing the viable technology set for coke production while reshaping how foundries source their metallurgical fuel.
Heat-recovery coking systems capture waste heat for power generation while eliminating visible emissions from traditional by-product ovens. Foundries in Germany and the Netherlands are adopting these systems to pre-empt EU carbon border tax exposure. The technology is migrating from niche demonstration projects to mainstream capacity replacement as financing costs for environmental compliance rise.
REACH chemical registration requirements and the EU Green Deal carbon border adjustment mechanism impose documentation and certification burdens on non-European suppliers. European importers now demand full supply chain carbon intensity disclosures. Merchant coke traders serving EU foundries face margin compression from compliance costs and rejected shipments.
Foundries are consolidating procurement through long-term offtake agreements with captive coke producers rather than spot market purchases. Tier-1 automotive suppliers in China and Germany are locking in multi-year contracts to secure supply for casting programs. This pattern is most visible in Shandong and the Ruhr Valley, where integrated mill proximity enables direct sourcing relationships.
Foundry Coke Market Segmentation
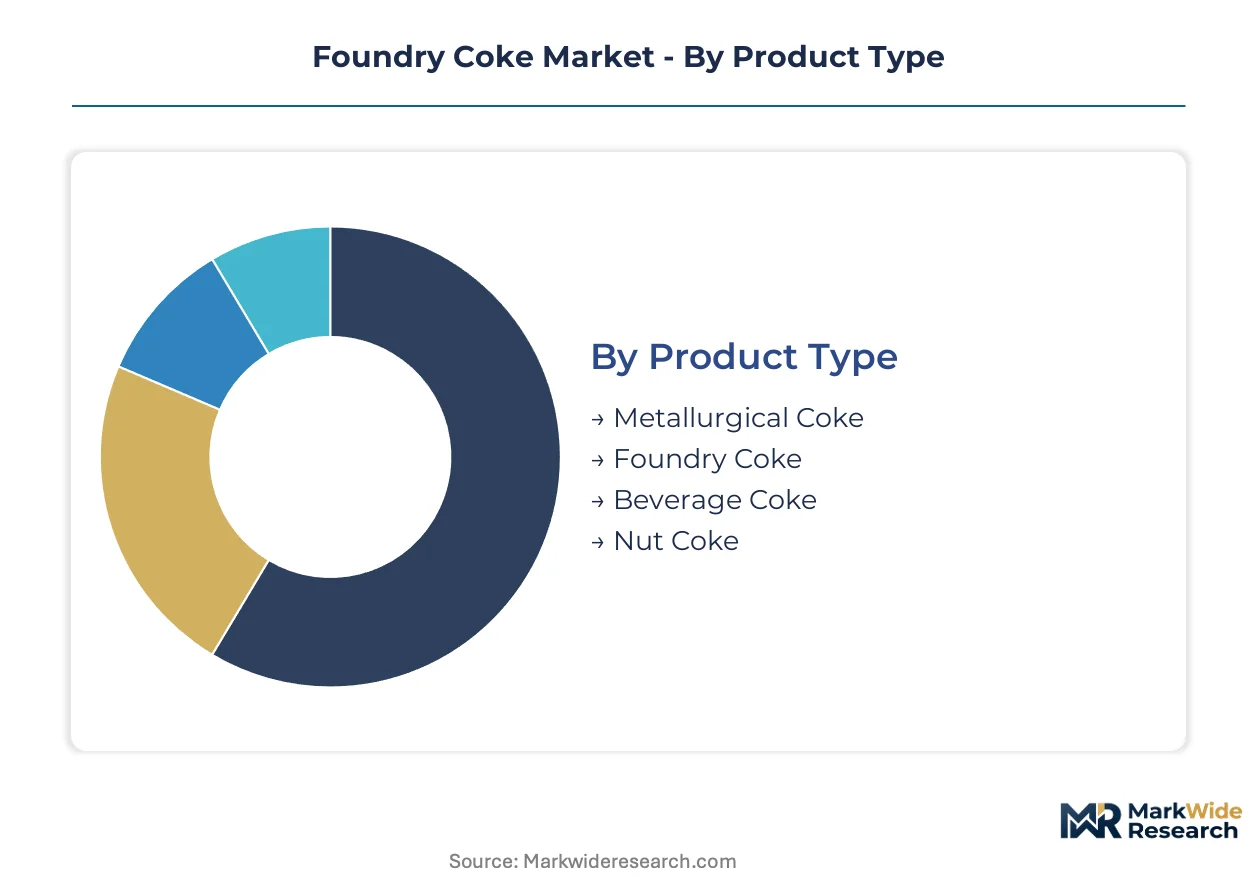
Foundry coke buyers segment procurement across carbon purity thresholds, furnace compatibility, and regulatory certification tiers. Cupola operators in automotive supply chains impose stricter specifications than general foundry customers, fragmenting pricing and supplier qualification requirements.
Product Type:
Cost tier differentiation separates commodity-grade material from premium furnace-ready coke commanding substantial price premiums.
- Metallurgical Coke:High-carbon material with 88-92% fixed carbon and 8-12% volatile matter, engineered for blast furnace reduction chemistry. Steel mills in Germany's Ruhr Valley and China's Shandong province consume the largest volumes, though EAF substitution is compressing long-term demand trajectories.
- Foundry Coke:Large-lump material with superior crushing strength above 90% M40 index and ash content below 8%, optimized for cupola furnace thermal stability. Automotive OEMs in Stuttgart and Wolfsburg specify this grade for ductile iron powertrain castings under tightening EU Green Deal carbon accounting rules.
- Beverage Coke:Activated carbon precursor with controlled porosity for filtration applications. Water treatment facilities in France and the Netherlands represent concentrated demand pockets.
- Nut Coke:Screened fines and undersized material recycled into sinter plant feedstock. Integrated steelworks in Japan and South Korea utilize this grade for cost optimization in ore agglomeration.
Metallurgical coke holds installed capacity. Foundry coke is rotating up the share rankings.
Use Case:
Application maturity varies dramatically across metal production pathways, with legacy blast furnace routes facing steeper decarbonization pressure than specialized casting operations.
- Iron Casting:Cupola furnace melting of pig iron for gray and ductile iron components, requiring consistent carbon dissolution rates. Tier-1 automotive suppliers in China's Hebei province are locking in multi-year offtake agreements to secure supply for transmission housing programs.
- Steel Production:Blast furnace burden material providing reducing gas and structural support in the shaft. ArcelorMittal's Ghent facility and POSCO's Pohang works anchor European and Korean demand respectively, though hydrogen-direct reduction pilot projects threaten substitution timelines.
- Ferro Alloys:Submerged arc furnace feedstock for silicon and manganese alloy smelting. Norwegian producers near Rana leverage hydroelectric power integration to offset carbon intensity.
- Sintering Operations:Fuel and flux in iron ore agglomeration ahead of blast furnace charging. Australian export-oriented steelworks maintain captive sinter plants with integrated coke oven batteries.
Steel production holds installed capacity. Iron casting is rotating up the share rankings.
Application:
Customer type concentration determines specification stringency, with automotive certification programs imposing the most demanding quality documentation requirements.
- Metalworking:General foundry operations producing machinery castings and industrial components. Machine tool builders in Italy's Emilia-Romagna region source through merchant traders with limited long-term contracting.
- Automotive Manufacturing:Precision casting of engine blocks, transmission cases, and suspension components requiring defect-free microstructures. BMW's foundry network in Bavaria and Volkswagen's Kassel plant enforce IATF 16949-aligned supplier audits with carbon intensity disclosure mandates.
- Construction Materials:Drainage and sanitary castings with lower mechanical property requirements. Municipal infrastructure programs in Spain and Poland drive seasonal demand fluctuations.
- Chemical Processes:Carbon source for calcium carbide and synthetic gas production. Acetylene manufacturers in Ukraine and Kazakhstan represent fragmented demand.
Metalworking holds installed capacity. Automotive manufacturing is rotating up the share rankings.
End User:
Supply concentration patterns align with captive integration economics, distinguishing asset-heavy steel producers from merchant-dependent foundry operators.
- Automotive OEMs:Vertically integrated casting divisions and tier-1 supplier networks with direct coke procurement authority. Mercedes-Benz's Untertürkheim foundry and BYD's Xi'an casting complex exemplify the specification-setting customer segment.
- Foundries:Independent cupola operators serving job-shop and contract casting markets. Germany's Schleswig-Holstein and China's Jiangsu province host dense clusters of mid-scale family-owned operations.
- Steel Mills:Integrated producers with captive coke oven batteries or long-term merchant contracts. Tata Steel's IJmuiden facility and Nippon Steel's Nagoya works maintain self-sufficient carbon supply chains.
- Industrial Plants:Non-ferrous smelters and chemical processors with intermittent coke demand. Alcoa's Icelandic aluminum smelters and Solvay's soda ash facilities in Belgium source through spot market intermediaries.
Steel mills hold installed capacity. Automotive OEMs are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors the dominant geography through capacity置换 enforcement that constrains new coke oven construction while consolidating output in Shandong province. The regulatory divergence between carbon-intensive production hubs and import-dependent consuming regions is reshaping trade flows and asset positioning across the analysis window.
China
Shandong province hosts dense coking clusters around integrated steelworks in Jinan and Zibo. The MEE's capacity置换 ratios mandate replacement capacity for any new builds, effectively blocking expansion in oversupplied regions. China Risun Group leverages backward integration from coal mining through coke export to dominate domestic merchant sales.
United States
EPA enforcement under the Clean Air Act shapes coke oven emissions standards for foundries serving automotive OEMs in the Midwest. SunCoke Energy sustains technology leadership through heat-recovery coking systems that lower emissions intensity. Alabama and Indiana host concentrated merchant coke capacity tied to regional blast furnace networks.
Germany
The Ruhr Valley anchors European foundry coke demand through ArcelorMittal's captive coke ovens at its Ghent facility network. REACH chemical registration and EU Green Deal carbon border adjustments threaten import competitiveness for non-European suppliers. Stuttgart and Wolfsburg automotive OEMs enforce IATF 16949-aligned supplier audits with carbon intensity disclosure mandates.
India
The PLI scheme for automotive component manufacturing expands addressable foundry demand in Maharashtra and Tamil Nadu. The country's national environmental regulator imposes emissions monitoring requirements that strain operator expertise. Dharwad and Coimbatore casting clusters are consolidating procurement through long-term offtake agreements with captive producers.
Japan
POSCO's Pohang works and Nippon Steel's Nagoya facilities maintain self-sufficient carbon supply chains through integrated coke oven batteries. METI standards govern energy efficiency in metallurgical fuel production. Kyushu and Chubu regions host specialized foundry operations serving precision automotive casting programs.
Foundry Coke Market Vendor Landscape
Capability concentration sits with technology-integrated specialists; scale advantage sits with steel-integrated majors. The market structures around three tiers: captive producers serving internal steel demand, merchant specialists selling to independent foundries, and regional traders bridging spot market gaps. Dominant competitive moves include backward integration into coal mining assets and heat-recovery technology licensing to preempt EU carbon border exposure.
Within the steel-integrated tier, ArcelorMittal and Nippon Coke and Engineering exemplify captive supply chain control. Among technology-focused specialists, SunCoke Energy represents heat-recovery coking advancement. China Risun Group Limited occupies a position as a vertically integrated merchant operator spanning extraction through export logistics.
| Leading Market Players |
|---|
| ArcelorMittal |
| China Risun Group Limited |
| Drummond Company |
| SunCoke Energy |
| Nippon Coke and Engineering |
| Shandong Coking Group |
| ABC Coke |
| OKK Koksovny |
| Italiana Coke |
| Others |
Supply Flow & Price Mechanics
Shandong province's coking corridor concentration funnels margin pools toward integrated steelworks with captive coke ovens, while merchant operators absorb coal price volatility through contract structures. The interplay between bituminous coal input costs and foundry-grade premium tiers shapes how procurement managers balance spot exposure against long-term offtake security.
Pricing Analysis
Price spreads between Chinese export grades and European domestic material reflect carbon border adjustment exposure under the EU Green Deal. Three-tier pricing structure across premium IATF-certified, standard foundry-grade, and economy sinter-feed tiers separates automotive OEM contracts from general metalworking spot purchases. Pricing pressure stems from electric arc furnace substitution eroding blast furnace coke demand, with tier-1 automotive suppliers showing lowest price sensitivity due to specification lock-in.
Supply Chain Analysis
Extended payment terms from automotive OEMs strain working capital for merchant coke traders, accelerating supply-chain finance facility adoption. Raw material sourcing draws from Australian metallurgical coal, Mongolian coking coal, and domestic Chinese bituminous deposits. Single-source vulnerability concentrates in Shandong's integrated mill corridor, where MEE capacity置换 enforcement constrains alternative supply development. Distribution runs through direct mill-to-foundry contracts displacing traditional trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry coke incumbents face structural substitution pressure from hydrogen-direct reduction pilot projects and scrap-based electric arc furnace expansion, requiring defensive positioning around irreplaceable cupola furnace applications.
For Market Incumbents: Pre-empt EU carbon border tax exposure by licensing heat-recovery coking technology to European foundry partners before compliance deadlines tighten. Lock in multi-year offtake agreements with Stuttgart and Wolfsburg automotive casting programs to defend against EAF substitution in powertrain component demand. Prioritize backward integration into Mongolian coking coal assets to offset Australian supply cost volatility.
For New Entrants and Emerging Players: Build out heat-recovery coking capacity in India's Maharashtra and Tamil Nadu automotive corridors, where PLI scheme incentives expand addressable foundry demand without legacy slot-oven capital burdens. Target tier-2 automotive suppliers in Germany's Schleswig-Holstein region with carbon intensity disclosure capabilities that incumbent traders lack. Pursue direct-to-foundry digital procurement platforms to displace fragmented spot-market intermediaries.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated merchant operators with captive coal mining and export logistics control across the analysis window. Acquisition targets should demonstrate heat-recovery technology adoption and IATF 16949 certification pathways. Watch hydrogen-direct reduction commercialization timelines at ArcelorMittal's Ghent facility as the key demand destruction signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Recovery Technology Licensing | Enables EU Green Deal compliance without slot-oven capital intensity for German foundries. |
| Backward Integration into Coal Mining | Secures Mongolian coking coal supply against Australian price volatility for China Risun-type operators. |
| Long-Term Offtake Agreements | Locks in Stuttgart automotive casting demand before EAF substitution accelerates. |
| Digital Procurement Platform Launch | Displaces traditional trader intermediaries in Shandong spot purchasing. |
| IATF 16949 Certification Investment | Qualifies supply for BMW and Volkswagen carbon intensity disclosure mandates. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cupola furnace managers, automotive tier-1 procurement leads, coke oven battery engineers, and merchant trading desk heads. Secondary validation drew from EPA enforcement filings, China MEE capacity置换 notices, EU ETS carbon border adjustment documentation, and integrated steelworks SEC disclosures. Bottom-up volume modeling across product grades and top-down macroeconomic calibration ensured triangulation integrity.
Calibration against historical trade flows and capacity utilization rates anchored projections across the modeling period. Segmentation dimensions included carbon purity tier, furnace compatibility class, regulatory certification level, and end-user supply chain integration depth. CAGRs were derived from supply-demand balance modeling incorporating MEE capacity constraints and automotive lightweighting program pipelines.
Stress conditions across bituminous coal price bands, EU carbon border tax implementation timelines, and EAF substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Castor Oil Derivatives Market
Bulk Chemicals
Precipitated Calcium Carbonate Market
Bulk Chemicals
Aluminum Potassium Sulfate Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Benzyl Chloride Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Tin Fluoborate Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Global Ferrous Sulfate Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Global Cyclohexylbenzene Market