
 Glyceryl Triacetate (Triacetin) Market | 2026-2036
Glyceryl Triacetate (Triacetin) Market Size, Share, and Industry Trends Forecast 2026-2036
Glyceryl Triacetate (Triacetin) Market Foresight
Chemical engineering talent specializing in esterification processes is reorganizing competitive dynamics across the triacetin value chain. BASF leverages its integrated acetic acid and glycerol supply networks to sustain cost advantages in European production. Eastman Chemical Company anchors North American supply through specialized plasticizer manufacturing capabilities. Jiangsu Ruijia Food Ingredient competes aggressively on food-grade certification breadth across Asian export markets.
Glyceryl triacetate is a triester of glycerol and acetic acid, typically manufactured through esterification of glycerol with acetic acid or acetic anhydride at controlled temperatures, yielding a clear, odorless liquid with a boiling point near 259°C. It functions primarily as a plasticizer, solvent, and humectant across food, pharmaceutical, and polymer applications. The pharmaceutical application segment leads value generation due to stringent excipient purity requirements and long qualification cycles with drug manufacturers. The polymer industry application is expanding fastest as PVC and cellulose acetate producers seek phthalate-free plasticizer alternatives. Food additive grade product types occupy mature margin pools where certification maintenance costs create defensive moats for incumbent suppliers.
The European Chemicals Agency enforces REACH registration and hazard classification protocols that elevate compliance costs for triacetin importers into EU member states. The FDA maintains Food Chemicals Codex monographs and pharmaceutical excipient guidelines that shape product specifications for US-bound manufacturers. China's Ministry of Ecology and Environment applies dual carbon goals and emission intensity standards that influence glycerol-to-triacetin conversion technology choices. Stakeholders must monitor evolving excipient pharmacopeia harmonization between USP, EP, and ChP standards to anticipate qualification burden shifts.
Market Dynamics
The phthalate-free plasticizer mandate across polymer compounding is compressing qualification timelines for triacetin suppliers while simultaneously elevating purity thresholds beyond legacy glycerol ester specifications.
Growth Catalysts
- REACH Annex XIV restrictions on phthalates:European PVC manufacturers face binding substitution deadlines that accelerate triacetin qualification for flexible film and medical tubing applications.
- Controlled-release pharmaceutical formulations:Drug developers exploit triacetin's solvent-plasticizer dual function to engineer precise API release kinetics in oral and transdermal delivery systems.
- Acetic anhydride route optimization:Continuous esterification reactor designs cut conversion cycle times and energy intensity compared to batch acetic acid processes.
Market Restraints
- Refined glycerol feedstock volatility:Biodiesel production swings and oleochemical demand spikes transmit directly to triacetin variable cost structures.
- Jiangsu and Shandong supply concentration:Chinese coastal chemical clusters control disproportionate export capacity, creating geographic single-point vulnerability for Atlantic buyers.
- Citrate ester substitution threat:Acetyl tributyl citrate and triethyl citrate compete for identical phthalate-replacement slots in food-contact and pediatric-sensitive polymer grades.
Strategic Opportunities
- Brazilian polymer compounding expansion:ANVISA-aligned local production bypasses import tariff barriers while serving Mercosur flexible packaging demand growth.
- Cosmetic humectant certification stacking:Dual ECOCERT and COSMOS approvals open premium personal care segments where glycerol triacetate replaces petroleum-derived alternatives.
- Carbon intensity labeling convergence:EU Green Deal carbon border adjustments reward low-emission esterification routes with preferential market access positioning.
Industry Challenges
- Excipient pharmacopeia harmonization complexity:Divergent USP, EP, and ChP heavy metal limits force redundant testing protocols and extended qualification cycles with multinational drug manufacturers.
- Specialized chemical engineering scarcity:Esterification process design expertise concentrates at mid-career levels without sufficient university pipeline replenishment for plant optimization roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glyceryl Triacetate (Triacetin) Market |
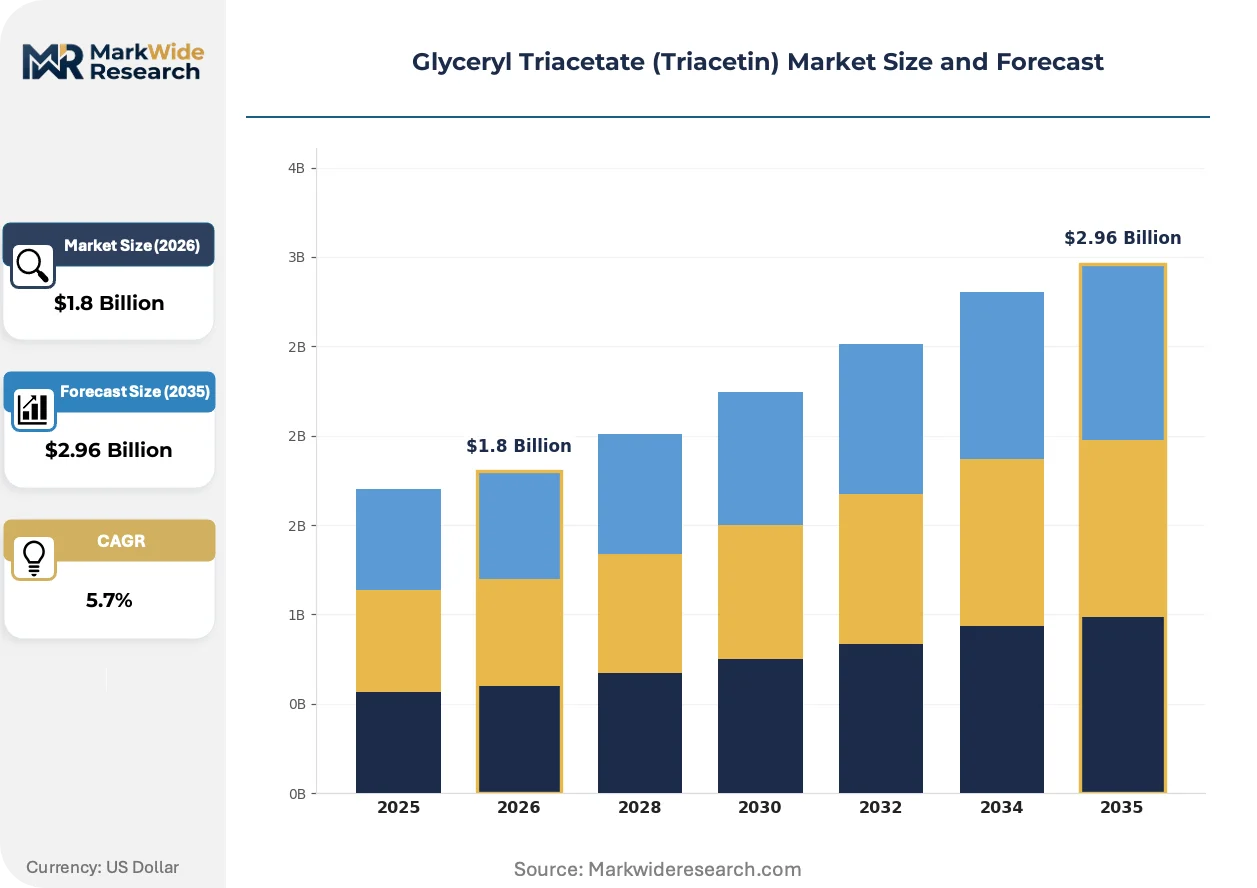
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Additive, Cosmetic Ingredient, Solvent, Plasticizer Application: Beverages, Personal Care, Pharmaceuticals, Polymer Industry End User: Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Chemical Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Polynt Group, Mitsubishi Chemical Corporation, BASF, Jiangsu Ruijia Food Ingredient, Anhui Hongyang Chemical, Eastman Chemical Company, Daicel Corporation, Yixing Kaixin Chemical, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glyceryl Triacetate (Triacetin) Market Shifts & Advancements
Process intensification and regulatory substitution mandates are compressing the technology lifecycle for glycerol ester production while fragmenting end-use specifications across pharmaceutical, food, and industrial tiers.
Membrane-assisted reactive distillation is displacing conventional batch esterification in new capacity installations. European and North American specialty chemical producers adopt these hybrid reactor-separator systems to cut acetic acid recovery costs and boost triacetin purity above 99.5% in single-pass configurations. The technology is displacing legacy sulfuric acid catalysis in premium-grade applications where residual catalyst traces trigger pharmacopeia rejection.
REACH SVHC candidate list expansion is tightening hazard communication obligations for triacetin importers into EU member states. The European Chemicals Agency's 2024-2025 substance evaluation work program targets plasticizer metabolite toxicology, forcing suppliers to generate extended safety data sets ahead of potential restriction proposals. Pharmaceutical excipient manufacturers face the steepest compliance cost escalation given their downstream liability exposure in drug master files.
Specification-driven procurement consolidation is compressing supplier bases across polymer compounding. Large PVC and cellulose acetate compounders now mandate dual food-grade and pharmaceutical-grade certification breadth from core triacetin sources, eliminating single-grade specialists from approved vendor lists. This pattern is most visible in German and Italian automotive interior supply chains where OEM material bans cascade through tiered supplier qualification requirements.
Glyceryl Triacetate (Triacetin) Market Segmentation
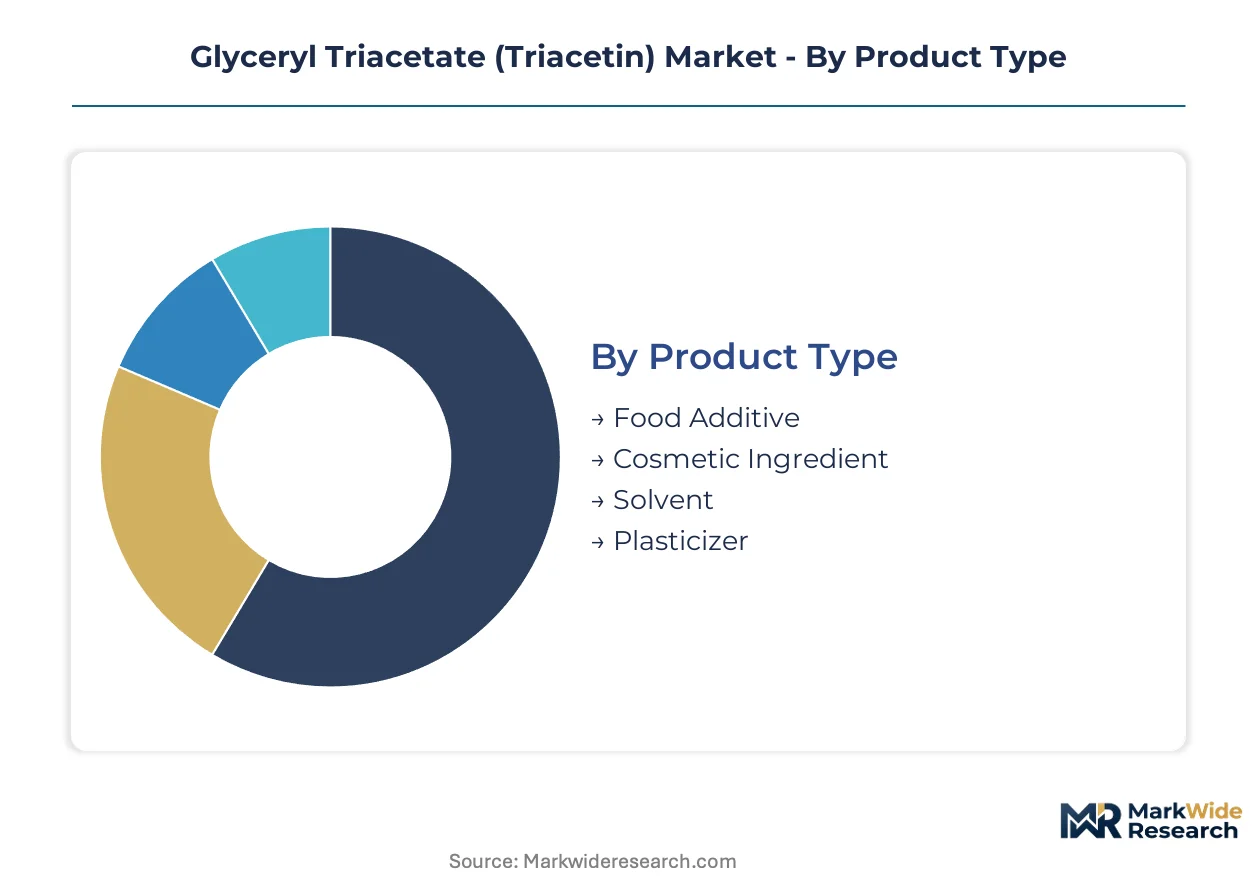
Triacetin specifications diverge sharply across pharmaceutical, food, and industrial tiers, with purity thresholds and certification burdens determining channel access and margin capture. Suppliers must maintain parallel production streams because pharmaceutical-grade lots cannot downgrade into food applications, while food-grade material fails polymer compounding specifications.
Product Type:
Food additive and cosmetic ingredient grades flow predominantly through distributor networks serving fragmented small-batch buyers, while plasticizer and solvent volumes move via direct sales to integrated polymer compounders.
- Food Additive:FCC and JECFA-compliant specifications with glycerol source traceability requirements for halal and kosher certification stacks. Demand concentrates in Japanese and Southeast Asian sauce manufacturers seeking humectant stability in high-moisture formulations. Certification maintenance costs create defensive moats for incumbent suppliers with established audit histories.
- Cosmetic Ingredient:ECOCERT and COSMOS approvals enable premium positioning in European and North American personal care formulations where petroleum-derived alternatives face clean-label displacement. French and German cosmetic brands drive qualification timelines for natural-origin glycerol feedstocks.
- Solvent:USP and EP monograph compliance for pharmaceutical extraction and coating applications.
- Plasticizer:Phthalate-free PVC and cellulose acetate compounding for medical tubing and flexible packaging.
Food additive dominates installed base. Plasticizer is where expansion concentrates.
Application:
Cost tier stratification separates commodity beverage applications from premium pharmaceutical excipient contracts.
- Pharmaceuticals:Excipient-grade material commands qualification cycles exceeding 18 months with drug manufacturers seeking solvent-plasticizer dual function in controlled-release matrices. USP, EP, and ChP harmonization gaps force redundant heavy metal testing protocols.
- Polymer Industry:REACH Annex XIV phthalate restrictions accelerate substitution timelines for flexible film and medical tubing producers. German and Italian automotive interior supply chains cascade OEM material bans through tiered supplier requirements.
- Beverages:Clouding agent and flavor carrier applications in citrus and cola formulations.
- Personal Care:Humectant and solvent functions in premium skincare emulsions.
Pharmaceuticals captures premium margin tiers. Polymer industry shows steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies mandating dual-grade certification breadth that eliminates single-tier suppliers.
- Pharmaceutical Companies:Drug master file obligations and excipient pharmacopeia compliance create sticky supplier relationships with high switching costs. Multinational manufacturers in Switzerland and the United States enforce extended safety data requirements ahead of potential ECHA restriction proposals.
- Food Manufacturers:BRC and FSSC 22000 audit requirements for direct-contact additives with batch-level traceability.
- Cosmetic Brands:Clean-label positioning drives natural-origin certification stacking.
- Chemical Producers:Integrated acetic acid and glycerol supply networks enable backward integration into captive triacetin production.
Pharmaceutical companies anchor long-term contract volumes. Chemical producers are consolidating backward integration.
Distribution Channel:
Geographic supply concentration in Chinese coastal clusters shapes Atlantic buyer vulnerability and channel selection.
- Distributors:Regional chemical distributors stock food-grade and cosmetic-grade material for fragmented small-batch buyers in Brazil and Mexico. Inventory pooling reduces working capital burdens for buyers facing glycerol feedstock volatility.
- Direct Sales:Polymer compounders and pharmaceutical manufacturers negotiate frame contracts with producers for specification-customized lots. BASF and Eastman anchor European and North American supply through dedicated account management.
- Online Retail:Laboratory and small-scale cosmetic formulation suppliers.
- Specialty Stores:Food ingredient and personal care DIY channels.
Direct sales dominates pharmaceutical and polymer volumes. Distributors handle fragmented food and cosmetic demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment anchors the dominant geography through dual carbon goals and emission intensity standards that shape glycerol-to-triacetin conversion technology choices across the largest production base.
China
Jiangsu and Shandong coastal chemical clusters control disproportionate export capacity for both polymer industry feedstock and pharmaceutical-grade material. The Ministry of Ecology and Environment applies dual carbon goals that influence esterification reactor technology selection. Yixing and Nantong chemical parks concentrate new membrane-assisted reactive distillation installations serving Asian export markets.
Germany
REACH Annex XIV phthalate restrictions accelerate triacetin qualification timelines for flexible PVC film and medical tubing producers. The European Chemicals Agency enforces SVHC candidate list expansion that elevates hazard communication obligations for importers. BASF leverages integrated acetic acid and glycerol supply networks from Ludwigshafen to sustain cost advantages in European pharmaceutical excipient production.
United States
Eastman Chemical Company anchors North American supply through specialized plasticizer manufacturing capabilities serving controlled-release drug formulations. The FDA maintains Food Chemicals Codex monographs and pharmaceutical excipient guidelines that shape product specifications for domestic manufacturers. Tennessee and Texas chemical corridors concentrate compounding operations for medical tubing and flexible packaging applications.
Japan
Mitsubishi Chemical Corporation and Daicel Corporation serve domestic pharmaceutical and polymer demand with high-purity esterification output. The Ministry of Economy, Trade and Industry (METI) oversees chemical industry decarbonization roadmaps that influence glycerol feedstock sourcing. Osaka and Chiba industrial zones maintain specialized production lines for electronics-grade plasticizer applications.
Brazil
ANVISA-aligned local production targets Mercosur flexible packaging demand growth while bypassing import tariff barriers. The national health surveillance agency applies pharmaceutical excipient registration requirements that shape qualification timelines for multinational suppliers. São Paulo state chemical parks attract regional compounding investment serving automotive interior and medical device sectors.
Glyceryl Triacetate (Triacetin) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the triacetin value chain. European and North American specialty chemical producers dominate premium-grade pharmaceutical and food-certified segments through advanced esterification process control. Chinese domestic chemical producers anchor volume supply for polymer plasticizer applications through scaled acetic anhydride route capacity. Strategic moves concentrate on backward integration into glycerol feedstock security and membrane-assisted reactive distillation technology licensing.
Within the integrated multinational tier, BASF and Eastman Chemical Company exemplify archetypes combining acetic acid supply network control with pharmaceutical-grade certification breadth. Jiangsu Ruijia Food Ingredient occupies a position representing aggressive Asian competition on food-grade certification stacking across export markets. These three anchors illustrate how geographic feedstock access and regulatory compliance capabilities determine competitive positioning across pharmaceutical, food, and polymer end-use tiers.
| Leading Market Players |
|---|
| Polynt Group |
| Mitsubishi Chemical Corporation |
| BASF |
| Jiangsu Ruijia Food Ingredient |
| Anhui Hongyang Chemical |
| Eastman Chemical Company |
| Daicel Corporation |
| Yixing Kaixin Chemical |
| LANXESS |
| Others |
Supply & Pricing Matrix
REACH Annex XIV phthalate restrictions gate both supplier qualification timelines and price differentiation across pharmaceutical, food-grade, and polymer-tier triacetin segments simultaneously. Buyers face compressed vendor lists where dual-grade certification breadth commands measurable premiums over single-tier specialists.
Pricing Analysis
Atlantic buyers absorb 15-25% delivered cost premiums versus Asian polymer compounders sourcing directly from Jiangsu and Shandong coastal clusters. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels reflects certification maintenance burdens and pharmacopeia testing redundancy. Cost compression in industrial-grade tiers is intensifying because Chinese acetic anhydride route expansions flood export markets with undifferentiated plasticizer feedstock. Polymer compounders exhibit highest price sensitivity due to commodity substitution elasticity, while pharmaceutical excipient buyers prioritize supply security over unit economics.
Supply Chain Analysis
Biodiesel-derived refined glycerol availability in Southeast Asian oleochemical hubs creates single-source vulnerability for European and North American esterification plants. Production draws from acetic acid supply networks anchored in Ludwigshafen, Texas Gulf Coast, and Nantong chemical parks, with membrane-assisted reactive distillation technology concentrating in Yixing and Chiba industrial zones. Tariff exposure runs through Atlantic import corridors dependent on Chinese coastal cluster output. Distribution runs through direct frame contracts for pharmaceutical and polymer volumes, with regional chemical distributors pooling food-grade and cosmetic-grade inventory for fragmented Latin American and Southeast Asian buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across pharmaceutical excipient, food additive, and phthalate-free plasticizer tiers creates defendable niche positions for specialists with certification stacking capabilities. REACH SVHC candidate list expansion and dual carbon compliance in China accelerate vendor consolidation pressures.
For Market Incumbents: Shield pharmaceutical-grade margin pools through preemptive ECHA extended safety data set generation ahead of metabolite toxicology evaluations. Deepen backward integration into biodiesel glycerol offtake agreements to neutralize feedstock volatility transmission. Prioritize membrane-assisted reactive distillation licensing revenue from Chinese producers seeking European market access. For New Entrants and Emerging Players: Lead with ECOCERT and COSMOS dual certification in Brazilian and Mexican cosmetic humectant segments where petroleum-derived alternatives face clean-label displacement. Target ANVISA-aligned local production in São Paulo state chemical parks to capture Mercosur flexible packaging demand while bypassing import tariff barriers. Deploy distributor partnerships with regional chemical inventory poolers to reduce working capital burdens for small-batch buyers. For Investors and Strategic Acquirers: REACH Annex XIV phthalate substitution deadlines reshape the acquisition landscape toward mid-cap esterification specialists with pharmaceutical-grade pharmacopeia breadth and polymer compounding qualification histories. Five-to-ten year viability favors producers with captive acetic acid supply and membrane technology licensing portfolios over pure-play glycerol ester converters. Monitor ECHA substance evaluation work program announcements for restriction proposal signals that would accelerate incumbent liability exposure and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycerol Feedstock | Biodiesel offtake agreements neutralize refined glycerol price volatility for European and North American esterification plants. |
| Membrane-Assisted Reactive Distillation Licensing | Technology transfer revenue from Chinese producers seeking REACH-compliant purity thresholds above 99.5%. |
| Dual Pharmacopeia Certification Investment | USP and EP heavy metal harmonization gaps force redundant testing that eliminates single-grade specialists from approved vendor lists. |
| ANVISA-Aligned Local Production | São Paulo state chemical park presence captures Mercosur medical tubing and automotive interior demand while bypassing Atlantic tariff exposure. |
| ECOCERT and COSMOS Certification Stacking | French and German cosmetic brand qualification timelines open premium personal care segments for natural-origin glycerol feedstock positioning. |
Research Methodology
Cross-validation between primary interviews with esterification plant managers, pharmaceutical procurement leads, polymer compounding technical directors, and cosmetic brand formulators anchors the qualitative findings against secondary validation from customs/trade data, SEC 10-K filings, Cefic chemical industry reports, and ECHA substance evaluation documentation. Bottom-up capacity and demand modeling triangulates against top-down value chain analysis across the glycerol ester sector.
Sensitivity analysis around biodiesel production swings and acetic acid supply disruptions tests forecast robustness across the projection horizon. Segmentation dimensions include grade tier (pharmaceutical, food, industrial), end-use industry (drug formulation, PVC compounding, personal care, food manufacturing), packaging format (bulk tanker, drum, IBC), and regional production hub (Chinese coastal clusters, German chemical corridor, US Gulf Coast). CAGRs derive from trend extrapolation moderated by regulatory inflection timing and technology substitution elasticity, with glycerol feedstock cost curves and REACH restriction implementation schedules as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained biodiesel production growth or accelerated ECHA metabolite restriction timelines would require recalibration. Forecasts reflect documented assumptions regarding pharmacopeia harmonization progress and dual carbon policy enforcement intensity in Chinese chemical parks. Practitioners should keep alternative scenarios live as ECHA SVHC candidate list expansion and EU Green Deal carbon border adjustment implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
Cobalt (II) Sulfate Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
2,4-Dichlorophenoxyacetic Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
Mexico Calcium Carbonate Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Europe Calcium Carbonate Market