
 Africa Polyethylene Terephthalate (PET) Market | 2026-2036
Africa Polyethylene Terephthalate (PET) Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Polyethylene Terephthalate (PET) Market Insights
Small-scale beverage bottlers and regional dairy processors is bifurcating Africa's PET procurement landscape, pulling volume away from multinational CPG conglomerates that once dominated contract structures. Indorama Ventures leverages its integrated PTA-PET resin complexes in Nigeria and Egypt to anchor supply security for downstream preform converters. Safripol sustains technical leadership in food-grade bottle resin formulations tailored to hot-fill applications across Southern African markets. Extrupet competes through its closed-loop rPET operations in South Africa, converting post-consumer waste into certified food-grade flake.
Polyethylene terephthalate is a linear thermoplastic polymer synthesized through esterification of terephthalic acid with ethylene glycol, yielding a material with crystallinity between 30-40% in standard bottle grades and melt temperatures near 260°C that delivers barrier performance against CO₂ and moisture in carbonated beverage containment. Preforms dominate value capture across African conversion economics due to their role as the intermediate input for blow-molded bottles serving Coca-Cola and Pepsi bottling networks. Fibers represent the fastest-expanding grade category as Ethiopian and Egyptian textile mills displace cotton-polyester blends with 100% rPET filament for export apparel contracts bound to European fast-fashion retailers. Food-grade PET commands persistent margin premiums over industrial-grade resin because CDSCO-equivalent national food safety authorities in Kenya, Nigeria, and South Africa enforce migration limit testing on aromatic polyester oligomers.
South Africa's National Regulator for Compulsory Specifications enforces SANS 1649 packaging material standards that restrict heavy metal content in PET containers, while Egypt's EOS applies mandatory conformity assessment on imported resin lots under its quality surveillance program. Kenya's National Environment Management Authority enforces extended producer responsibility regulations that obligate brand owners to finance collection infrastructure for post-consumer PET bottles, directly shaping recycler feedstock economics. Stakeholders must monitor how rapidly evolving EPR enforcement timelines and rPET content mandates across African economic blocs will reshape capital allocation between virgin resin expansion and mechanical recycling infrastructure.
Market Dynamics
Kenya's ban on single-use plastics in protected areas is accelerating demand for recycled-grade PET feedstock, forcing converters to reconfigure sourcing strategies across East African packaging corridors.
Growth Catalysts
- Extended Producer Responsibility mandates:Kenya's National Environment Management Authority obligates brand owners to finance collection infrastructure, directly expanding recycler feedstock availability.
- Hot-fill packaging expansion:Regional dairy processors in Southern African markets are adopting food-grade bottle resin formulations for extended shelf-life products.
- Lagos industrial corridor concentration:Nigeria's packaging cluster attracts preform converters serving Coca-Cola and Pepsi bottling networks with integrated resin supply.
Market Restraints
- PTA feedstock volatility:Purified terephthalic acid price swings constrain margin stability for resin producers lacking captive aromatics supply.
- South African recycler dominance:Extrupet's closed-loop rPET operations concentrate food-grade flake supply in a single geography, creating bottleneck risk.
- Migration limit testing regimes:CDSCO-equivalent national food safety authorities in Kenya, Nigeria, and South Africa impose aromatic polyester oligomer compliance costs on importers.
Strategic Opportunities
- Ethiopian textile mill expansion:Export apparel contracts bound to European fast-fashion retailers drive 100% rPET filament adoption in fiber-grade applications.
- Alexandria packaging cluster scale-up:Egypt's EOS quality surveillance program creates certified import pathways for preform converters serving North African beverage markets.
- Mechanical recycling infrastructure gaps:Underdeveloped collection networks in West Africa outside Nigeria present first-mover terrain for integrated waste-to-flake operators.
Industry Challenges
- Food-grade rPET certification timelines:National regulators lack harmonized protocols for post-consumer waste conversion to certified bottle resin, delaying capital deployment.
- Blow-molding technician scarcity:Preform-to-bottle conversion operations face skilled operator shortages across East African industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Polyethylene Terephthalate (PET) Market |
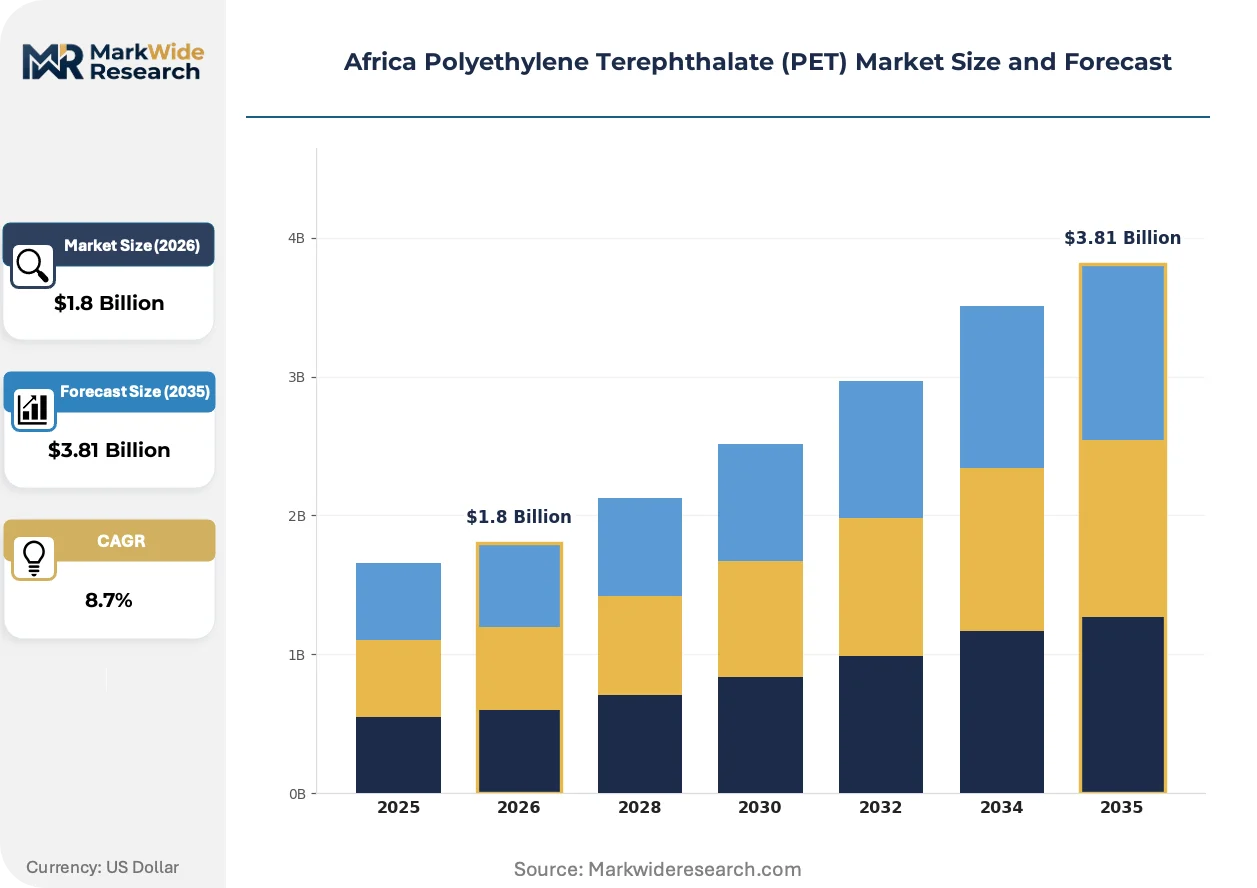
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preforms, Bottles, Films, Fibers End Use Industry: Packaging, Textiles, Automotive, Electronics Grade: Food Grade, Industrial Grade, Recycled, Copolymer Application: Container Production, Textile Manufacturing, Electrical Insulation, Automotive Components |
| Companies Covered | Indorama Ventures Public Company Limited, Safripol Pty Ltd, ALPLA, Extrupet (Pty) Ltd, Mpact Group Limited, Egyptian International Packaging, Polyserve Africa, PakPal, Nampak, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Polyethylene Terephthalate (PET) Market Trends and Innovations
Recycled-content mandates and collection infrastructure financing are reconfiguring competitive advantage toward integrated waste-to-resin operators rather than standalone virgin producers.
Advanced optical sorting and flake washing systems are supplanting manual separation in African mechanical recycling facilities. Egyptian and South African recyclers deploy near-infrared polymer identification to achieve food-grade purity thresholds. This technology compression enables certified rPET supply to preform converters at price parity with virgin resin in select corridors.
Kenya's National Environment Management Authority enforces extended producer responsibility regulations that obligate brand owners to finance collection infrastructure. Industrial consequence: multinational beverage bottlers now directly contract with informal waste picker networks, bypassing traditional aggregator middlemen. The preform converter segment in Nairobi and Mombasa faces working capital pressure from feedstock prepayment requirements.
Small-scale beverage bottlers and regional dairy processors are fragmenting procurement concentration once held by multinational CPG conglomerates. Direct resin contracts with Indorama Ventures' Nigerian PTA-PET complexes replace distributor-mediated supply. This pattern concentrates in Nigeria's Lagos industrial corridor where local bottlers now command volume discounts previously reserved for global brand owners.
Africa Polyethylene Terephthalate (PET) Market Segmentation
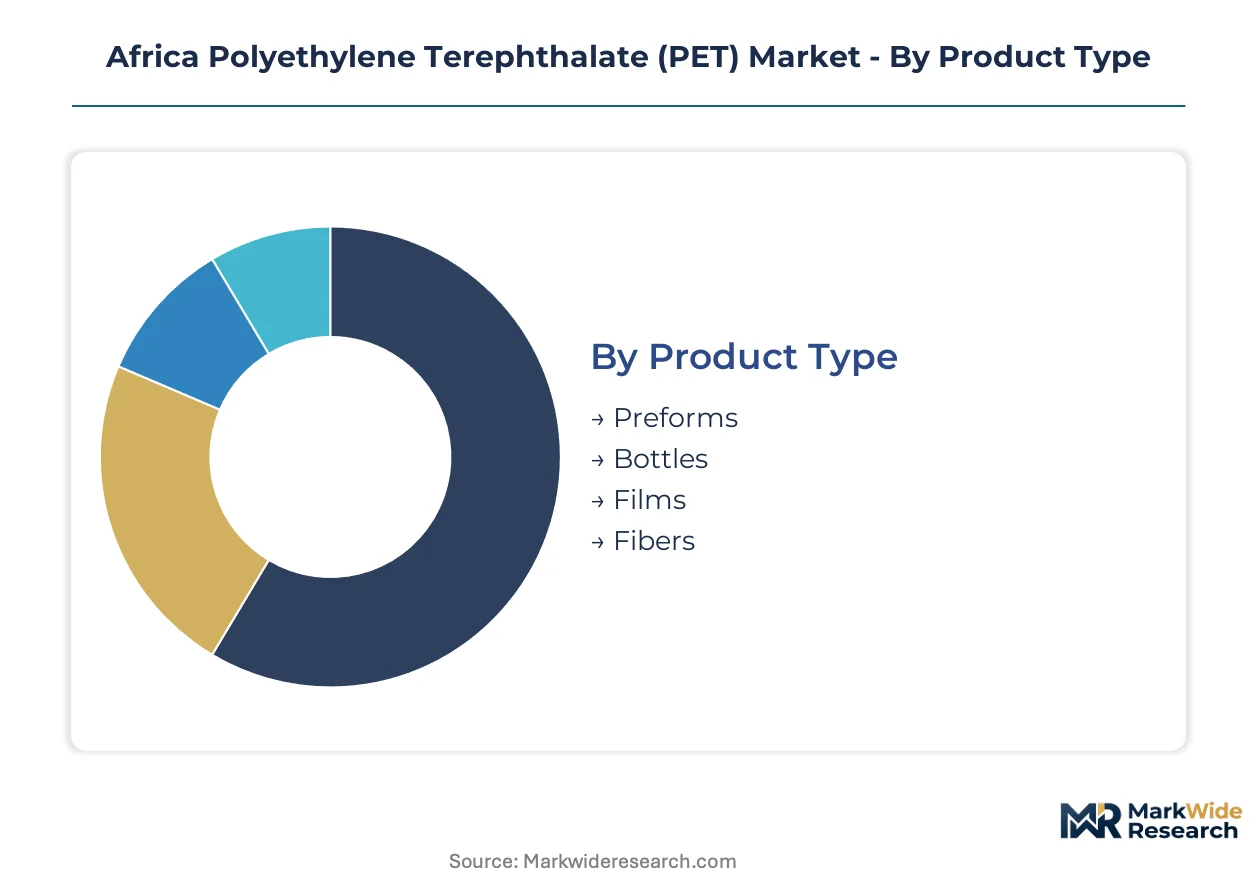
PET procurement patterns across Africa fragment sharply by product form and grade specification, with margin pools concentrating in intermediates and certified food-grade resin. Understanding these segment boundaries clarifies where converters capture value versus where resin producers retain pricing power.
Product Type:
Margin pools concentrate in intermediate forms that command technical premiums over commodity resin pellets.
- Preforms:Injection-molded PET parisons with calibrated neck finishes and controlled wall thickness distribution serve as the standardized input for stretch blow molding. Demand clusters in Nigeria's Lagos industrial corridor where preform converters supply Coca-Cola and Pepsi bottling networks with just-in-time delivery schedules.
- Bottles:Finished containers dominate end-use value capture but face margin compression from converter competition and lightweighting mandates. Kenya's National Environment Management Authority extended producer responsibility regulations force brand owners to finance collection infrastructure, reshaping bottle economics toward post-consumer recovery integration.
- Films:Biaxially oriented PET sheeting serves thermoforming and lidding applications across North African dairy packaging.
- Fibers:Melt-spun filament displaces cotton-polyester blends in Ethiopian and Egyptian textile mills supplying European fast-fashion retailers.
Preforms hold installed capacity. Fibers is rotating up the share rankings.
End Use Industry:
Application-driven volume distribution shows packaging commanding procurement concentration while textiles climbs fastest.
- Packaging:Beverage containment, food trays, and personal care bottles absorb the majority of African PET offtake. Egypt's Alexandria packaging cluster attracts preform converters serving North African markets with integrated resin supply from Indorama Ventures' regional PTA-PET complexes.
- Textiles:Apparel filament and industrial yarn production expands most quickly as Ethiopian and Egyptian mills pivot toward 100% rPET feedstock for export contracts bound to European retailers.
- Automotive:Under-the-hood electrical connectors and interior trim components utilize glass-reinforced PET grades.
- Electronics:Film substrates and connector housings serve regional appliance assembly operations.
Packaging maintains capacity dominance. Textiles is gaining share fastest.
Grade:
Certification tiers create pricing stratification with food-grade and recycled material commanding persistent premiums.
- Food Grade:Resin meeting CDSCO-equivalent national food safety authority standards in Kenya, Nigeria, and South Africa undergoes migration limit testing for aromatic polyester oligomers. South Africa's National Regulator for Compulsory Specifications enforces SANS 1649 packaging material standards that restrict heavy metal content, adding compliance cost layers.
- Recycled:Post-consumer flake and pellet supply concentrates in South Africa where Extrupet's closed-loop operations convert collected bottles into certified food-grade material. Kenya's ban on single-use plastics in protected areas accelerates demand for recycled-grade feedstock across East African packaging corridors.
- Industrial Grade:Non-food applications in automotive and electronics tolerate broader specification ranges at lower price points.
- Copolymer:Modified PET with isophthalic acid or cyclohexane dimethanol comonomers enhances barrier performance and processing windows.
Food Grade holds installed capacity. Recycled is climbing the fastest.
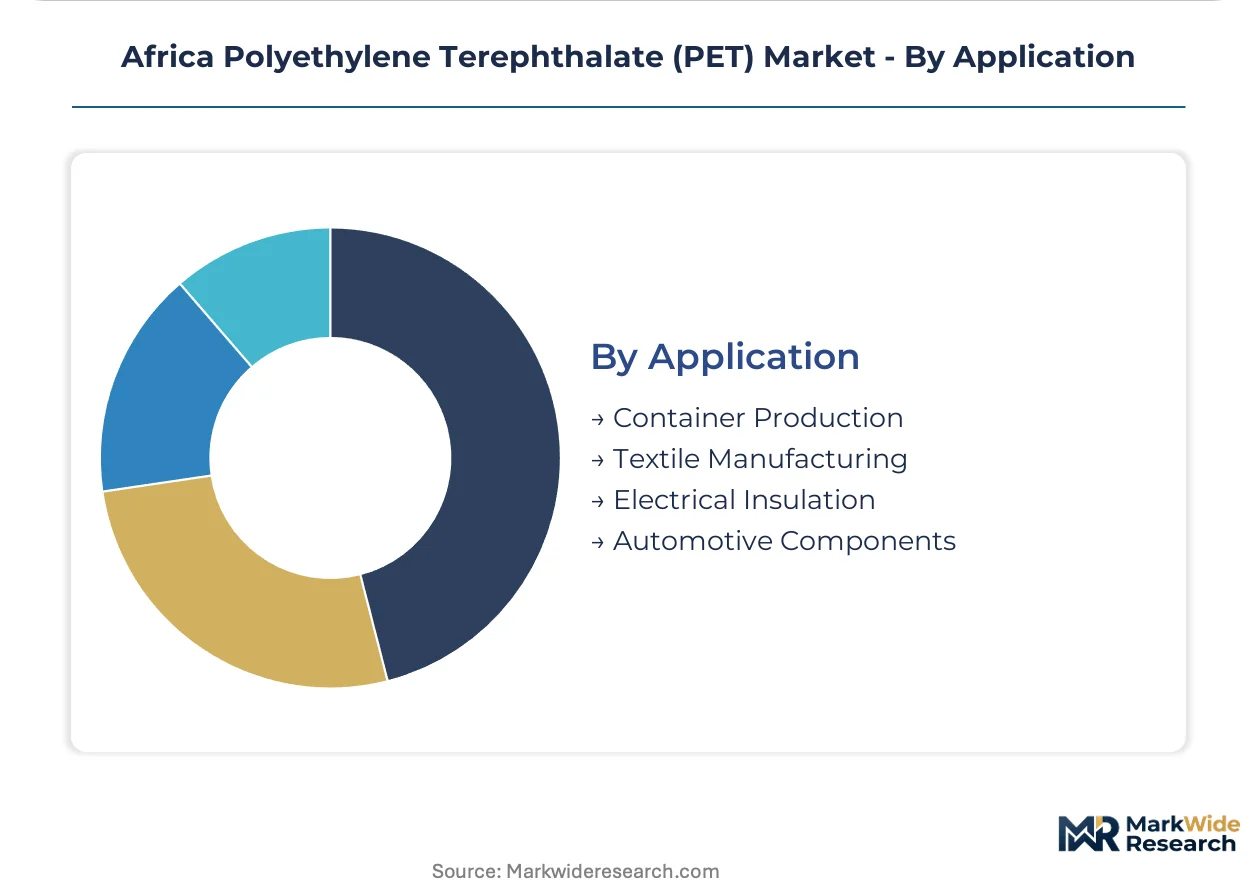
Application:
Downstream conversion economics favor container production for its scale and technical entry barriers.
- Container Production:Stretch blow molding of preforms into carbonated beverage bottles, still water containers, and hot-fill dairy packaging represents the most technically mature conversion pathway. Regional dairy processors in Southern African markets adopt food-grade bottle resin formulations for extended shelf-life products.
- Textile Manufacturing:Melt spinning of rPET chip into filament yarn for apparel and industrial applications expands with Ethiopian mill capacity additions.
- Electrical Insulation:Film and molding grades serve transformer components and cable wrapping in regional electrical infrastructure.
- Automotive Components:Glass-filled compounds withstand under-hood thermal and chemical exposure.
Container Production holds installed capacity. Textile Manufacturing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers and dairy processors concentrate PET procurement in four African markets where resin supply and regulatory frameworks diverge sharply.
Nigeria
Coca-Cola and Pepsi bottling networks anchor preform demand in the Lagos industrial corridor. The country's national food safety authority enforces migration limit testing on imported resin lots. Indorama Ventures operates integrated PTA-PET complexes that supply downstream converters with captive feedstock security.
South Africa
Regional dairy processors adopt hot-fill bottle resin formulations for extended shelf-life products. The National Regulator for Compulsory Specifications enforces SANS 1649 packaging standards restricting heavy metal content. Extrupet's closed-loop rPET operations in Gauteng dominate food-grade flake supply for preform converters.
Egypt
Textile mills pivot toward 100% rPET filament for European fast-fashion export contracts. The Egyptian Organization for Standardization applies mandatory conformity assessment on imported resin under its quality surveillance program. Alexandria's packaging cluster attracts preform converters serving North African beverage markets.
Kenya
Bottled water producers reconfigure sourcing strategies around recycled-grade feedstock requirements. The National Environment Management Authority enforces extended producer responsibility regulations obligating brand owners to finance collection infrastructure. Nairobi and Mombasa preform converters face working capital pressure from feedstock prepayment demands.
Africa Polyethylene Terephthalate (PET) Market Competitive Landscape
Player mix skews toward integrated resin producers and specialized recyclers with limited standalone converter presence. Market structure concentrates around three strategic archetypes: petrochemical conglomerates with captive aromatics supply, mechanical recyclers with closed-loop certification capabilities, and regional packaging specialists with preform-to-bottle integration. Dominant competitive moves include backward integration into PTA feedstock and geographic expansion through preform converter partnerships.
Among integrated petrochemical operators, Indorama Ventures Public Company Limited and Safripol Pty Ltd exemplify the scale-driven archetype with captive resin production. Extrupet (Pty) Ltd occupies a distinct position within the certified recycling tier, representing mechanical reclamation capabilities. These three entities anchor competitive positioning across virgin and recycled-grade supply vectors.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Safripol Pty Ltd |
| ALPLA |
| Extrupet (Pty) Ltd |
| Mpact Group Limited |
| Egyptian International Packaging |
| Polyserve Africa |
| PakPal |
| Nampak |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Indorama Ventures and Lagos corridor preform converters lock in PTA-PET resin access while anchoring price visibility against purified terephthalic acid index volatility. These arrangements concentrate procurement power among integrated producers, forcing standalone converters to absorb spot market swings or surrender margin through prepayment demands.
Pricing Analysis
Cost-plus contracts with PTA feedstock indexation dominate resin procurement between Nigerian petrochemical complexes and downstream preform converters. Price differentiation separates food-grade certified resin meeting Kenya's NEMA migration limits from industrial-grade material, with volume scale and hot-fill technical specifications as secondary tiering factors. Cost compression in standard bottle-grade resin is intensifying as Safripol's Southern African capacity expansions loosen supply. Small-scale beverage bottlers exhibit highest price sensitivity, while multinational dairy processors accept premiums for extended shelf-life formulations.
Supply Chain Analysis
Inventory buffers and extended lead times characterize resin procurement across East African packaging corridors lacking integrated PTA production. Supply concentrates in Nigeria, Egypt, and South Africa where Indorama Ventures and Safripol operate captive aromatics-to-resin complexes. Raw material flows draw from imported purified terephthalic acid, ethylene glycol, and cobalt-manganese catalyst systems. Single-source vulnerability concentrates in South Africa where Extrupet's closed-loop rPET operations dominate food-grade flake supply. Distribution runs through preform converter networks serving Coca-Cola and Pepsi bottling franchises with just-in-time delivery schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat anchored in regulatory entrenchment: Kenya's NEMA extended producer responsibility mandates and South Africa's SANS 1649 standards create compliance barriers that favor incumbent integrated producers over new resin entrants.
For Market Incumbents: Shield market position through backward integration into collection infrastructure and mechanical recycling certification. Indorama Ventures' PTA-PET complexes in Nigeria and Egypt demonstrate how captive feedstock security neutralizes PTA price volatility threats. Invest in optical sorting and flake washing technology to capture rPET premium pools as Kenya's recycled-grade mandates tighten. For New Entrants and Emerging Players: Differentiate on closed-loop waste-to-flake operations in West African corridors outside Nigeria's Lagos cluster. Underdeveloped collection networks in Ghana and Côte d'Ivoire present first-mover terrain for integrated recyclers. Target informal waste picker network partnerships as the go-to-market anchor, bypassing traditional aggregator middlemen to secure feedstock at source. For Investors and Strategic Acquirers: Capital is best deployed toward mechanical recyclers with food-grade certification pathways and preform converter partnerships. Long-term viability rests on operators positioned at the intersection of EPR enforcement and rPET content mandates. Watch for harmonized national protocols on post-consumer waste conversion to certified bottle resin as the inflection signal for scaled capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | NEMA regulations obligate brand owners to finance recovery networks, reshaping feedstock economics. |
| Food-Grade rPET Certification Investment | CDSCO-equivalent authorities in Kenya, Nigeria, and South Africa enforce migration limit testing protocols. |
| Preform Converter Partnership Expansion | Lagos and Alexandria packaging clusters attract just-in-time delivery contracts with Coca-Cola and Pepsi networks. |
| Hot-Fill Resin Formulation R&D | Southern African dairy processors adopt extended shelf-life packaging, commanding technical premiums. |
| Optical Sorting Technology Deployment | Egyptian and South African recyclers deploy near-infrared systems to achieve food-grade purity thresholds. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with resin procurement managers, preform converter operations directors, and NEMA regulatory enforcement officers; and secondary validation through customs trade records, SEC filings of listed petrochemical operators, and national standards authority publications. Bottom-up volume modeling triangulated against top-down macroeconomic drivers.
Across the projection horizon, the analytical framework segmented volume and value outputs by product form, grade certification tier, end-use industry, and regional production hub. CAGRs were derived from trend extrapolation of historical procurement patterns adjusted for EPR enforcement timelines and rPET adoption curves. Key inputs included PTA feedstock price indices, blow-molding capacity utilization rates, and textile mill filament demand from Ethiopian and Egyptian export contracts.
The analysis sits within stated boundaries; outcomes outside sustained EPR enforcement, PTA price stability, or harmonized food-grade certification protocols would require recalibration. Forecasts reflect documented assumptions about regulatory implementation pace and recycler capital deployment. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Nylon 66 Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Global Ultra-High Molecular Weight Polyethylene Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Synthetic Polymer Waxes Market