
 Vinyl Acetate Ethylene (VAE) Market | 2026-2036
Vinyl Acetate Ethylene (VAE) Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Acetate Ethylene (VAE) Market Analytics
A shift from solvent-based to water-based procurement is repositioning how formulators source VAE emulsions across the adhesives and coatings value chain. Celanese Corporation leverages its integrated acetyls chain to secure ethylene and vinyl acetate feedstock economics in North America. Wacker Chemie AG anchors European supply through specialized dispersion technology for construction adhesives. Dow Inc. competes on manufacturing scale, operating large-batch emulsion plants that serve packaging and textile converters globally.
Vinyl Acetate Ethylene denotes a copolymer synthesized from vinyl acetate and ethylene monomers, typically containing 60–95% vinyl acetate by weight and produced through emulsion polymerization at 40–90°C to yield aqueous dispersions with particle sizes of 0.1–5.0 micrometers; these dispersions serve as film-forming binders in adhesives, paints, and construction sealants where flexibility and adhesion to polar substrates prove critical. The emulsion product type dominates volume due to its direct applicability in water-based adhesives and interior paints, while powder grades command margin premiums in dry-mix mortar and cement modification. Water-based technology leads absolute consumption, though hot-melt VAE formulations gain traction in automotive interior assembly where solvent elimination meets OEM specifications.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based adhesive production, channeling investment toward water-based VAE capacity. REACH registration requirements and the EU Green Deal's embodied carbon tracking compel European manufacturers to document copolymer lifecycle emissions. China's MEE enforces stricter VOC limits in architectural coatings, favoring domestic emulsion producers with localized supply chains. Stakeholders must monitor feedstock volatility in ethylene and vinyl acetate monomers, as integrated versus merchant sourcing determines cost resilience across forecast scenarios.
Market Dynamics
Water-based VAE emulsion procurement is displacing solvent-based formulations as EPA NESHAP enforcement tightens permissible emission thresholds across adhesive manufacturing, compressing legacy capacity economics and redirecting capital toward aqueous dispersion plants.
Growth Catalysts
- REACH Registration:ECHA compliance mandates for copolymer lifecycle documentation accelerate documented low-emission formulations across European construction adhesives.
- China Infrastructure Investment:Domestic manufacturing expansion and urban development projects sustain raw material offtake for cement modification and tile adhesive applications.
- Hot-Melt Formulation Advances:Automotive interior assembly specifications favor solvent-eliminated VAE systems for dashboard lamination and trim bonding.
Market Restraints
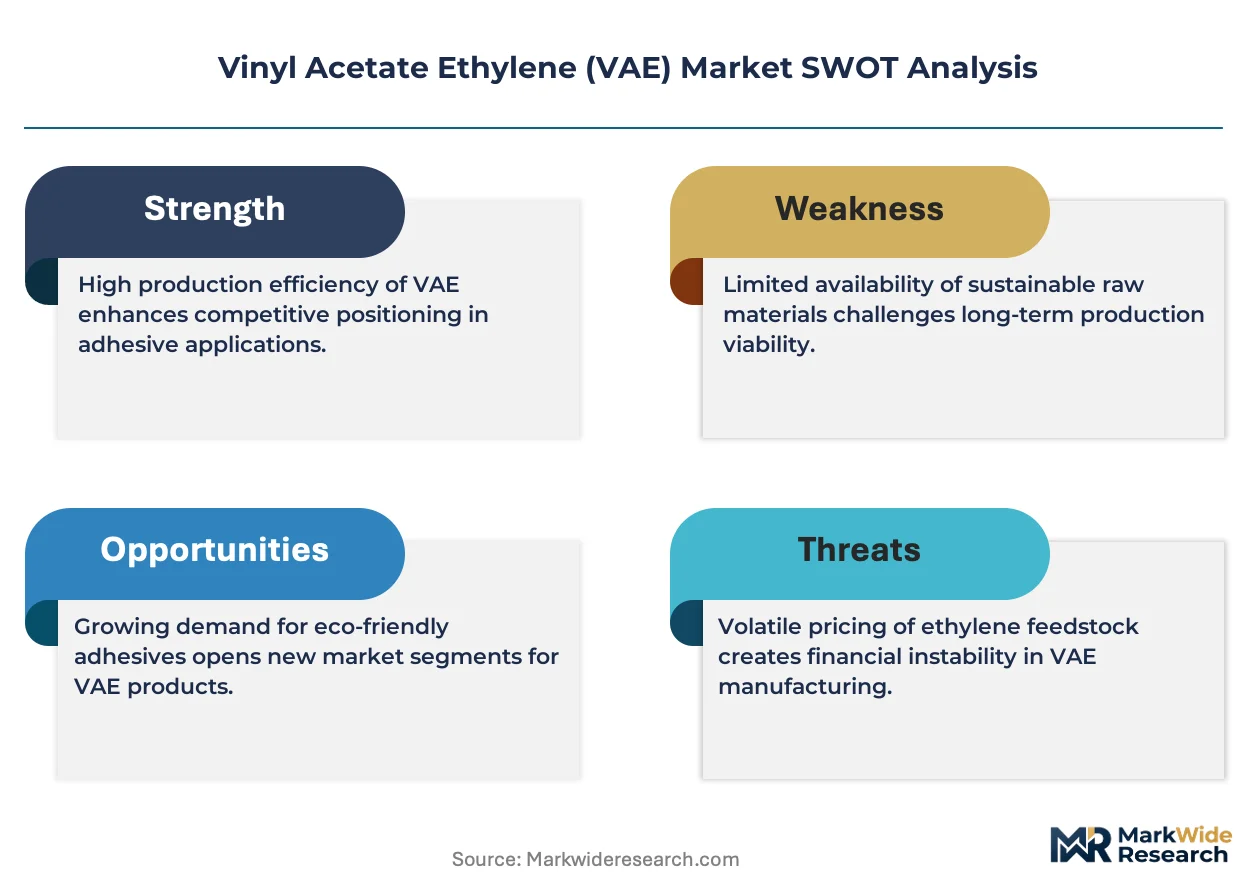
- Ethylene Feedstock Volatility:Merchant versus integrated sourcing economics determine margin resilience when naphtha-cracker output fluctuates.
- Acetic Acid Supply Concentration:Vinyl acetate monomer production clusters in select coastal Chinese and US Gulf Coast complexes, exposing formulators to single-point disruption.
- Polyurethane Substitution:Two-component PU systems compete for flexible packaging lamination where extreme moisture resistance proves mandatory.
Strategic Opportunities
- India Construction Chemicals:BIS certification requirements for dry-mix mortars create specification-driven entry points for redispersible powder grades.
- EU Green Deal Embodied Carbon Tracking:CSRD-aligned disclosure mandates reward producers with verified low-carbon emulsion polymerization processes.
- Digital Distribution Platforms:Specialized chemical marketplaces enable mid-size adhesive formulators to bypass traditional distributor markups on standard dispersion grades.
Industry Challenges
- Emulsion Polymerization Expertise Scarcity:Process engineers capable of optimizing particle size distribution for specific adhesion substrates command premium compensation.
- Multi-Jurisdictional Registration Burden:Separate dossier requirements under EPA TSCA, ECHA REACH, and China MEE new chemical notification prolong product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Acetate Ethylene (VAE) Market |
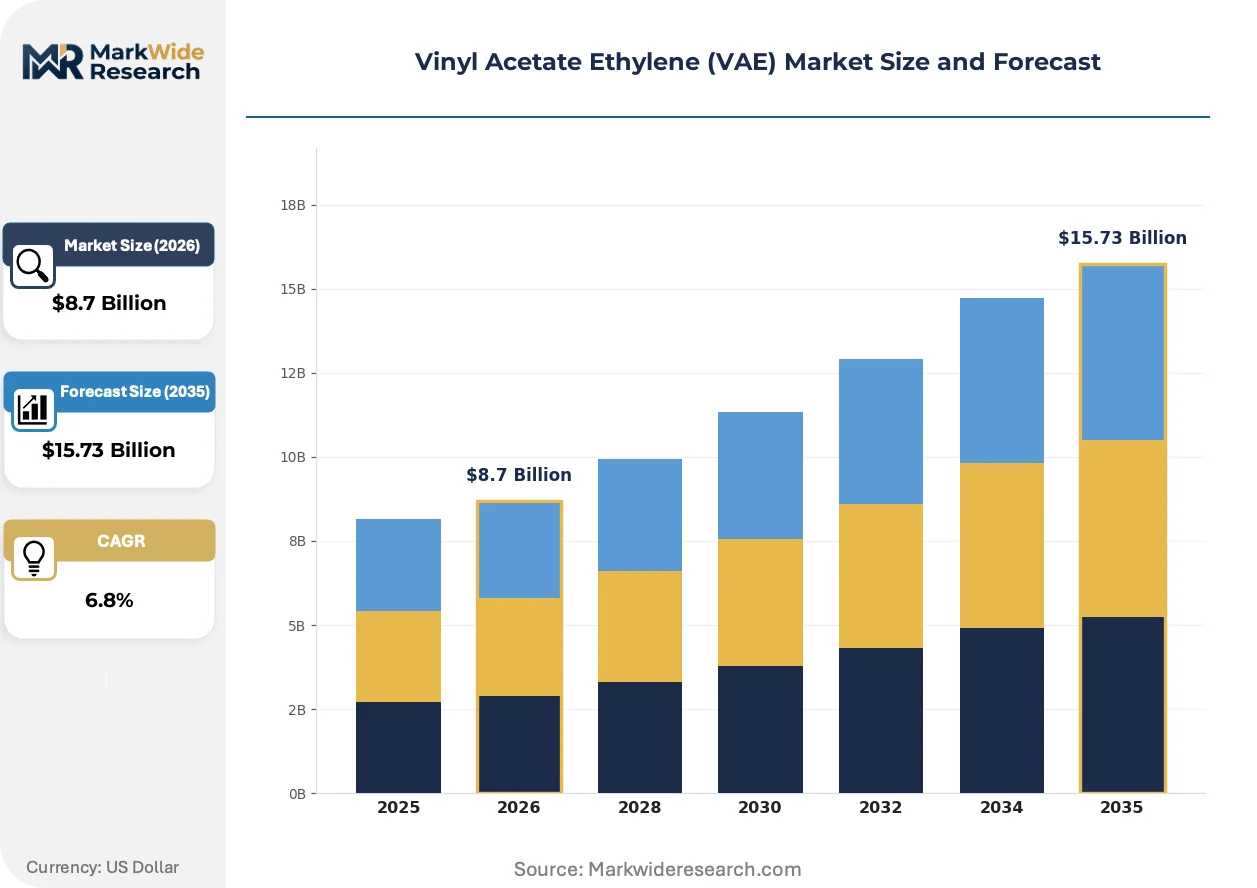
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Dispersion, Powder, Solution Application: Adhesives, Paints, Coatings, Sealants End User: Construction, Automotive, Packaging, Textile Technology: Water-based, Solvent-based, Hot-melt, Others |
| Companies Covered | Celanese Corporation, SINOPEC, ExxonMobil Corporation, Arkema SA, LG Chemical, Dow Inc., LyondellBasell Industries N.V., BASF SE, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Acetate Ethylene (VAE) Market Evolving Landscape
Formulation chemistry and compliance architecture are converging to redefine how VAE copolymers compete against acrylic and styrene-butadiene alternatives across water-based adhesive segments.
Hybrid VAE-acrylic copolymerization is unifying the flexibility of ethylene-vinyl acetate backbones with the UV stability of acrylic esters, enabling exterior paint and coating applications previously closed to pure VAE systems. Exterior architectural coating manufacturers in Germany and the Netherlands are qualifying these hybrids for facade applications. The technology is compressing the historical performance gap that segmented premium acrylics from commodity VAE in outdoor exposure categories.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is eliminating solvent-based adhesive production lines across US Midwest manufacturing corridors. Facility operators face retrofit costs or closure decisions as inspection cycles intensify. Water-based VAE capacity expansions in Texas and Louisiana are capturing displaced volume from solvent-based alkyd and chloroprene systems.
Specification-driven procurement now dominates construction adhesive selection as general contractors consolidate supplier relationships around documented low-VOC portfolios. Master specification databases from large US and German engineering firms filter out uncertified emulsion sources. China and Southeast Asia project developers increasingly mirror this pattern, embedding MEE VOC limits into tender documentation.
Vinyl Acetate Ethylene (VAE) Market Segmentation
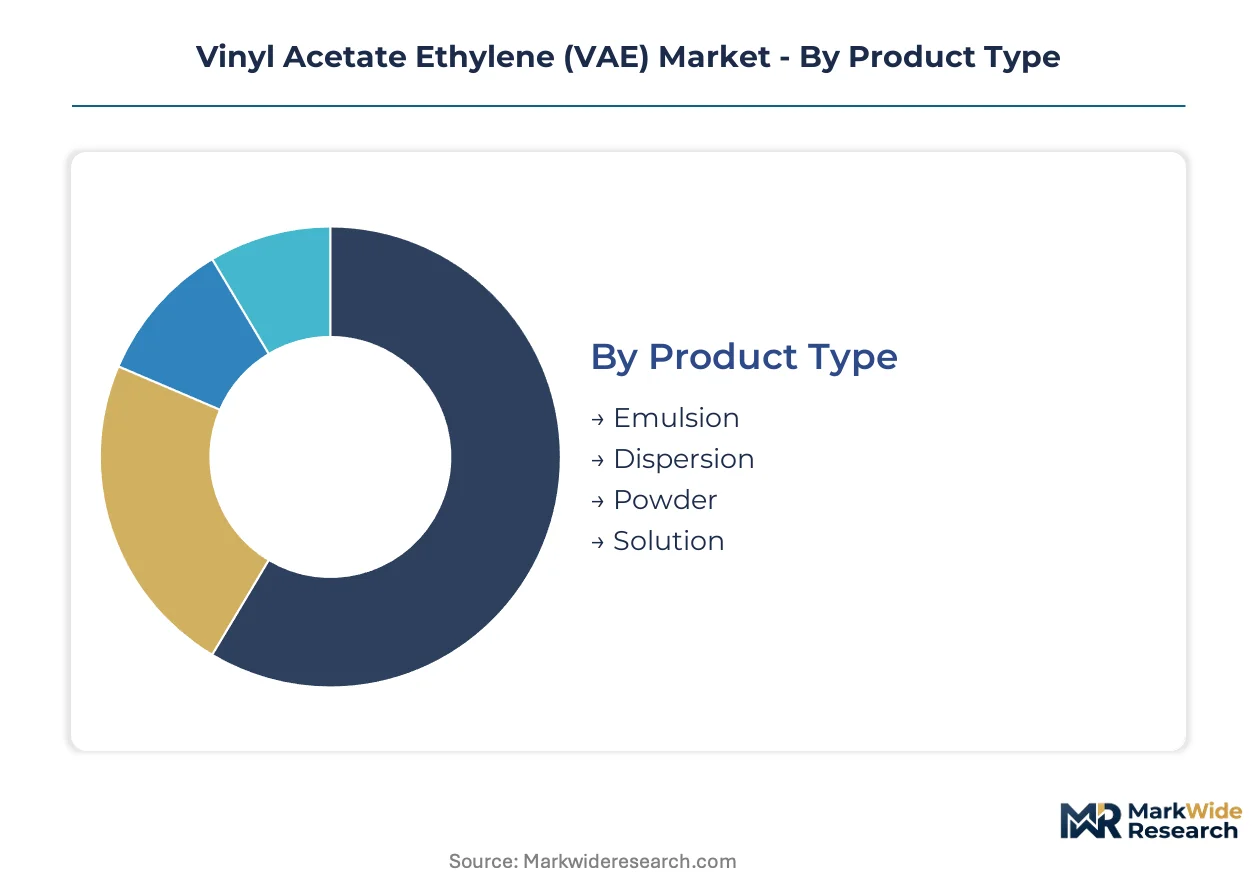
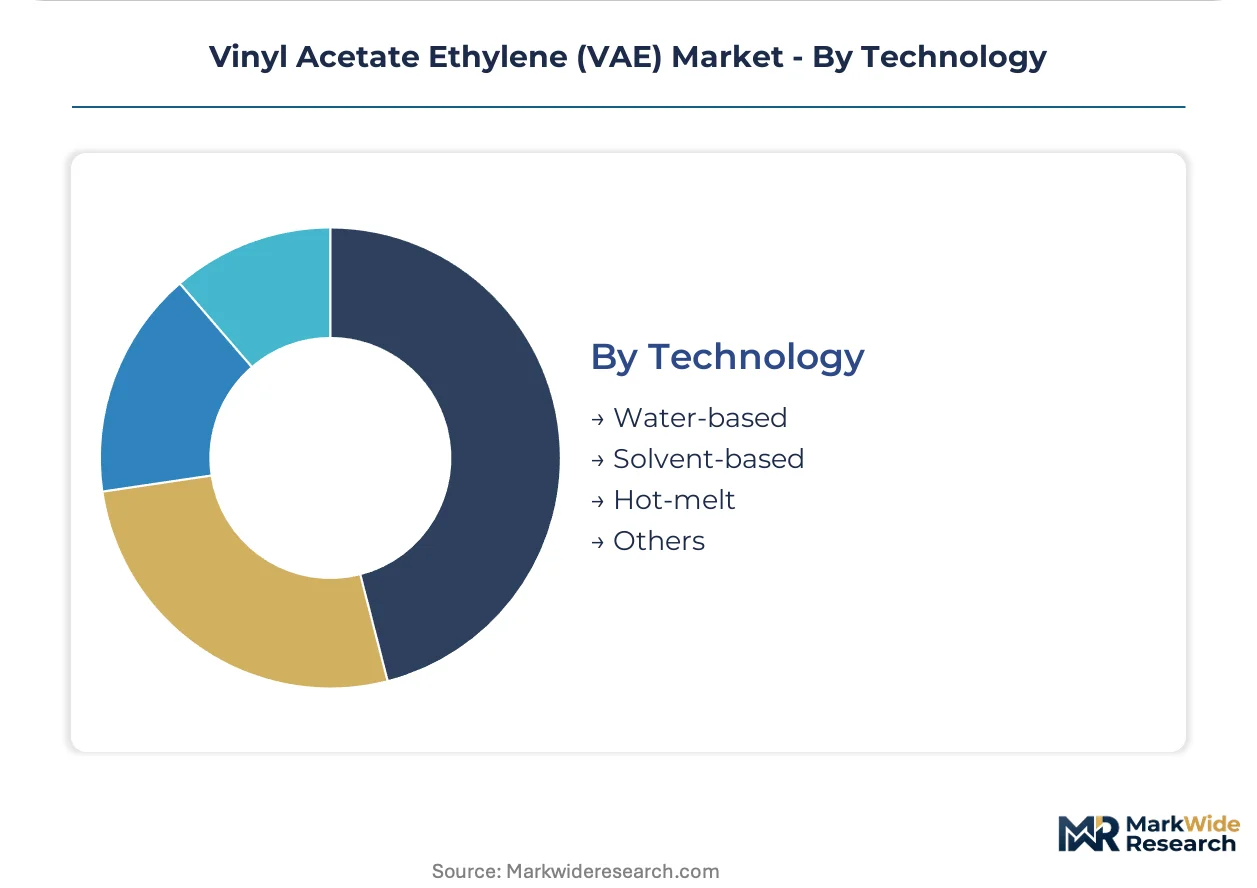
VAE copolymer architectures diverge sharply across physical form factors and formulation technologies, with each segment commanding distinct supply chain configurations and customer qualification protocols. Procurement patterns in this market track closely to end-use certification requirements rather than commodity pricing dynamics.
Product Type:
Supply concentration tilts heavily toward aqueous delivery systems, with dispersion capacity clustering around integrated monomer producers who control vinyl acetate and ethylene feedstock economics.
- Emulsion:Aqueous colloidal dispersions containing 40–60% solids by weight, stabilized with polyvinyl alcohol or surfactant systems. Construction adhesive formulators in China and Germany consume the majority of volume, driven by MEE and REACH-compliant low-VOC specifications for interior bonding applications.
- Powder:Spray-dried redispersible polymer particles designed for dry-mix mortar integration, requiring protective colloid coatings to prevent premature coalescence. Cement modification demand in India and Southeast Asia climbs fastest as BIS and local building codes mandate polymer-enhanced tile adhesives.
- Dispersion:Higher-solids liquid systems typically exceeding 55% copolymer content, optimized for industrial coating lines where transport efficiency matters.
- Solution:Solvent-dissolved VAE grades serving legacy coating applications, now contracting under EPA NESHAP and MEE enforcement pressure.
Today's leader: Emulsion. Tomorrow's challenger: Powder.
Application:
Cost tier stratification separates specification-grade construction adhesives from commodity coating binders, with certification premiums widening the gap between qualified and unqualified suppliers.
- Adhesives:Pressure-sensitive and laminating formulations exploiting ethylene-rich copolymer flexibility for polar substrate bonding. Packaging converters in the United States and automotive interior assemblers specify solvent-eliminated VAE systems to satisfy OEM sustainability scorecards.
- Coatings:Hybrid VAE-acrylic exterior paints gaining qualification in the Netherlands and Germany for facade durability previously reserved for pure acrylics.
- Paints:Interior architectural emulsions where opacity and scrub resistance trade off against raw material cost.
- Sealants:Elastomeric joint compounds for construction movement accommodation, typically formulated with higher ethylene content for low-temperature flexibility.
Adhesives dominate current procurement spend. Coatings represent the steepest expansion trajectory as hybrid technologies unlock exterior performance tiers.
End User:
Volume concentration follows infrastructure investment cycles, with construction sector offtake dwarfing specialty applications in absolute tonnage terms.
- Construction:Tile adhesives, cement modifiers, and waterproofing membranes consuming emulsion and powder grades. Chinese urban development projects and Indian affordable housing programs sustain raw material demand despite interest rate volatility.
- Packaging:Flexible film lamination and paperboard bonding where food-contact compliance narrows the qualified supplier base.
- Automotive:Dashboard lamination, headliner bonding, and interior trim assembly favoring hot-melt VAE formulations for solvent elimination.
- Textile:Nonwoven fabric binders and carpet backing applications competing with styrene-butadiene alternatives on cost-performance positioning.
Construction commands absolute volume. Automotive offers the highest formulation value per kilogram.
Technology:
Customer type segmentation separates regulatory-driven adopters from performance-driven specifiers, with compliance timelines dictating technology migration speed.
- Water-based:Emulsion polymerization yielding aqueous dispersions with particle sizes of 0.1–5.0 micrometers. EPA NESHAP enforcement and EU Green Deal embodied carbon tracking channel nearly all new adhesive capacity investment toward this technology.
- Hot-melt:Solvent-free solid formulations applied molten and setting on cooling. Automotive OEM specifications in Germany and Japan favor these systems for interior assembly where volatile elimination is mandatory.
- Solvent-based:Declining legacy technology concentrated in specialty coating applications not yet convertible to aqueous systems.
- Others:Emerging radiation-curable and reactive VAE modifications still in pilot-scale qualification.
Water-based technology anchors current supply. Hot-melt systems are gaining share fastest in premium automotive specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors VAE emulsion manufacturing capacity through integrated vinyl acetate monomer clusters serving construction adhesive formulators across East China.
China
Urban infrastructure investment and domestic manufacturing expansion sustain raw material offtake for cement modification applications. The Ministry of Ecology and Environment enforces stricter VOC limits in architectural coatings, favoring localized emulsion producers. Shanghai and Jiangsu province concentration of dispersion plants captures specification-grade demand from tile adhesive compounders.
United States
Packaging converters and automotive interior assemblers specify solvent-eliminated VAE systems to satisfy OEM sustainability scorecards. EPA National Emission Standards for Hazardous Air Pollutants enforcement eliminates legacy solvent-based adhesive production lines across Midwest manufacturing corridors. Texas and Louisiana water-based capacity expansions capture displaced volume from chloroprene and alkyd systems.
Germany
Exterior architectural coating manufacturers qualify hybrid VAE-acrylic copolymers for facade durability applications previously reserved for pure acrylics. ECHA REACH registration requirements and EU Green Deal embodied carbon tracking compel manufacturers to document copolymer lifecycle emissions. The Ruhr industrial cluster and Bavarian chemical parks anchor European dispersion technology for construction adhesives.
India
Affordable housing programs and dry-mix mortar standardization sustain powder-grade demand for cement modification. Bureau of Indian Standards certification requirements for polymer-enhanced tile adhesives create specification-driven entry points for redispersible powder grades. Gujarat and Maharashtra industrial corridors concentrate formulation capacity serving domestic infrastructure projects.
Japan
Automotive OEM specifications favor hot-melt VAE formulations for dashboard lamination and interior trim bonding where volatile elimination is mandatory. METI industrial standards guide adhesive qualification protocols for vehicle interior assembly. The Nagoya manufacturing belt and Kanto region host compounders supplying Toyota and Honda specification chains.
Vinyl Acetate Ethylene (VAE) Market Competitive Landscape
Global majors compete with regional champions across feedstock integration and dispersion technology specialization. The vendor base separates into integrated petrochemical conglomerates controlling ethylene and vinyl acetate economics, specialized European dispersion technology holders, and Asian state-affiliated producers with domestic market priority. Strategic moves concentrate on backward integration into acetyls chain assets and geographic expansion of aqueous emulsion capacity to capture EPA and MEE regulatory displacement.
Among North American integrated producers, Celanese Corporation exemplifies captive feedstock positioning through acetyls chain control. Dow Inc. occupies the scale-driven manufacturing tier with large-batch emulsion plants serving packaging converters globally. Wacker Chemie AG anchors specialized dispersion technology for European construction adhesive specifications. These three represent distinct competitive archetypes: upstream-integrated, scale-optimized, and technology-differentiated.
| Leading Market Players |
|---|
| Celanese Corporation |
| SINOPEC |
| ExxonMobil Corporation |
| Arkema SA |
| LG Chemical |
| Dow Inc. |
| LyondellBasell Industries N.V. |
| BASF SE |
| Wacker Chemie AG |
| Others |
Value Network & Pricing Analysis
Water-based emulsion polymerization technology migration simultaneously compresses legacy solvent-based cost structures and concentrates aqueous dispersion capacity among integrated vinyl acetate monomer producers in China, the United States, and Germany. EPA NESHAP enforcement and MEE VOC limits accelerate this dual shift, rewarding backward-integrated suppliers with captive ethylene feedstock economics while merchant-dependent formulators absorb margin volatility.
Pricing Analysis
Ethylene and vinyl acetate monomer cost pass-through dominates VAE pricing mechanics, with integrated producers commanding premium-mid-economy pricing differentiation against merchant-dependent competitors. Certification grade under REACH and MEE compliance tiers separates specification-grade emulsions from commodity construction adhesive binders. Pricing pressure stems from naphtha-cracker output fluctuations and acetic acid supply concentration on the US Gulf Coast and coastal China. Volume-scale buyers in Chinese tile adhesive compounding exhibit highest price sensitivity, while automotive OEMs specifying hot-melt formulations for interior assembly demonstrate lowest sensitivity due to solvent-elimination mandates.
Supply Chain Analysis
VAE emulsion supply rests on vinyl acetate monomer production clustering in China, the United States, and Germany, with ethylene feedstock drawing from regional naphtha crackers and shale gas complexes. Acetic acid, ethylene, and protective colloid stabilizers constitute critical input dependencies. Single-source vulnerability concentrates in coastal Chinese VAM complexes exposed to port logistics disruption and environmental compliance shutdowns. Distribution runs through integrated producer direct sales for large adhesive formulators, supplemented by specialized chemical distributors serving mid-size dry-mix mortar compounders in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VAE market margin expansion is accelerating through solvent-based capacity displacement and premium-tier qualification of hybrid VAE-acrylic systems for exterior architectural coatings. Hot-melt formulation advances in automotive assembly and redispersible powder standardization in Indian dry-mix mortars create additional pricing power layers.
For Market Incumbents: Hedge ethylene feedstock volatility through backward integration into acetyls chain assets or long-term offtake agreements with Gulf Coast and Yangtze River Delta monomer producers. Secure REACH and MEE certification dossiers ahead of compliance deadlines to lock specification-grade positioning in European and Chinese construction adhesive tenders. Defend against polyurethane substitution in flexible packaging by qualifying hybrid copolymer grades for moisture-resistant lamination applications. For New Entrants and Emerging Players: Begin with redispersible powder grades for India's BIS-certified dry-mix mortar segment, where specification-driven procurement creates entry barriers for unqualified suppliers but rewards documented polymer-enhanced cement modifiers. Target Gujarat and Maharashtra industrial corridors with localized technical service capabilities supporting tile adhesive compounders. Pursue digital marketplace distribution to bypass traditional chemical distributor markups on standard dispersion grades. For Investors and Strategic Acquirers: Roll-up economics work for regional emulsion specialists with captive vinyl acetate supply and MEE-compliant Chinese manufacturing footprints because regulatory displacement is compressing legacy solvent-based capacity valuations. Focus on mid-cap producers with demonstrated ECHA registration capabilities and automotive hot-melt qualification pipelines. Watch EPA NESHAP inspection cycle intensity and MEE enforcement actions as inflection indicators for accelerated water-based capacity replacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetyls Chain | Captive vinyl acetate supply insulates Celanese and Dow from naphtha-cracker margin volatility. |
| Hybrid VAE-Acrylic Copolymer Launch | Exterior facade qualification in Germany and Netherlands unlocks premium coating tier previously closed to pure VAE. |
| Redispersible Powder Capacity Expansion | BIS certification requirements in India create specification-driven entry points for cement modification grades. |
| Hot-Melt Formulation Qualification | Toyota and Honda OEM specifications favor solvent-eliminated systems for dashboard lamination. |
| Digital Distribution Platform Partnership | Specialized chemical marketplaces enable mid-size formulators to bypass traditional distributor markups. |
Research Methodology
Direct dialogue with adhesive formulators, construction chemical procurement leads, automotive interior assembly engineers, and dispersion plant technical directors grounded qualitative insights in operational reality. Secondary validation drew from ECHA REACH registration databases, EPA NESHAP enforcement records, MEE VOC compliance filings, and ACC/Cefic chemical trade statistics. Bottom-up and top-down triangulation reconciled capacity utilization data with end-use demand modeling across construction, packaging, and automotive segments.
Bottom-up volume modeling segmented demand by product type, application, technology, and end-use industry, while top-down macroeconomic anchoring tested aggregate consumption against infrastructure investment cycles and OEM specification trends. CAGRs were derived from regression analysis of historical offtake patterns and regulatory displacement timelines. Forecast inputs incorporated ethylene feedstock cost trajectories, hybrid copolymer qualification rates, and BIS certification adoption curves in Indian dry-mix mortars.
Several conditions sit outside the modeled scope, including geopolitical disruption to China-US chemical trade flows, breakthrough polyurethane adhesive formulations displacing VAE in flexible packaging, and unanticipated EPA enforcement pauses. Forecasts reflect assumptions about MEE VOC limit maintenance, REACH registration continuity, and sustained automotive OEM solvent-elimination mandates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Polyimides Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Global Nylon Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market