
 Zinc Gluconate Granules Market | 2026-2036
Zinc Gluconate Granules Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Gluconate Granules Market Insights
China is reconfiguring capacity across Hebei and Jiangsu provinces as domestic granulation facilities scale to meet pharmaceutical-grade demand. Disha Pharmaceutical Group Co., Ltd. leverages backward integration into zinc salt refining to secure raw material continuity. Nanjing Haiji Pharmaceutical Co., Ltd. anchors its position through specialized pediatric formulation expertise. Hunan Yada Pharmaceutical Co., Ltd. competes by controlling regional distribution networks across central Chinese provinces.
Zinc gluconate granules consist of a zinc salt of gluconic acid, typically standardized to deliver elemental zinc in dosages ranging from 10 mg to 25 mg per unit, produced via fluid-bed granulation or roller compaction for improved flow properties and content uniformity in downstream tableting or sachet packaging. The compound serves primarily as a bioavailable zinc source for dietary supplementation and pharmaceutical interventions targeting deficiency states, immune modulation, and wound healing protocols. Dietary Supplements represents the most mature application segment, with margin pools shifting toward Functional Foods as beverage and fortification brands seek GRAS-affirmed mineral delivery systems. The Pharmaceutical application segment sustains premium pricing through pharmacopeial certification requirements, while Veterinary Use remains fragmented with lower regulatory barriers.
China's NMPA enforces pharmacopeial standards for zinc content uniformity and microbial limits that determine market access for domestic manufacturers. The country's GB standards for food-grade mineral additives create parallel compliance tracks for suppliers serving both pharmaceutical and nutraceutical channels. India's CDSCO and BIS frameworks impose additional testing protocols on imported granule stock, shaping export qualification requirements for Chinese producers. Stakeholders must monitor evolving pharmacopeial harmonization between national regulators to anticipate reformulation investments and qualification timeline shifts.
Market Dynamics
China's NMPA pharmacopeial revisions are forcing simultaneous reformulation across pediatric zinc therapies and dietary supplement channels, compressing qualification timelines and consolidating production around certified granulation facilities.
Growth Catalysts
- Pediatric Deficiency Protocols:China's national essential medicines list expansion prioritizes zinc gluconate for childhood growth disorders, anchoring hospital procurement volumes.
- GB Standards Alignment:Food-grade mineral additive regulations now permit dual-channel pharmaceutical-nutraceutical production, unlocking formulation flexibility for certified manufacturers.
- Fluid-Bed Granulation:Continuous processing technology reduces batch-to-batch variability, satisfying content uniformity requirements for high-volume sachet packaging.
Market Restraints
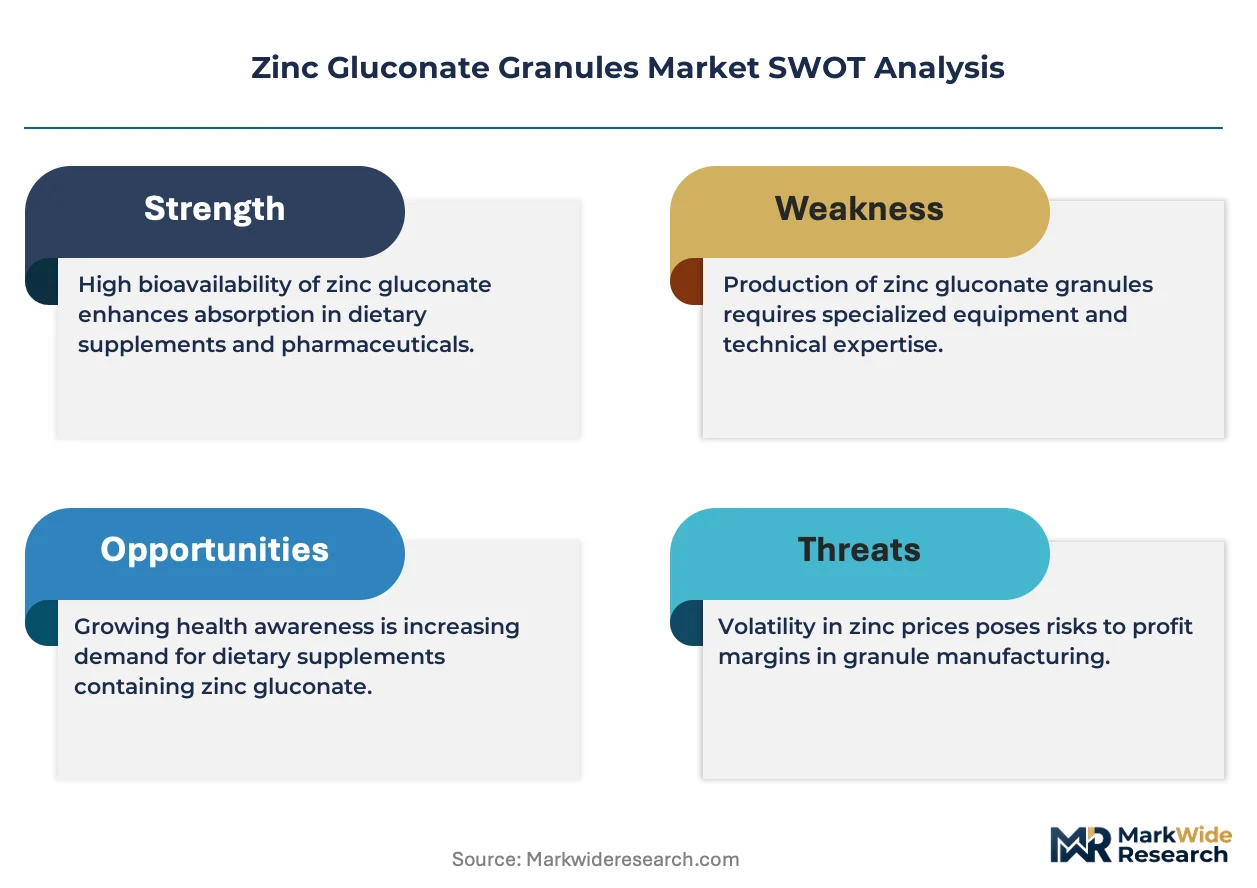
- Zinc Salt Input Volatility:Refined zinc oxide prices fluctuate with smelter output cycles, squeezing margin stability for non-integrated compounders.
- Hebei-Jiangsu Concentration:Over 60% of pharmaceutical-grade capacity clusters in two provinces, exposing supply chains to regional environmental compliance shutdowns.
- Microbial Limit Stringency:NMPA's tightened total aerobic count specifications reject batches that previously passed, elevating reject rates at smaller facilities.
Strategic Opportunities
- Central China Distribution Gaps:Hunan and Hubei provinces lack localized granulation capacity, creating first-mover advantage for regional hub investments.
- Veterinary Formulation Pivot:Livestock mineral premix regulations are loosening zinc additive restrictions, opening pharmaceutical-grade surplus absorption.
- Direct-to-Pharmacy Channels:Hospital procurement platform centralization enables bypass of traditional distributor markups for qualified suppliers.
Industry Challenges
- Pharmacopeial Harmonization Lag:Divergent zinc assay methodologies between NMPA and India's CDSCO delay export batch releases.
- Specialized Granulation Talent Scarcity:Fluid-bed process engineers command premium wages as pharmaceutical and food sectors compete for identical skill sets.
- Legacy Roller Compaction Retooling:Conversion to continuous processing demands capital outlays that mid-scale producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Gluconate Granules Market |
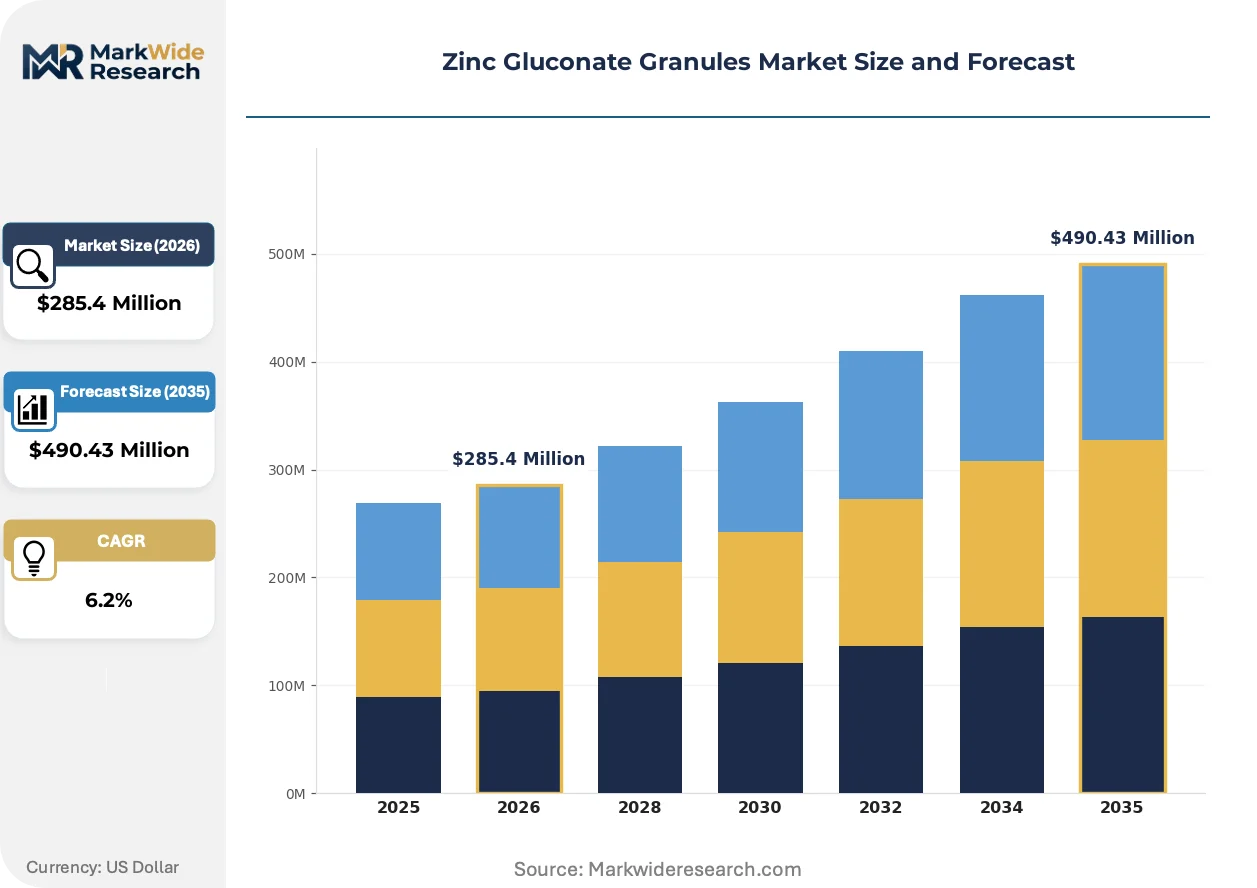
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Tablet, Liquid, Capsule Application: Dietary Supplements, Pharmaceuticals, Functional Foods, Veterinary Use Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores End User: Individuals, Healthcare Providers, Nutritionists, Veterinarians |
| Companies Covered | Disha Pharmaceutical Group Co., Ltd., Hunan Yada Pharmaceutical Co., Ltd., Nanjing Haiji Pharmaceutical Co., Ltd., Xinjiang Biochemical Pharmaceutical Co., Ltd., Shenyang Dongxin Pharmaceutical Co., Ltd., Hainan Huigu Pharmaceutical Co., Ltd., Changsha Dongfeng Pharmaceutical Co., Ltd., Shenyang Minghua Pharmaceutical Co., Ltd., Guangdong Sanshun Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Gluconate Granules Market Trends and Innovations
Granulation technology convergence with real-time release testing is collapsing traditional quality control timelines, while regulatory divergence between pharmaceutical and food channels forces parallel compliance investments.
Continuous fluid-bed granulation with process analytical technology integration is rendering obsolete batch-wise wet granulation followed by offline laboratory testing. Pediatric formulation specialists in East Asia are adopting these systems fastest, driven by sachet packaging demand for precise dose uniformity. The shift compresses manufacturing cycle times from days to hours and eliminates hold periods awaiting analytical clearance.
China's NMPA 2024 pharmacopeial supplement introduced elemental zinc assay by atomic absorption spectrophotometry as mandatory, displacing titrimetric methods for official certification. This industrial consequence elevates capital requirements for analytical infrastructure, favoring integrated manufacturers over toll granulators. The pharmaceutical segment bears the heaviest compliance burden, with facilities in Jiangsu province accelerating instrument procurement to maintain batch release authority.
Hospital procurement platform consolidation is compressing supplier bases to pre-qualified manufacturers with direct logistics capability. Traditional pharmaceutical distributors in central Chinese provinces are losing volume to platform-integrated compounders with captive delivery networks. This pattern concentrates most visibly in pediatric zinc therapies, where provincial centralized procurement mandates single-source or dual-source awards to logistics-capable bidders.
Zinc Gluconate Granules Market Segmentation
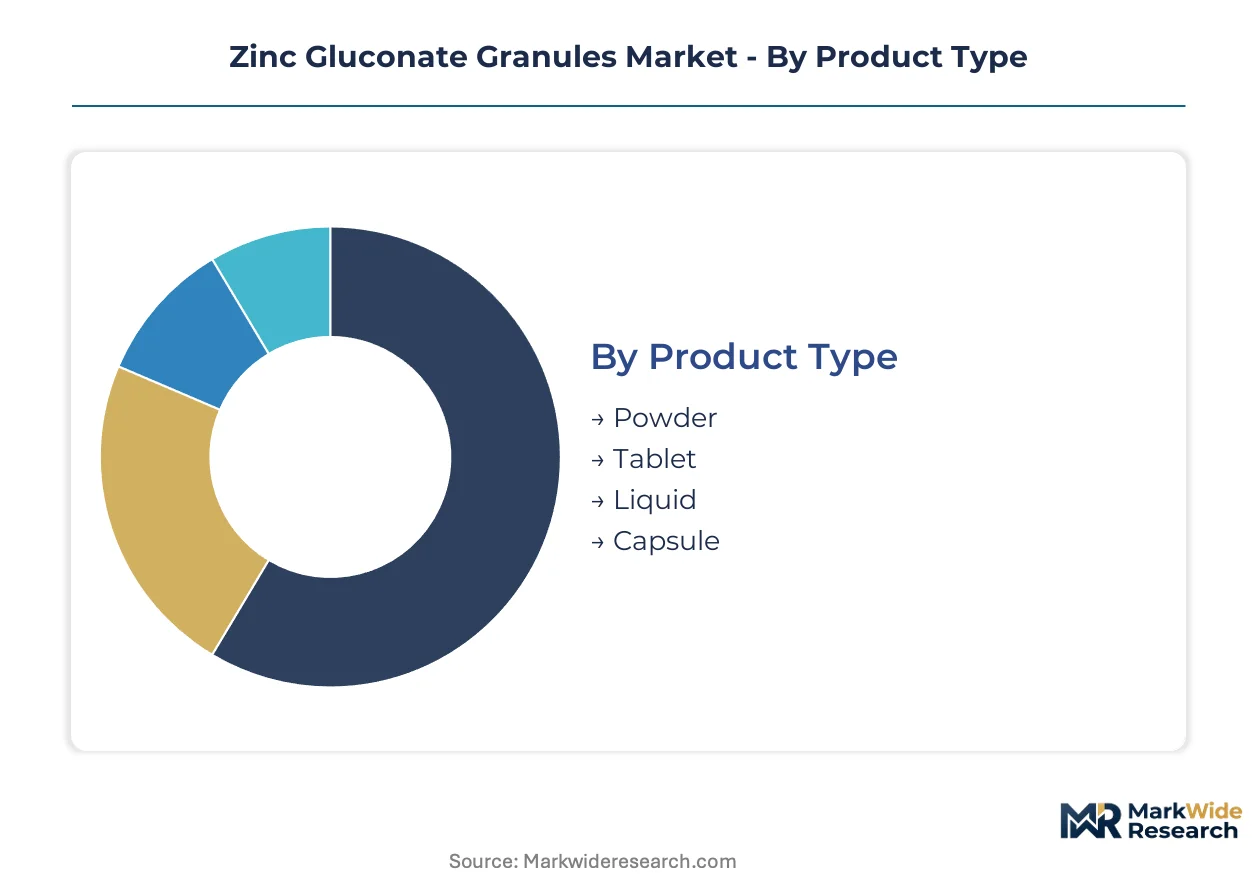
Zinc gluconate granules serve distinct formulation requirements across pharmaceutical and nutraceutical channels, with each segment demanding specific granulation specifications, content uniformity standards, and packaging formats. Segmentation clarity determines procurement strategy for buyers navigating dual pharmacopeial and food-grade compliance tracks.
Product Type:
Cycle times vary dramatically across physical formats, with liquid formulations turning inventory fastest due to shorter shelf stability, while tablet production requires extended granulation-to-coating timelines that compress working capital efficiency.
- Powder:Uncompressed zinc gluconate with particle sizes optimized for direct compression or sachet filling, typically requiring 80-120 mesh specifications for flow uniformity. Demand concentrates in Hebei province contract manufacturing facilities serving pediatric sachet brands, driven by NMPA's tightened content uniformity enforcement that rejects coarse particle distributions.
- Tablet:Compressed dosage forms requiring pre-granulation to improve compressibility and prevent capping, with hardness specifications typically 50-70 N for immediate-release pediatric formulations. Hospital procurement platforms in Jiangsu province favor tablet presentations for essential medicines list compliance, though granule-to-tablet conversion adds 48-72 hours to release timelines.
- Liquid:Suspension or solution formats bypassing solid granulation entirely, manufactured via direct dissolution of zinc gluconate in aqueous vehicles with viscosity modifiers.
- Capsule:Hard gelatin or vegetable-derived shells filled with granulated powder, requiring tighter particle size distribution than bulk powder to prevent dose variability.
Powder dominates installed base. Tablet is where expansion concentrates.
Application:
Margin tiers separate pharmaceutical-grade certification from food-grade flexibility, with the former commanding premium pricing through NMPA batch release authority while the latter competes on formulation speed and flavor masking innovation.
- Dietary Supplements:The most mature application channel, characterized by GRAS-affirmed mineral delivery systems with flexible dosing from 10-25 mg elemental zinc per serving. Functional food and beverage brands in East Asia drive reformulation velocity, seeking heat-stable granule variants for baked good fortification that withstands 180°C processing temperatures without zinc degradation.
- Pharmaceuticals:Pharmacopeial-grade production with mandatory atomic absorption spectrophotometry assay per NMPA 2024 supplement, requiring dedicated analytical infrastructure and qualified person batch release. Pediatric zinc deficiency protocols anchor hospital procurement volumes in China's national essential medicines list expansion, sustaining premium pricing despite 18-24 month qualification timelines for new suppliers.
- Functional Foods:Mineral fortification of cereals, dairy analogs, and nutrition bars with sensory-optimized granule coatings that mask metallic off-notes.
- Veterinary Use:Livestock mineral premix applications with lower regulatory barriers and price-sensitive procurement through feed compounders.
Pharmaceuticals dominates installed base. Functional Foods is where expansion concentrates.
Distribution Channel:
Channel selection determines margin capture versus volume scale, with direct hospital platform integration yielding highest per-unit returns while mass retail sacrifices margin for brand visibility and repeat purchase velocity.
- Online Retail:E-commerce platforms and direct-to-consumer subscription models with 24-48 hour fulfillment expectations. Cross-border channels into India face CDSCO import testing delays that extend delivery timelines by 15-30 days, compressing reorder frequency for Chinese exporters.
- Supermarkets:Mass-market shelf placement requiring case-ready packaging and promotional slotting fees that favor high-volume powder formats over specialized pediatric presentations.
- Pharmacies:Professional recommendation-driven sales with pharmacist counseling requirements in China's hospital-affiliated retail network.
- Health Stores:Specialty retail with trained staff and premium positioning for organic or clean-label zinc formulations.
Pharmacies dominates installed base. Online Retail is where expansion concentrates.
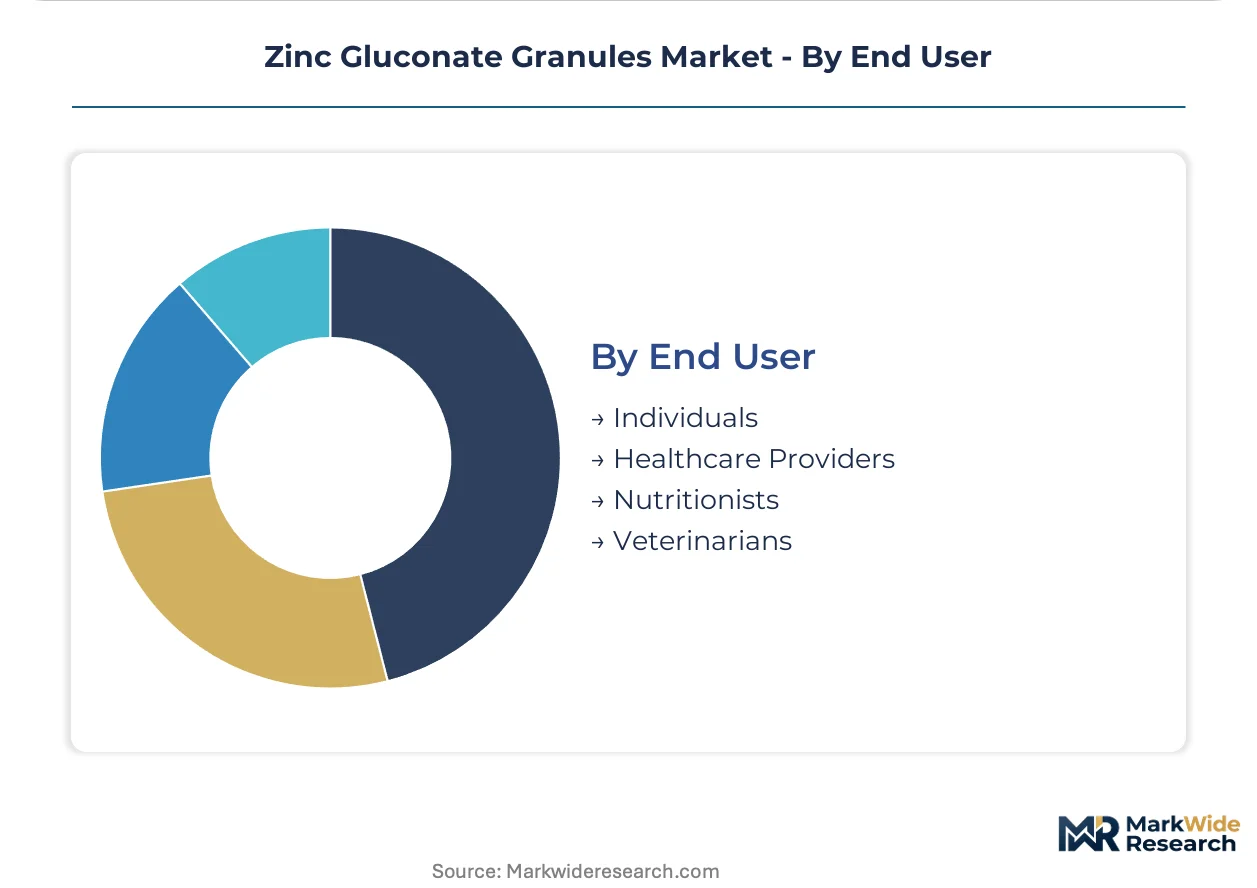
End User:
Prescription authority and formulation expertise create distinct procurement behaviors, with healthcare institutions demanding certificate of analysis documentation while individual consumers prioritize taste and convenience attributes.
- Individuals:Self-directed supplementation with preference for single-serve sachets and flavored dispersible formats. Central Chinese provinces show underpenetration versus coastal demand density, creating distribution infrastructure gaps that regional hub investments could capture.
- Healthcare Providers:Hospital and clinic prescribing with mandatory inclusion on provincial centralized procurement platforms, requiring logistics-capable bidders with direct delivery networks to bypass traditional distributor markups.
- Nutritionists:Professional counseling channel with customized dosing protocols and brand loyalty through continuing education relationships.
- Veterinarians:Livestock and companion animal practitioners with species-specific formulation requirements and bulk procurement through agricultural supply cooperatives.
Individuals dominates installed base. Healthcare Providers is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hebei and Jiangsu provinces concentrate over 60% of pharmaceutical-grade capacity, yet regional environmental compliance shutdowns expose supply vulnerabilities that manufacturers are addressing through geographic diversification.
China
Pediatric zinc deficiency therapies and national essential medicines list expansion drive hospital procurement volumes. NMPA pharmacopeial revisions mandate atomic absorption spectrophotometry assay, displacing titrimetric methods. Jiangsu province accelerates analytical infrastructure procurement to maintain batch release authority.
India
CDSCO import testing protocols extend delivery timelines for Chinese exporters by 15-30 days, compressing reorder frequency. BIS frameworks impose additional qualification requirements on granule stock. Domestic formulation demand concentrates around Mumbai and Hyderabad pharmaceutical clusters.
United States
FDA GRAS-affirmed mineral delivery systems attract functional food and beverage brands seeking heat-stable fortification variants. Dietary supplement channel maturity sustains steady powder format demand. New Jersey and California house primary import distribution nodes for Chinese-manufactured API.
Germany
EMA pharmacopeial harmonization efforts with Asian regulators shape export qualification requirements for EU-bound Chinese producers. Bavarian pharmaceutical distributors prioritize suppliers with dedicated analytical infrastructure. Munich-based formulation specialists demand precise content uniformity specifications.
Japan
PMDA standards for elemental zinc assay create parallel compliance tracks for suppliers serving pharmaceutical and nutraceutical channels. METI industrial policy supports domestic granulation technology upgrades. Osaka-Kobe pharmaceutical corridor concentrates import qualification expertise.
Zinc Gluconate Granules Market Competitive Landscape
Backward-integrated compounders and specialized pediatric formulators split the market between margin-protected supply security and clinical indication expertise. Production consolidation favors facilities with captive zinc salt refining and fluid-bed granulation capability. Three archetypes dominate: provincial champions with regional distribution control, technology-forward Jiangsu-based specialists, and Hebei-scale powder producers serving contract manufacturing demand. Competitive moves center on analytical infrastructure investment and direct hospital platform integration to bypass distributor markups.
Among Jiangsu-based specialists, Nanjing Haiji Pharmaceutical Co., Ltd. exemplifies pediatric formulation expertise, while Disha Pharmaceutical Group Co., Ltd. anchors the backward-integrated archetype through zinc salt refining control. Hunan Yada Pharmaceutical Co., Ltd. occupies a position within the provincial champion tier, leveraging central China distribution network density. These three represent distinct strategic postures: technology specialization, upstream supply security, and geographic channel dominance.
| Leading Market Players |
|---|
| Disha Pharmaceutical Group Co., Ltd. |
| Hunan Yada Pharmaceutical Co., Ltd. |
| Nanjing Haiji Pharmaceutical Co., Ltd. |
| Xinjiang Biochemical Pharmaceutical Co., Ltd. |
| Shenyang Dongxin Pharmaceutical Co., Ltd. |
| Hainan Huigu Pharmaceutical Co., Ltd. |
| Changsha Dongfeng Pharmaceutical Co., Ltd. |
| Shenyang Minghua Pharmaceutical Co., Ltd. |
| Guangdong Sanshun Pharmaceutical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Zinc oxide smelter output volatility determines both the spread between pharmaceutical-grade and food-grade pricing tiers and the geographic clustering of granulation capacity around captive salt refining assets. NMPA pharmacopeial enforcement compresses margin pools at non-integrated compounders while rewarding backward-integrated producers with pricing power during raw material spikes.
Pricing Analysis
NMPA's 2024 pharmacopeial supplement dictates the pricing tier structure by mandating atomic absorption spectrophotometry infrastructure that only certified facilities can amortize across batch volumes. Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeial-grade pediatric formulations from GRAS-affirmed nutraceuticals and veterinary-grade surplus. Cost compression in the standard tier is intensifying because Hebei-Jiangsu concentration exposes smaller compounders to environmental compliance shutdowns. Healthcare providers show least price sensitivity due to essential medicines list procurement mandates, while individual consumers in central provinces drive economy-tier volume.
Supply Chain Analysis
Export-control scrutiny on pharmaceutical-grade mineral processing equipment limits technology transfer to Indian and Southeast Asian granulation facilities, tethering capacity expansion to domestic Chinese engineering capabilities. Supply draws from China, India, and Germany, with refined zinc oxide sourcing from Australian and Peruvian concentrate. Single-source vulnerability concentrates in Hebei province environmental regulatory actions that idle 60% of pharmaceutical-grade capacity simultaneously. Distribution runs through hospital procurement platforms that disintermediate traditional pharmaceutical distributors in Jiangsu and central Chinese provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery anchored to pediatric zinc deficiency protocol expansion on China's national essential medicines list, with hospital procurement volumes providing demand floor stability through regulatory commitment cycles.
For Market Incumbents: Harden analytical infrastructure investments against NMPA assay methodology shifts that disqualify titrimetric-reliant competitors. Deepen backward integration into zinc salt refining to insulate margin pools from smelter output volatility. Lock direct hospital platform integration to bypass distributor markups before provincial procurement centralization completes. For New Entrants and Emerging Players: Central China distribution gaps in Hunan and Hubei provinces represent the most penetrable entry point for regional hub investments with captive logistics networks. Veterinary formulation pivot opportunities absorb pharmaceutical-grade surplus as livestock mineral premix regulations loosen. Target fluid-bed granulation technology licensing from Jiangsu-based engineering specialists to compress qualification timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated compounders with pharmacopeial batch release authority and direct platform logistics capability. Long-term viability across the 5-10 year window rests on regulatory harmonization between NMPA and CDSCO frameworks that determine export market access. Watch CDSCO import testing protocol streamlining as the inflection signal for Chinese exporter margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Salt Refining | Disha Pharmaceutical Group secures raw material continuity against smelter output cycles. |
| Fluid-Bed Granulation Technology Upgrade | Nanjing Haiji Pharmaceutical compresses batch release timelines from days to hours. |
| Direct Hospital Platform Integration | Hunan Yada Pharmaceutical bypasses distributor markups in central China procurement. |
| Atomic Absorption Spectrophotometry Infrastructure | Jiangsu province facilities maintain NMPA batch release authority post-2024 supplement. |
| Veterinary Formulation Pivot | Livestock mineral premix channels absorb pharmaceutical-grade surplus volume. |
Research Methodology
A standing panel of pediatric formulation specialists, hospital procurement managers, zinc salt refining engineers, and NMPA regulatory affairs consultants provided ongoing calibration across the study period. Primary interviews with pharmaceutical manufacturing executives and central China distribution channel partners combined with secondary validation from NMPA pharmacopeial supplements, CDSCO import testing protocols, and customs trade data for zinc gluconate API. Bottom-up facility capacity assessments and top-down essential medicines list procurement volume estimates were triangulated for convergence.
Scenario-bracketing around NMPA enforcement intensity and zinc oxide price volatility bands shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application channel, distribution format, and provincial regulatory cluster. CAGRs were derived from facility capacity expansion announcements, hospital procurement platform award data, and pediatric deficiency protocol adoption curves. Forecast inputs incorporated fluid-bed granulation technology penetration rates and pharmacopeial harmonization progress between Asian regulators.
Stress conditions across zinc concentrate supply disruptions, NMPA microbial limit stringency escalations, and CDSCO import testing timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around continued pediatric protocol prioritization and granulation technology adoption trajectories. Cross-checking against provincial hospital procurement platform award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Bromine Market
Bulk Chemicals
Maleic Anhydride Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Castor Wax Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Gluconic Acid Market