
 Ammonium Nitrate Market | 2026-2036
Ammonium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Nitrate Market Analysis
The mining explosives sector is pivoting toward higher-density prilled formulations as open-pit operations deepen in Australia and Southeast Asia. CF Industries Holdings Inc. leverages its North American natural gas feedstock advantage to sustain cost leadership in fertilizer-grade output. Yara International ASA anchors European supply through its integrated ammonia-nitrate network, while Orica Limited dominates explosives application technology in hard-rock mining.
Ammonium nitrate is a white crystalline salt with the chemical formula NH₄NO₃, produced through the neutralization of nitric acid with ammonia and typically containing 34% nitrogen by weight; it serves primarily as a high-nitrogen fertilizer and as the oxidizer core in industrial explosives. Prilled product commands the largest volume share due to its free-flowing handling properties and compatibility with mechanized spreading equipment, though solution forms are gaining traction in liquid fertilizer blending operations. The agriculture application segment retains structural depth through recurring seasonal demand cycles, while mining explosives generates premium pricing through specialized density and oil-absorption specifications.
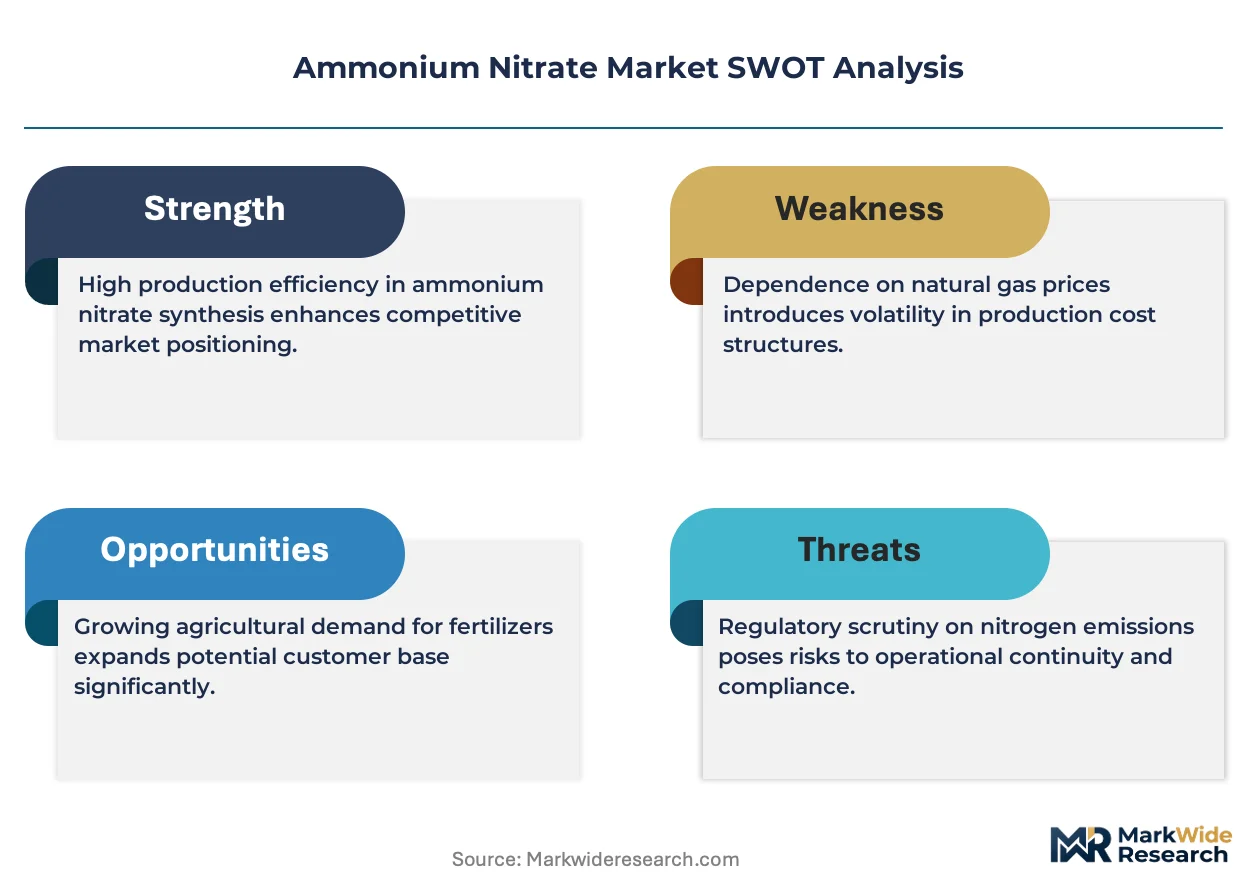
The EPA regulates ammonium nitrate storage security under the Chemical Facility Anti-Terrorism Standards, while the EU REACH framework mandates registration and hazard communication for imported fertilizer materials; these requirements shape facility siting decisions and cross-border trade documentation burdens. OSHA process safety management rules further constrain US manufacturing uptime through rigorous mechanical integrity audits. Stakeholders must weigh feedstock cost volatility against regulatory compliance capital requirements when evaluating greenfield capacity additions.
Market Dynamics
Natural gas price volatility is compressing fertilizer-grade margins while EU F-Gas Regulation and REACH compliance frameworks are forcing capital reallocation toward emissions abatement and purity certification. Mining explosives demand in Australia and Indonesia is absorbing excess prilled capacity, creating cross-segment arbitrage opportunities.
Growth Catalysts
- EU F-Gas Regulation:Stringent purity mandates for fertilizer-grade imports are accelerating facility upgrades at major European ports, tightening supply quality thresholds and favoring integrated producers with in-house testing capabilities.
- Australian surface blasting:Open-pit iron ore and coal operations are deepening extraction horizons, driving procurement of higher-density prilled formulations optimized for wet-hole blasting conditions.
- Brazil's Cerrado intensification:Soybean producers are escalating nitrogen application rates on converted savanna soils, anchoring seasonal demand spikes that absorb South American import volumes.
Market Restraints
- Natural gas feedstock volatility:Ammonia production costs swing with Henry Hub and TTF pricing, eroding margin predictability for merchant nitrate producers without long-term gas contracts.
- Black Sea supply concentration:Ukrainian and Russian ammonium nitrate export disruptions have concentrated available volumes through Turkish and Egyptian transshipment hubs, elevating freight cost exposure.
- Calcium ammonium nitrate substitution:EU fertilizer buyers are partially substituting straight ammonium nitrate with calcium ammonium nitrate to reduce detonation risk and satisfy storage insurance requirements.
Strategic Opportunities
- Indonesian mining corridor:Nickel laterite and bauxite operations in Sulawesi and Halmahera are underpenetrated by explosives application technology providers, opening service-contract entry points.
- US IRA clean ammonia incentives:Section 45Q carbon capture credits and hydrogen hub funding are creating pathways for low-carbon ammonium nitrate production with differentiated premium positioning.
- Liquid fertilizer blending:Urea-ammonium nitrate solution demand from precision agriculture operators is converging with irrigation system digitization, enabling direct-to-farm distribution bypassing wholesale cooperatives.
Industry Challenges
- Process safety management audits:OSHA mechanical integrity requirements are constraining US manufacturing uptime, forcing extended turnaround schedules that compress effective annual production days.
- REACH registration timelines:EU fertilizer importers face 12-18 month hazard communication documentation delays, freezing supplier qualification processes and stranding working capital in pre-approval inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Nitrate Market |
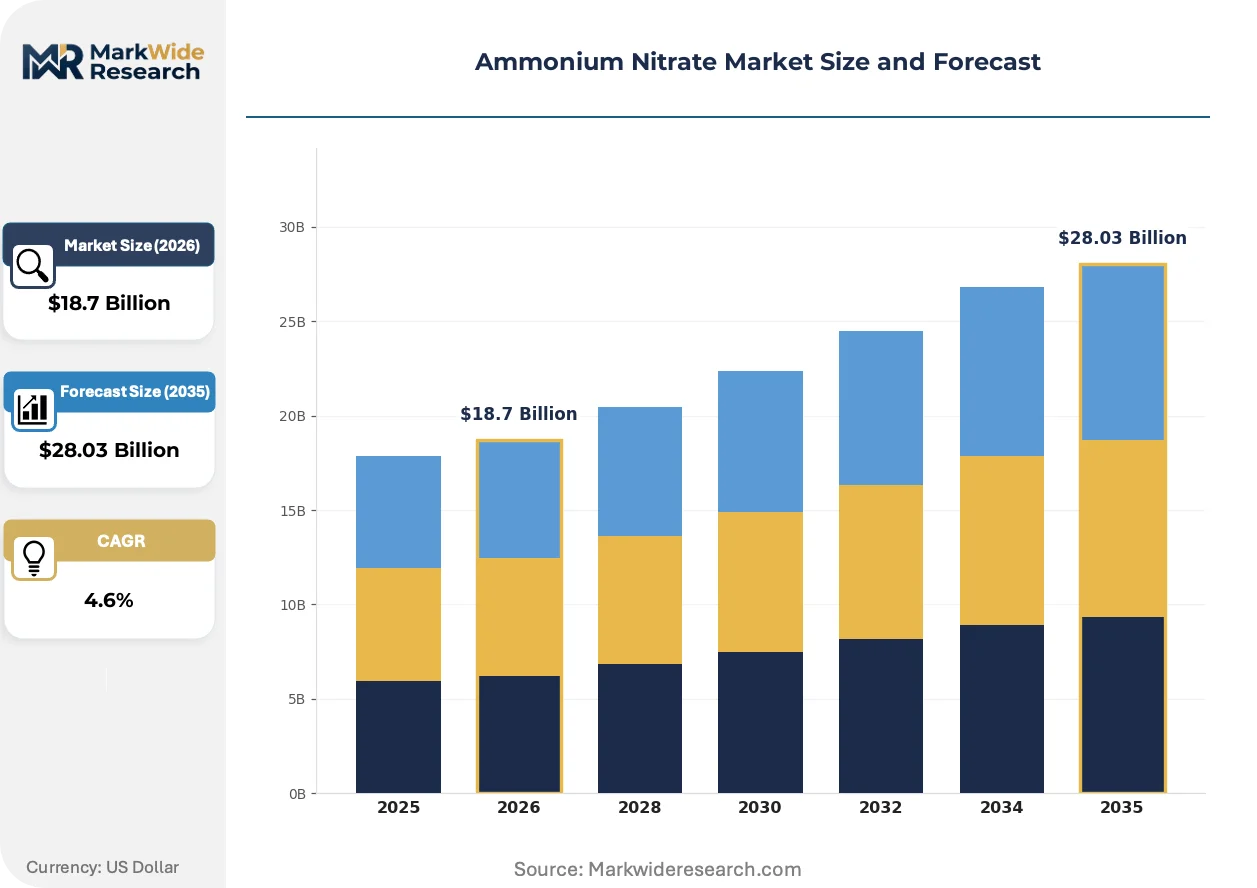
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Prilled, Solution, Liquid Application: Agriculture, Mining, Explosives, Fertilizers End User: Chemical Industry, Agriculture Sector, Construction, Food Industry Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | CF Industries Holdings Inc., Yara International ASA, URALCHEM JSC, EuroChem Group AG, Orica Limited, Incitec Pivot Limited, Austin Powder Company, Enaex SA, San Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Nitrate Market Emerging Trajectories
Emissions monitoring integration and explosives density engineering are reshaping competitive differentiation. Producers are racing to embed carbon accounting into supply chains while mining customers demand blast optimization through real-time down-hole sensing.
Encapsulated emulsion blasting agents are decentralizing explosives manufacturing by enabling on-site sensitization at remote mine locations. Hard-rock operators in Western Australia and northern Canada are adopting mobile mixing units to reduce transport of high-density precursor materials. This technology is decentralizing supply chain risk away from centralized prilled production hubs toward distributed manufacturing nodes.
EU REACH framework amendments on fertilizer impurity thresholds are forcing third-country exporters to install dedicated purification trains. The industrial consequence is a bifurcation between REACH-registered supply chains and non-compliant parallel trade. Fertilizer-grade imports into Rotterdam and Hamburg are most affected, with Brazilian and Australian buyers now demanding equivalent purity documentation to preempt future regulatory alignment.
Buyer concentration among multinational mining houses is compressing explosives procurement cycles from annual tenders to quarterly price reviews. Tier-1 operators in Chilean copper and Pilbara iron ore are unbundling supply contracts from technical services, forcing explosives vendors to compete on material pricing alone. This behavior is most visible in Australian iron ore, where BHP and Rio Tinto have separated blasting design from product supply.
Ammonium Nitrate Market Segmentation
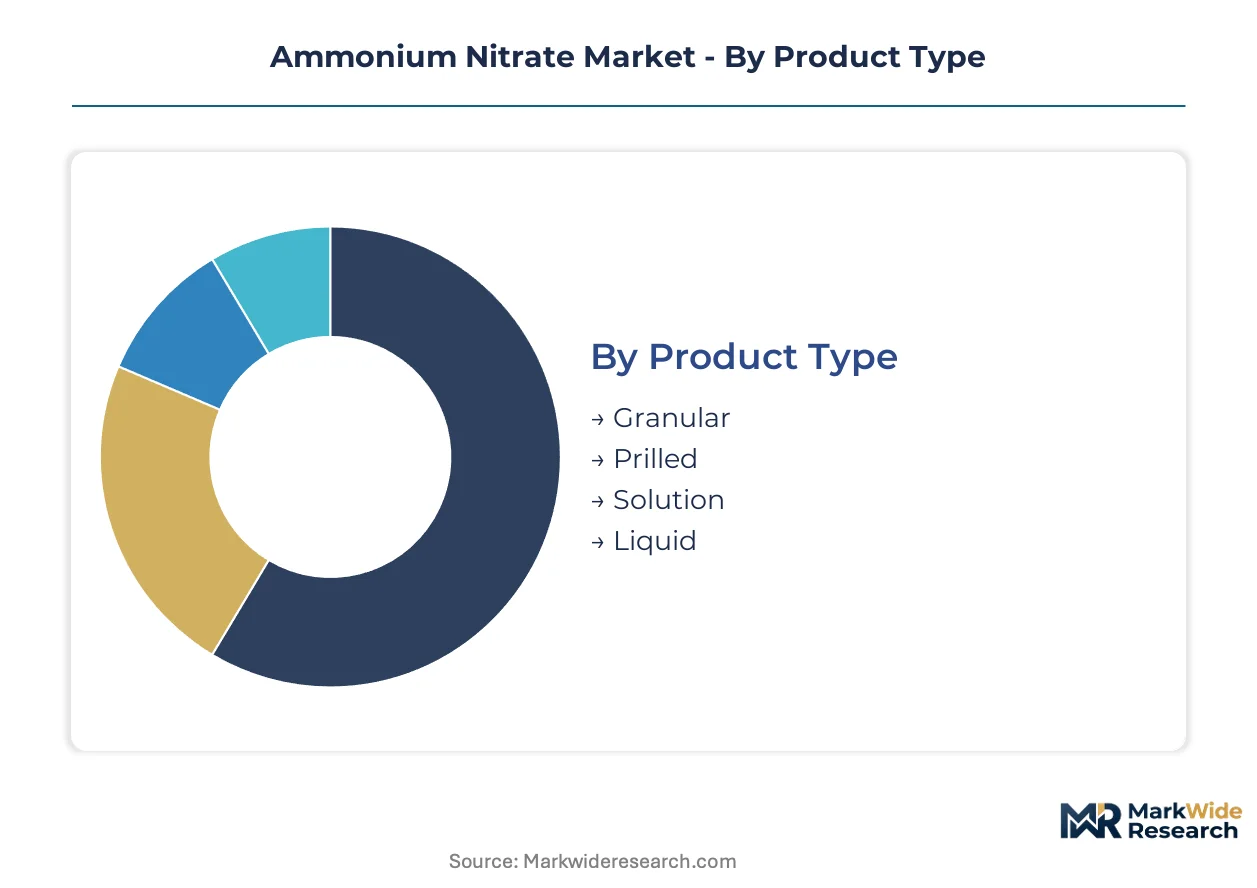
Ammonium nitrate's dual role as fertilizer feedstock and explosives oxidizer creates divergent certification pathways across segments. Product specifications, end-use registration, and channel access rights vary sharply between agricultural and industrial applications, forcing producers to maintain parallel compliance systems.
Product Type:
REACH registration burdens fall heaviest on prilled and granular forms destined for EU fertilizer markets, while solution grades face lighter documentation under downstream mixture exemptions. Explosives-grade prills trigger additional OSHA Process Safety Management audits in US manufacturing facilities.
- Prilled:Spherical beads manufactured through spray-drying towers, optimized for free-flowing bulk handling and mechanized spreading equipment. Australian iron ore and Indonesian nickel laterite mines are absorbing premium-density prilled volumes for wet-hole blasting, with BHP and Rio Tinto unbundling supply contracts from technical services. Leading the category by volume: Prilled. Growing fastest: Solution.
- Granular:Larger, irregular particles produced via drum or pan granulation, offering slower dissolution rates preferred in controlled-release fertilizer formulations. Brazil's Cerrado soybean belt drives seasonal procurement of granular grades for broadcast application on converted savanna soils.
- Solution:Urea-ammonium nitrate blends in aqueous form, gaining traction among precision agriculture operators integrating liquid injection with drip irrigation systems. US Section 45Q carbon capture credits are creating pathways for low-carbon solution production with differentiated premium positioning.
- Liquid:High-concentration formulations requiring specialized storage and handling infrastructure, primarily deployed in industrial processing and niche explosives manufacturing.
Prilled product dominates explosives procurement cycles, while solution forms are climbing fastest through precision agriculture digitization.
Application:
Margin structures diverge sharply: agriculture trades on feedstock cost efficiency, mining explosives commands premium pricing through density and oil-absorption specifications, and fertilizer-grade volumes absorb regulatory compliance capital.
- Fertilizers:Straight nitrogen applications and compound NPK blends, subject to EU F-Gas Regulation purity mandates and REACH import documentation. Brazilian buyers now demand equivalent purity documentation to Rotterdam and Hamburg standards, preempting future regulatory alignment.
- Mining:Surface blasting and underground excavation, where encapsulated emulsion technologies are decentralizing manufacturing toward remote mine sites. Western Australian hard-rock operators adopt mobile mixing units to reduce transport of high-density precursor materials.
- Explosives:Industrial and military ordnance applications, regulated under EPA Chemical Facility Anti-Terrorism Standards for storage security and OSHA mechanical integrity requirements constraining US manufacturing uptime.
- Agriculture:Direct crop nutrition applications, experiencing partial substitution by calcium ammonium nitrate among EU buyers seeking reduced detonation risk and favorable storage insurance terms.
Fertilizer applications anchor volume throughput, while mining explosives generates the steepest expansion trajectory through Australian and Indonesian surface blasting demand.
End User:
Procurement concentration varies by sector: multinational mining houses compress explosives cycles to quarterly reviews, while agricultural offtake remains fragmented across cooperative networks.
- Agriculture Sector:Broadacre crop producers and specialty farming operations, with nitrogen application rates intensifying on Brazil's Cerrado converted savanna soils.
- Chemical Industry:Downstream nitrate derivative manufacturing, requiring consistent feedstock quality for explosives precursor and industrial chemical synthesis.
- Construction:Quarrying and infrastructure excavation, absorbing mid-density prilled grades for controlled blasting in populated areas.
- Food Industry:Limited food-grade applications as a processing aid, subject to stringent purity certification beyond standard fertilizer specifications.
The agriculture sector commands the largest volume share, with chemical industry offtake expanding most quickly through explosives precursor demand.
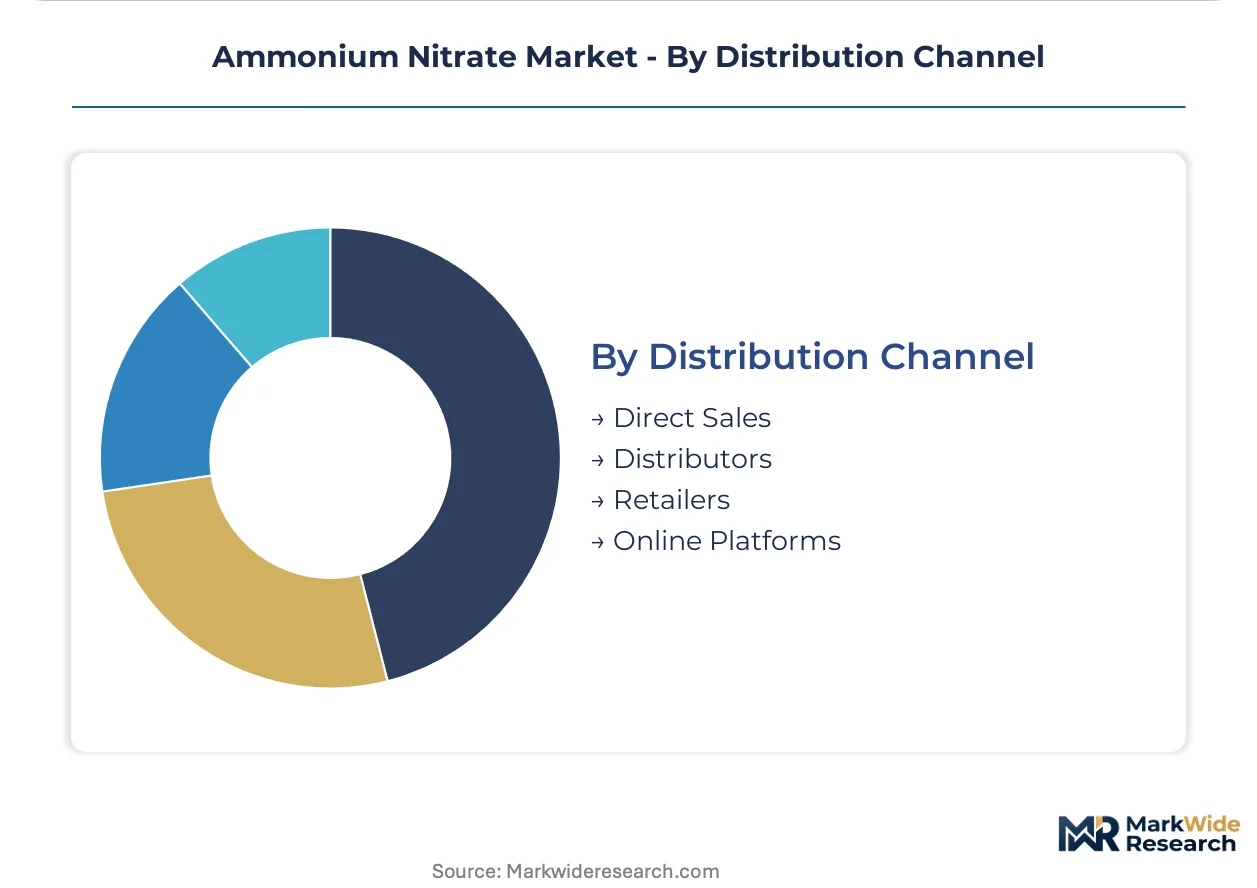
Distribution Channel:
Channel economics reflect cargo security requirements: explosives-grade movements demand chain-of-custody documentation, while fertilizer volumes flow through conventional bulk logistics.
- Distributors:Wholesale cooperatives and agricultural supply houses, historically dominating Brazilian and Australian fertilizer offtake but facing disintermediation from precision agriculture direct-to-farm models.
- Direct Sales:Large-account mining contracts with BHP, Rio Tinto, and Chilean copper operators, now unbundling blasting design from product supply to force pure material pricing competition.
- Retailers:Farm supply stores and regional agricultural merchants, serving fragmented smallholder demand with bagged and packaged formats.
- Online Platforms:Emerging digital procurement channels for standardized fertilizer grades, constrained by hazardous materials shipping regulations and insurance limitations.
Distributor networks retain structural depth in agricultural segments, while direct sales channels gain share fastest through mining procurement rationalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Russia and Ukraine while consumption concentrates in Brazil and Australia, creating freight-intensive trade flows across the Black Sea and Pacific corridors. This geographic mismatch shapes inventory positioning and margin capture for merchant traders.
Australia
Pilbara iron ore operators and Queensland coal mines absorb premium-density prilled volumes for wet-hole blasting in deepening open-pit horizons. EPA Chemical Facility Anti-Terrorism Standards govern storage security at Port Hedland and Newcastle import terminals. Perth-based explosives application specialists deploy mobile mixing units to remote Western Australian hard-rock sites.
Brazil
Soybean producers in the Cerrado agricultural belt escalate nitrogen application rates on converted savanna soils, anchoring seasonal demand spikes. ANVISA and Ministry of Agriculture regulations mandate import documentation for fertilizer-grade materials entering Santos and Paranaguá ports. Mato Grosso and Goiás states concentrate mechanized spreading operations for granular formulations.
Indonesia
Nickel laterite and bauxite operations in Sulawesi and Halmahera drive procurement of ammonium nitrate fuel oil blends for surface blasting. The country's national mining regulator imposes explosive precursor tracking requirements across the mineral processing corridor. Sulawesi's Morowali Industrial Park hosts underpenetrated demand for explosives application technology providers.
Germany
EU F-Gas Regulation and REACH compliance frameworks tighten purity thresholds for fertilizer-grade imports through Rotterdam and Hamburg transshipment hubs. ECHA registration mandates 12-18 month hazard communication documentation for third-country exporters. The Rhine-Ruhr industrial cluster maintains ammonia-nitrate integration for domestic fertilizer blending.
United States
Section 45Q carbon capture credits and hydrogen hub funding create pathways for low-carbon ammonium nitrate production with differentiated premium positioning. OSHA Process Safety Management rules constrain manufacturing uptime through rigorous mechanical integrity audits. Gulf Coast ammonia producers leverage Henry Hub natural gas feedstock advantages for cost-competitive nitrate output.
Ammonium Nitrate Market Vendor Landscape
Top-tier vendors anchor integrated ammonia-nitrate production, while regional specialists compete on explosives application technology and distribution proximity. The vendor base stratifies across three archetypes: natural gas-advantaged fertilizer producers, mining-focused explosives technology providers, and regional trading houses managing Black Sea supply disruptions. Dominant competitive moves include backward integration into ammonia feedstock and geographic expansion through port terminal acquisitions.
Among North American integrated producers, CF Industries Holdings Inc. exemplifies the natural gas-feedstock archetype, while Orica Limited occupies a position within the explosives technology tier. Yara International ASA represents the European integrated network model. These three anchors demonstrate how feedstock access, regulatory compliance capabilities, and end-use specialization partition competitive advantage across the value chain.
| Leading Market Players |
|---|
| CF Industries Holdings Inc. |
| Yara International ASA |
| URALCHEM JSC |
| EuroChem Group AG |
| Orica Limited |
| Incitec Pivot Limited |
| Austin Powder Company |
| Enaex SA |
| San Corporation |
| Others |
Supply Flow & Price Mechanics
Skilled ammonia plant operators concentrated along the US Gulf Coast and Rhine-Ruhr corridor command wage premiums that widen spreads between standard and premium fertilizer-grade tiers. Labor-cost differentials between integrated producers and merchant importers amplify pricing stratification across REACH-registered and non-compliant supply chains.
Pricing Analysis
Margin tightening in fertilizer-grade tiers reflects Henry Hub and TTF natural gas volatility eroding cost predictability for non-integrated producers. Contract-based long-term offtake dominates mining explosives procurement, while spot transactions govern agricultural fertilizer volumes. Price differentiation hinges on REACH certification status and density specifications for wet-hole blasting. Agricultural cooperatives exhibit highest price sensitivity; Australian iron ore operators demonstrate lowest sensitivity due to unbundled technical service contracts.
Supply Chain Analysis
Direct-to-mine service contracts handle explosives demand from BHP and Rio Tinto, while bulk vessel charters move fertilizer-grade volumes through Rotterdam and Santos. Production gravity centers on Russia, Ukraine, and the US Gulf Coast, with ammonia feedstock drawn from stranded gas fields and shale basins. Supply chain risk concentrates in Black Sea transshipment disruptions through Turkish and Egyptian hubs. Distribution runs through port terminal operators with integrated storage and blending capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ammonium nitrate sector is consolidating as REACH compliance burdens and natural gas cost volatility force sub-scale merchant producers toward exit or acquisition.
For Market Incumbents: Hedge feedstock exposure through long-term Henry Hub contracts or backward integration into ammonia production. Incumbents should deepen explosives application technology capabilities to resist unbundling pressure from Australian mining houses. Prioritize port terminal acquisitions at Rotterdam and Santos to control import bottlenecks. For New Entrants and Emerging Players: Mobile explosives service providers represent the most penetrable channel partner type for Indonesian nickel laterite and bauxite corridors. New entrants should target Sulawesi and Halmahera mining districts with encapsulated emulsion blending units. A technical service-first go-to-market angle bypasses commodity pricing wars with established prilled suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with integrated ammonia-nitrate producers possessing REACH registration and Gulf Coast gas access given IRA clean ammonia incentives. Acquisition targets should demonstrate captive feedstock supply and explosives technology IP. Watch for EU F-Gas Regulation amendments tightening purity thresholds as the inflection signal for margin expansion at compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia | Captive natural gas feedstock locks in cost advantage against merchant competitors at Henry Hub pricing. |
| REACH Registration Investment | ECHA-compliant hazard documentation opens Rotterdam and Hamburg fertilizer import channels to premium tier capture. |
| Mobile Emulsion Blending Deployment | On-site sensitization units reduce transport risk for Western Australian hard-rock mining customers. |
| Port Terminal Acquisition | Control of Santos and Paranaguá storage assets secures Brazilian Cerrado agricultural belt distribution. |
| Carbon Capture Retrofit | Section 45Q credit eligibility positions US Gulf Coast output for low-carbon premium differentiation. |
Methodological Framework
Document review covered trade customs databases, ECHA registration filings, and SEC 10-K disclosures from integrated producers, complemented by interviews with ammonia plant managers, mining procurement officers at Australian iron ore operators, fertilizer cooperative purchasing leads, and explosives application engineers. Secondary validation drew from EPA Chemical Facility Anti-Terrorism Standards guidance, EU F-Gas Regulation amendments, and IEA energy price data. Bottom-up volume builds and top-down market sizing were triangulated against capacity utilization rates across Black Sea and US Gulf production clusters.
Output models generated volume trajectories across prilled, granular, and solution product forms; fertilizer, mining, and explosives applications; and distributor versus direct sales channels throughout the projection horizon. CAGRs were derived from regression against natural gas price scenarios and mining capex cycles. Industry-specific inputs included Australian iron ore pit deepening schedules and Brazilian soybean nitrogen application intensity curves.
Caveats apply where Black Sea supply disruptions, OSHA Process Safety Management audit enforcement, or EU REACH timeline delays could materially shift the outlook. Forecasts reflect documented assumptions on feedstock cost trajectories and regulatory implementation pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Hypophosphite Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Nitric Acid Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Mexico Calcium Carbonate Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Asia-Pacific Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Global Concentrated Nitric Acid Market
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
Phosphorus Market
Bulk Chemicals
Meta Tartaric Acid Market
Bulk Chemicals
Saudi Arabia Sodium Thiosulphate Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Granular Urea Market