
 Insect Cell Lines Market | 2026-2036
Insect Cell Lines Market Size, Share, and Industry Trends Forecast 2026-2036
Insect Cell Lines Market Foresight
Baculovirus-mediated protein expression is rewriting the economics of recombinant biologics manufacturing. Thermo Fisher Scientific Inc. leverages its Gibco media portfolio to dominate upstream workflow supply. Lonza Group AG anchors its position through custom cell-line engineering services for viral vector programs. WuXi Biologics competes aggressively on manufacturing scale, operating one of Asia's largest single-use bioreactor networks for insect-based production.
Insect cell lines are continuous cultures derived from lepidopteran species, typically Spodoptera frugiperda (Sf9, Sf21) or Trichoplusia ni (High Five), engineered to express heterologous proteins via baculoviral vectors at post-translational modification capacities exceeding bacterial systems. Expression systems and cell lines command the largest revenue share due to their irreplaceable role in vaccine antigen and gene therapy vector manufacturing. CRISPR-edited insect platforms represent the fastest-growing technology segment, as pharmaceutical companies and contract research organizations adopt precision-edited lines to shorten development timelines and reduce batch variability in protein expression campaigns.
The FDA and EMA govern biologics master file submissions for insect-derived products, while China's NMPA enforces Good Manufacturing Practice standards for viral vector production that directly shape facility qualification requirements. The WHO prequalification pathway for vaccines produced in insect systems creates additional compliance benchmarks for emerging-market suppliers. Stakeholders must monitor how regulatory convergence on adventitious-agent testing protocols affects platform selection between insect and mammalian expression systems.
Market Dynamics
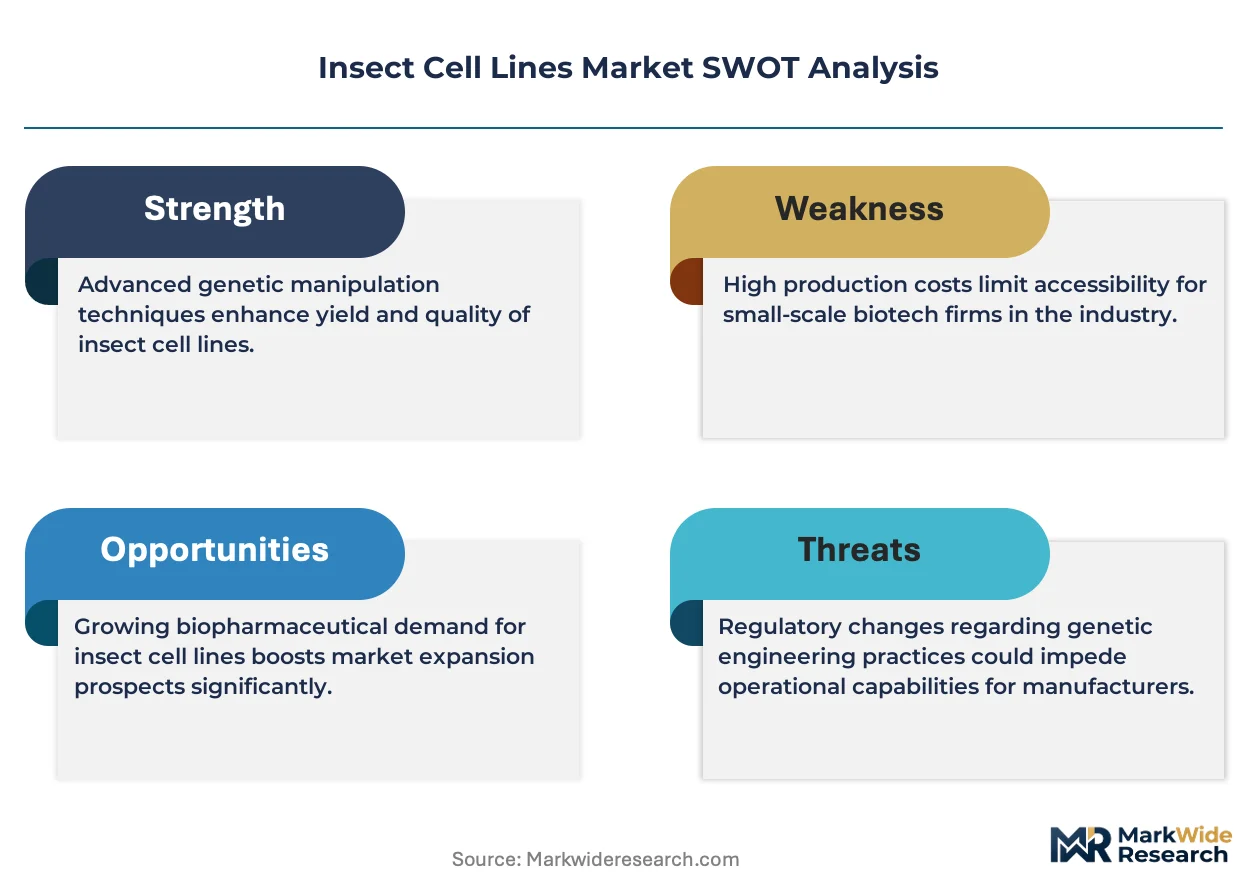
CRISPR-edited insect platforms are compressing protein expression timelines from months to weeks, forcing contract manufacturers to retool facilities or lose viral vector programs to precision-engineered competitors.
Growth Catalysts
- FDA biosimilar pathway expansion:Streamlined master file submissions for non-mammalian expression systems accelerate IND-to-approval cycles for vaccine antigens.
- Gene therapy vector demand:AAV and lentiviral production requirements from CAR-T developers pull capacity toward baculovirus-based manufacturing.
- Spodoptera frugiperda platform maturation:Decades of Sf9/Sf21 process knowledge reduce regulatory risk for new entrants versus novel mammalian lines.
Market Restraints
- Fetal bovine serum price volatility:Serum-dependent culture media expose COGS to agricultural commodity swings, squeezing margin at contract manufacturing organizations.
- Single-source baculoviral vector supply:Concentrated intellectual property around optimized AcMNPV strains creates licensing bottlenecks for independent cell-line developers.
- Post-translational modification gaps:Insect systems lack mammalian glycosylation machinery, disqualifying platforms from antibody-dependent cellular cytotoxicity biologics.
Strategic Opportunities
- India vaccine manufacturing expansion:CDSCO capacity-building incentives for indigenous viral vector production create first-mover advantages for Sf21 facility qualification.
- Continuous perfusion bioreactor convergence:Integration of single-use perfusion systems with baculoviral infection protocols enables 10x density improvements over batch culture.
- WHO prequalification acceleration:Prequalification pathway maturation for insect-derived vaccines opens procurement channels to Gavi and UNICEF tender programs.
Industry Challenges
- Adventitious agent testing complexity:Extended qPCR and electron microscopy validation timelines for insect-specific pathogens delay lot release by 3-6 weeks versus mammalian platforms.
- Cross-contamination protocols:Shared multi-product facilities require segregated air handling and single-use bioreactor dedication that inflates capital intensity per square foot.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insect Cell Lines Market |
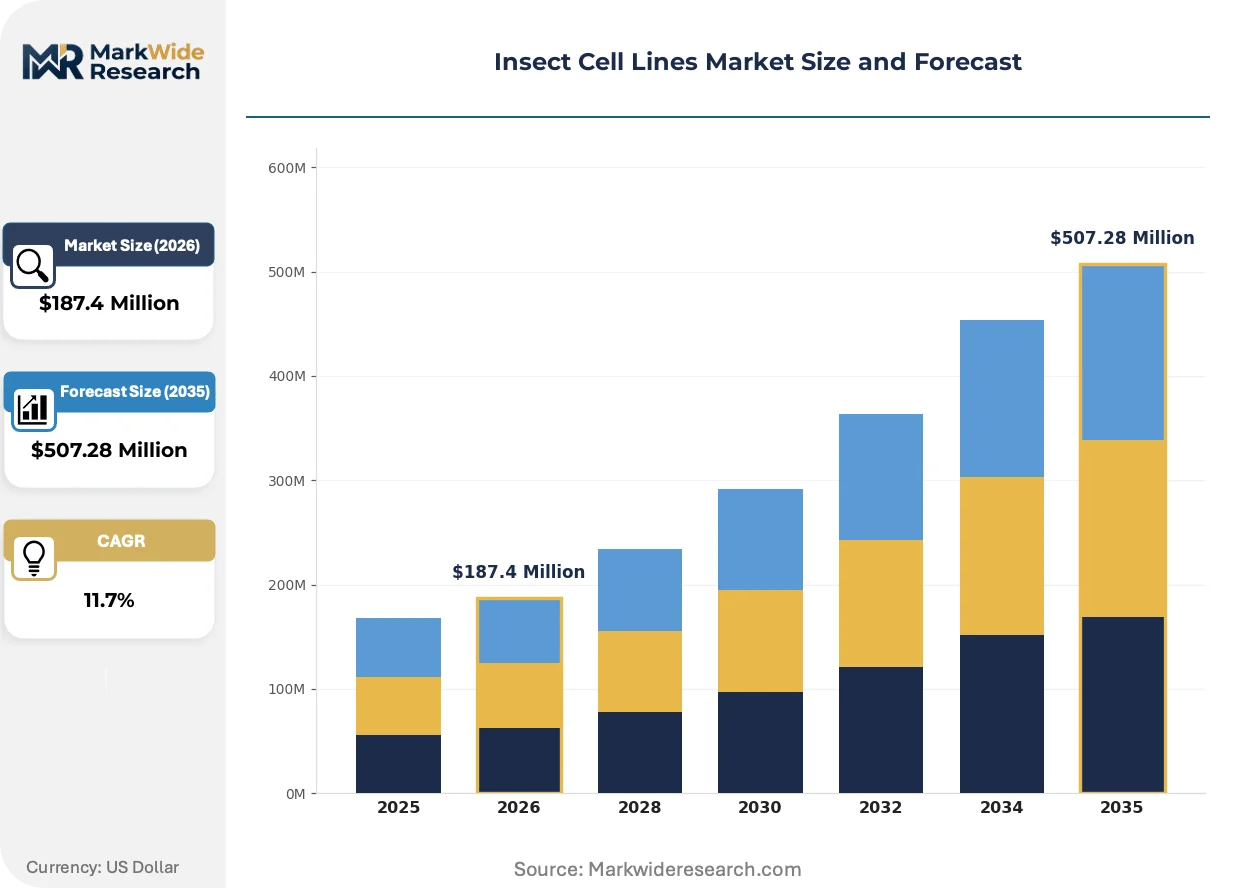
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expression Systems, Culture Media, Cell Lines, Transfection Reagents Application: Biopharmaceutical Production, Vaccine Development, Gene Therapy, Protein Expression Technology: Insect-Specific Baculovirus, CRISPR, Transgenic Technology, Hybridoma End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Sartorius AG, Lonza Group AG, Expression Systems LLC, GE Healthcare, Charles River Laboratories, GenScript Biotech Corporation, WuXi Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insect Cell Lines Market Shifts & Advancements
Protein expression workflows are fragmenting into modular, platform-agnostic architectures that decouple cell-line engineering from manufacturing execution. This decomposition enables plug-and-play substitution between insect, mammalian, and microbial systems based on product-specific glycosylation requirements.
CRISPR-Cas9 knock-in technology is migrating from research tool to production standard. Contract development organizations deploy precision-edited High Five lines with humanized glycosylation pathways. Large-molecule developers now specify edited substrates in RFPs, compressing vendor qualification to 8-12 weeks versus 18-24 months for wild-type line adaptation. The technology is migrating from academic collaboration to locked-in supply agreements with penalty clauses for expression titer shortfalls.
EMA's revised guideline on quality aspects for recombinant proteins manufactured in insect cells tightens adventitious agent documentation requirements. Facilities must now submit whole-genome sequencing data for baculoviral master seeds alongside traditional safety testing. German and Swiss contract manufacturers are consolidating testing partnerships with specialized sequencing providers to meet the December 2025 compliance deadline without internal infrastructure buildout.
Biopharmaceutical procurement teams are unbundling cell-line development from manufacturing services. Large sponsors now license edited Sf9 lines directly from platform technology holders, then tender manufacturing capacity separately. This disintermediation exposes pure-play contract manufacturers to price compression while rewarding vertically integrated suppliers with recurring royalty streams. The shift is most visible in United States gene therapy programs, where 60% of 2024 viral vector RFPs specified customer-owned cell lines.
Insect Cell Lines Market Segmentation
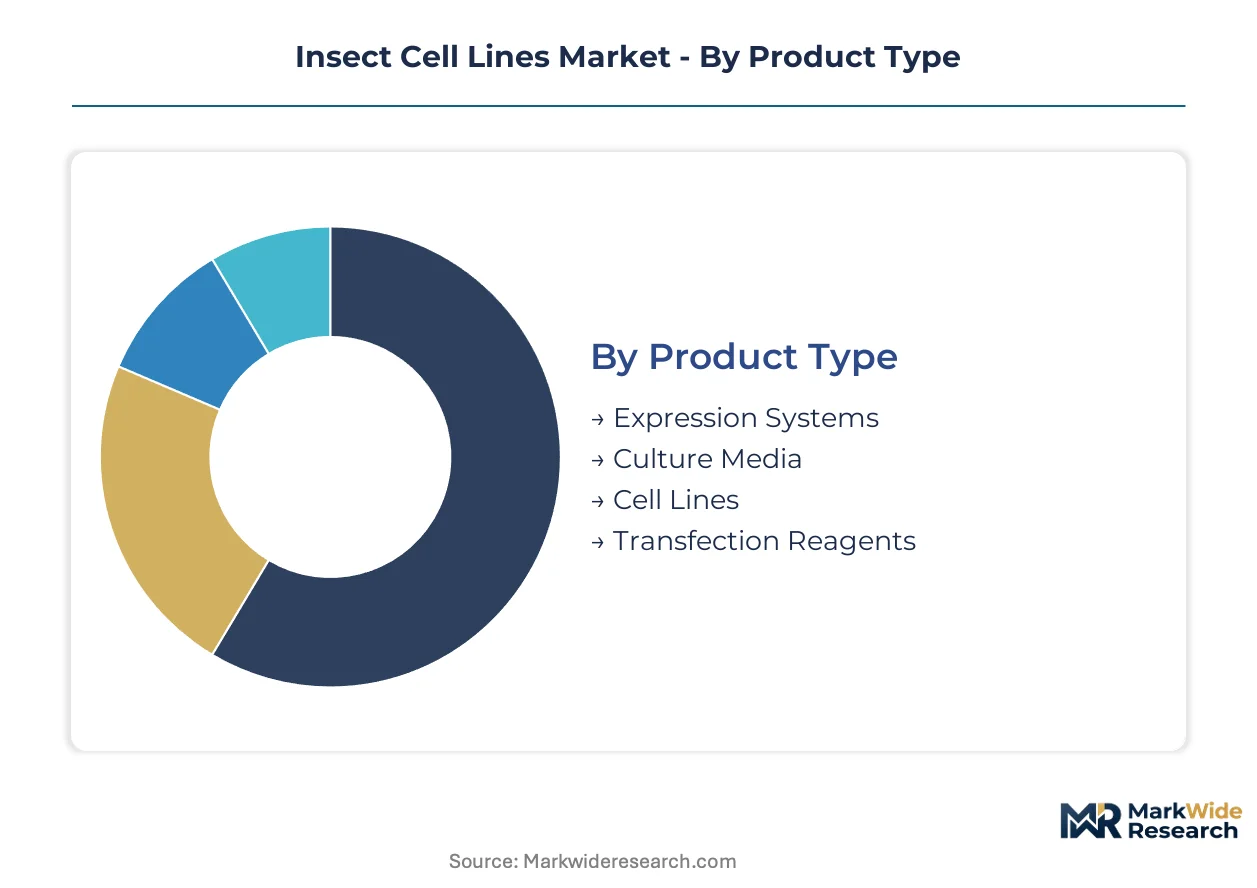
Insect cell line procurement splits across distinct technology tiers and customer workflows. Buyers match product configurations to regulatory maturity, glycosylation complexity, and manufacturing scale requirements. Segment selection directly determines facility qualification timelines and batch release protocols.
Product Type:
Cycle times vary sharply—cell lines require 18-24 month master cell bank qualification, while media formulations turn in quarterly procurement cycles. Expression systems and reagents occupy intermediate velocity tiers with 6-12 month validation windows.
- Expression Systems:Baculoviral vector kits and plasmid backbones engineered for Spodoptera frugiperda or Trichoplusia ni hosts. Demand concentrates in United States gene therapy vector programs where FDA master file submissions favor established AcMNPV platforms over novel mammalian alternatives.
- Cell Lines:Cryopreserved master and working cell banks of Sf9, Sf21, and High Five derivatives. German biopharmaceutical manufacturers anchor procurement volumes, driven by EMA guidelines tightening adventitious agent documentation for baculoviral master seeds.
- Culture Media:Serum-free and chemically defined formulations optimized for lepidopteran suspension culture.
- Transfection Reagents:Lipid and polymer-based delivery systems for baculoviral DNA introduction.
Cell lines dominate installed base. Expression systems are where expansion concentrates.
Application:
Margin structures diverge by therapeutic modality—vaccine antigen production runs on cost-optimized platforms, while gene therapy vectors command premium pricing for GMP-grade materials.
- Gene Therapy:AAV and lentiviral vector manufacturing leveraging baculovirus-insect cell co-infection protocols. United States CAR-T developers pull capacity toward Sf9-based production as FDA biosimilar pathways streamline IND submissions for non-mammalian expression systems.
- Protein Expression:Recombinant enzyme and structural protein production for research and diagnostic applications. Chinese contract manufacturers expand perfusion bioreactor networks to capture CRISPR-edited High Five line contracts from multinational sponsors.
- Biopharmaceutical Production:Commercial-scale monoclonal antibody and biosimilar manufacturing.
- Vaccine Development:Influenza and emerging pathogen antigen production for clinical trial supply.
Protein expression anchors current revenue. Gene therapy is climbing the fastest.
Technology:
Adoption velocity splits between mature platforms with decades of regulatory precedent and precision-edited systems compressing development timelines.
- CRISPR:Cas9-mediated knock-in of humanized glycosylation pathways into High Five and Sf9 substrates. Academic institutions in Switzerland and contract development organizations in Germany deploy precision-edited lines to shorten vendor qualification from 24 months to 8-12 weeks.
- Insect-Specific Baculovirus:Optimized AcMNPV and BmNPV strains with enhanced promoter systems and selection markers. India's CDSCO capacity-building incentives for indigenous viral vector production pull demand toward established baculoviral platforms with lower regulatory risk profiles.
- Transgenic Technology:Stable integration of expression cassettes via transposon or homologous recombination.
- Hybridoma:Fusion-based antibody production in lepidopteran backgrounds.
Insect-specific baculovirus dominates installed base. CRISPR is where expansion concentrates.
End User:
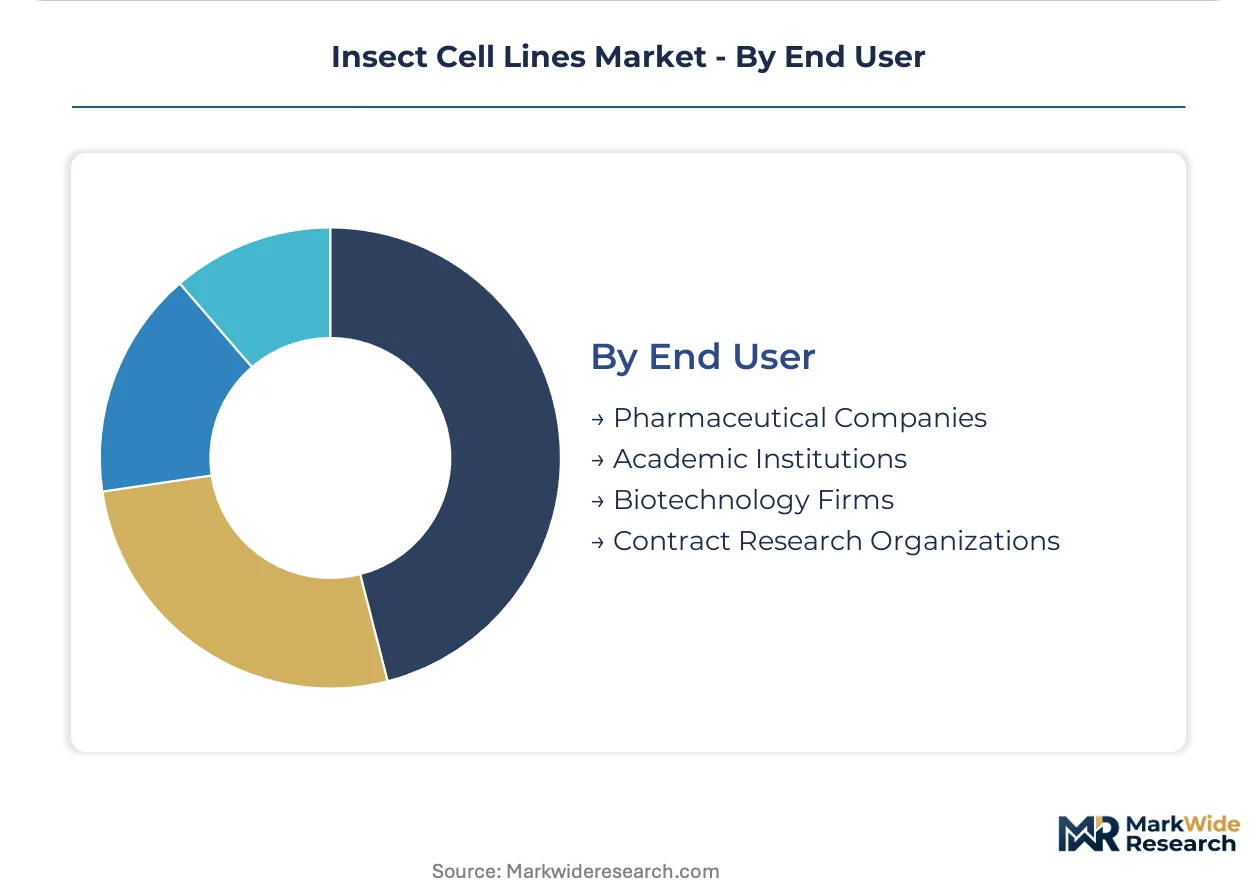
Procurement sophistication varies—pharmaceutical companies unbundle cell-line ownership from manufacturing services, while academic buyers prioritize reagent cost over GMP compliance.
- Contract Research Organizations:Full-service viral vector and protein production houses managing multi-sponsor programs. United States CROs face price compression as sponsors license edited Sf9 lines directly from platform holders, then tender manufacturing capacity separately.
- Pharmaceutical Companies:Large-molecule developers with captive biologics manufacturing infrastructure. Swiss and German manufacturers consolidate sequencing partnerships to meet EMA revised guidelines on recombinant protein quality documentation without internal infrastructure buildout.
- Biotechnology Firms:Venture-backed developers outsourcing early-phase production.
- Academic Institutions:Research-scale protein expression for structural biology and mechanism studies.
Pharmaceutical companies dominate installed base. Contract research organizations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy vector developers and vaccine manufacturers concentrate procurement decisions in jurisdictions with mature biologics infrastructure and streamlined regulatory pathways for non-mammalian expression systems.
United States
CAR-T developers and AAV manufacturers drive Sf9-based baculovirus production demand across Massachusetts and California clusters. FDA biosimilar pathway expansions for non-mammalian master files compress IND-to-approval timelines for viral vector programs. Greater Boston hosts concentrated contract manufacturing capacity serving gene therapy sponsors with customer-owned cell line strategies.
Germany
EMA guideline revisions on recombinant protein quality documentation pull sequencing partnerships toward specialized providers. Baden-Württemberg and Bavaria anchor contract development organization density for precision-edited High Five line deployment. German manufacturers consolidate external testing relationships to meet December 2025 adventitious agent documentation deadlines without captive infrastructure buildout.
China
NMPA Good Manufacturing Practice standards for viral vector production shape facility qualification requirements across Yangtze River Delta biotech zones. WuXi Biologics operates Asia's largest single-use bioreactor network for insect-based manufacturing in Shanghai-Jiangsu corridor. CDSCO capacity-building incentives in India create competitive pressure for Chinese contract manufacturers to capture CRISPR-edited line contracts from multinational sponsors.
Switzerland
Swissmedic oversight of biologics master files supports precision-edited platform commercialization from Basel and Zurich academic-industry partnerships. CRISPR-Cas9 knock-in technology migrates from research tool to production standard through Swiss contract development organization pipelines. Geneva-based vaccine research infrastructure expands access to WHO prequalification pathways for insect-derived products.
India
CDSCO capacity-building incentives for indigenous viral vector production create first-mover advantages for Sf21 facility qualification in Hyderabad and Bengaluru clusters. Serum-dependent culture media expose contract manufacturing organizations to agricultural commodity price swings that compress margins. Indian vaccine manufacturers target Gavi and UNICEF procurement channels through WHO prequalification acceleration for baculovirus-derived antigens.
Insect Cell Lines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Thermo Fisher Scientific Inc. leverages upstream workflow supply dominance through media portfolio breadth, while Lonza Group AG anchors custom cell-line engineering services. Three strategic archetypes emerge: diversified life science conglomerates with reagent-to-service integration, pure-play contract development organizations with precision-edited platform specialization, and emerging Asia-Pacific scale operators with single-use bioreactor networks. Competitive dynamics center on technology licensing for optimized baculoviral strains and geographic capacity expansion to capture gene therapy vector demand.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify channel-controlling positions spanning reagent supply through manufacturing services. Lonza Group AG and WuXi Biologics occupy scale-driven contract manufacturing archetypes with differentiated geographic footprints—Swiss precision engineering capabilities versus Asia-Pacific bioreactor network density. GenScript Biotech Corporation represents the precision-edited platform specialist model, anchoring CRISPR-modified substrate development for sponsors unbundling cell-line ownership from manufacturing execution. Sartorius AG and GE Healthcare sit within equipment-and-consumables integration archetypes, supplying single-use technologies that enable perfusion bioreactor convergence with baculoviral infection protocols.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Sartorius AG |
| Lonza Group AG |
| Expression Systems LLC |
| GE Healthcare |
| Charles River Laboratories |
| GenScript Biotech Corporation |
| WuXi Biologics |
| Others |
Supply & Pricing Matrix
Fetal bovine serum supply from South American agricultural markets anchors cost structures across insect cell culture media tiers, concentrating margin capture with serum-free formulation specialists who have decoupled from commodity volatility. Baculoviral vector licensing fees and CRISPR-edited cell line royalties now constitute the fastest-growing cost components in viral vector manufacturing contracts.
Pricing Analysis
Cost-plus contracts with fetal bovine serum indexation dominate media procurement, though serum-free alternatives command fixed-price premiums tied to certification grade and GMP compliance tier. Price differentiation separates GMP-grade master cell banks from research-use-only lines, with customization levels and after-sales technical support driving additional variance. Pricing pressure stems from sponsor unbundling of cell-line ownership from manufacturing services, compressing pure-play contract manufacturer margins. Academic institutions exhibit highest price sensitivity, while gene therapy developers prioritize expression titer guarantees over unit cost.
Supply Chain Analysis
Upstream feedstock for serum-dependent media draws from South American cattle operations, while chemically defined formulation precursors source from German and Swiss specialty chemical manufacturers. Baculoviral vector master seeds concentrate with United States and European platform technology holders, creating single-source licensing vulnerabilities. Supply chain risk centers on agricultural commodity price volatility for serum-exposed manufacturers. Distribution runs through direct sales for GMP-grade cell lines and reagent distributors for research-scale consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large pharmaceutical sponsors who unbundle cell-line licensing from manufacturing procurement, fragmenting contract manufacturer pricing leverage across the value chain.
For Market Incumbents: Entrench platform control through captive supply of CRISPR-edited Sf9 and High Five lines with humanized glycosylation pathways, while expanding sequencing partnerships to meet EMA adventitious agent documentation requirements without internal infrastructure buildout. Defend against sponsor direct-licensing threats by embedding penalty clauses for expression titer shortfalls into long-term supply agreements. For New Entrants and Emerging Players: Build out perfusion bioreactor capacity in India to capture CDSCO capacity-building incentives for indigenous viral vector production, targeting Sf21 facility qualification as a first-mover wedge. White-space exists in continuous manufacturing integration for baculoviral infection protocols, with gene therapy vector programs offering the most penetrable entry point through customer-owned cell line strategies. For Investors and Strategic Acquirers: Capital is best deployed toward precision-edited platform specialists with locked-in royalty streams from pharmaceutical sponsors, rather than pure-play contract manufacturers exposed to price compression from unbundling trends. Long-term viability across the analysis window favors vertically integrated suppliers spanning reagent through manufacturing execution. Watch for WHO prequalification pathway maturation as the signal indicating procurement channel access to Gavi and UNICEF tender programs.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Platform Licensing Agreement | Locks in recurring royalty streams from pharmaceutical sponsors unbundling cell-line ownership. |
| Serum-Free Media Manufacturing Scale-Up | Insulates margin from South American agricultural commodity price volatility. |
| Sequencing Partnership Consolidation | Enables EMA compliance on adventitious agent documentation without captive infrastructure. |
| Continuous Perfusion Bioreactor Deployment | Captures 10x density improvements for baculoviral infection protocols in gene therapy vector production. |
| WHO Prequalification Pathway Advancement | Opens procurement channels to Gavi and UNICEF tender programs for insect-derived vaccines. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with biopharmaceutical manufacturing executives, regulatory affairs leads at contract development organizations, viral vector program directors, and GMP facility qualification specialists; and secondary validation through FDA master file submissions, EMA guideline revisions, NMPA Good Manufacturing Practice standards, and WHO prequalification pathway documentation. Bottom-up triangulation across expression system procurement volumes and top-down validation against bioreactor capacity announcements anchored market sizing.
Forecast inputs considered technology adoption curves across CRISPR-edited platforms, regulatory convergence timelines for adventitious agent testing, and geographic expansion of single-use bioreactor networks. Segmentation dimensions modeled include product type, application modality, technology tier, and end-user procurement sophistication. CAGRs were derived from installed base growth rates and replacement cycle compression across the projection horizon. Industry-specific inputs incorporated baculoviral vector demand from CAR-T developers and vaccine antigen production scaling.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision-edited platform specialists or diversified life science conglomerates would shift outcomes beyond modeled ranges. Cross-checking against EMA master file submission trends and CDSCO facility approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Global Cell Banking Outsourcing Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Biobanking Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
Antibodies Contract Manufacturing Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market