
 Antibody Contract Development & Manufacturing Organization Market | 2026-2036
Antibody Contract Development & Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Contract Development & Manufacturing Organization Market Analytics
Process development services is recalibrating what biopharmaceutical clients purchase from antibody CDMOs, shifting contracts toward integrated discovery-to-commercialization partnerships rather than discrete manufacturing runs. Lonza Group anchors European biologics capacity through its mammalian cell culture network. Samsung Biologics dominates large-scale commercial manufacturing with one of the world's biggest single-site bioproduction facilities. WuXi Biologics extends its position through global multi-modal antibody platforms spanning discovery, development, and GMP production.
An Antibody Contract Development & Manufacturing Organization provides outsourced biopharmaceutical services encompassing cell line development, upstream and downstream bioprocessing, formulation, fill-finish, and analytical characterization for antibody-based therapeutics, typically employing Chinese hamster ovary (CHO) cell expression systems in stainless steel or single-use bioreactors ranging from 1,000 to 20,000 liters. The primary commercial purpose is to enable drug developers to access specialized manufacturing expertise and capital-intensive infrastructure without building in-house biologics capacity. Monoclonal antibodies remain the dominant product type by revenue volume, reflecting decades of clinical validation and established regulatory pathways. Bispecific antibodies represent the fastest-growing product category, driven by oncology pipeline expansion and complex protein engineering requirements that favor specialized CDMO partners. Antibody-drug conjugates command premium pricing due to their multi-step conjugation chemistry and stringent linker-payload handling requirements.
FDA's Current Good Manufacturing Practice regulations and EMA's Guideline on Development and Manufacture of Biotechnology-Derived Medicinal Products govern antibody CDMO facility design, process validation, and lot release testing across the United States and European Union. China's NMPA and South Korea's MFDS impose comparable biologics standards, creating a fragmented compliance landscape that favors CDMOs with multi-regulatory accreditations. Stakeholders must monitor evolving biosimilar guidance and gene-editing platform qualifications as these technologies reshape antibody production methodologies and regulatory scrutiny.
Market Dynamics
Biopharmaceutical developers are consolidating antibody production contracts with fewer CDMO partners capable of end-to-end service integration, compressing vendor lists as regulatory complexity and molecule sophistication rise simultaneously.
Growth Catalysts
- EMA's Guideline on Development and Manufacture of Biotechnology-Derived Medicinal Products:Stringent European quality standards push developers toward accredited CDMO partners with proven compliance track records, accelerating outsourcing decisions for EU-bound antibody programs.
- Bispecific antibody engineering:Complex dual-targeting architectures demand specialized protein folding expertise and analytical capabilities that in-house biologics teams rarely maintain, funneling development to dedicated contract partners.
- South Korean biocluster concentration:Incheon's Songdo district anchors large-scale mammalian cell culture capacity, attracting global biopharmaceutical sponsors seeking single-site commercial manufacturing at scale.
Market Restraints
- Stainless steel bioreactor capital intensity:Fixed-tank infrastructure requires $200-500 million facility investments with decade-long depreciation horizons, limiting new entrant participation and preserving incumbent dominance.
- Protein A resin supply concentration:Chromatography media production concentrates among three specialized chemical suppliers, creating input bottleneck vulnerability for downstream purification operations.
- FDA lot release testing timelines:Extended analytical validation periods for novel antibody formats delay commercial revenue recognition, compressing CDMO cash conversion cycles.
Strategic Opportunities
- India's emerging biologics corridor:Hyderabad and Bengaluru develop mammalian cell culture infrastructure under CDSCO oversight, offering cost-advantaged development capacity for early-phase antibody programs.
- Antibody-drug conjugate payload-linker integration:CDMOs mastering both biologics production and cytotoxic small-molecule handling capture premium pricing through differentiated one-stop service models.
- Continuous bioprocessing technology convergence:Perfusion cell culture married with continuous chromatography enables smaller facility footprints and higher productivity, rewarding early technology adopters with manufacturing cost advantages.
Industry Challenges
- Cell line development scientist scarcity:Qualified molecular biologists capable of high-producing CHO clone isolation command compensation premiums that erode CDMO margin structures.
- Multi-regulatory filing synchronization:Simultaneous FDA, EMA, and NMPA approval pathway management demands dedicated regulatory affairs teams with geography-specific submission expertise.
- Legacy batch record system integration:Paper-based manufacturing documentation workflows resist digitization, compling electronic data integrity compliance under 21 CFR Part 11.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Contract Development & Manufacturing Organization Market |
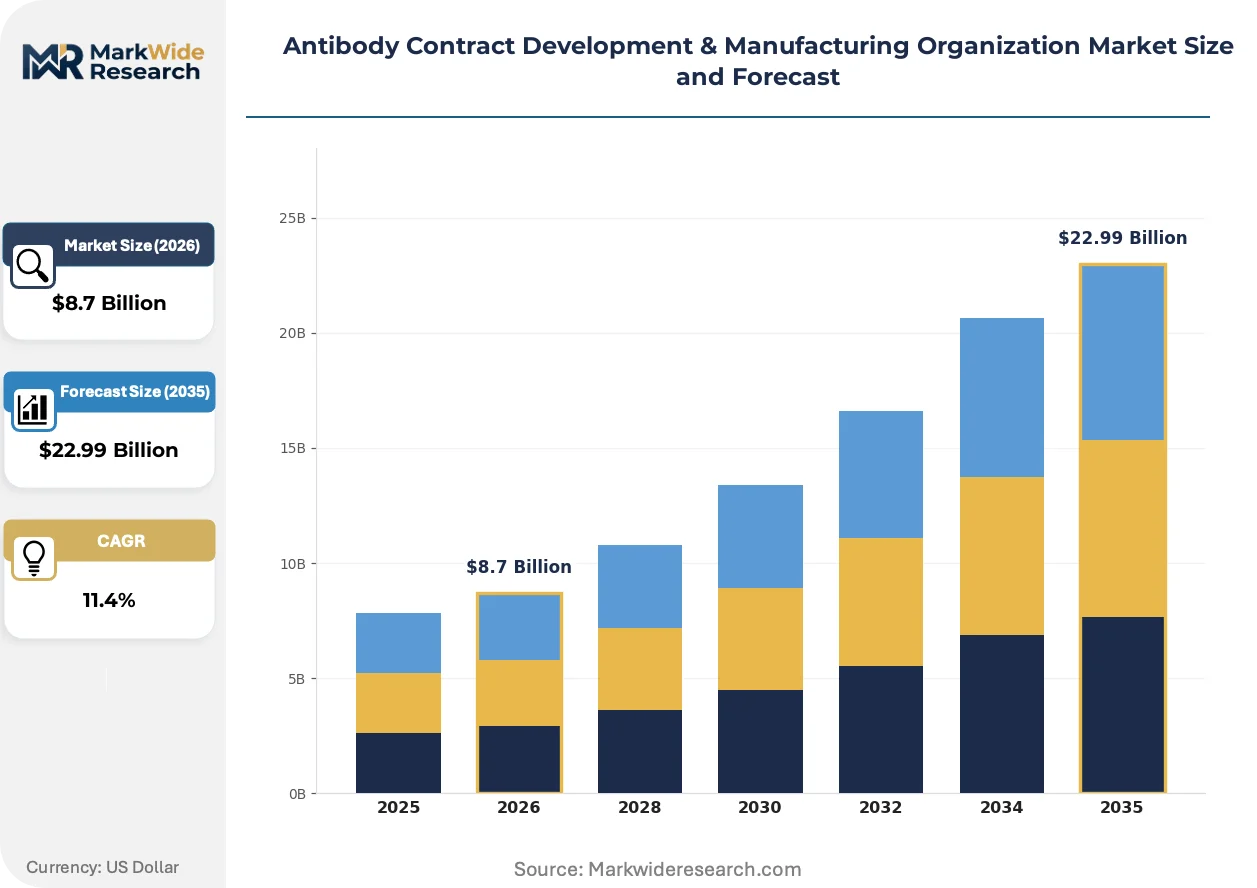
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Bispecific Antibodies, Antibody-Drug Conjugates, Fc-Engineering Service Type: Process Development, Clinical Manufacturing, Commercial Manufacturing, Quality Control End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Delivery Mode: Onsite Services, Remote Services, Hybrid Services, Vendor Management |
| Companies Covered | AGC Biologics, Samsung Biologics, Lonza Group, Boehringer Ingelheim, Thermo Fisher Scientific, Catalent, Charles River, FUJIFILM, WuXi Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Contract Development & Manufacturing Organization Market Evolving Landscape
Single-use bioprocessing systems are compressing facility construction timelines while modular manufacturing architectures enable rapid capacity reconfiguration between antibody product types.
Continuous manufacturing technology is electrifying antibody production economics by replacing fed-batch cell culture with perfusion-based systems that maintain cells in exponential growth phase for weeks. Mid-sized biopharmaceutical developers are adopting these platforms fastest, seeking to match productivity metrics previously exclusive to large-cap sponsors. The technology is electrifying competitive positioning by collapsing cost-per-gram curves and enabling smaller-footprint facilities that challenge incumbent scale advantages.
FDA's Quality Management Maturity program is elevating inspection intensity for antibody CDMO facilities, with risk-based scheduling prioritizing sites with prior warning letter history or novel platform technologies. The industrial consequence is accelerated investment in automated environmental monitoring and real-time release testing capabilities. Sites supplying oncology bispecifics face the steepest compliance burden, responding with dedicated quality unit expansion and enhanced training protocols.
Sponsor companies are unbundling discovery, development, and commercial manufacturing phases across distinct contract partners rather than locking into single CDMO relationships. Early-phase antibody engineering services now concentrate with specialized discovery boutiques, while commercial-scale production migrates toward volume-dedicated manufacturing specialists. This fragmentation is most pronounced among US-based biotech sponsors, who prioritize geographic proximity for development work and cost optimization for commercial supply.
Antibody Contract Development & Manufacturing Organization Market Segmentation
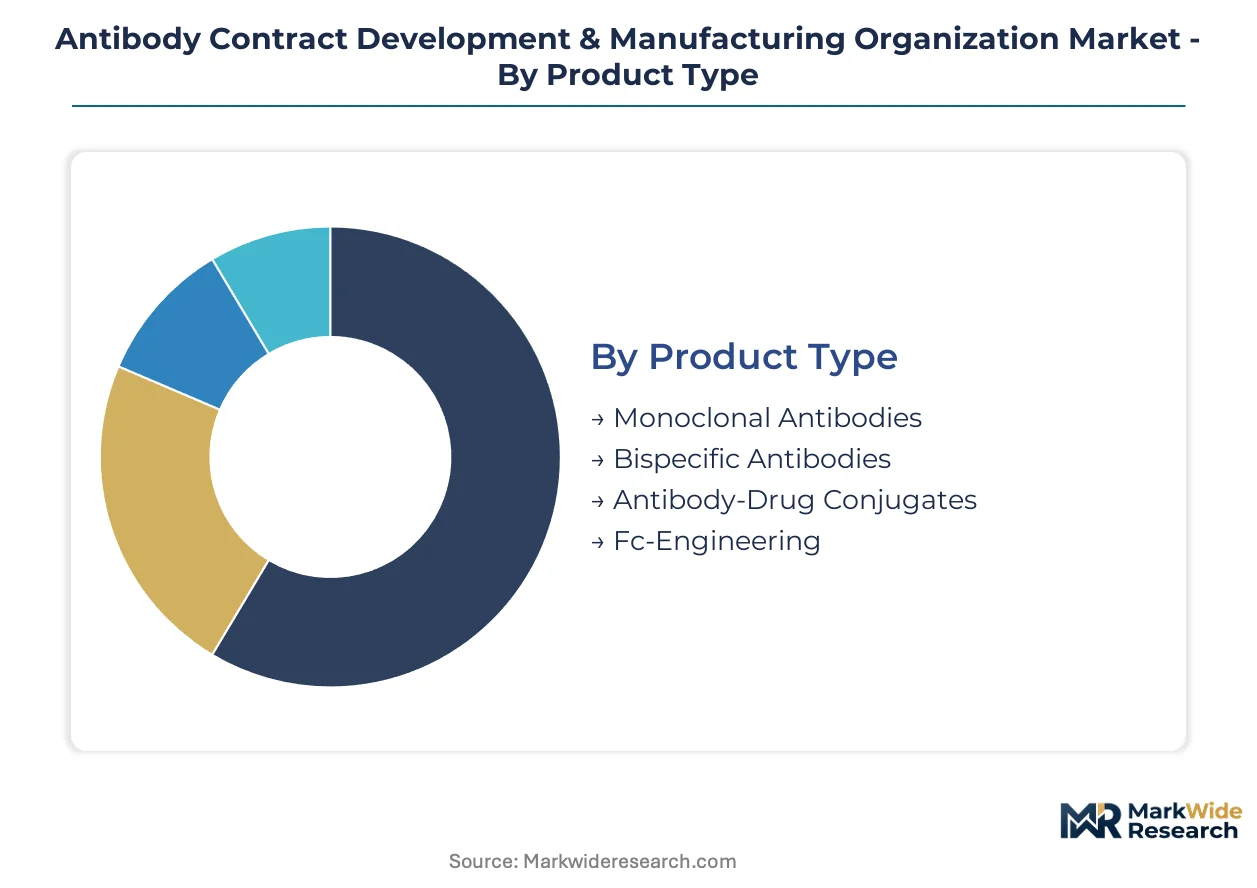
Antibody CDMO segmentation reveals how service bundling and molecule complexity reshape procurement patterns across the biopharmaceutical value chain. Contract structures diverge sharply between standalone manufacturing engagements and integrated discovery-to-commercial partnerships.
Product Type:
Standalone antibody formats dominate current manufacturing volumes, while engineered architectures increasingly embed into multi-specific therapeutic platforms.
- Monoclonal Antibodies:These single-target immunoglobulins utilize established CHO cell expression systems with well-characterized glycosylation profiles. Demand concentrates among mid-cap pharmaceutical sponsors in the United States seeking validated regulatory pathways for oncology and autoimmune indications; manufacturing scale and FDA submission familiarity anchor outsourcing decisions.
- Bispecific Antibodies:Dual-targeting architectures require specialized heavy-light chain pairing technologies and complex analytical characterization. South Korean bioclusters attract the steepest capacity investment here, driven by global sponsors pursuing differentiated oncology mechanisms that in-house facilities cannot accommodate.
- Antibody-Drug Conjugates:Multi-step bioconjugation chemistry demands integrated cytotoxic payload handling and linker stability expertise under stringent containment protocols.
- Fc-Engineering:Modified constant region variants enhance effector function or extend serum half-life through glycoengineering and amino acid substitution platforms.
Volume placements concentrate in monoclonal antibodies; the faster expansion belongs to bispecific antibodies.
Service Type:
Cost tier differentiation separates early-phase development services from commercial-scale manufacturing, with margin structures widening across the progression.
- Process Development:Cell line optimization, media formulation, and scale-up validation establish manufacturing feasibility for novel antibody formats. German biologics clusters capture disproportionate early-phase demand as sponsors prioritize EMA-aligned quality systems from program inception.
- Commercial Manufacturing:Large-scale GMP production in stainless steel or single-use bioreactors generates recurring revenue through multi-year supply agreements. United States-based sponsors dominate contract value here, seeking FDA-inspected capacity for approved antibody therapeutics with established patient populations.
- Clinical Manufacturing:Phase-appropriate GMP material supply for human trials with flexible batch sizing and rapid turnaround protocols.
- Quality Control:Release testing, stability studies, and regulatory documentation support spanning analytical method development and validation.
Revenue concentration sits with commercial manufacturing; steepest margin expansion tracks to process development.
End User:
Customer type determines contract duration, technical specification depth, and regulatory filing responsibility allocation.
- Pharmaceutical Companies:Large-cap sponsors with in-house biologics capabilities selectively outsource capacity-constrained programs or novel formats exceeding internal expertise. These buyers prioritize multi-regulatory accreditation and established FDA inspection histories in vendor selection.
- Biotechnology Firms:Venture-backed developers without captive manufacturing infrastructure depend entirely on CDMO partners from IND through commercialization. United States coastal hubs—Boston and San Francisco—generate dense demand clusters as these sponsors value geographic proximity for development-phase collaboration.
- Research Institutions:Academic medical centers and nonprofit research organizations seeking GMP material for investigator-initiated trials and early translational studies.
- Contract Research Organizations:Discovery-focused service providers extending downstream into development and manufacturing through partnership or acquisition.
Contract volume concentrates among biotechnology firms; the most rapid user base expansion is occurring within research institutions.
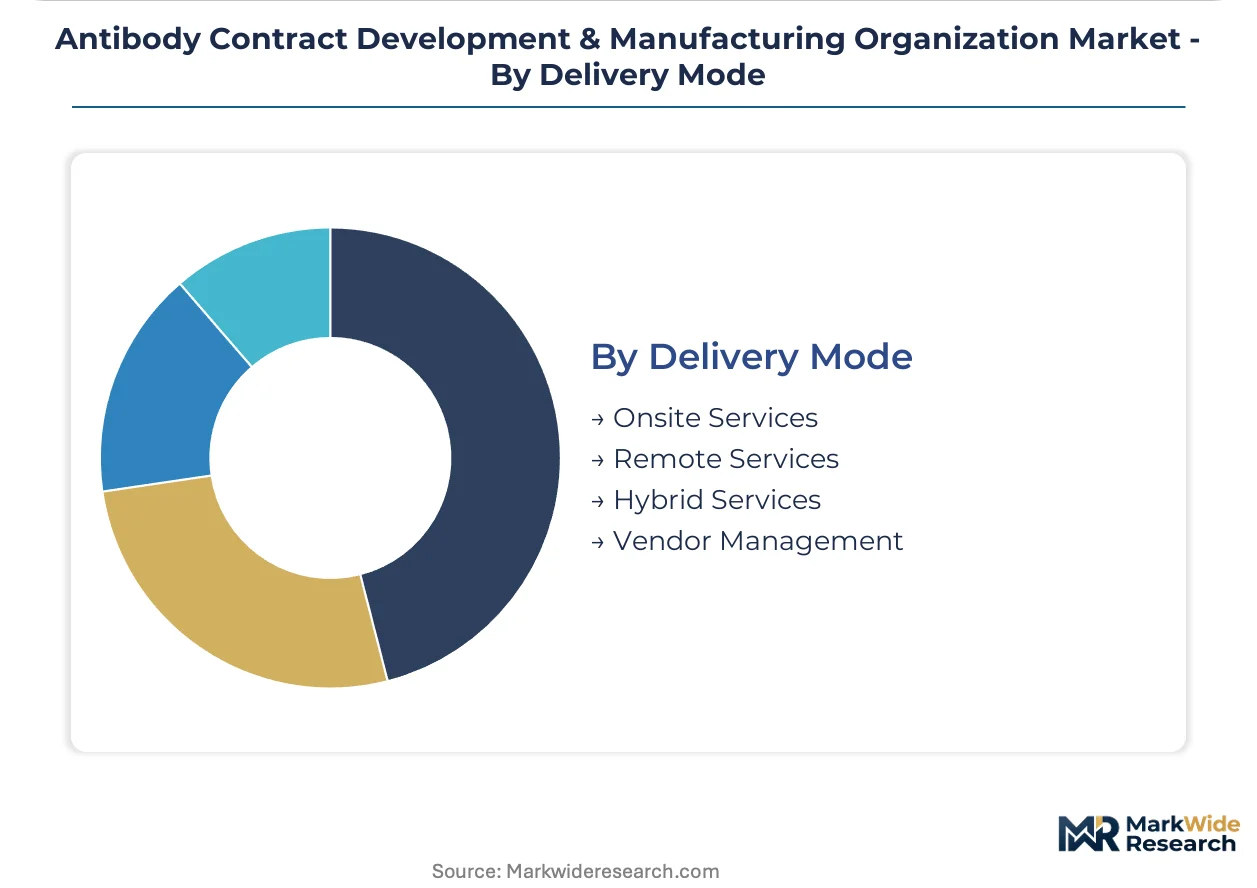
Delivery Mode:
Service delivery configuration shapes risk allocation, intellectual property protection, and operational flexibility for antibody program sponsors.
- Onsite Services:Dedicated manufacturing suites and embedded client personnel enable maximum process control and IP security. South Korean facilities attract the densest onsite deployment for commercial antibody supply, where single-site scale justifies dedicated infrastructure investment.
- Hybrid Services:Blended models combine development-phase colocation with commercial manufacturing at distant high-volume sites. United States sponsors increasingly adopt this structure, maintaining proximity for cell line development while exploiting Asian cost structures for large-scale production.
- Remote Services:Technology transfer and project management conducted through digital collaboration platforms with limited physical presence.
- Vendor Management:Client-directed oversight of subcontracted analytical or fill-finish operations within the CDMO's supplier network.
Onsite engagements capture the largest contract values; hybrid services are gaining share fastest among mid-cap sponsors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Songdo anchors the largest concentration of antibody manufacturing capacity worldwide, with single-site bioproduction facilities exceeding 180,000 liters of mammalian cell culture capacity. Germany and the United States maintain dense networks of development-stage CDMOs serving early-phase biopharmaceutical sponsors. China's NMPA-aligned manufacturing clusters are expanding to capture outsourced demand from Western sponsors seeking cost-advantaged GMP production.
United States
Biotechnology firms in Greater Boston and San Francisco drive contract demand for IND-enabling process development and Phase I clinical manufacturing. FDA's Quality Management Maturity program intensifies inspection schedules for antibody CDMO facilities, accelerating investment in automated environmental monitoring systems. The Southeast corridor—North Carolina's Research Triangle and Georgia's biocluster—attracts commercial-scale capacity expansion for late-stage antibody programs.
Germany
EMA-aligned quality systems from program inception attract early-phase antibody development contracts from sponsors targeting European commercialization. The country's national pharmaceutical regulator enforces Guideline on Development and Manufacture of Biotechnology-Derived Medicinal Products with stringent process validation requirements. Bavaria and Baden-Württemberg concentrate mammalian cell culture expertise, with Basel-proximate facilities serving cross-border biopharmaceutical sponsors.
South Korea
Incheon's Songdo district hosts one of the world's largest single-site bioproduction facilities, specializing in commercial-scale monoclonal and bispecific antibody manufacturing. MFDS imposes biologics standards comparable to FDA and EMA, enabling multi-regulatory filing synchronization from Korean-based CDMOs. The Seoul Capital Area extends development-stage capabilities upstream, creating integrated discovery-to-commercialization service corridors.
China
Cost-advantaged mammalian cell culture capacity in Shanghai and Suzhou attracts outsourced manufacturing from Western sponsors seeking GMP production at reduced cost-per-gram. NMPA's evolving biologics standards align progressively with ICH guidelines, reducing regulatory friction for multi-regional antibody programs. Wuhan and Hangzhou bioclusters develop specialized capabilities in antibody-drug conjugate payload-linker integration.
Switzerland
Swissmedic's precision-focused regulatory framework supports high-complexity antibody formats requiring specialized analytical characterization. Basel's pharmaceutical corridor concentrates Fc-engineering and glycoengineering expertise for modified constant region variants. The country's central European location enables efficient technology transfer and supply chain coordination across German, French, and Italian sponsor operations.
Antibody Contract Development & Manufacturing Organization Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that rewards end-to-end service integration. Stainless steel bioreactor infrastructure and single-use platform specialists occupy distinct competitive tiers, with consolidation favoring partners capable of spanning discovery through commercial manufacturing. Three archetypes dominate: scale-driven volume manufacturers, technology-differentiated development specialists, and integrated platform providers. Capacity expansion and strategic partnerships constitute the primary competitive moves, as sponsors consolidate vendor lists under regulatory complexity pressure.
Within the integrated platform tier, WuXi Biologics and Lonza Group exemplify archetypes spanning discovery, development, and GMP production capabilities. Samsung Biologics anchors the scale-driven segment with concentrated large-site manufacturing capacity. These three entities occupy positions that reflect broader industry segmentation between geographic proximity for development-phase collaboration and cost-optimized commercial supply.
| Leading Market Players |
|---|
| AGC Biologics |
| Samsung Biologics |
| Lonza Group |
| Boehringer Ingelheim |
| Thermo Fisher Scientific |
| Catalent |
| Charles River |
| FUJIFILM |
| WuXi Biologics |
| Others |
Value Network & Pricing Analysis
Protein A resin costs cascade through antibody CDMO pricing tiers, with chromatography media accounting for disproportionate downstream purification expense before contract value differentiates across stainless steel and single-use platform engagements. South Korean manufacturers exploit concentrated bioreactor scale to compress per-gram production economics, while German and United States facilities command development-phase premiums through EMA and FDA proximity.
Pricing Analysis
Yield-guaranteed throughput contracts anchor antibody CDMO pricing structures, with sponsors paying premium rates for facilities demonstrating consistent titers above established thresholds. Three-tier pricing structure across premium, standard, and economy levels separates dedicated suite access from shared manufacturing campaigns and emerging-market capacity. Cost compression in economy-tier production is intensifying because Chinese NMPA-aligned facilities expand mammalian cell culture offerings. Biotechnology firms without captive infrastructure exhibit highest price sensitivity, while large-cap pharmaceutical sponsors prioritize regulatory track record over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for Protein A resin and cell culture media compel CDMOs to qualify multiple chemical suppliers despite production concentrating among specialized manufacturers in the United States, Germany, and Japan. Stainless steel bioreactor fabrication draws from precision engineering clusters in Germany and South Korea, while single-use assembly systems rest on polymer film supply from specialized converters. Single-source vulnerability in chromatography media creates input bottleneck exposure for downstream purification operations. Distribution runs through sponsor-directed logistics networks with temperature-controlled cold chain custody from GMP facility to clinical site or commercial warehouse.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibody CDMO market consolidation accelerates as regulatory complexity and capital intensity force sub-scale facilities toward exit or acquisition, compressing viable vendor lists for biopharmaceutical sponsors.
For Market Incumbents: Lock in multi-year supply agreements with biotechnology sponsors before FDA's Quality Management Maturity program intensifies inspection scheduling and elevates compliance costs for smaller competitors. Expand single-use bioprocessing capacity in the United States Southeast corridor to capture sponsor demand for flexible, FDA-inspected clinical manufacturing. Backward integration into cell line development capabilities protects margin structures against molecular biologist scarcity.
For New Entrants and Emerging Players: India's CDSCO-aligned biologics corridor opens a window for cost-advantaged early-phase antibody development, targeting venture-backed United States biotech sponsors seeking IND-enabling process development at reduced burn rates. Focus initial capacity on bispecific antibody engineering, where complex dual-targeting architectures create specialist demand that volume manufacturers cannot accommodate. Pursue hybrid service models combining Indian development-phase proximity with Korean commercial manufacturing partnerships.
For Investors and Strategic Acquirers: MFDS inspection clearance for Korean facilities is the leading indicator that commercial-scale antibody capacity will command sustained pricing power across multi-regulatory filing programs. Target mid-tier CDMOs with established EMA quality systems and underutilized stainless steel bioreactor networks, where consolidation synergies extract value from fixed-cost leverage. Watch for continuous bioprocessing technology adoption rates as the signal distinguishing future cost leaders from stranded batch-manufacturing assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Perfusion cell culture married with continuous chromatography collapses cost-per-gram curves for mid-cap sponsors. |
| Multi-Regulatory Accreditation Investment | Simultaneous FDA, EMA, and NMPA qualification expands addressable sponsor base for integrated platform providers. |
| Antibody-Drug Conjugate Capability Integration | Combined biologics production and cytotoxic small-molecule handling captures premium pricing through differentiated service. |
| Single-Use Platform Expansion | Modular manufacturing architectures enable rapid capacity reconfiguration between monoclonal and bispecific antibody programs. |
| Cell Line Development Talent Acquisition | Qualified molecular biologists capable of high-producing CHO clone isolation command compensation premiums that erode competitor margins. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads, CDMO operations directors, and biopharmaceutical procurement managers underwrites the qualitative findings, with secondary validation drawing from FDA filings, EMA submissions, ClinicalTrials.gov records, and GMP inspection databases. Bottom-up capacity assessments triangulate against top-down sponsor outsourcing spend estimates across the analysis window.
Comparable-period anchoring to historical biologics manufacturing investment cycles shapes the forecast framework, with segmentation dimensions spanning product type, service tier, end-user archetype, and delivery mode across the projection horizon. CAGRs derive from facility utilization trajectories, sponsor pipeline conversion rates, and regulatory approval velocity assumptions for novel antibody formats.
The model assumes a particular technology adoption path; alternative pathways for continuous bioprocessing would alter the outlook if perfusion cell culture achieves faster sponsor adoption than fed-batch displacement models project. Deviation in Protein A resin supply availability or MFDS inspection clearance timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Monoclonal Antibody Custom Service Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Antibodies Contract Manufacturing Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Biobanking Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
TSG6 Antibody Market