
 Europe Flow Cytometry Market | 2026-2036
Europe Flow Cytometry Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flow Cytometry Market Insights
Multi-source procurement of optical detectors and fluidic systems is restructuring supply economics for European instrument vendors. Becton Dickinson and Company leverages captive manufacturing of laser modules to protect margin pools in high-parameter cell analyzers. Beckman Coulter anchors its European service network through region-dedicated application specialists. Thermo Fisher Scientific competes by bundling flow cytometry with adjacent mass spectrometry workflows in core facilities.
Flow cytometry is a laser-based analytical technique that measures physical and chemical characteristics of particles, typically cells, as they flow in a fluid stream through a beam of light; instruments detect scattered light and fluorescence emissions at wavelengths from 350 nm to 800 nm to quantify cell size, granularity, and marker expression for diagnostic and research purposes. Instrumentation commands the largest revenue pool in the product hierarchy, though reagent consumables generate superior recurring margins through locked-in protocol dependencies. Cancer Research absorbs the dominant share of application spending, while Immunology represents the fastest-expanding segment as CAR-T development programs multiply across European contract research organizations.
The EU In Vitro Diagnostic Regulation (IVDR) and Medical Device Regulation (MDR) impose stricter conformity assessment pathways on clinical flow cytometry systems sold in member states, elevating documentation burdens and third-party audit costs for manufacturers. EMA guidance on cell therapy characterization further shapes instrument specification requirements for pharmaceutical end users seeking regulatory-aligned analytical platforms. Stakeholders must monitor how notified body capacity constraints delay IVDR certifications and redirect procurement timelines for hospital laboratories.
Market Dynamics
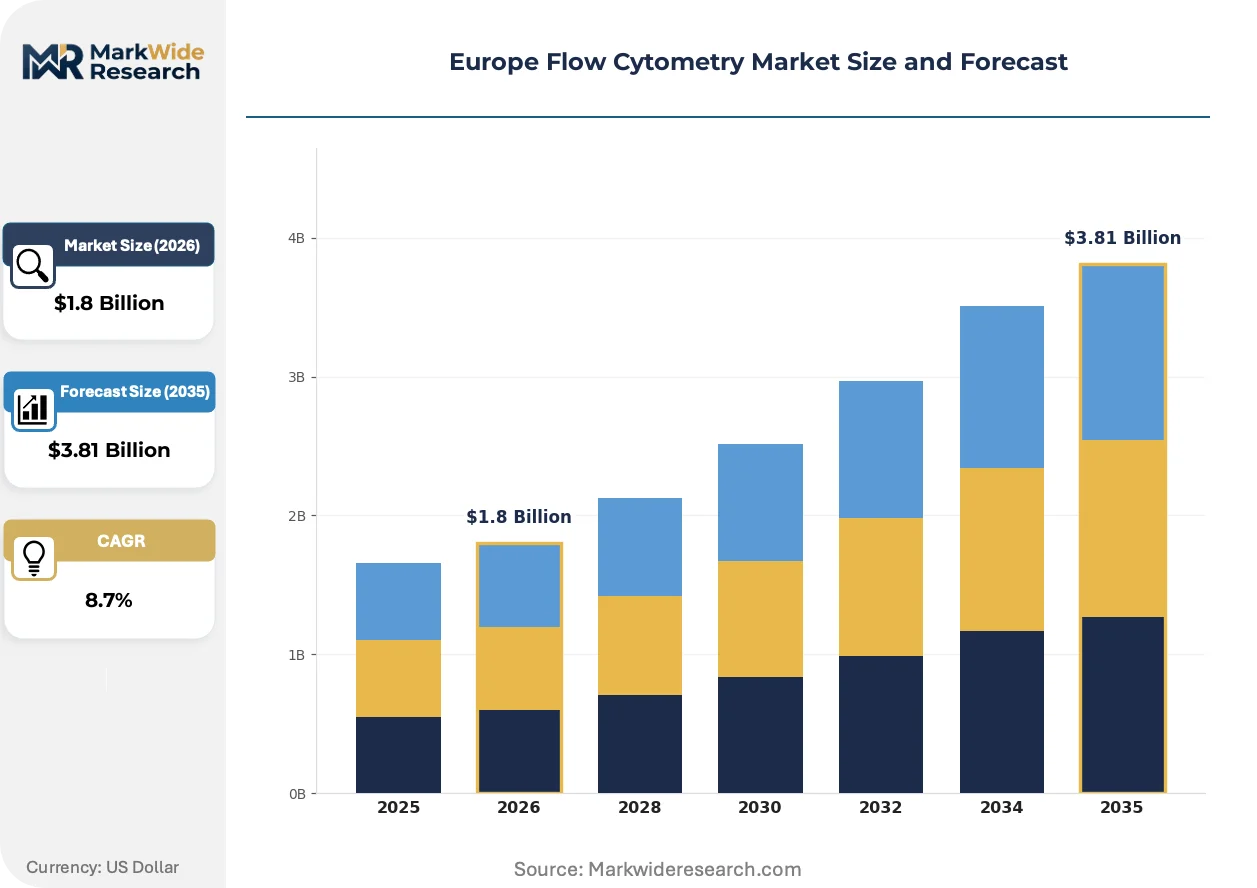
The EU IVDR and MDR frameworks are restructuring commercial pathways for clinical-grade flow cytometry systems, elevating documentation burdens and third-party audit costs that compress vendor margins while favoring incumbents with established notified body relationships.
Growth Catalysts
- CAR-T Manufacturing Expansion:Contract research organizations across Germany and France are scaling cell therapy characterization workflows, driving demand for high-parameter analyzers with validated GMP protocols.
- EMA Cell Therapy Guidance:The agency's analytical platform specifications for cell therapy developers mandate flow cytometry for identity, purity, and potency testing, creating regulatory-aligned procurement pull.
- Heidelberg-Munich Biotech Corridor:Germany's concentrated pharmaceutical R&D infrastructure generates clustered demand for service-intensive instrument deployments with dedicated application support.
Market Restraints
- Optical Detector Supply Concentration:European vendors remain dependent on Asian-manufactured photomultiplier tubes and avalanche photodiodes, exposing margin pools to input cost volatility and lead-time extensions.
- IVDR Certification Bottlenecks:Notified body capacity constraints in Germany and the Netherlands are extending conformity assessment timelines to 18-24 months, delaying hospital laboratory procurement cycles.
- Mass Spectrometry Convergence:Thermo Fisher Scientific's bundled mass cytometry workflows in core facilities present functional substitution for traditional fluorescence-based cell analysis in deep phenotyping applications.
Strategic Opportunities
- Point-of-Care Diagnostics in Eastern Europe:Poland and Hungary show underpenetrated clinical flow cytometry adoption relative to Western European benchmarks, presenting whitespace for compact, IVDR-aligned benchtop systems.
- AI-Enabled Automated Gating:Machine learning algorithms for population identification are converging with cloud-based data management, enabling decentralized pathology networks to standardize inter-laboratory variability.
- EU Green Deal Instrument Efficiency Mandates:Energy consumption specifications for laboratory equipment are creating procurement preference for solid-state laser modules and reduced sheath fluid consumption architectures.
Industry Challenges
- Multicolor Panel Design Expertise Scarcity:Pharmaceutical end users face recruitment friction for flow cytometrists capable of optimizing 20+ color immunophenotyping protocols for regulatory submission packages.
- Legacy LIS Integration Complexity:Hospital laboratories encounter middleware incompatibility when connecting modern cytometers to established laboratory information systems, requiring costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flow Cytometry Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instrumentation, Reagents, Software, Accessories Application: Cancer Research, Immunology, Drug Development, Stem Cell Research End User: Hospitals, Academic Institutions, Clinical Laboratories, Pharmaceutical Companies Technology: Cell Sorting, Cell Identification, Multicolor Analysis, Imaging |
| Companies Covered | Becton Dickinson and Company, Beckman Coulter, Thermo Fisher Scientific, Sysmex Partec, Miltenyi Biotec, Bio-Rad Laboratories, Agilent Technologies, Luminex, Sony Biotechnology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flow Cytometry Market Trends and Innovations
Spectral detection architectures and cloud-native data platforms are actively displacing conventional compensation-based analysis, compressing workflow timelines while expanding parameter scalability for European research and clinical users.
Spectral flow cytometry is electrifying the European market by replacing traditional optical filters with full-spectrum detectors that capture continuous wavelength data. Academic medical centers in the Netherlands and Sweden are adopting 40+ color panels at accelerated pace, enabled by unmixing algorithms that resolve fluorochrome overlap computationally. This technology is electrifying competitive positioning by enabling differentiation through parameter depth rather than hardware volume, compressing the addressable market for conventional compensation-based systems.
The EU IVDR's risk-classification restructure for in vitro diagnostics is elevating clinical flow cytometry systems to Class C or D categories, mandating third-party notified body involvement for conformity assessment. Manufacturers now face expanded clinical evidence requirements and post-market surveillance obligations that extend development timelines. High-complexity hospital laboratories in France and Germany are responding by consolidating procurement around vendors with established IVDR technical documentation, reducing supplier diversity in active tenders.
Service unbundling is fragmenting traditional instrument-reagent bundling models as pharmaceutical buyers negotiate separate pricing for hardware, software licenses, and per-test consumables. Contract research organizations in the United Kingdom are driving this disintermediation, demanding transparent cost structures for cell therapy development programs with milestone-based payment terms. This behavioral shift is most visible in the Cambridge-Oxford-London biotech triangle, where procurement teams prioritize operational expenditure flexibility over capital-heavy instrument ownership.
Europe Flow Cytometry Market Segmentation
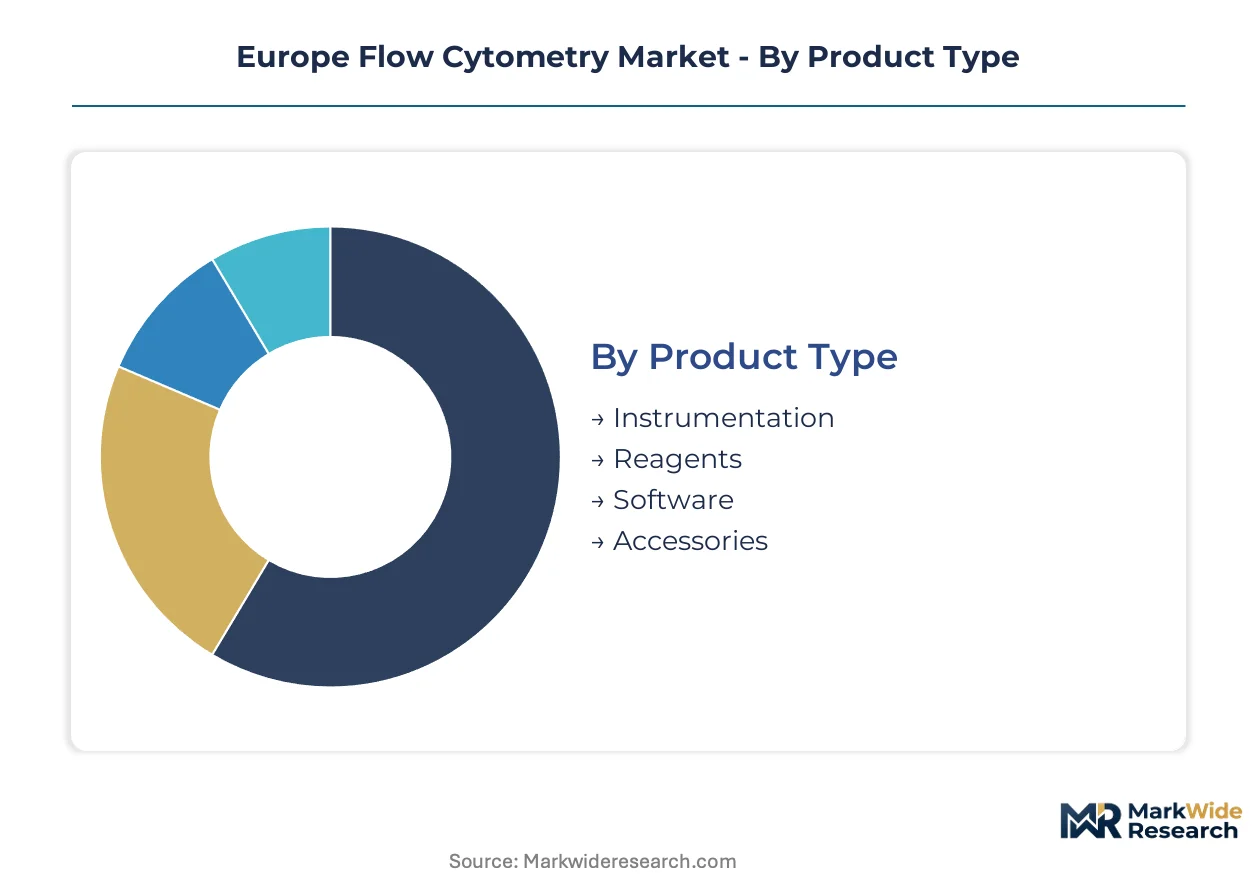
Flow cytometry market segmentation reveals distinct margin architectures across hardware and consumable layers. Product configuration, application intensity, and end-user procurement sophistication create tiered pricing and service requirements across European markets.
Product Type:
Instrumentation commands premium capital outlays while reagents lock in recurring revenue streams through protocol dependencies.
- Instrumentation:Cell analyzers and sorters incorporate laser modules, fluidic systems, and detector arrays spanning 350-800 nm wavelengths. German pharmaceutical corridors in Munich and Heidelberg drive demand for high-parameter systems with validated GMP protocols. IVDR compliance documentation elevates procurement timelines and vendor selection criteria.
- Reagents:Fluorochrome-conjugated antibodies, calibration beads, and sheath fluids generate superior recurring margins through locked-in experimental protocols. Academic medical centers in the Netherlands and Sweden accelerate 40+ color panel adoption, intensifying consumable throughput.
- Software:Data acquisition platforms and unmixing algorithms enable spectral compensation and automated population gating. Cloud-native deployments are gaining traction among decentralized pathology networks.
- Accessories:Replacement lasers, tubing assemblies, and optical filters support instrument longevity. Service contracts bundle these components with preventive maintenance schedules.
Mature deployment sits with Instrumentation. Newer deployment is concentrated in Software.
Application:
Research intensity and regulatory submission requirements differentiate application segments by margin potential and technical support needs.
- Cancer Research:Immunophenotyping and minimal residual disease monitoring dominate hospital laboratory workflows. France and Germany concentrate spending on clinical-grade systems with IVDR-aligned documentation for diagnostic use.
- Immunology:CAR-T development programs multiply across European contract research organizations, expanding fastest. Cambridge-Oxford-London biotech triangle demands transparent per-test pricing for milestone-based cell therapy contracts.
- Drug Development:High-content screening and lead optimization workflows utilize flow cytometry for compound efficacy profiling. Pharmaceutical companies negotiate unbundled hardware and consumable pricing.
- Stem Cell Research:Pluripotency marker analysis and differentiation tracking support regenerative medicine pipelines. Heidelberg-Munich corridor generates clustered demand for service-intensive deployments.
Volume concentration rests with Cancer Research. Steepest expansion trajectory belongs to Immunology.
End User:
Procurement sophistication and regulatory exposure segment end users by contract structure and application support intensity.
- Pharmaceutical Companies:Cell therapy developers mandate GMP-validated platforms with dedicated application specialists. EMA guidance on identity, purity, and potency testing shapes instrument specifications and procurement timelines.
- Hospitals:High-complexity laboratories in France and Germany consolidate around vendors with established IVDR technical documentation. Notified body capacity constraints extend conformity assessments to 18-24 months.
- Academic Institutions:Netherlands and Swedish medical centers pioneer spectral detection architectures with 40+ color panels. Research funding cycles drive capital equipment refresh timelines.
- Clinical Laboratories:Middleware integration challenges with legacy laboratory information systems require costly custom interface development. Poland and Hungary show whitespace for compact benchtop systems.
Service intensity peaks with Pharmaceutical Companies. Procurement flexibility is expanding fastest among Clinical Laboratories.
Technology:
Detection architecture and analytical depth differentiate technology segments by parameter scalability and workflow compression.
- Multicolor Analysis:Spectral unmixing algorithms resolve fluorochrome overlap computationally, enabling 40+ parameter panels. Full-spectrum detectors displace conventional optical filters in Netherlands and Swedish installations.
- Cell Sorting:Fluorescence-activated cell separation supports single-cell genomics and rare population isolation. GMP-compliant sorters command premium positioning in cell therapy manufacturing.
- Cell Identification:Immunophenotyping workflows quantify marker expression for diagnostic classification. EU IVDR risk-classification restructure elevates systems to Class C or D categories.
- Imaging:Image-streaming cytometry combines morphological visualization with quantitative fluorescence. Core facilities evaluate functional substitution against traditional microscopy workflows.
Established penetration rests with Cell Identification. Parameter scalability is climbing fastest in Multicolor Analysis.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German laser module manufacturing anchors European instrument supply chains, while reagent production concentrates in Swiss and Dutch chemical corridors. Pharmaceutical R&D clustering across the continent generates heterogeneous demand patterns for analytical platforms.
Germany
Heidelberg-Munich biotechnology corridor drives demand for GMP-validated cell analyzers with dedicated application support. IVDR notified body capacity constraints in Berlin and Hamburg extend conformity assessments to 18-24 months, compressing hospital procurement timelines. Bavarian pharmaceutical clusters prioritize service-intensive instrument deployments with validated protocols.
France
Paris-Saclay research plateau and Lyon biotech hub concentrate immunophenotyping demand for clinical-grade systems. ANSM oversight aligns with EMA cell therapy guidance, mandating flow cytometry for identity and potency testing. High-complexity hospital laboratories in Île-de-France consolidate procurement around established IVDR technical documentation.
United Kingdom
Cambridge-Oxford-London biotech triangle accelerates CAR-T development programs with milestone-based contract structures. MHRA post-Brexit regulatory framework maintains alignment with IVDR risk classifications for clinical diagnostics. Contract research organizations drive service unbundling, negotiating transparent per-test pricing for cell therapy characterization.
Netherlands
Leiden-Utrecht life sciences corridor pioneers spectral detection architectures with 40+ color panel adoption. EMA headquarters in Amsterdam shapes analytical platform specifications for pharmaceutical end users seeking regulatory-aligned procurement. Academic medical centers in Rotterdam accelerate full-spectrum detector deployment for deep phenotyping workflows.
Sweden
Stockholm-Uppsala pharmaceutical cluster advances multicolor analysis for single-cell genomics applications. Swedish Medical Products Agency enforces IVDR compliance timelines that favor vendors with established notified body relationships. Karolinska Institute drives parameter scalability requirements for immunotherapy monitoring protocols.
Europe Flow Cytometry Market Competitive Landscape
Global majors compete with regional champions across service network density and regulatory documentation depth. Market structure tilts toward consolidated instrumentation supply with fragmented reagent specialization. Three archetypes dominate: full-platform vendors with captive laser manufacturing, service-intensive specialists with region-dedicated application teams, and bundled-workflow providers leveraging adjacent analytical technologies. Competitive moves center on IVDR technical documentation accumulation and unbundled pricing negotiations for pharmaceutical contracts.
Among US-based diversified life sciences conglomerates, Becton Dickinson and Company, Beckman Coulter, and Thermo Fisher Scientific occupy positions spanning the full-platform and bundled-workflow archetypes. Becton Dickinson exemplifies captive manufacturing strategy for optical components. Beckman Coulter anchors service-intensive positioning through European application specialist networks. Thermo Fisher Scientific represents workflow convergence, bundling flow cytometry with mass spectrometry capabilities for core facility penetration. German and Japanese specialists including Miltenyi Biotec, Sysmex Partec, and Sony Biotechnology sit within regional champion tier, leveraging geographic proximity for rapid service response.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Beckman Coulter |
| Thermo Fisher Scientific |
| Sysmex Partec |
| Miltenyi Biotec |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Luminex |
| Sony Biotechnology |
| Others |
Pricing and Supply Chain Analysis
Captive laser module manufacturing anchors both supply security and pricing power for full-platform vendors serving European pharmaceutical corridors. Becton Dickinson's in-house production of optical components insulates margin pools from Asian photomultiplier tube volatility while enabling premium positioning for high-parameter cell analyzers. This integration choice compresses procurement timelines for GMP-validated systems and supports bundled service contracts that lock in recurring revenue.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier vendors from unbundled competitors in active tenders. Three-tier pricing structure across premium, standard, and economy levels reflects IVDR certification grade and dedicated application specialist availability. Cost compression in economy benchtop systems is intensifying because Polish and Hungarian buyers prioritize capital expenditure minimization over service intensity. Contract research organizations in the Cambridge-Oxford-London biotech triangle exhibit lowest price sensitivity, accepting transparent per-test pricing for milestone-based cell therapy contracts.
Supply Chain Analysis
Single-source vulnerability sits with Asian-manufactured photomultiplier tubes and avalanche photodiodes that European instrument vendors draw from concentrated suppliers. Laser modules source from German captive facilities, fluidic systems from Swiss precision manufacturers, and optical filters from Japanese specialty suppliers. Tariff exposure on Chinese-sourced electronic components presents structural risk to margin pools. Distribution runs through direct sales teams for pharmaceutical accounts and authorized distributors for hospital laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints in Germany and the Netherlands prop pricing power by extending IVDR certification timelines to 18-24 months, creating supply-constrained vendor selection dynamics.
For Market Incumbents: Hedge against spectral flow cytometry substitution by accelerating full-spectrum detector roadmaps and cloud-native data platform integration. Secure backward integration into solid-state laser modules to protect margin pools from Asian component volatility. Accumulate IVDR technical documentation depth to exploit notified body relationship advantages in active hospital tenders.
For New Entrants and Emerging Players: Begin with compact benchtop systems targeting Poland and Hungary, where clinical flow cytometry penetration lags Western European benchmarks by substantial margins. Prioritize IVDR-aligned documentation investment over feature depth to accelerate market access. Pursue direct-to-clinical-laboratory distribution partnerships that bypass entrenched hospital procurement consolidations.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-technology acquisitions by diversified life sciences conglomerates seeking workflow convergence capabilities. Five-to-ten year viability favors vendors with established EMA regulatory alignment and GMP protocol validation depth. Monitor AI-enabled automated gating adoption curves as inflection indicator for cloud-native data platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Accumulation | Accelerates conformity assessment timelines through notified body relationship depth in Berlin and Hamburg. |
| Spectral Detection Architecture Migration | Enables 40+ color panel differentiation against conventional compensation-based systems in Dutch and Swedish centers. |
| AI-Enabled Automated Gating Development | Compresses inter-laboratory variability for decentralized pathology networks under EMA cell therapy guidance. |
| Service Unbundling Negotiation Capability | Captures milestone-based contract structures from Cambridge-Oxford-London CAR-T development programs. |
| Point-of-Care Benchtop System Launch | Addresses whitespace in Polish and Hungarian clinical laboratories with IVDR-aligned compact architectures. |
Research Methodology
Document review covered EMA guidance publications, IVDR conformity assessment databases, and EFSI funding disclosures, complemented by interviews with flow cytometry platform directors, hospital laboratory managers, pharmaceutical cell therapy development leads, and notified body certification specialists. Secondary validation drew from EU medical device registration databases, GMP inspection records, and academic medical center procurement tender archives. Bottom-up instrumentation and reagent demand modeling triangulated against top-down European pharmaceutical R&D expenditure allocation.
Cross-referencing historical adoption curves against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, application intensity, end-user procurement sophistication, and technology detection architecture. CAGRs were derived from weighted scenario analysis incorporating EMA regulatory timeline assumptions and CAR-T manufacturing expansion trajectories. Forecast inputs incorporated spectral detection adoption rates and AI-enabled gating penetration patterns.
Notified body capacity constraints, CAR-T clinical trial suspension events, and Asian component supply disruptions are the dominant revision risks for demand and pricing assumptions. Forecasts reflect documented regulatory timelines and pharmaceutical pipeline disclosures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Drug Discovery and Development Laboratory Services Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Biobank Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Recombinant Factor C Assay Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Drug Discovery Services Market