
 ASEAN Switchgear Market | 2026-2036
ASEAN Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Switchgear Market Insights
IEC 62271-100 certification-grade switchgear is unwinding legacy procurement patterns across ASEAN power infrastructure. ABB Ltd leverages its regional manufacturing footprint to anchor utility tenders in Indonesia and Thailand. Siemens AG sustains technology leadership through vacuum interrupter specialization. Schneider Electric SE competes on digital switchgear integration with grid automation platforms.
Switchgear comprises electrical disconnecting, switching, and protective equipment engineered to rated voltages up to 52 kV for medium-voltage networks and beyond, utilizing vacuum interrupters, SF6 gas insulation, or air-insulated busbar systems to control power flow and isolate fault currents. Circuit breakers dominate product-type revenue pools due to mandatory replacement cycles in aging ASEAN distribution networks. Vacuum technology captures expanding share as utilities retire SF6-dependent installations under emerging environmental compliance frameworks. Gas insulated switchgear retains premium positioning where space-constrained urban substations in Singapore and Kuala Lumpur command compact footprint solutions.
Thailand's Provincial Electricity Authority, Indonesia's PLN, and Malaysia's ST enforce divergent grid code specifications that fragment product homologation requirements across ASEAN member states. BIS-equivalent national standards in Vietnam and Philippines add further certification layers for cross-border equipment suppliers. Stakeholders must monitor regulatory harmonization momentum under the ASEAN Power Grid initiative to anticipate whether unified technical standards will consolidate supplier landscapes or preserve country-specific qualification barriers.
Market Dynamics
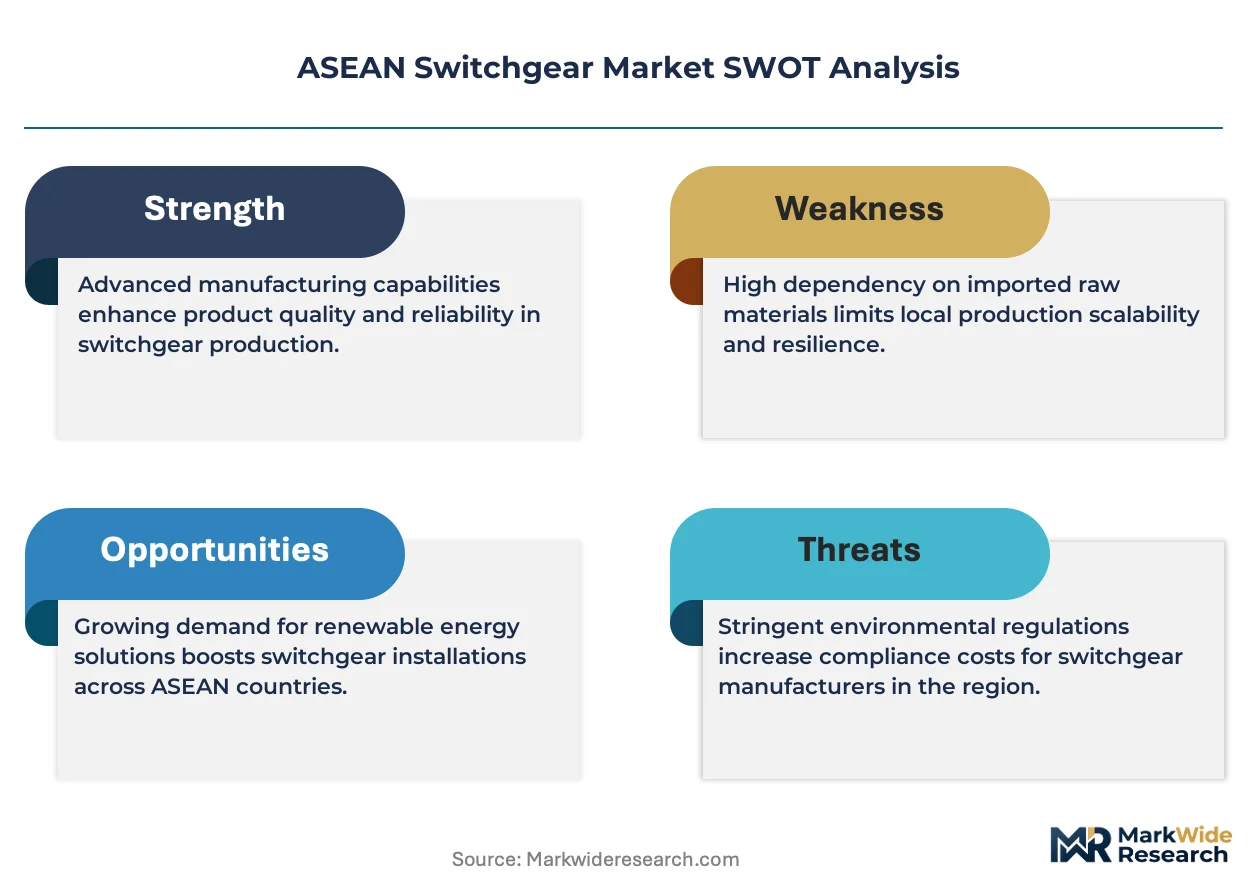
SF6 phase-out mandates across ASEAN member states are forcing accelerated technology transitions in medium-voltage infrastructure, compressing supplier qualification timelines and reshaping procurement specifications toward vacuum interrupter architectures.
Growth Catalysts
- Grid Modernization Mandates:Indonesia's PLN and Thailand's Provincial Electricity Authority are executing substation upgrade programs that specify IEC 62271-100 certified assemblies, creating immediate demand pull for higher-specification equipment.
- Environmental Compliance Frameworks:Emerging national regulations restricting sulfur hexafluoride emissions are accelerating retirement schedules for gas-insulated switchgear installations in urban substations across Singapore and Kuala Lumpur.
- Urban Densification:Space-constrained metropolitan load centers in Manila and Ho Chi Minh City are specifying compact gas-insulated switchgear configurations despite premium positioning, sustaining revenue pools for footprint-optimized designs.
Market Restraints
- Copper and Aluminum Volatility:Raw material price swings for conductive busbar systems are compressing margin stability for air-insulated switchgear manufacturers serving price-sensitive distribution segments.
- Fragmented Certification Requirements:Divergent grid code specifications enforced by Thailand's PEA, Indonesia's PLN, and Malaysia's ST are multiplying homologation costs for cross-border equipment suppliers.
- Technical Skill Scarcity:Specialized vacuum interrupter maintenance expertise remains concentrated in Singapore and Bangkok, limiting deployment velocity in secondary Vietnamese and Philippine markets.
Strategic Opportunities
- Digital Switchgear Integration:Grid automation platform convergence with condition monitoring sensors is creating white space for suppliers offering predictive maintenance-enabled circuit breaker assemblies.
- Vietnam Secondary Cities:Underpenetrated provincial load centers outside Hanoi and Ho Chi Minh City present expansion opportunities as EVN accelerates rural electrification programs.
- ASEAN Power Grid Harmonization:Proposed unified technical standards under regional interconnection initiatives could consolidate supplier qualification barriers and reduce cross-border certification friction.
Industry Challenges
- IEC 62271-100 Certification Timelines:Extended testing protocols for vacuum interrupter endurance are delaying product launches and compressing competitive response windows.
- Legacy SF6 Infrastructure Integration:Mixed-technology substations requiring interoperability between retiring gas-insulated and incoming vacuum-based systems are complicating engineering specifications and commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Switchgear Market |
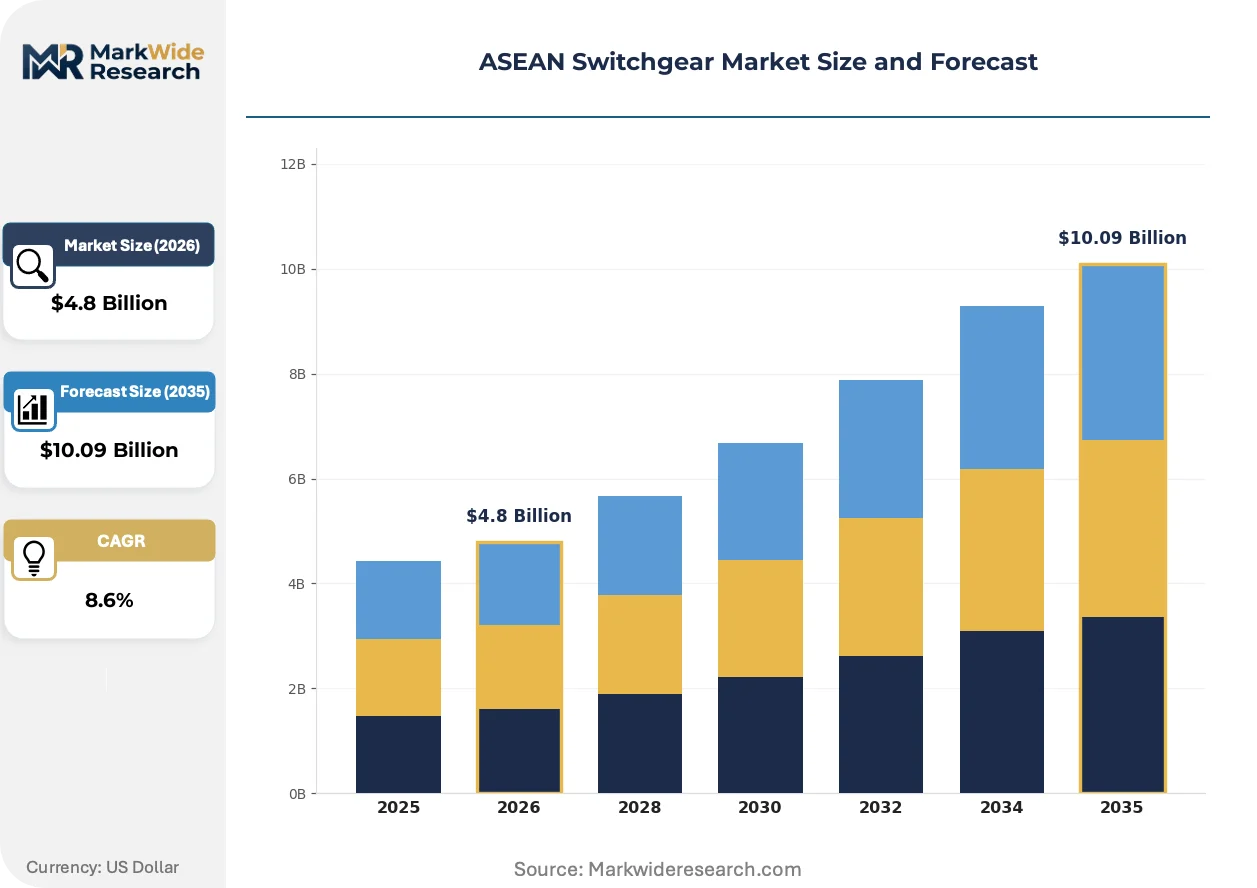
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Isolators, Reclosers, Fuse Gear Technology: Vacuum, Air Insulated, Gas Insulated, SF6 End User: Utilities, Industrial, Commercial, Residential Installation Method: Indoor, Outdoor, Wall-Mounted, Free-Standing |
| Companies Covered | ABB Ltd, Siemens AG, Schneider Electric SE, Mitsubishi Electric Corporation, Hitachi Energy Ltd, Eaton Corporation PLC, Fuji Electric Co., Ltd., HD Hyundai Electric, Rockwell Automation Inc., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Switchgear Market Trends and Innovations
Vacuum insulation technology is actively displacing established SF6-dependent architectures across ASEAN medium-voltage infrastructure, while digitalization mandates and procurement model evolution are simultaneously reshaping supplier-customer relationships.
Vacuum interrupter technology is decomposing the historical dominance of sulfur hexafluoride gas insulation in medium-voltage switchgear assemblies. Thailand's Provincial Electricity Authority and Vietnam's EVN are specifying vacuum-based circuit breakers for all new substation deployments above 24 kV. This technology transition is compressing the addressable market for SF6 gas handling equipment and reconfiguring supplier service revenue models toward vacuum chamber refurbishment.
ASEAN member states are transposing IEC 62271-100 standards into national grid codes with country-specific testing protocols. Indonesia's PLN and Malaysia's ST have enacted divergent certification requirements that fragment equipment qualification pathways. Medium-voltage circuit breaker suppliers are responding by establishing in-country testing partnerships rather than centralized regional certification.
Utility procurement departments are unbundling switchgear supply from installation and commissioning services, creating discrete contract vehicles for equipment-only transactions. This purchasing pattern shift is compressing margins for integrated solution providers while enabling specialized local contractors to capture installation revenue pools. The disaggregation is most visible in Thailand's Provincial Electricity Authority tenders, where equipment and EPC scopes now separate at bid stage.
ASEAN Switchgear Market Segmentation
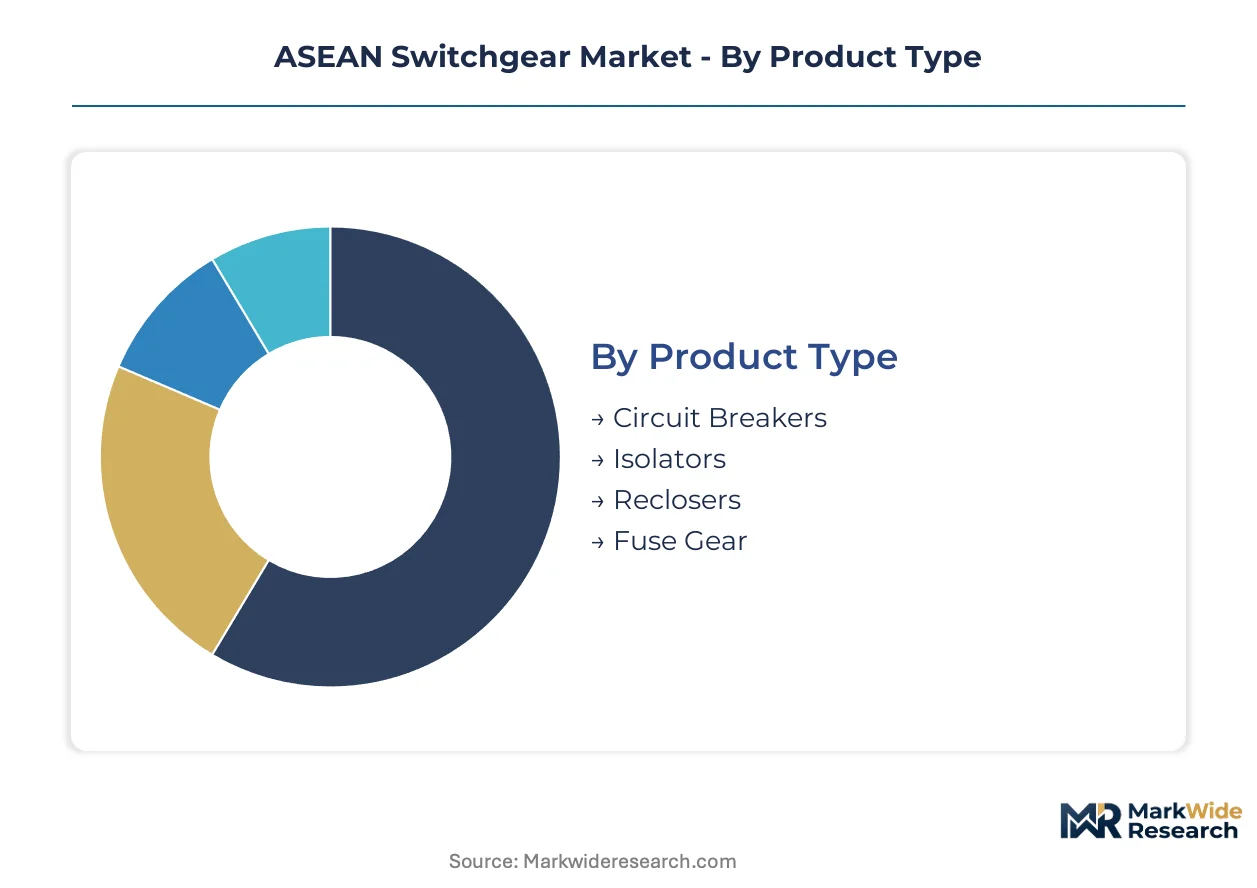
Switchgear procurement across ASEAN fragments sharply across technology generations and end-user sophistication. Segment boundaries determine supplier qualification pathways, certification requirements, and margin structures.
Product Type:
Domestic demand concentrates in circuit breakers and isolators serving utility substation programs, while fuse gear exports primarily serve Philippine and Vietnamese distribution contractors.
- Circuit Breakers:Medium-voltage assemblies rated 12-36 kV dominate procurement volumes. Thailand's Provincial Electricity Authority and Indonesia's PLN specify vacuum interrupter configurations for all new substation deployments above 24 kV, compressing SF6 replacement cycles.
- Isolators:Disconnect switches engineered for visible isolation points in air-insulated substations. Malaysian transmission utilities favor three-pole motorized variants for remote-controlled switching operations in Peninsular grid extensions.
- Reclosers:Self-contained fault protection devices for overhead distribution lines. Vietnam's EVN deploys single-phase hydraulic reclosers across Mekong Delta rural electrification corridors.
- Fuse Gear:Current-limiting fuse assemblies for transformer protection. Philippine electric cooperatives specify expulsion fuse cutouts for cost-sensitive secondary distribution networks.
Circuit breakers hold the largest share; momentum sits with reclosers as rural automation accelerates.
Technology:
Cost tiers separate premium vacuum systems from commodity air-insulated architectures, with gas-insulated configurations commanding niche urban premiums.
- Vacuum:Ceramic-enclosed interrupter technology eliminates SF6 environmental compliance burdens. Singapore Power and Bangkok's Metropolitan Electricity Authority mandate vacuum for all indoor substation retrofits.
- Air Insulated:Open-busbar designs for space-available outdoor installations. Indonesian PLN procurement favors air-insulated switchgear for Java-Bali transmission corridor expansions where land constraints are minimal.
- Gas Insulated:Compact SF6-insulated assemblies for footprint-constrained applications. Kuala Lumpur's Tenaga Nasional Berhad specifies gas-insulated switchgear for urban underground substations despite emerging phase-out pressures.
- SF6:Legacy sulfur hexafluoride technology facing accelerated retirement. Philippine grid operators maintain existing SF6 installations while blocking new procurement under draft environmental regulations.
Vacuum technology holds the largest share; gas-insulated configurations are climbing the fastest as urban densification intensifies.
End User:
Volume concentrates in utility tenders, while industrial and commercial segments fragment across facility-scale applications with divergent technical specifications.
- Utilities:Transmission and distribution operators procuring substation-grade equipment. Vietnam's EVN and Thailand's PEA execute centralized tenders with IEC 62271-100 certification mandates.
- Industrial:Manufacturing facilities requiring arc-resistant switchgear for process continuity. Indonesian smelter complexes in Sulawesi specify withdrawable circuit breaker configurations for maintenance access.
- Commercial:High-rise developments and data centers demanding compact, low-maintenance solutions. Singapore's Marina Bay financial district specifications favor digital switchgear with integrated condition monitoring.
- Residential:Low-voltage distribution boards and ring main units for housing estates. Malaysian developer procurement prioritizes cost-optimized air-insulated ring main units for township electrification.
Utilities hold the largest share; commercial applications are expanding most quickly as building automation standards tighten.
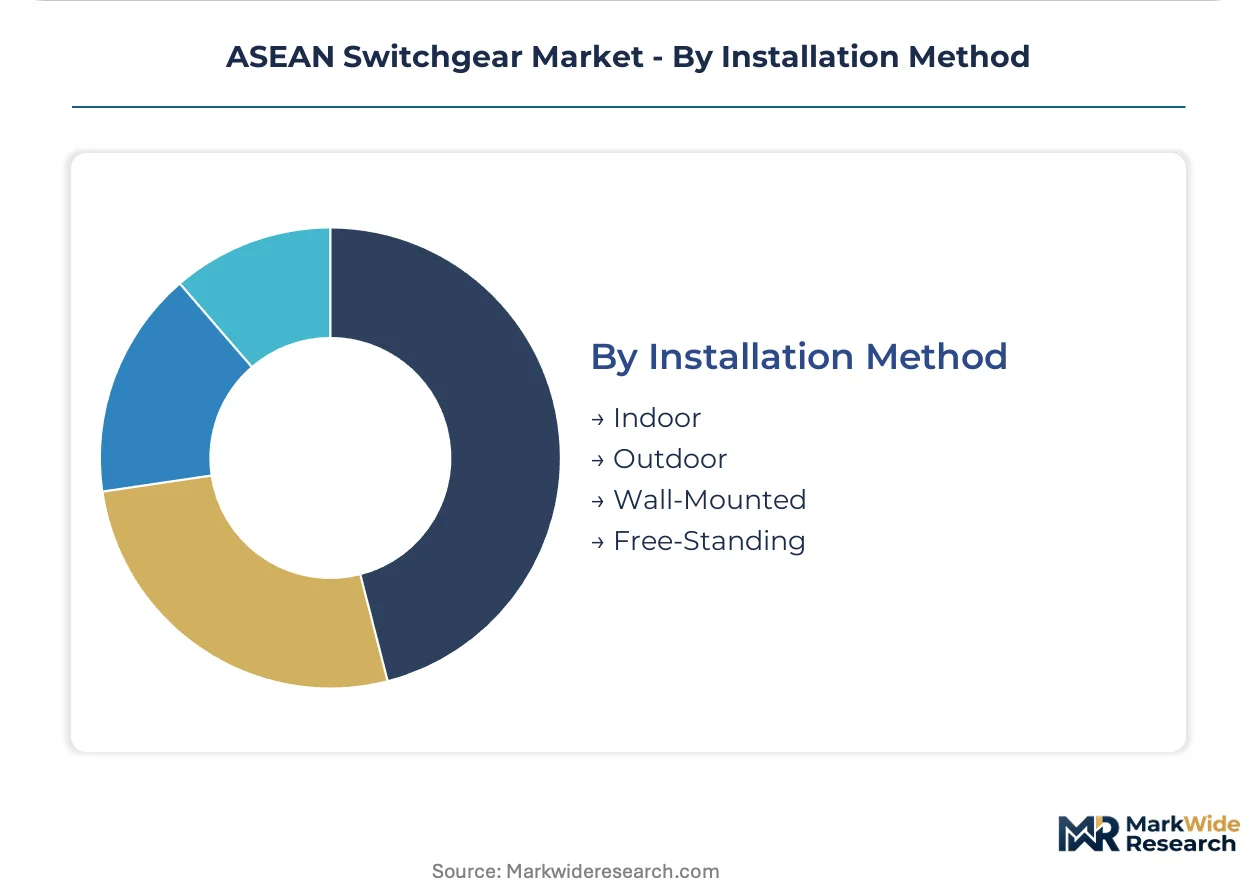
Installation Method:
Customer type separates utility-scale outdoor installations from commercial indoor deployments, with mounting configurations determining enclosure engineering requirements.
- Indoor:Metal-enclosed switchgear for controlled-environment substations. Bangkok's Metropolitan Electricity Authority specifies indoor configurations for all new 22 kV distribution substations in central business districts.
- Outdoor:Weather-resistant housings for exposed installations. Indonesian PLN deploys outdoor kiosk-type switchgear across Java's overhead distribution network.
- Wall-Mounted:Compact units for space-restricted commercial and residential applications. Philippine condominium developers favor wall-mounted ring main units for basement electrical rooms.
- Free-Standing:Floor-mounted assemblies for industrial facilities with dedicated electrical rooms. Vietnamese manufacturing zones specify free-standing withdrawable switchgear for heavy-industry power centers.
Outdoor installations hold the largest share; indoor configurations are gaining share fastest as urban underground substation construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supplier manufacturing footprints cluster in Thailand and Singapore, creating asymmetric access to utility procurement channels across Southeast Asia. Technology transfer partnerships with European majors concentrate vacuum interrupter assembly capacity in these hubs. National grid code divergence forces parallel certification investments, elevating barriers for cross-border equipment flows.
Indonesia
Java-Bali transmission corridor expansions drive air-insulated switchgear procurement from domestic fabricators. Perusahaan Listrik Negara enforces BIS-equivalent SNI certification for all medium-voltage assemblies above 20 kV. Surabaya industrial zones absorb withdrawable circuit breaker configurations for smelter complexes in Sulawesi.
Thailand
Provincial Electricity Authority tenders specify vacuum interrupter technology for substation deployments above 24 kV. The Ministry of Energy mandates IEC 62271-100 compliance for grid-connected equipment under national reliability frameworks. Bangkok Metropolitan Electricity Authority concentrates indoor switchgear retrofits in central business district underground substations.
Vietnam
Electricity of Vietnam accelerates rural electrification across Mekong Delta provinces using single-phase hydraulic reclosers. The Institute of Energy requires type testing under national grid code transpositions of IEC standards. Ho Chi Minh City load centers specify compact gas-insulated configurations for space-constrained urban substations.
Singapore
Singapore Power mandates vacuum technology for all indoor substation retrofits under environmental compliance timelines. The Energy Market Authority enforces strict SF6 emission reporting for existing gas-insulated installations. Marina Bay financial district specifications favor digital switchgear with integrated condition monitoring platforms.
Malaysia
Tenaga Nasional Berhad specifies gas-insulated switchgear for Kuala Lumpur urban underground substations despite phase-out pressures. The Suruhanjaya Tenaga administers divergent certification requirements that fragment equipment qualification pathways. Peninsular grid extensions favor three-pole motorized isolators for remote-controlled switching operations.
ASEAN Switchgear Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. European majors anchor premium positioning through vacuum interrupter specialization and digital integration capabilities. Regional Asian fabricators compete on cost-optimized air-insulated assemblies for price-sensitive distribution segments. Dominant competitive moves include in-country testing partnerships to navigate fragmented certification requirements and unbundling of equipment supply from installation services.
Within the European technology tier, ABB Ltd and Siemens AG exemplify vacuum interrupter leadership, while Schneider Electric SE occupies a position emphasizing digital switchgear convergence with grid automation platforms. Among Asia-Pacific-based suppliers, Mitsubishi Electric Corporation and Hitachi Energy Ltd represent integrated industrial conglomerates with captive electrical equipment divisions. These five entities collectively anchor the competitive landscape, with HD Hyundai Electric and Fuji Electric Co., Ltd. serving as regional specialists in cost-optimized configurations for secondary markets.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Hitachi Energy Ltd |
| Eaton Corporation PLC |
| Fuji Electric Co., Ltd. |
| HD Hyundai Electric |
| Rockwell Automation Inc. |
| Others |
Pricing and Supply Chain Analysis
Vacuum interrupter technology substitution for SF6 gas insulation is simultaneously redrawing procurement economics and supplier geography across ASEAN switchgear markets. This technology pivot elevates ceramic-enclosed vacuum chamber sourcing from Japan and South Korea while compressing margins on legacy gas-handling equipment as utilities accelerate environmental compliance timelines.
Pricing Analysis
IEC 62271-100 certification dictates the pricing tier structure across ASEAN procurement channels. Three-tier pricing structure across premium vacuum systems, standard air-insulated configurations, and economy fuse gear separates utility-grade substation equipment from cost-sensitive distribution segments. Cost compression in air-insulated switchgear is intensifying because Indonesian PLN procurement favors open-busbar designs for Java-Bali corridor expansions. Philippine electric cooperatives exhibit the highest price sensitivity, while Singapore Power tenders for Marina Bay financial district command premium positioning for digital-integrated assemblies.
Supply Chain Analysis
Ceramic vacuum interrupter substrate supply from Kyushu manufacturing clusters underwrites technology transition viability for ASEAN utilities. Thailand and Singapore concentrate regional assembly capacity, drawing from Japanese ceramic substrate suppliers, Chinese copper busbar fabricators, and German digital control module producers. Single-source vulnerability concentrates in vacuum chamber ceramic metallization processes. Distribution runs through utility procurement departments unbundling equipment supply from EPC services, with specialized local contractors capturing installation revenue pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology fragmentation across vacuum, air-insulated, and gas-insulated architectures creates specialized supply niches as divergent national grid codes multiply qualification pathways. The unbundling of equipment procurement from installation services fragments vendor relationships and opens entry points for focused specialists.
For Market Incumbents: Shield established utility relationships by accelerating in-country testing partnerships to navigate Indonesia's SNI and Vietnam's Institute of Energy certification divergences. Deepen backward integration into vacuum interrupter refurbishment services as SF6 phase-out compresses replacement cycles and shifts recurring revenue models. Prioritize certification maintenance investments over price competition in Thailand PEA tenders where IEC 62271-100 compliance gates market access.
For New Entrants and Emerging Players: IEC 62271-100 certification fast-track partnerships with Bangkok and Singapore testing laboratories unlock Thailand and Singapore utility procurement channels without centralized regional qualification. Vietnam's Mekong Delta rural electrification corridors present the most penetrable geography, with EVN single-phase recloser deployments favoring specialized automation suppliers over integrated majors. Position through equipment-only contract vehicles that capture margin from Thailand PEA's separated tender structures.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors vacuum interrupter specialists with captive ceramic supply relationships and established utility service contracts. Target acquisition archetypes include regional fabricators with SNI certification and existing PLN supply relationships that can anchor Southeast Asian manufacturing footprints. Watch for harmonization momentum under ASEAN Power Grid initiatives as the signal indicating whether qualification barriers consolidate or fragment further.
| Strategic Initiative | Industry Significance |
|---|---|
| In-Country Testing Partnership | Establishes direct pathway through Indonesia's SNI and Vietnam's Institute of Energy certification requirements. |
| Vacuum Interrupter Service Network | Captures recurring revenue as Thailand PEA and Singapore Power accelerate SF6 replacement schedules. |
| Digital Switchgear Platform Integration | Aligns with Singapore Marina Bay specifications for condition monitoring and predictive maintenance capabilities. |
| Rural Electrification Recloser Supply | Targets EVN Mekong Delta deployment programs with specialized automation solutions. |
| Equipment-Only Contract Positioning | Exploits Thailand PEA procurement unbundling to capture margin from separated equipment tenders. |
Research Methodology
A spread of perspectives from utility procurement officers at Indonesia's PLN and Thailand's PEA, vacuum interrupter manufacturing engineers, EPC contractors, and national standards administrators converged on the working assumptions for technology transition timelines. Primary fieldwork combined structured interviews with secondary validation through IEC standard transposition documents, national grid code filings, and utility tender specifications. Trade flow analysis from regional customs databases and equipment import records anchored supply chain mapping. Bottom-up utility expenditure tracking and top-down infrastructure investment forecasts were cross-referenced for triangulation.
Product type, technology generation, end-user sophistication, and installation method dimensions structured the analytical framework across the projection horizon. CAGRs were derived from utility capital expenditure trajectories and technology replacement cycle analysis. Modeled inputs included Indonesia's Java-Bali transmission corridor expansion schedules, Vietnam's rural electrification program pacing, and Singapore's SF6 phase-out enforcement timelines.
Underlying assumptions cover sustained grid modernization funding across ASEAN member states, with deviation risk concentrated in regulatory harmonization delays and raw material price volatility for copper and aluminum conductive systems. Practitioners should keep alternative scenarios live as national environmental compliance timelines and ASEAN Power Grid standardization momentum evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Reed Switches Sensors Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
North America Medium Voltage Switchgear Market
Switches
Differential Pressure Switches Market
Switches
Global Switchgear Market
Switches
UK Reed Sensors Switches Market
Switches
Proximity Switches Market
Switches
Vibration Level Switch Market
Switches
Push Button Dropper Market
Switches
Asia Pacific Reed Sensors Switches Market
Switches
Digital Crosspoint Switches Market
Switches
Saudi Arabia Switchgear Market
Switches
Antenna Switch Module Market
Switches
Electric Switch Market
Switches
Smart Home Switches Market
Switches
Tactile Switch Keyboard Market