
 Fixed Switch Cabinet Market | 2026-2036
Fixed Switch Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Switch Cabinet Market Analysis
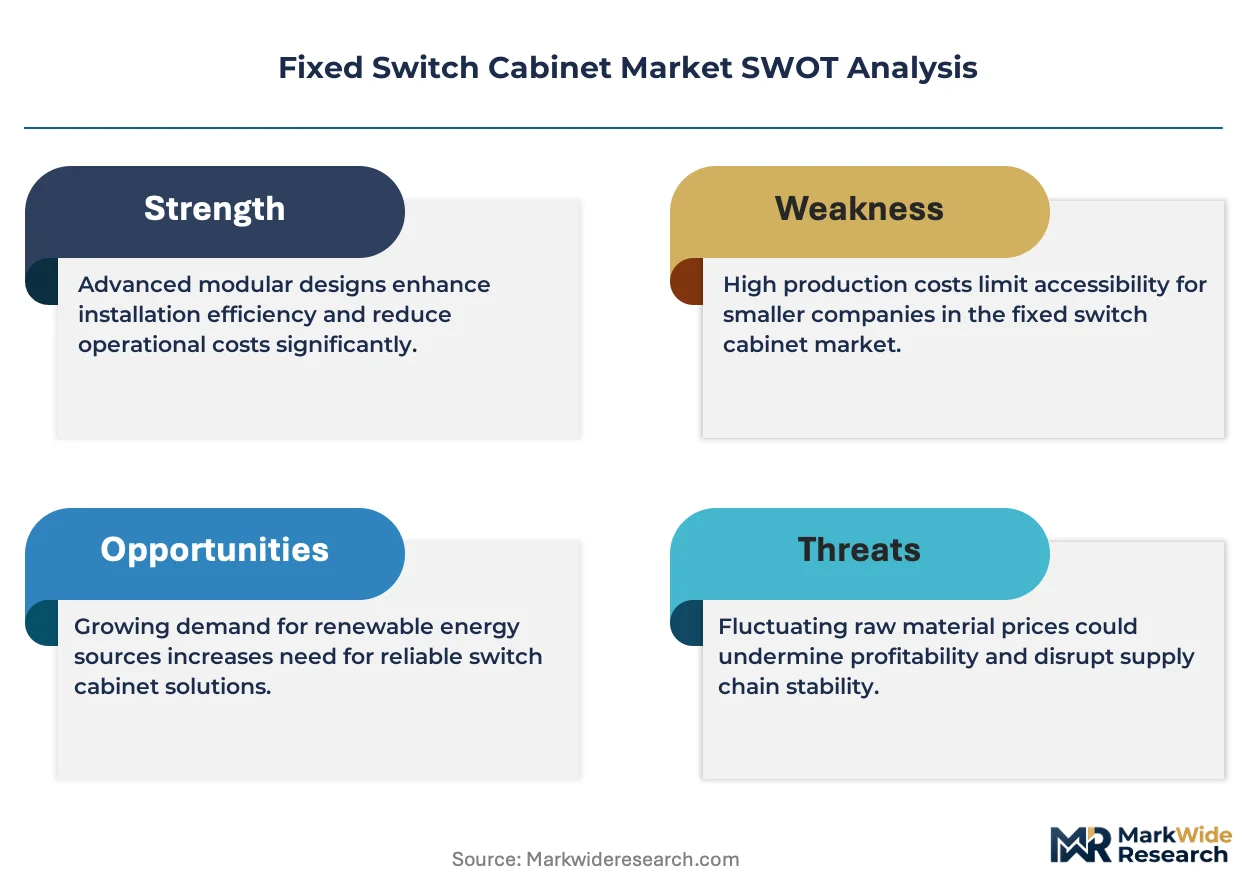
REACH compliance is rebalancing the cost-of-entry calculus for European manufacturers of fixed switch cabinets, forcing reformulation of insulating materials and extended supply-chain documentation. ABB Ltd. leverages its captive gas-insulated technology portfolio to sustain premium positioning across Nordic utility tenders. Schneider Electric SE anchors its competitive stance through integrated digital monitoring platforms that extend beyond hardware sales. SIEMENS AG dominates the German industrial automation channel with localized production networks.
A fixed switch cabinet is an enclosed assembly of electrical switching and protection devices, typically rated up to 52 kV, designed to control, protect, and isolate power circuits in distribution and sub-transmission networks. Metal enclosed configurations retain the largest installed base due to their cost efficiency and repairability in utility applications. Gas insulated segments command higher margins from space-constrained urban substations and offshore renewable energy platforms. Industrial automation applications are outpacing infrastructure deployment in growth velocity, driven by factory electrification and process reliability mandates.
The IEC 62271 series governs switchgear performance and testing protocols, while the EU F-Gas Regulation restricts fluorinated insulating media with high global warming potential, compelling material transitions across European supply chains. In the United States, NHTSA and OSHA electrical safety standards shape product liability frameworks and installation contractor certification requirements. Stakeholders must monitor evolving carbon-border adjustment mechanisms and regional content rules that will determine competitive access to protected procurement pools.
Market Dynamics
Grid interconnection mandates across Southeast Asia are accelerating fixed switch cabinet deployment, while IEC 62271-200 certification requirements are compressing supplier qualification timelines and reshaping competitive access.
Growth Catalysts
- India's power distribution modernization:State electricity boards are replacing aging electromechanical switchgear with fixed switch cabinets rated for higher fault tolerance. Central Electricity Authority directives mandate arc-flash containment standards that favor metal-enclosed designs.
- Offshore renewable energy platforms:Gas-insulated fixed switch cabinets are penetrating North Sea wind substations where salt corrosion and space constraints eliminate air-insulated alternatives. DNV certification requirements for marine environments favor sealed enclosures.
- EU F-Gas Regulation phase-down:The 2024-2030 stepped reduction in SF6 availability is forcing utilities to specify vacuum interrupter technology. This material transition is expanding the addressable market for SF6-free fixed switch cabinet platforms.
Market Restraints
- Copper and electrical steel price volatility:Raw material input costs for busbar systems and magnetic cores fluctuate with commodity cycles, compressing margins for manufacturers without long-term supply agreements.
- Specialized enclosure fabrication concentration:Precision sheet metal forming for IP-rated cabinets concentrates in German and Italian supplier clusters, creating geographic supply risk for non-European OEMs.
- Air-insulated switchgear substitution:Lower-cost AIS alternatives retain cost advantage in rural distribution applications where space constraints do not apply, limiting fixed switch cabinet penetration in price-sensitive segments.
Strategic Opportunities
- Vietnam and Philippines grid expansion:Rural electrification programs in these Southeast Asian markets are creating first-mover advantages for suppliers establishing localized assembly partnerships.
- Digital twin integration:Convergence of fixed switch cabinets with IoT sensor networks and predictive analytics platforms enables recurring software revenue streams beyond hardware sales.
- EU Green Deal public procurement rules:Carbon footprint disclosure requirements and recycled content mandates are creating preference windows for manufacturers with verified lifecycle assessments and circular material flows.
Industry Challenges
- IEC 62271-200 type-test certification timelines:Internal arc classification and mechanical endurance testing require 12-18 month qualification cycles, delaying product launches and locking out speculative entrants.
- Legacy SCADA protocol integration:Utilities operating decades-old control systems demand costly protocol bridges and custom engineering to connect modern fixed switch cabinets with existing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Switch Cabinet Market |
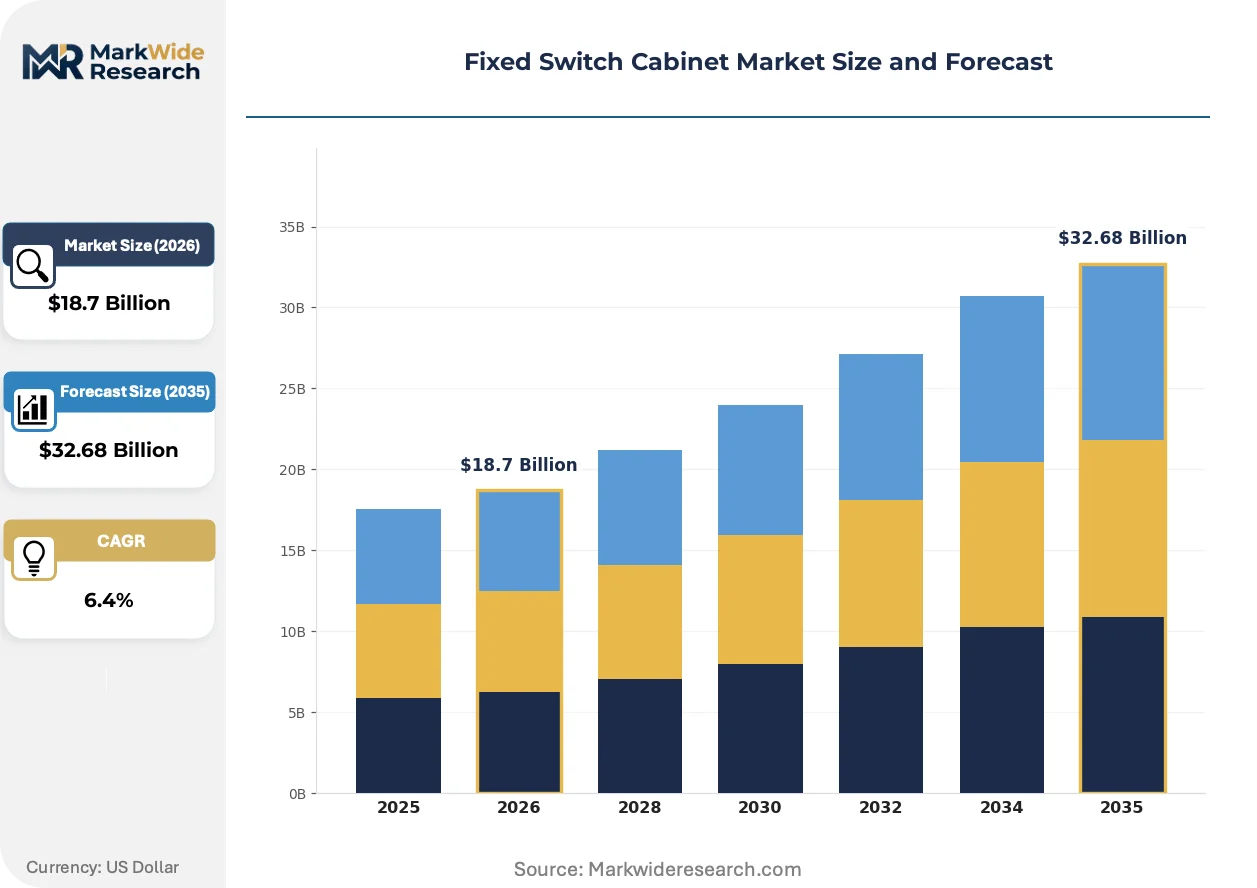
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Enclosed, Air Insulated, Gas Insulated, Compact Application: Power Distribution, Renewable Energy, Industrial Automation, Infrastructure End User: Utilities, Construction, Manufacturing, Commercial Installation Type: Indoor, Outdoor, Substation, Mobile |
| Companies Covered | ABB Ltd., Schneider Electric SE, SIEMENS AG, General Electric Company, Fuji Electric Co. Ltd., Mitsubishi Electric, Eaton Corporation plc, Toshiba Corporation, Hyundai Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Switch Cabinet Market Emerging Trajectories
Digitalization of medium-voltage distribution infrastructure is redefining fixed switch cabinet value propositions, while material science advances and procurement model evolution are compressing traditional hardware-centric business models.
Solid-state circuit protection is expanding into fixed switch cabinet architectures, replacing electromechanical relays with silicon-carbide-based fault isolation. Data center operators and semiconductor fabrication facilities are adopting these platforms for sub-cycle interruption speeds. This technology is expanding into premium industrial segments where process continuity losses dwarf equipment cost differentials.
The EU F-Gas Regulation's 2024 ban on virgin SF6 in new medium-voltage equipment is forcing vacuum interrupter and clean air insulation adoption across European utility procurement. German network operators are specifying SF6-free alternatives in transmission-connected substations. Nordic tenders now mandate lifecycle global warming potential disclosures that disadvantage conventional gas-insulated designs.
Performance-based maintenance contracts are displacing traditional time-based service agreements in utility segments. Equipment availability guarantees and predictive replacement scheduling are replacing scheduled inspections. This shift is most visible in German and Dutch distribution network operators, where unbundled service providers now compete directly with manufacturer service arms.
Fixed Switch Cabinet Market Segmentation
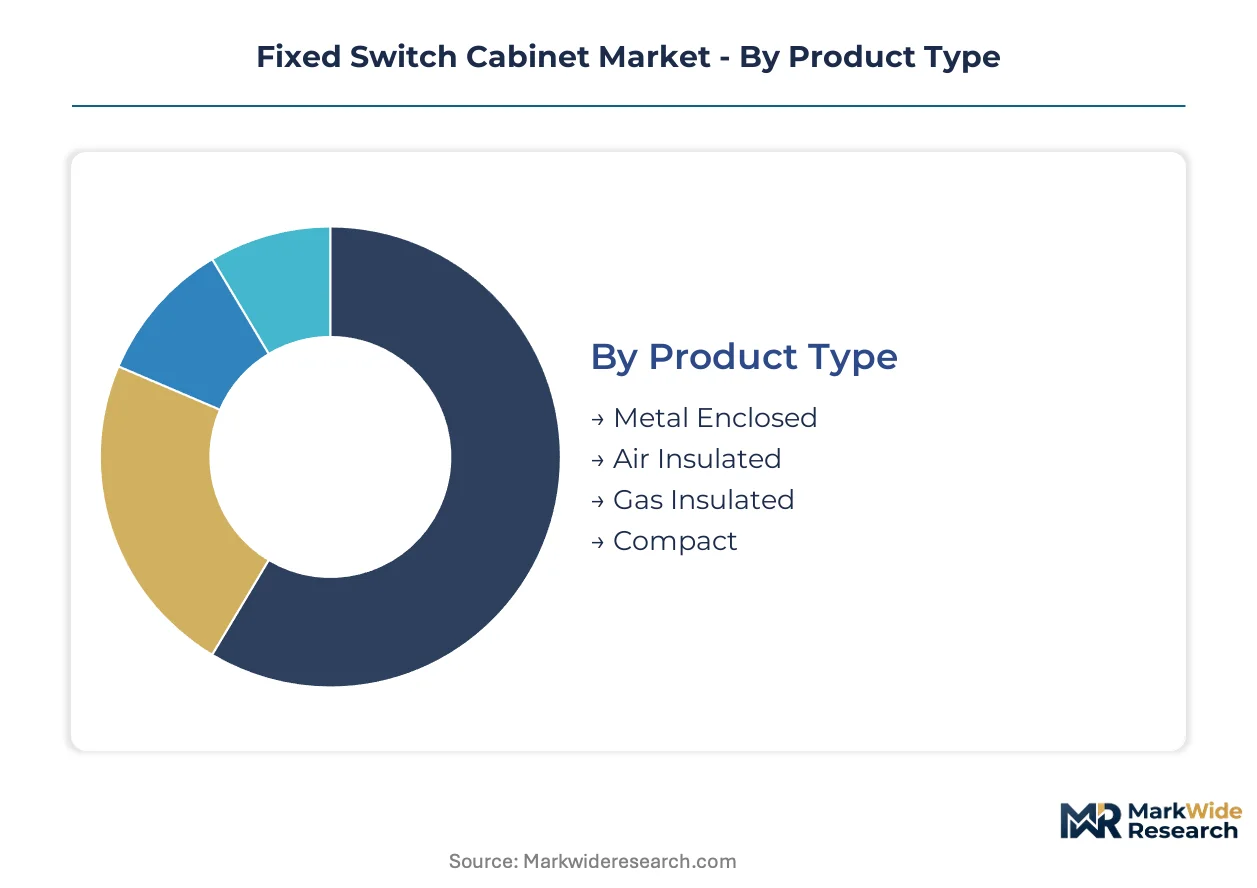
Segmentation in fixed switch cabinets separates commoditized utility procurement from premium industrial applications where arc-flash containment and digital integration command price premiums. Material choices and enclosure ratings determine competitive access to regulated tenders.
Product Type:
Metal-enclosed designs function as standalone assemblies requiring minimal site integration, while gas-insulated variants embed into densely packed substation architectures where footprint constraints dominate.
- Metal Enclosed:Fabricated from cold-rolled steel or aluminum with IP4X-IP65 ingress protection ratings. India's state electricity boards favor these for rural distribution modernization where repairability and field serviceability outweigh space optimization.
- Gas Insulated:Sealed SF6 or clean-air enclosures achieving 3-5x space reduction versus air-insulated equivalents. North Sea offshore wind platforms specify these for salt-marine environments where DNV certification mandates sealed construction.
- Air Insulated:Open busbar designs with natural convection cooling and visible isolation points.
- Compact:Modular factory-assembled units with integrated protection and metering.
Metal Enclosed leads volumes today; Gas Insulated is gaining share fastest.
Application:
Cost tiering separates mission-critical process continuity applications from price-sensitive infrastructure deployment where standardized specifications dominate procurement.
- Power Distribution:Fault isolation and load management in medium-voltage networks up to 52 kV. Southeast Asian grid interconnection projects in Vietnam and the Philippines concentrate demand for IEC 62271-200 certified cabinets with internal arc classification.
- Industrial Automation:Semiconductor fabrication and automotive assembly lines demand sub-cycle interruption speeds. Solid-state protection integration enables premium positioning where downtime costs dwarf equipment differentials.
- Renewable Energy:Collection and step-up functions at solar farms and wind substations.
- Infrastructure:Airport, railway, and hospital electrification with reliability mandates.
Power Distribution commands the largest installed base; Industrial Automation shows the steepest expansion trajectory.
End User:
Customer type determines specification authority—centralized utility procurement favors standardized platforms while fragmented construction channels reward flexible configuration.
- Utilities:State electricity boards and distribution network operators with mandatory arc-flash containment standards. Germany's unbundled distribution operators now specify performance-based availability guarantees rather than time-based maintenance contracts.
- Manufacturing:Process industries with continuous production requirements. Data center operators specify solid-state protection for sub-cycle fault clearing where semiconductor fabrication downtime exceeds equipment cost multiples.
- Construction:Contractor-led procurement for commercial and residential developments.
- Commercial:Office complexes, retail centers, and healthcare facilities with standard reliability requirements.
Utilities dominate procurement volumes; Manufacturing exhibits the most rapid specification upgrading.
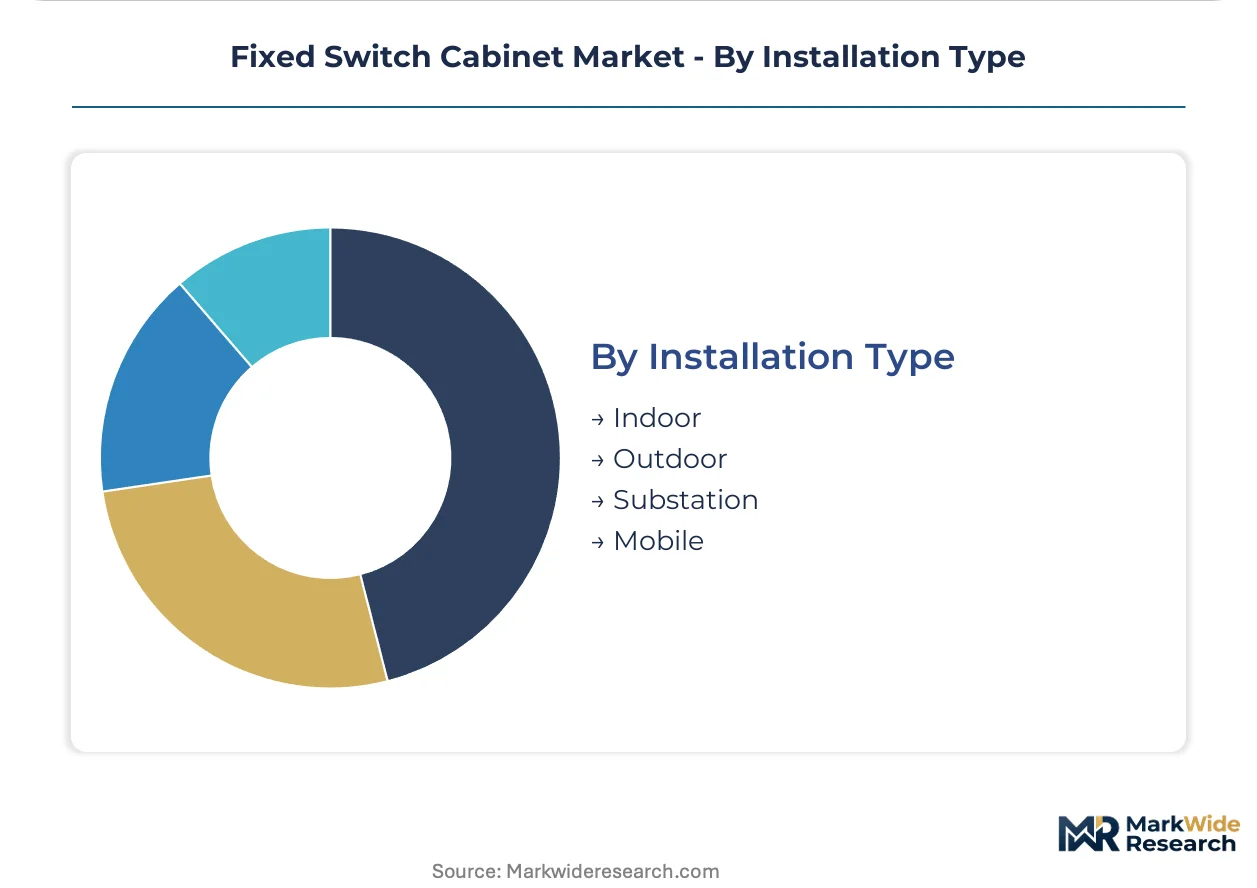
Installation Type:
Environmental exposure requirements separate indoor climate-controlled deployment from outdoor substations demanding corrosion resistance and thermal management.
- Indoor:Climate-controlled electrical rooms with standardized IP ratings. German industrial automation channels favor these for factory floor integration where localized production networks enable rapid configuration.
- Outdoor:Pad-mounted or pole-mounted enclosures with weatherproofing and vandal resistance. Nordic utility tenders specify lifecycle global warming potential disclosures that disadvantage conventional gas-insulated outdoor designs.
- Substation:Integrated into primary distribution infrastructure with busbar connections.
- Mobile:Trailer-mounted or skid-mounted units for temporary power and emergency restoration.
Indoor installations maintain volume leadership; Outdoor configurations are climbing fastest on renewable energy deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized electrical engineers and switchgear technicians concentrate in Germany's industrial belt, India's power infrastructure hubs, and Southeast Asian manufacturing corridors, anchoring regional production capabilities and technical service networks.
Germany
Industrial automation demand from automotive and semiconductor fabrication drives specification upgrades toward solid-state protection platforms. The EU F-Gas Regulation mandates SF6 phase-down by 2030, accelerating vacuum interrupter adoption. Bavaria's manufacturing corridor hosts precision sheet metal fabricators supplying sealed enclosure components to Nordic utility tenders.
India
State electricity boards are replacing aging electromechanical switchgear with fault-tolerant metal-enclosed designs across rural distribution networks. Central Electricity Authority directives enforce arc-flash containment standards that disqualify legacy equipment. Maharashtra's Mumbai-Pune industrial belt concentrates localized assembly partnerships serving Southeast Asian export markets.
Vietnam
Rural electrification programs and grid interconnection projects with neighboring Cambodia and Laos create first-mover opportunities for cabinet suppliers. The national power utility's technical standards increasingly reference IEC 62271-200 certification requirements. Ho Chi Minh City's southern manufacturing zone hosts emerging fabrication facilities targeting ASEAN regional demand.
United States
Data center construction and semiconductor fabrication facility expansion drive demand for sub-cycle interruption speeds in premium industrial segments. NHTSA and OSHA electrical safety standards shape installation contractor certification and product liability frameworks. Texas's Permian Basin and Arizona's Phoenix-Tucson corridor concentrate utility-scale renewable energy substation deployment.
United Kingdom
Offshore wind platform electrification in the North Sea generates demand for DNV-certified gas-insulated cabinets resistant to salt-marine corrosion. The EU Green Deal's carbon-border adjustment mechanisms influence procurement specifications for transmission-connected infrastructure. Scotland's Aberdeen energy cluster anchors marine-rated switchgear engineering expertise serving North Sea renewable projects.
Fixed Switch Cabinet Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive electrical equipment portfolios. Market concentration remains moderate, with top-tier players commanding premium positioning through integrated digital platforms while mid-scale regional fabricators compete on cost and customization velocity. Two archetypes dominate: technology-integrated multinationals leveraging software-hardware convergence, and specialized enclosure fabricators with precision sheet metal capabilities. Competitive moves center on strategic partnerships for localized assembly and portfolio diversification into SF6-free insulation platforms.
Among technology-integrated conglomerates, ABB Ltd. and Schneider Electric SE exemplify the premium-tier archetype through their positioning around digital monitoring ecosystems. SIEMENS AG anchors the German industrial channel with localized production networks. These three occupy positions that extend beyond hardware sales toward recurring service revenue models, representing the competitive direction reshaping value capture in medium-voltage distribution infrastructure.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric SE |
| SIEMENS AG |
| General Electric Company |
| Fuji Electric Co. Ltd. |
| Mitsubishi Electric |
| Eaton Corporation plc |
| Toshiba Corporation |
| Hyundai Heavy Industries |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation's phased SF6 reduction gates qualified supply and premium-tier pricing access for manufacturers with certified clean-air and vacuum interrupter platforms. Buyers in Germany and the Nordic markets now pay structural premiums for lifecycle global warming potential disclosures, while price-sensitive segments in rural India and Southeast Asia prioritize repairable metal-enclosed designs over sealed gas-insulated alternatives.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware-only transactions from performance-based availability guarantees. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Pricing pressure stems from copper and electrical steel commodity volatility, compressing margins for manufacturers without long-term raw material agreements. Utilities in India exhibit highest price sensitivity, while semiconductor fabrication facilities in Germany and the United States accept premium positioning for sub-cycle interruption speeds.
Supply Chain Analysis
Domestic-content mandates in India's power distribution sector and Vietnam's rural electrification programs are reshaping sourcing toward localized assembly partnerships. Precision sheet metal forming concentrates in Germany, Italy, and emerging facilities in Ho Chi Minh City. Raw material dependencies center on copper busbar systems, cold-rolled steel enclosures, and silicon-carbide components for solid-state protection. Single-source vulnerability runs through German and Italian IP-rated cabinet fabricators. Distribution runs through utility procurement departments, industrial automation channels, and EPC contractors serving renewable energy substations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fixed switch cabinet market operates as a stable compounder, with grid interconnection mandates and electrification programs providing steady demand visibility across the projection horizon.
For Market Incumbents: Lock in captive supply of precision sheet metal components through backward integration into German and Italian fabrication clusters. Secure IEC 62271-200 type-test certification pipelines to maintain 12-18 month qualification barriers against speculative entrants. Deepen software-hardware convergence through predictive analytics platforms that generate recurring revenue beyond equipment sales.
For New Entrants and Emerging Players: The price-point gap between premium gas-insulated and economy metal-enclosed tiers creates white-space opportunity in Southeast Asian rural electrification. Target Vietnam and Philippines grid expansion programs through localized assembly partnerships that satisfy domestic-content requirements. Enter via compact modular designs with integrated protection and metering for contractor-led procurement channels.
For Investors and Strategic Acquirers: Roll-up economics work for precision enclosure fabricators because geographic supply concentration creates scarcity value for qualified components. The 5-10 year viability window favors manufacturers with verified SF6-free platforms and circular material flows. Watch for inflection in EU carbon-border adjustment mechanism enforcement as signal for premium-tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Platform Transition | Vacuum interrupter adoption satisfies EU F-Gas Regulation mandates and unlocks Nordic utility tenders. |
| Localized Assembly Partnerships | Domestic-content compliance in India and Vietnam bypasses import restrictions and reduces logistics exposure. |
| Digital Twin Integration | IoT sensor convergence enables predictive maintenance contracts with German distribution network operators. |
| Precision Sheet Metal Backward Integration | Captive supply of IP-rated enclosures mitigates geographic concentration risk in German and Italian clusters. |
| IEC 62271-200 Certification Investment | Type-test qualification creates 12-18 month barriers against speculative entrants in arc-flash containment segments. |
Methodological Framework
Bottom-up power distribution and industrial automation modeling reconciled against top-down switchgear production tracking forms the analytical core. Primary interviews with utility planning officers, EPC contractors, plant engineers at semiconductor fabrication facilities, and aftermarket service heads informed demand segmentation. Secondary validation drew from IEC standards documentation, Central Electricity Authority directives, EU F-Gas Regulation filings, and customs trade data for copper and electrical steel flows. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of metal-enclosed and gas-insulated deployment patterns established baseline growth trajectories across the projection horizon. The forecast framework models segmentation by product type, application, end user, and installation type, with regional regulatory clusters as an additional dimension. CAGRs derive from fitted trend extrapolation adjusted for named policy inflections including SF6 phase-down schedules and India's rural electrification targets. Industry-specific inputs include arc-flash containment standard adoption curves and solid-state protection penetration rates in premium industrial segments.
Caveats apply where raw material commodity spikes, IEC certification timeline delays, or SCADA protocol integration failures could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and grid interconnection project execution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Antenna Switch Module Market
Switches
Timer Switch Socket Market
Switches
Analog Switches Market
Switches
UAE Switchgear Market
Switches
Cross Point Switch Market
Switches
Miniature-Circuit Breaker Market
Switches
Off-Road Machine Ruggedized Switch and Indicator Systems Market
Switches
Europe Low Voltage Switchgear Market
Switches
Canada Switch Gear Market
Switches
Electric Switch Market
Switches
Power Load Switches Market
Switches
Digital Crosspoint Switches Market
Switches
Disconnect Switch Market
Switches
Outdoor Boundary Vacuum Load Switch Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Europe Switchgear Market