
 Analog Switches Market | 2026-2036
Analog Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Analog Switches Market Outlook
Modular signal-path unbundling is decoupling analog switch selection from monolithic ASSP procurement. Texas Instruments leverages its broad CMOS portfolio to sustain design-win momentum across industrial automation controllers. Infineon Technologies anchors automotive-grade switch supply through AEC-Q100-qualified production lines.
Analog switches are semiconductor devices that route analog signals between ports with controlled impedance, typically exhibiting on-resistance below 10 ohms and bandwidth exceeding 500 MHz for high-fidelity signal preservation. These components serve critical roles in audio routing, sensor multiplexing, and test instrumentation where digital switching would introduce quantization artifacts. CMOS technology dominates the technology dimension due to its near-zero static power draw and compatibility with mixed-signal SoC integration, while BiCMOS variants command premium positioning in RF front-ends where linearity requirements exceed pure CMOS capability. Automotive applications represent the fastest-expanding application segment, driven by zone-architecture vehicle designs that multiply switch counts per ECU.
FCC Part 15 emissions rules in the United States constrain spurious signal leakage from switching arrays in telecommunications gear. ETSI EN 301 489 standards in Europe mandate electromagnetic compatibility testing for switches deployed in wireless infrastructure. China's MIIT enforces GB/T 17626 immunity requirements on domestically sourced analog components. Stakeholders must track how regional semiconductor subsidy programs redirect manufacturing investment and alter supply security calculations.
Market Dynamics
Semiconductor packaging unbundling is decoupling analog switch procurement from monolithic ASSP sourcing, forcing ECU designers to evaluate discrete signal-path components on standalone merit rather than bundled silicon economics.
Growth Catalysts
- AEC-Q100 qualification pathways:Automotive-grade certification requirements are expanding addressable switch volumes in zone-architecture vehicle designs. Tier-1 suppliers now specify discrete switches for redundancy-critical signal paths.
- South Korea's display driver IC cluster:Concentrated OLED panel manufacturing in Gyeonggi Province generates dense demand for high-bandwidth analog multiplexers in source driver modules. Local foundry partnerships accelerate design-win cycles.
- IEC 60747-5 signal integrity standards:Tightened on-resistance flatness specifications across industrial temperature ranges are disqualifying legacy bipolar switch families. CMOS process nodes below 180nm capture specification-driven replacement demand.
Market Restraints
- 300mm silicon wafer supply concentration:Taiwan-based foundries control critical analog-CMOS capacity allocation. Fabless switch vendors face 26-week lead times during automotive demand surges.
- Electrostatic discharge sensitivity:Sub-10-ohm on-resistance designs require thin-gate oxide processes inherently vulnerable to handling damage. Assembly yield losses exceed 3% in high-volume contract manufacturers.
- BiCMOS process obsolescence:RF linearity-optimized switch families depend on shrinking bipolar-CMOS foundry availability. Fewer than four foundries maintain qualified BiCMOS lines for sub-6-GHz applications.
Strategic Opportunities
- India's PLI scheme for semiconductor assembly:Subsidized packaging capacity in Gujarat and Karnataka creates regional supply security for automotive ECU programs targeting domestic content requirements.
- Sensor fusion convergence:LiDAR-to-camera signal aggregation in ADAS architectures demands ultra-low charge-injection switches. Multi-channel integration at the pixel-array interface enables new component categories.
- Medical imaging unbundling:MRI gradient coil switching is migrating from custom relay banks to solid-state semiconductor arrays. IEC 60601-1 isolation requirements create certification-barriered premium segments.
Industry Challenges
- Mixed-signal verification talent scarcity:Analog switch characterization requires expertise in charge injection, crosstalk, and THD measurement. Semiconductor design programs emphasize digital VLSI over precision analog.
- Automotive PPAP timeline compression:Tier-1 suppliers demand 12-week production part approval process completion versus historical 24-week cycles. Test data documentation requirements strain quality engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analog Switches Market |
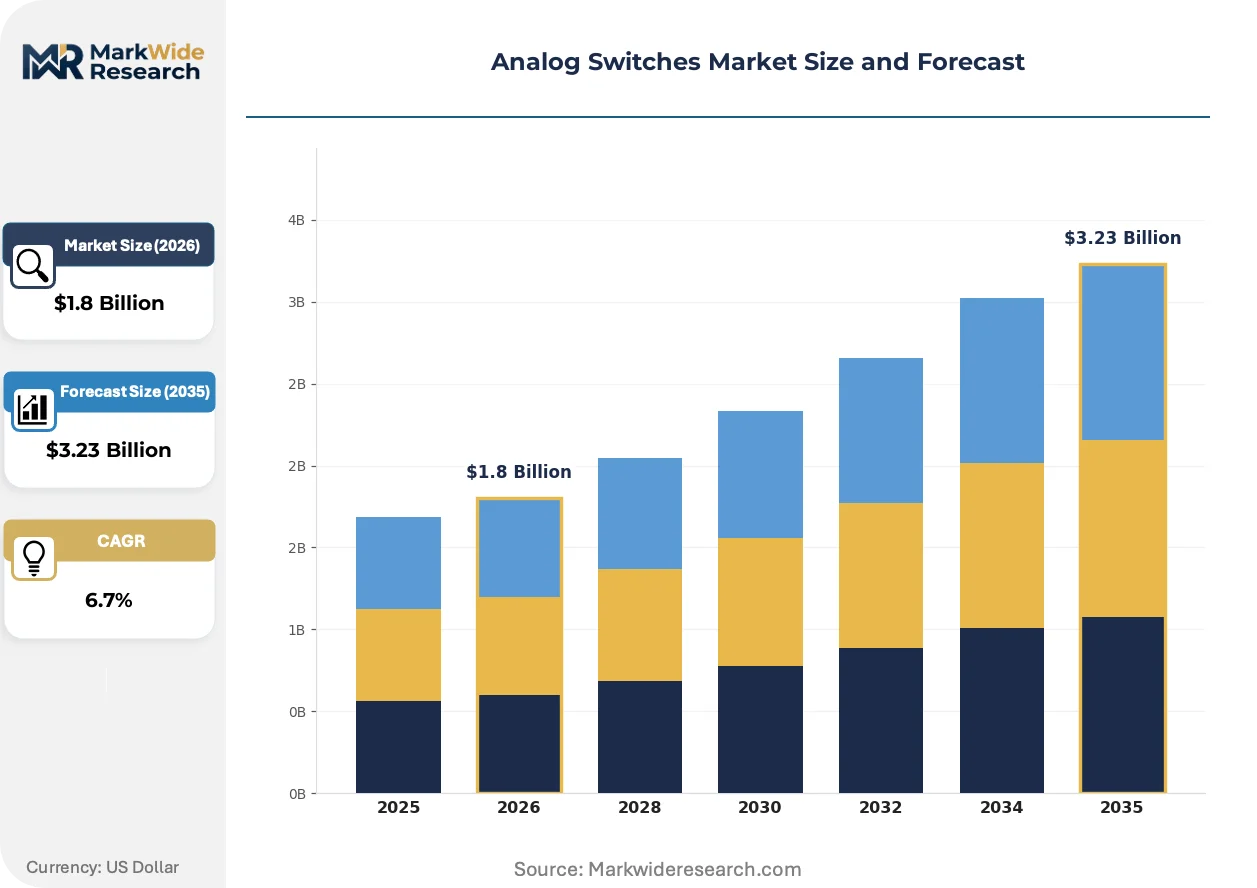
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Single Pole, Double Pole, Integrated Circuit, Relay Application: Telecommunications, Consumer Electronics, Automotive, Industrial Automation Technology: CMOS, BiCMOS, Bipolar, Analog End User: OEMs, System Integrators, Distributors, Aftermarket Providers |
| Companies Covered | Texas Instruments, Analog Devices, NXP Semiconductors, ON Semiconductor, Maxim Integrated, STMicroelectronics, Infineon Technologies, Microchip Technology, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analog Switches Market Strategic Shifts
Signal-path architectures are fragmenting into discrete functional blocks, with analog switches repositioned as independently optimized components rather than integrated peripheral elements within larger ASSPs.
Silicon-on-insulator CMOS switch technology is modularizing high-voltage analog routing in industrial automation controllers. Machine builders in Germany's automotive electronics corridor are adopting 60V-tolerant switch families for 24V fieldbus termination. This process shift is modularizing what previously required electromechanical relay banks into solid-state arrays with 10-million-cycle endurance ratings.
China's GB/T 17626 electromagnetic immunity standards are tightening conducted susceptibility thresholds for domestically sourced analog components. MIIT enforcement is disqualifying imported switches lacking certified test reports from accredited Chinese laboratories. Industrial equipment OEMs serving state-owned enterprise procurement channels are accelerating local qualification programs to maintain bid eligibility.
Consolidated vendor-managed inventory programs are compressing distributor stocking for standard-grade analog switches. Large automotive electronics manufacturers in Germany's Baden-Württemberg region now specify direct ship-from-foundry logistics with 72-hour dock-to-line requirements. This channel restructuring concentrates procurement leverage among buyers with sufficient volume to justify bypassing traditional semiconductor distribution.
Analog Switches Market Segmentation
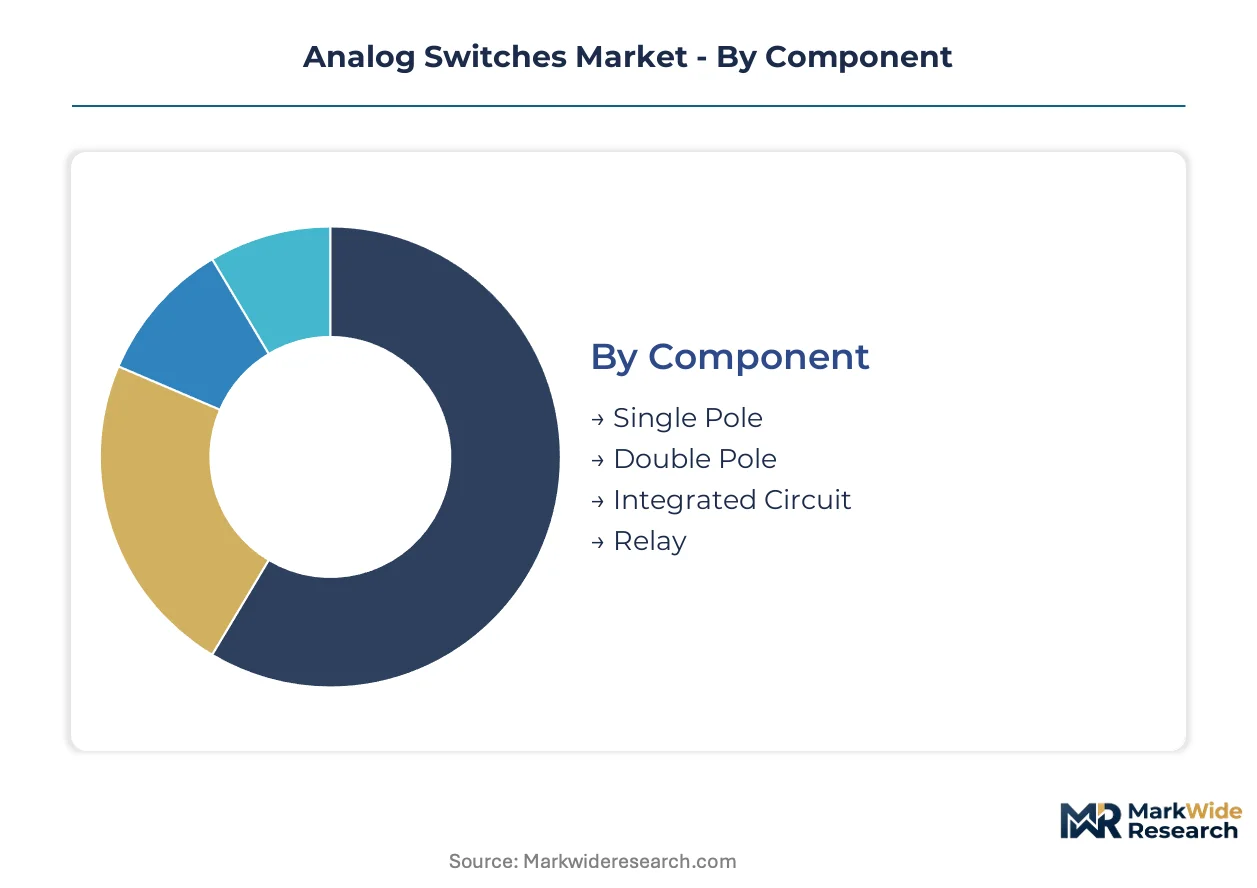
Analog switch procurement diverges sharply across technical specifications, with CMOS integration levels and automotive qualification grades commanding premium positioning. Component architecture and end-user channel structure determine margin capture and design-win cycles.
Component:
Standardization concentrates in high-volume single-pole variants, while double-pole and integrated configurations retain customization premiums for signal-path optimization.
- Single Pole:One input routes to one output with minimal insertion loss. Smartphone audio jack detection circuits in South Korea's Gyeonggi Province cluster consume millions of units monthly. The segment anchors volume economics through die-size minimization below 0.5mm².
- Double Pole:Simultaneous dual-channel switching preserves phase coherence in differential signal pairs. Germany's automotive electronics corridor specifies these for redundant sensor paths in zone-architecture ECUs. AEC-Q100 qualification requirements extend design-win cycles but lock in multi-year supply agreements.
- Integrated Circuit:Multi-channel arrays with built-in charge-pump drivers reduce external component counts. Industrial automation controllers in Japan's Kansai region adopt these for programmable logic I/O expansion.
- Relay:Electromechanical switching survives in kilovolt-isolation applications. Medical imaging OEMs migrating from relay banks to solid-state alternatives create replacement demand for semiconductor-emulating variants.
Leading the category by volume: Single Pole. Growing fastest: Double Pole.
Application:
End-use concentration shifts toward electrification-intensive sectors, with automotive and industrial automation outpacing legacy consumer electronics deployment.
- Automotive:Zone-architecture vehicle designs multiply switch counts per ECU from single-digit to 40-plus discrete components. Tier-1 suppliers in Germany's Baden-Württemberg region now specify discrete switches for redundancy-critical signal paths rather than bundled ASSP peripherals.
- Industrial Automation:24V fieldbus termination and 60V-tolerant switching arrays displace electromechanical relay banks. Machine builders specify 10-million-cycle endurance ratings for solid-state replacements.
- Telecommunications:FCC Part 15 emissions rules constrain spurious signal leakage from switching arrays in 5G infrastructure. Base station antenna tuning circuits demand sub-10-ohm on-resistance flatness.
- Consumer Electronics:Audio routing and display driver multiplexing concentrate in South Korea's display driver IC cluster. OLED source driver modules require high-bandwidth analog multiplexers with sub-nanosecond switching times.
Highest margin capture: Automotive. Steepest expansion trajectory: Industrial Automation.
Technology:
Process node economics favor CMOS scaling, while BiCMOS and bipolar variants retreat to RF linearity niches with shrinking foundry support.
- CMOS:Near-zero static power draw and mixed-signal SoC compatibility dominate new designs. Sub-180nm process nodes capture specification-driven replacement demand as IEC 60747-5 standards tighten on-resistance flatness requirements.
- BiCMOS:Superior linearity for sub-6-GHz RF front-ends commands premium positioning. Fewer than four foundries maintain qualified production lines, creating supply security vulnerabilities for 5G infrastructure programs.
- Bipolar:Legacy families face disqualification under tightened industrial temperature range specifications. Remaining demand concentrates in avionics and military applications with extended qualification timelines.
- Analog:Continuous signal-path switching without quantization artifacts serves test instrumentation and precision measurement. National metrology laboratories specify these for calibration-grade signal routing.
Dominant by wafer starts: CMOS. Fastest process node migration: CMOS.
End User:
Channel structure fragments between direct procurement leverage and distributor-mediated technical support, with logistics requirements reshaping inventory positioning.
- OEMs:Large automotive electronics manufacturers specify direct ship-from-foundry logistics with 72-hour dock-to-line requirements. Consolidated vendor-managed inventory programs bypass traditional semiconductor distribution.
- System Integrators:Industrial automation specialists bundle switches into programmable controller subsystems. Germany's automotive electronics corridor sources through these intermediaries for fieldbus termination modules.
- Distributors:Technical support and small-lot availability sustain relevance for mid-volume industrial customers. China's MIIT enforcement of GB/T 17626 certification requirements accelerates local qualification programs.
- Aftermarket Providers:Replacement switch sourcing for legacy telecommunications and industrial equipment. Obsolescence management services command premium margins for end-of-life bipolar families.
Largest procurement volume: OEMs. Fastest channel restructuring: System Integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Taiwan and South Korea where foundries control analog-CMOS wafer starts. Consumption diverges across automotive electronics corridors in Germany, display driver clusters in South Korea, and industrial automation hubs in Japan and the United States.
United States
FCC Part 15 emissions rules constrain spurious signal leakage from switching arrays in 5G telecommunications infrastructure. The National Institute of Standards and Technology maintains calibration-grade analog switch specifications for precision measurement applications. Base station antenna tuning circuits in Texas and California demand sub-10-ohm on-resistance flatness for high-fidelity signal preservation.
Germany
Zone-architecture vehicle designs in Baden-Württemberg multiply analog switch counts per ECU from single-digit to 40-plus discrete components. The Kraftfahrt-Bundesamt enforces electromagnetic compatibility standards for automotive electronics through type-approval processes. Machine builders in Bavaria specify 60V-tolerant switch families for 24V fieldbus termination in industrial automation controllers.
South Korea
OLED panel manufacturing in Gyeonggi Province generates dense demand for high-bandwidth analog multiplexers in source driver modules. The Ministry of Trade, Industry and Energy administers semiconductor subsidy programs redirecting manufacturing investment toward domestic content requirements. Local foundry partnerships in the Seoul Capital Area accelerate design-win cycles for display driver IC programs.
China
MIIT enforcement of GB/T 17626 electromagnetic immunity standards disqualifies imported switches lacking certified test reports from accredited Chinese laboratories. The dual carbon goals framework redirects state-owned enterprise procurement toward domestically qualified component suppliers. Industrial equipment OEMs serving state-owned channels in the Yangtze River Delta accelerate local qualification programs to maintain bid eligibility.
Japan
Industrial automation controllers in the Kansai region adopt multi-channel integrated switch arrays for programmable logic I/O expansion. METI standards for industrial semiconductor components tighten reliability specifications across extended temperature ranges. Precision measurement equipment manufacturers in Tokyo-Osaka corridor specify continuous signal-path switching without quantization artifacts for metrology-grade applications.
Analog Switches Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct tiered positions. The vendor base organizes around three strategic archetypes: broad-line semiconductor manufacturers with mixed-signal portfolios, automotive-grade specialists with AEC-Q100-qualified production lines, and industrial-focused vendors with high-voltage tolerant switch families. Consolidation pressures intensify as tier-1 suppliers demand compressed PPAP timelines and direct ship-from-foundry logistics arrangements.
Within the broad-line mixed-signal tier, Texas Instruments and Analog Devices exemplify portfolio diversification strategies spanning industrial automation and telecommunications applications. Infineon Technologies occupies a position anchoring automotive-grade supply through qualification-heavy production investments. These three companies represent divergent approaches to signal-path component positioning—volume-driven standardization, precision analog specialization, and automotive certification depth—each capturing distinct procurement leverage points across end-user channels.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| NXP Semiconductors |
| ON Semiconductor |
| Maxim Integrated |
| STMicroelectronics |
| Infineon Technologies |
| Microchip Technology |
| Renesas Electronics |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Taiwan and South Korea anchor analog-CMOS wafer supply, translating captive foundry relationships into pricing discipline that resists spot-market volatility. Their concentrated ownership structures enable long-term capacity contracting with automotive Tier-1 suppliers, insulating premium AEC-Q100-qualified switch families from commodity pricing erosion.
Pricing Analysis
Margin tightening in standard-grade single-pole variants reflects 300mm wafer allocation competition from higher-margin automotive programs. Three-tier pricing structure across AEC-Q100 automotive, industrial-grade extended temperature, and commercial consumer tiers separates qualification investment from die-size economics. Pricing pressure stems from consolidated vendor-managed inventory programs compressing distributor margins. Automotive OEMs exhibit lowest price sensitivity due to PPAP-locked multi-year agreements, while consumer electronics procurement teams in South Korea's Gyeonggi Province drive hardest cost-down negotiations.
Supply Chain Analysis
AEC-Q100 certification gates entry to automotive ECU supply chains, forcing fabless vendors into foundry partnerships with qualified 180nm-and-below CMOS lines. Wafer supply concentrates in Taiwan, South Korea, and Japan where analog-CMOS capacity allocation determines component availability. Silicon-on-insulator substrates, gold wirebond materials, and molded epoxy compounds constitute critical input dependencies. Single-source vulnerability pervades BiCMOS process availability with fewer than four qualified foundries maintaining sub-6-GHz RF switch production. Distribution runs through direct ship-from-foundry logistics for high-volume automotive programs, while industrial customers retain distributor-mediated technical support channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where AEC-Q100 qualification investments erect barrier-to-entry moats protecting incumbent automotive-grade suppliers from commoditization.
For Market Incumbents: Lock in multi-year foundry capacity reservations at Taiwan-based 300mm analog-CMOS facilities to defend against automotive demand surge allocation competition. Deepen backward integration into silicon-on-insulator substrate sourcing for 60V-tolerant industrial switch families, insulating margin structures from raw material volatility. Prioritize charge-pump driver integration R&D to capture sensor-fusion convergence demand in LiDAR-to-camera signal aggregation architectures. For New Entrants and Emerging Players: Direct-to-industrial-automation channel routes bypass entrenched automotive qualification timelines, offering faster design-win cycles for 24V fieldbus termination modules. Target India's Gujarat and Karnataka packaging corridors where PLI-subsidized assembly capacity supports domestic content requirements for state-mandated automotive ECU programs. Lead with medical imaging solid-state relay replacement applications where IEC 60601-1 isolation requirements create certification-barriered premium segments with limited incumbent competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor BiCMOS-capable mid-caps in Japan and Europe where foundry obsolescence strands RF linearity-optimized switch families with irreplaceable sub-6-GHz expertise. Long-term viability hinges on CMOS process migration capability across the 5-to-10-year technology refresh window. Monitor MIIT enforcement intensity on GB/T 17626 certification requirements as inflection indicator for China market access premium capture versus import displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Qualification Investment | Unlocks automotive zone-architecture ECU procurement channels with multi-year supply lock-in. |
| Foundry Capacity Reservation | Secures 300mm analog-CMOS wafer allocation ahead of industrial automation demand surges. |
| Silicon-on-Insulator Process Migration | Enables 60V-tolerant switch families displacing electromechanical relay banks in German machine building. |
| Direct Ship-from-Foundry Logistics | Meets 72-hour dock-to-line requirements from Baden-Württemberg automotive electronics manufacturers. |
| GB/T 17626 Certification Program | Maintains bid eligibility for state-owned enterprise procurement channels in China's Yangtze River Delta. |
Study Parameters
SEC 10-K filings, customs trade databases, and IEC standards documentation formed the secondary backbone for supply-side capacity and regulatory requirement mapping. Primary interviews with analog switch design engineers, Tier-1 automotive supplier procurement directors, industrial automation controller product managers, and semiconductor foundry business development leads validated demand assumptions and qualification timeline estimates. Bottom-up die-size and wafer-start calculations triangulated against top-down market value reconstructions across component, application, technology, and end-user segmentation dimensions.
Historical trendline analysis of CMOS process node migration and automotive electronics content-per-vehicle expansion informed projection framework construction across the analysis window. Segmentation modeling incorporated component architecture, application sector electrification intensity, technology process node, and end-user channel structure as core dimensions. CAGRs derived from unit volume and average selling price trajectory synthesis, with specific weighting for AEC-Q100 qualification premium capture and BiCMOS foundry supply constraint impacts.
Inputs from foundry capacity planners and automotive PPAP documentation were available through the study window; gaps in BiCMOS process node retirement timelines introduce uncertainty bands for RF switch family supply security forecasts. Forecasts reflect documented assumptions regarding IEC 60747-5 flatness specification adoption rates and MIIT enforcement consistency on GB/T 17626 certification requirements. A model refresh is warranted upon material change in Taiwan-based 300mm analog-CMOS foundry allocation policies or automotive zone-architecture ECU deployment acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Outdoor Boundary Vacuum Load Switch Market
Switches
Oil Level Switches Market
Switches
Rotary Limit Switches Market
Switches
Australia Switchgear Market
Switches
Global Light Control Switches Market
Switches
Panel Mounted Disconnect Switch Market
Switches
Low Voltage Switchgear Market
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Dual Power Transfer Switches Market
Switches
Haptic Feedback Switch and Button Platforms Market
Switches
North America Medium Voltage Switchgear Market
Switches
Asia Pacific Transfer Switches Market
Switches
DC Circuit Breaker Market
Switches
KVM Switch Market
Switches
UK Reed Sensors Switches Market
Switches
Pressure Switch Market