
 Smart Plugs and Switches Market | 2026-2036
Smart Plugs and Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Plugs and Switches Market Analysis
China is narrowing its cost advantage in smart plug and switch assembly as Southeast Asian facilities scale output for export markets. TP-Link Technologies leverages its Shenzhen manufacturing base to sustain pricing power across Wi-Fi-enabled product lines. Schneider Electric anchors European demand through its Wiser home automation ecosystem and commercial building integration. Legrand competes on channel depth, controlling electrical distributor relationships across France, Italy, and Iberia.
Smart plugs and switches are networked electrical control devices that enable remote on/off operation, load monitoring, and scheduling through embedded radio modules operating at 2.4 GHz or sub-GHz frequencies. These devices serve residential and commercial users seeking to reduce standby power consumption and integrate lighting or appliance circuits with centralized automation platforms. Wi-Fi smart plugs and Zigbee switches together occupy the dominant volume position, with Zigbee gaining share in multi-device mesh deployments where hub-based topology outperforms direct router connections. Voice-activated control methods are expanding fastest as natural language processing migrates from smart speakers to embedded switch hardware, while sensor-based activation remains a premium feature concentrated in commercial establishments with occupancy-driven energy management.
The FCC in the United States certifies radio frequency emissions for all Wi-Fi and Z-Wave devices, while the EU Radio Equipment Directive mandates CE marking and interoperability testing for products sold across member states. China's MIIT enforces GB standards for short-range wireless devices, creating a fragmented compliance landscape that favors manufacturers with multi-regional certification capabilities. Ecodesign regulations in Europe and appliance efficiency programs administered by the EPA in North America are tightening standby power limits, directly influencing chipset selection and firmware design. Stakeholders must monitor evolving cybersecurity mandates for IoT devices, as draft legislation in multiple jurisdictions threatens to impose recurring certification burdens on hardware already slim on margin.
Market Dynamics
Mesh networking protocols are compressing hardware margins as manufacturers absorb hub-integration costs to compete with Wi-Fi direct-connect alternatives. The shift from standalone devices to ecosystem-locked platforms forces vendors to choose between open interoperability and proprietary recurring revenue streams.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power limits below 0.5 watts are accelerating chipset replacement cycles and creating refresh demand across installed European bases.
- Commercial building retrofits:Facility managers in Germany and the United States are deploying occupancy-triggered switch networks to meet corporate net-zero commitments and reduce HVAC load.
- Matter protocol standardization:Cross-platform compatibility is eliminating consumer hesitation about ecosystem lock-in, expanding addressable households beyond early adopter segments.
Market Restraints
- Silicon supply concentration:RF module fabrication depends on TSMC and Samsung foundry capacity in Taiwan and South Korea, exposing lead times to geopolitical disruption.
- Certification cost escalation:FCC Part 15 testing plus EU RED compliance creates five-figure per-SKU burdens that disproportionately constrain mid-tier entrants.
- Bluetooth Low Energy substitution:Direct phone-to-device control without router dependency is capturing price-sensitive residential segments in emerging markets.
Strategic Opportunities
- India residential electrification:Rural grid extension and urban smart city pilots are creating first-mover advantages for vendors establishing local assembly partnerships.
- Demand response aggregation:Utility-controlled load curtailment programs in California and Texas are creating recurring revenue streams for switch vendors with cloud-connectivity infrastructure.
- Voice-plus-sensor convergence:Embedded microphones and radar presence detection are enabling premium positioning in Japanese commercial hospitality installations.
Industry Challenges
- Firmware security maintenance:IoT cybersecurity mandates in draft UK and Australian legislation impose ongoing patch obligations that strain lean hardware organizations.
- Legacy electrical contractor training:Installation of neutral-wire-dependent smart switches requires upskilling electricians accustomed to legacy two-wire residential circuits in older housing stocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Plugs and Switches Market |
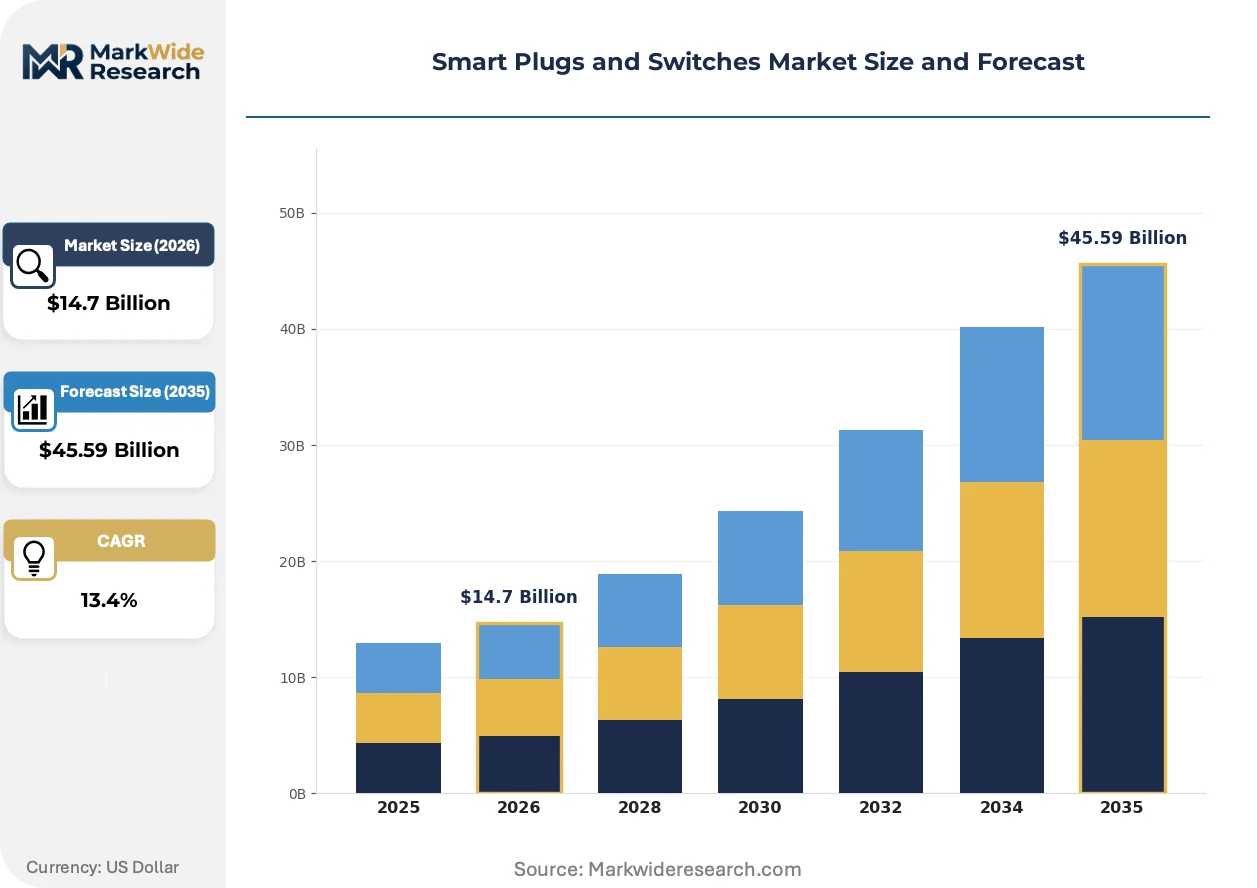
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $45.59 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Smart Plugs, Zigbee Switches, Bluetooth Plugs, Z-Wave Switches Control Method: App Controlled, Voice Activated, Remote Access, Sensor-Based End User: Residential Users, Commercial Establishments, Industrial Facilities, Smart Homes Feature: Energy Monitoring, Timer Functionality, Scheduling, Automation |
| Companies Covered | Belkin International, Inc., TP-Link Technologies Co., Ltd., Leviton Manufacturing Co., Inc., Schneider Electric, Lutron Electronics Co., Inc., D-Link Corporation, Xiaomi Inc., Panasonic Corporation, Legrand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Plugs and Switches Market Emerging Trajectories
Edge computing architectures are migrating processing from cloud relays to switch hardware itself, enabling millisecond response times for safety-critical applications. This localization trend intersects with tightening data sovereignty requirements and consumer privacy expectations.
Software-defined load control is virtualizing the traditional relay mechanism, replacing mechanical contacts with solid-state switching and enabling granular dimming curves previously requiring dedicated dimmer hardware. High-end residential integrators in the United States and Germany are specifying these silicon-based solutions for silent operation and extended cycle life. The technology is virtualizing the boundary between plug-level and circuit-level control, compressing the addressable market for separate product categories.
The EU Cyber Resilience Act is mandating vulnerability disclosure timelines and automatic update capabilities for all radio-connected devices sold in member states. Manufacturers must redesign supply chains to accommodate decade-long firmware support obligations previously handled by cloud service discontinuation. Small and mid-sized vendors without dedicated security engineering functions are exiting the European market rather than absorbing compliance infrastructure costs.
Buyer preference is rotating toward subscription-optional hardware as consumers reject recurring fees for basic remote access functionality. Direct-to-consumer brands with transparent pricing are capturing share from ecosystem incumbents in online channels. This pattern is most pronounced in the United States and Netherlands, where price comparison tools and review aggregation have reduced brand loyalty switching costs.
Smart Plugs and Switches Market Segmentation
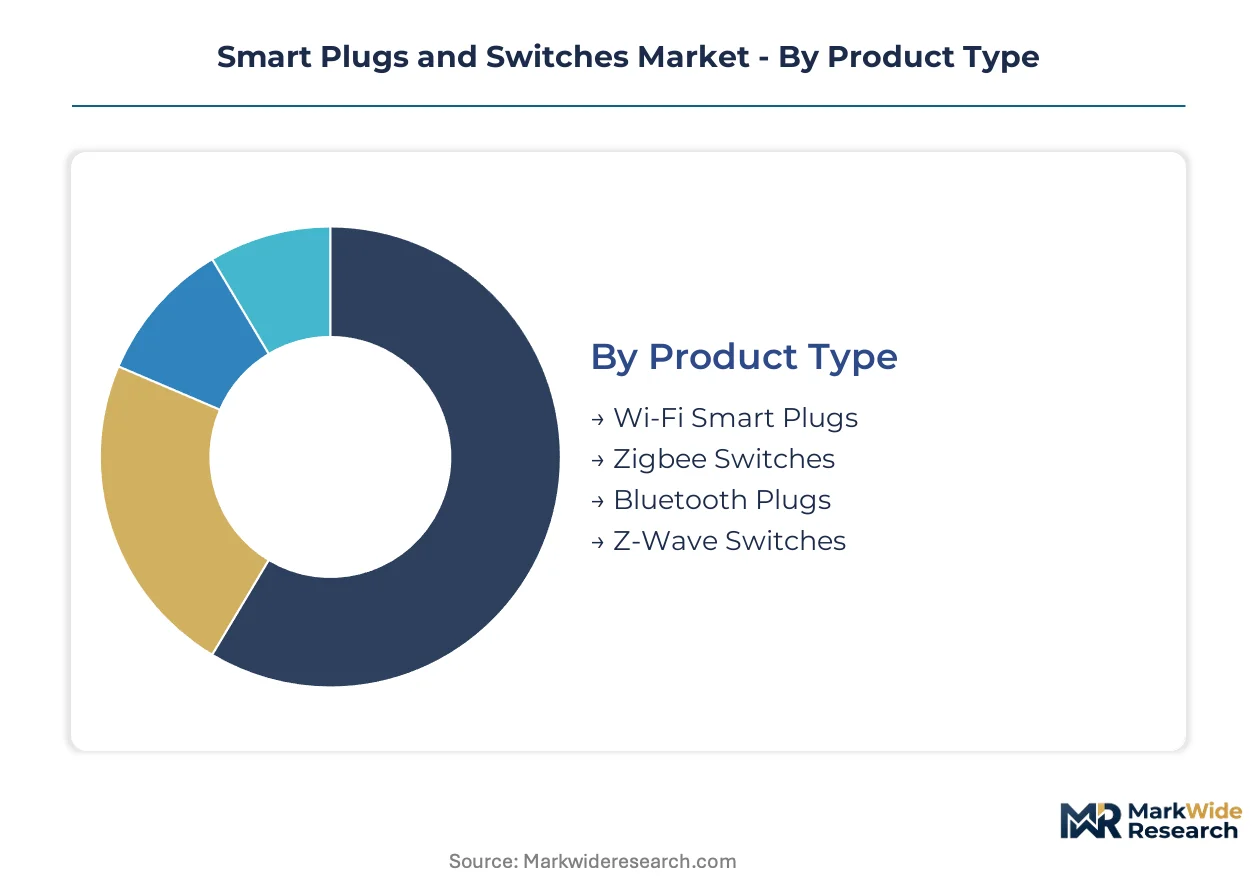
Smart plugs and switches fragment across protocol standards, user interfaces, deployment environments, and functional depth. Vendors must align hardware roadmaps with the specific certification burdens and margin structures each segment imposes.
Product Type:
Mature Wi-Fi and Zigbee deployments dominate volume, while Bluetooth and Z-Wave carve distinct addressable niches through cost or reliability positioning.
- Wi-Fi Smart Plugs:These devices embed 2.4 GHz radio modules for direct router connection without hub dependency. Demand concentrates in United States residential retrofits where consumers prioritize smartphone-native setup over ecosystem investment. FCC Part 15 certification costs constrain mid-tier entrants, entrenching established brands with testing infrastructure.
- Zigbee Switches:Mesh-topology devices operating on IEEE 802.15.4 standards enable multi-hop network resilience for whole-home coverage. Germany and Netherlands lead adoption as households integrate with Philips Hue and IKEA Dirigera ecosystems. The EU Radio Equipment Directive mandates interoperability testing that favors vendors with dedicated European certification teams.
- Bluetooth Plugs:BLE 5.0 modules enable phone-direct control without Wi-Fi infrastructure, penetrating price-sensitive emerging markets. India's rural electrification programs favor these low-cost entry points.
- Z-Wave Switches:Sub-GHz frequency operation avoids 2.4 GHz congestion in dense urban deployments. Professional installers in United States multi-family housing specify these for reliable penetration through concrete structures.
Wi-Fi Smart Plugs retain volume leadership; Bluetooth Plugs hold the steepest expansion curve.
Control Method:
Interface preferences diverge sharply between convenience-seeking residential buyers and compliance-driven commercial specifiers.
- App Controlled:Native smartphone applications provide scheduling, energy dashboards, and firmware update channels. United States and China lead adoption where mobile-first consumer behavior dominates.
- Voice Activated:Embedded microphones or speaker-pairing enable Alexa, Google Assistant, and Siri command execution. Natural language processing migration to edge hardware is accelerating in Japanese hospitality and United States premium residential segments.
- Remote Access:Cloud-relayed control enables off-premise operation for vacation property and small business managers. Cybersecurity mandates in draft UK and Australian legislation threaten recurring certification burdens for vendors maintaining these infrastructures.
- Sensor-Based:Occupancy, daylight, and temperature triggers automate load control without human intervention. Commercial building retrofits in Germany and United States deploy these for corporate net-zero compliance.
App Controlled maintains installed base dominance; Voice Activated commands the premium pricing tier.
End User:
Customer archetypes span from price-sensitive individual homeowners to enterprise procurement functions with decade-long support requirements.
- Residential Users:Individual homeowners seeking standby power reduction and lighting convenience. United States and China account for the majority of unit volume through retail and e-commerce channels.
- Commercial Establishments:Offices, retail, and hospitality facilities pursuing energy management and occupancy-driven automation. Germany's corporate sustainability reporting obligations under CSRD accelerate specification of monitored switch networks.
- Industrial Facilities:Manufacturing and warehouse environments requiring ruggedized hardware with extended temperature tolerances. Demand concentrates in automotive and electronics assembly clusters.
- Smart Homes:Integrated new construction and whole-home retrofit projects specifying ecosystem-coordinated device fleets. Netherlands and California lead these architect-involved deployments.
Residential Users absorb the highest unit volumes; Smart Homes deliver the strongest revenue per installation.
Feature:
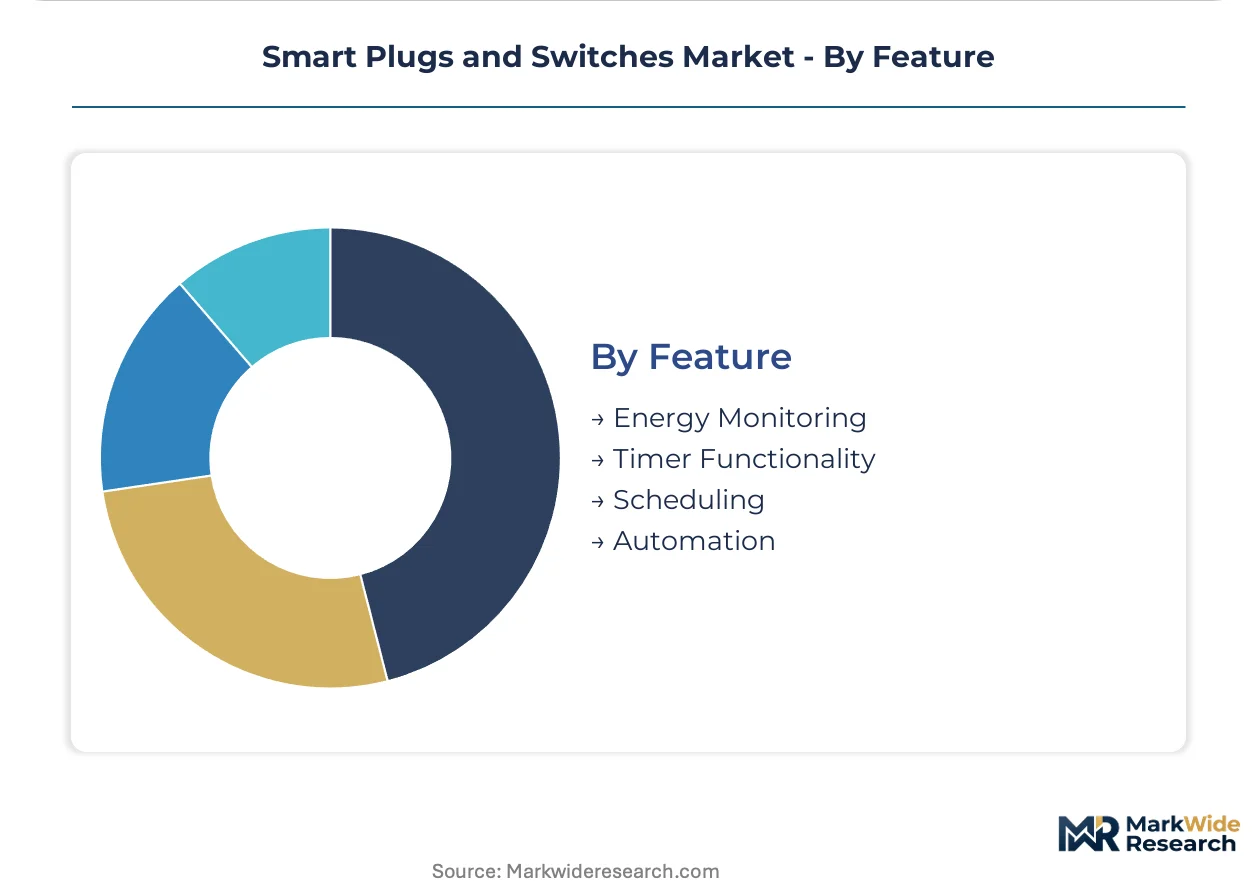
Functional depth determines chipset selection, firmware complexity, and margin capture potential across price tiers.
- Energy Monitoring:Integrated current sensors and power calculation algorithms provide real-time consumption data. Germany and United States utility rebate programs favor these for demand response participation.
- Timer Functionality:Basic scheduling through onboard real-time clocks or cloud-synchronized timers. Entry-level Wi-Fi plugs in Southeast Asian markets standardize this capability.
- Scheduling:Multi-event programming with sunrise/sunset alignment and seasonal adjustment. Commercial building managers in United States and Germany deploy these for HVAC load coordination.
- Automation:Rule engines and scene programming enabling cross-device conditional logic. Premium residential integrators in United States and Japan specify these for whole-home orchestration.
Energy Monitoring captures the highest average selling prices; Timer Functionality saturates the entry tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC certification requirements anchor the United States as the dominant geography for Wi-Fi-enabled device deployment, while EU Ecodesign mandates and China's MIIT standards create parallel compliance corridors that shape regional competitive dynamics.
United States
Residential retrofit demand concentrates in suburban markets where consumers prioritize smartphone-native setup over ecosystem investment. The EPA administers appliance efficiency programs that tighten standby power limits and influence chipset selection. Installation clusters in California and Texas benefit from utility-controlled demand response programs that create recurring revenue streams for cloud-connected switch vendors.
Germany
Corporate sustainability reporting obligations under CSRD accelerate specification of monitored switch networks in commercial building retrofits. The EU Radio Equipment Directive mandates CE marking and interoperability testing that favors vendors with dedicated European certification teams. Industrial demand concentrates in Bavaria and North Rhine-Westphalia where automotive and electronics assembly clusters drive ruggedized hardware procurement.
China
MIIT enforces GB standards for short-range wireless devices that fragment compliance landscapes and favor manufacturers with multi-regional certification capabilities. Shenzhen anchors manufacturing output for export markets as Southeast Asian facilities scale competing assembly capacity. Urban smart city pilots in Beijing and Shanghai create first-mover advantages for vendors establishing local distribution partnerships.
India
Rural grid extension and urban smart city initiatives generate demand for low-cost Bluetooth-enabled entry points that operate without Wi-Fi infrastructure. The Bureau of Indian Standards oversees product safety certification that shapes import compliance strategies. Manufacturing partnerships in Maharashtra and Karnataka enable tariff-advantaged assembly for price-sensitive residential segments.
Japan
Premium hospitality and commercial installations drive demand for voice-plus-sensor convergence with embedded microphones and radar presence detection. METI oversees energy efficiency standards that influence product specification in corporate procurement. Technology adoption clusters in Tokyo and Osaka where building automation integrators specify ecosystem-coordinated device fleets.
Smart Plugs and Switches Market Vendor Landscape
Capability concentration sits with ecosystem-anchored specialists; scale advantage sits with diversified electrical component conglomerates. The vendor base stratifies across three tiers: premium-tier integrators serving architect-involved smart home deployments, mass-market consumer brands competing on retail channel presence, and contract manufacturers supplying private-label distributors. Dominant competitive moves include strategic partnerships with cloud platform providers and geographic expansion through local assembly joint ventures.
Among diversified electrical component conglomerates, Schneider Electric and Legrand exemplify the ecosystem-anchored archetype through channel depth and building automation integration. TP-Link Technologies Co., Ltd. represents the scale-driven manufacturing tier with Shenzhen-based production capacity. These three entities occupy distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Belkin International, Inc. |
| TP-Link Technologies Co., Ltd. |
| Leviton Manufacturing Co., Inc. |
| Schneider Electric |
| Lutron Electronics Co., Inc. |
| D-Link Corporation |
| Xiaomi Inc. |
| Panasonic Corporation |
| Legrand |
| Others |
Supply Flow & Price Mechanics
Shenzhen's electronics manufacturing cluster anchors global smart plug and switch assembly capacity, with production scale dynamics directly transmitting into downstream pricing power for Wi-Fi-enabled product lines. The concentration of RF module fabrication and final assembly in this southern China hub compresses margins for mid-tier entrants lacking captive testing infrastructure while sustaining tiered pricing stratification across certification grades.
Pricing Analysis
Geographic price spreads between North American retail channels and Southeast Asian e-commerce platforms exceed three-to-one for functionally equivalent Wi-Fi smart plugs. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European SKUs from FCC-certified US variants and uncertified direct-import alternatives. Pricing pressure stems from Bluetooth Low Energy substitution in emerging markets where phone-direct control eliminates router dependency. Residential retrofit buyers in the United States exhibit highest price sensitivity, while German commercial specifiers prioritize interoperability certification over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Flex, and Jabil Electronics for final assembly, while TSMC and Samsung Foundry hold captive RF chip fabrication capacity. Component sourcing draws from Taiwan for silicon wafers, South Korea for memory modules, and mainland China for passive components and plastic enclosures. Single-source vulnerability in sub-6 GHz RF front-end modules exposes lead times to geopolitical disruption. Distribution runs through electrical distributor networks in Europe, big-box retail in North America, and platform e-commerce in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins in smart plugs and switches are compressing toward service-attach economics, with demand response aggregation and firmware maintenance subscriptions expanding faster than unit sales. Vendors capturing recurring revenue through utility-controlled load curtailment programs or automated update infrastructure will outearn transactional competitors.
For Market Incumbents: Build certification moats by accelerating EU Cyber Resilience Act compliance infrastructure ahead of smaller competitors. Absorb five-figure per-SKU testing costs that constrain mid-tier entrants. Defend against Bluetooth Low Energy substitution by embedding Matter protocol compatibility across Wi-Fi and Zigbee product lines. Deepen channel control through electrical distributor exclusivity arrangements in France, Italy, and Iberia where Legrand's position remains penetrable. For New Entrants and Emerging Players: Pursue white-space penetration in India's rural electrification programs where Bureau of Indian Standards certification creates tariff-advantaged assembly partnerships. Target price-sensitive residential segments with BLE 5.0 phone-direct products bypassing Wi-Fi infrastructure requirements. Establish go-to-market presence through platform e-commerce rather than competing for electrical distributor shelf space dominated by Schneider Electric and Legrand. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because ecosystem-locked device fleets generate recurring firmware revenue streams that hardware-only vendors cannot replicate. Acquisition targets should display dedicated security engineering functions capable of decade-long patch obligations under EU Cyber Resilience Act mandates. Monitor utility demand response program enrollment rates in California and Texas as inflection indicators for cloud-connectivity infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-platform compatibility eliminates consumer ecosystem lock-in hesitation across Philips Hue and IKEA Dirigera installations. |
| Demand Response Infrastructure | Utility-controlled load curtailment programs in California and Texas create recurring revenue streams for cloud-connected vendors. |
| EU Cyber Resilience Act Compliance | Automatic update capabilities and vulnerability disclosure timelines reshape supply chains for decade-long firmware support. |
| Local Assembly Joint Ventures | Maharashtra and Karnataka manufacturing partnerships enable tariff-advantaged production for India's price-sensitive residential segments. |
| Voice-Plus-Sensor Convergence | Embedded microphones and radar presence detection command premium positioning in Japanese commercial hospitality installations. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with smart home integrators, electrical contractors, facility managers, and RF chipset procurement leads. Secondary validation drew from FCC Part 15 equipment authorization databases, EU Radio Equipment Directive notified body filings, MIIT GB standard registrations, and utility demand response program enrollment disclosures. Bottom-up unit shipment estimates by protocol standard and control method were triangulated against top-down market value reconstructions from electrical component distributor revenue disclosures.
Calibration against historical price trajectories for Wi-Fi modules and Zigbee chipsets informed elasticity assumptions across the projection horizon. Segmentation modeling spanned protocol standard, deployment environment, functional depth, and regional regulatory cluster dimensions. CAGRs were derived from installed base replacement cycles, new construction penetration rates, and commercial retrofit intensity indicators. Forecast inputs incorporated EU Ecodesign Directive standby power limit enforcement timelines and Matter protocol adoption curves among major ecosystem platforms.
Sensitivities concentrate around silicon foundry capacity allocation, cybersecurity mandate implementation timelines, and Bluetooth Low Energy substitution rates in emerging markets. Forecasts embed assumptions regarding regulatory harmonization between FCC, EU RED, and MIIT certification frameworks. Quarterly review of RF module lead times, utility demand response program expansions, and draft IoT cybersecurity legislation progression is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Electric Switch Market
Switches
Cross Point Switch Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
China Reed Sensors Switches Market
Switches
Asia Pacific Transfer Switches Market
Switches
Global Smart Switch Panel Market
Switches
Australia Switchgear Market
Switches
Smart Home Switches Market
Switches
Smart Dimmer Switch Market
Switches
Mexico Rocker Switch Market
Switches
Oil Level Switches Market
Switches
DC Circuit Breaker Market
Switches
Saudi Arabia Switchgear Market
Switches
Off-Road Machine Ruggedized Switch and Indicator Systems Market
Switches
Pad-Mounted Switchgear Market
Switches
United States Circuit Breaker Market