
 Commercial Touch Display Market | 2026-2036
Commercial Touch Display Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Touch Display Market Analysis
A capital-intensity divergence between in-house semiconductor fabrication and outsourced panel assembly is redrawing competitive boundaries in commercial touch displays. Samsung Electronics Co., Ltd. leverages captive OLED supply chains to dominate premium interactive kiosk deployments. BOE Technology Group Co., Ltd. sustains massive Gen 10.5 fab scale to anchor cost leadership in touch monitors for education buyers. Panasonic Connect Co., Ltd. specializes in ruggedized optical touch systems that navigate harsh hospitality environments.
Commercial touch displays integrate transparent conductive layers, cover glass, and backplane electronics to enable direct human-machine interaction through capacitive, resistive, infrared, or optical sensing architectures. Interactive kiosk and digital signage product types command the widest deployment footprints, though touch tables retain premium positioning in collaborative corporate settings. Capacitive technology leads volume shipments while infrared maintains defensible share in large-format outdoor installations where glove operation and water resistance matter.
The EPA's ENERGY STAR specifications and the EU's Ecodesign Directive constrain standby power and luminance efficiency for displays sold across their respective jurisdictions, while China's GB standards enforce electromagnetic compatibility and safety testing through the country's national standardization administration. Stakeholders must monitor how evolving efficiency benchmarks reshape component sourcing and whether regional certification fragmentation creates compliance arbitrage between markets.
Market Dynamics
Retail self-service checkout lanes are pulling capacitive panels into high-traffic environments, compressing replacement cycles and forcing suppliers to engineer for 24/7 durability. This demand pull is colliding with the EU Green Deal's ecodesign requirements, which pressure manufacturers to cut display energy draw while maintaining brightness standards.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power limits are accelerating LED backlight retrofits in existing digital signage estates across Germany, France, and Italy.
- Guangdong Province Clustering:Panel fabs concentrated near Shenzhen's electronics corridor are shortening logistics legs for touch monitor assembly.
- Capacitive Sensing:Multi-touch precision is displacing resistive layers in hospitality point-of-sale terminals where gesture complexity matters.
Market Restraints
- Indium Tin Oxide Volatility:Transparent conductive layer costs fluctuate with rare earth supply constraints from concentrated mining jurisdictions.
- Gen 10.5 Fab Concentration:Massive LCD glass substrate production sits with three Asian suppliers, creating single-source vulnerability for 65-inch and larger touch displays.
- Infrared Limitation:Optical bezel arrays struggle with palm rejection in compact form factors below 15 inches, capping penetration in handheld industrial devices.
Strategic Opportunities
- India Education Procurement:National digital classroom mandates are opening tender volumes for interactive flat panels in secondary schools across Maharashtra and Karnataka.
- Touch Table Convergence:Haptic feedback integration with capacitive stacks is creating premium positioning in corporate collaborative workspaces.
- US IRA Efficiency Credits:Commercial building retrofit incentives are subsidizing ENERGY STAR-certified display upgrades in municipal government facilities.
Industry Challenges
- Optical Bonding Skill Gap:Cleanroom technicians capable of laminating cover glass to sensor layers without bubble defects command wage premiums in Shenzhen and Seoul.
- GB Standards Certification Lag:China's electromagnetic compatibility testing backlog extends product launch timelines by four to six months for foreign entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Touch Display Market |
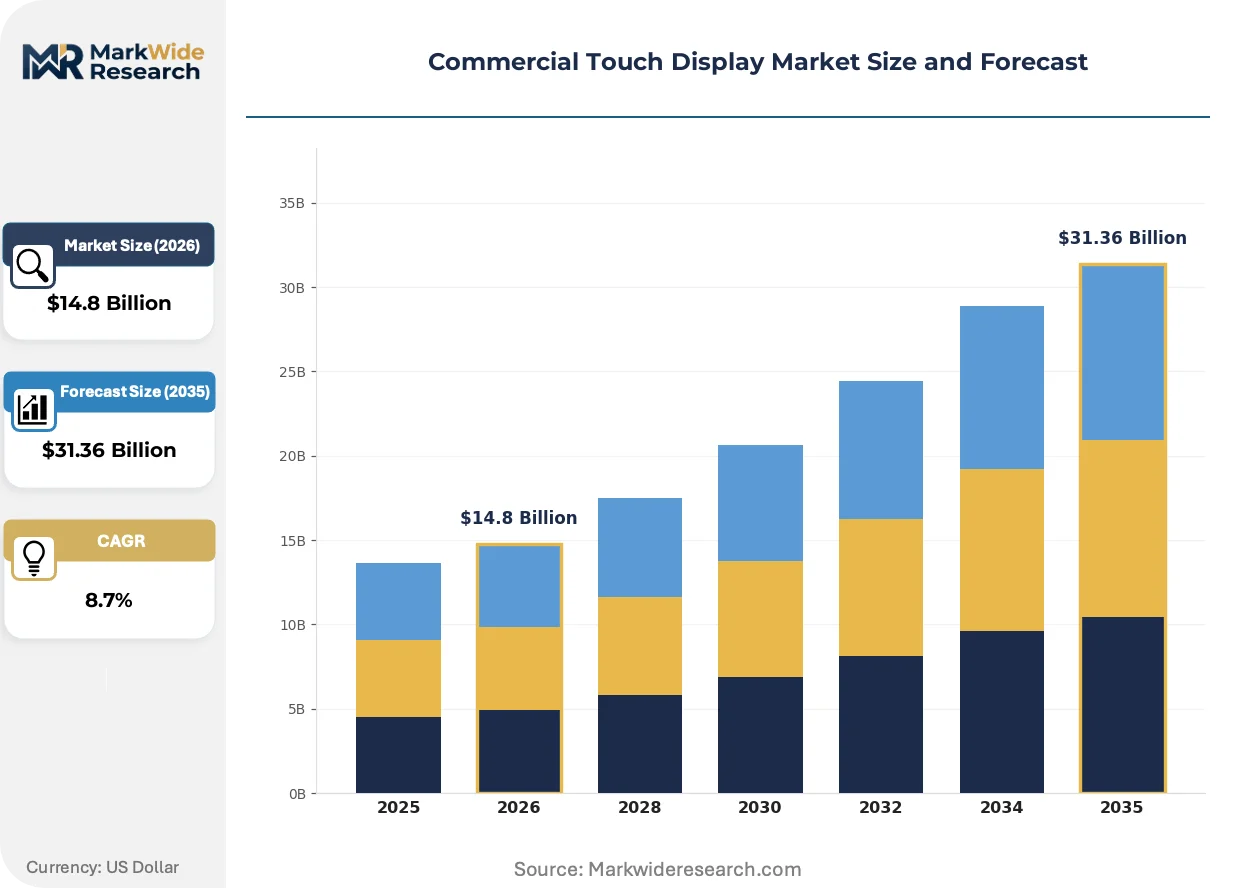
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Kiosk, Digital Signage, Touch Tables, Touch Monitors Technology: Capacitive, Resistive, Infrared, Optical End User: Retail, Education, Healthcare, Hospitality Installation: Wall-mounted, Freestanding, Tabletop, Embedded |
| Companies Covered | Sharp Corporation, ViewSonic Corporation, Samsung Electronics Co., Ltd., Barco NV, BenQ Corporation, LG Electronics Inc., BOE Technology Group Co., Ltd., Christie Digital Systems, Inc., Panasonic Connect Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Touch Display Market Emerging Trajectories
Touch display architecture is fragmenting as modular component strategies displace vertically integrated production. Suppliers are unbundling sensor fabrication from final assembly to optimize capital efficiency.
Metal mesh transparent conductors are decomposing the indium tin oxide monopoly in large-format touch overlays. Outdoor digital signage deployers in Dubai and Singapore are adopting silver nanowire alternatives for improved conductivity at 55-inch-plus diagonal sizes. This material transition is compressing cost curves for weather-resistant interactive kiosks.
REACH substance restrictions are forcing reformulation of optical clear adhesives used in display lamination. European manufacturers are qualifying acrylate-based alternatives to eliminate solvent content. Automotive-grade touch modules for commercial fleet dashboards face the steepest requalification burden under this regulatory pressure.
Buying committees in corporate IT departments are compressing vendor evaluation cycles from eighteen months to nine months. Value-added distributors with in-house integration capabilities are capturing specification influence previously held by direct OEM relationships. This pattern is most pronounced in North American healthcare and financial services verticals where procurement centralization is accelerating.
Commercial Touch Display Market Segmentation
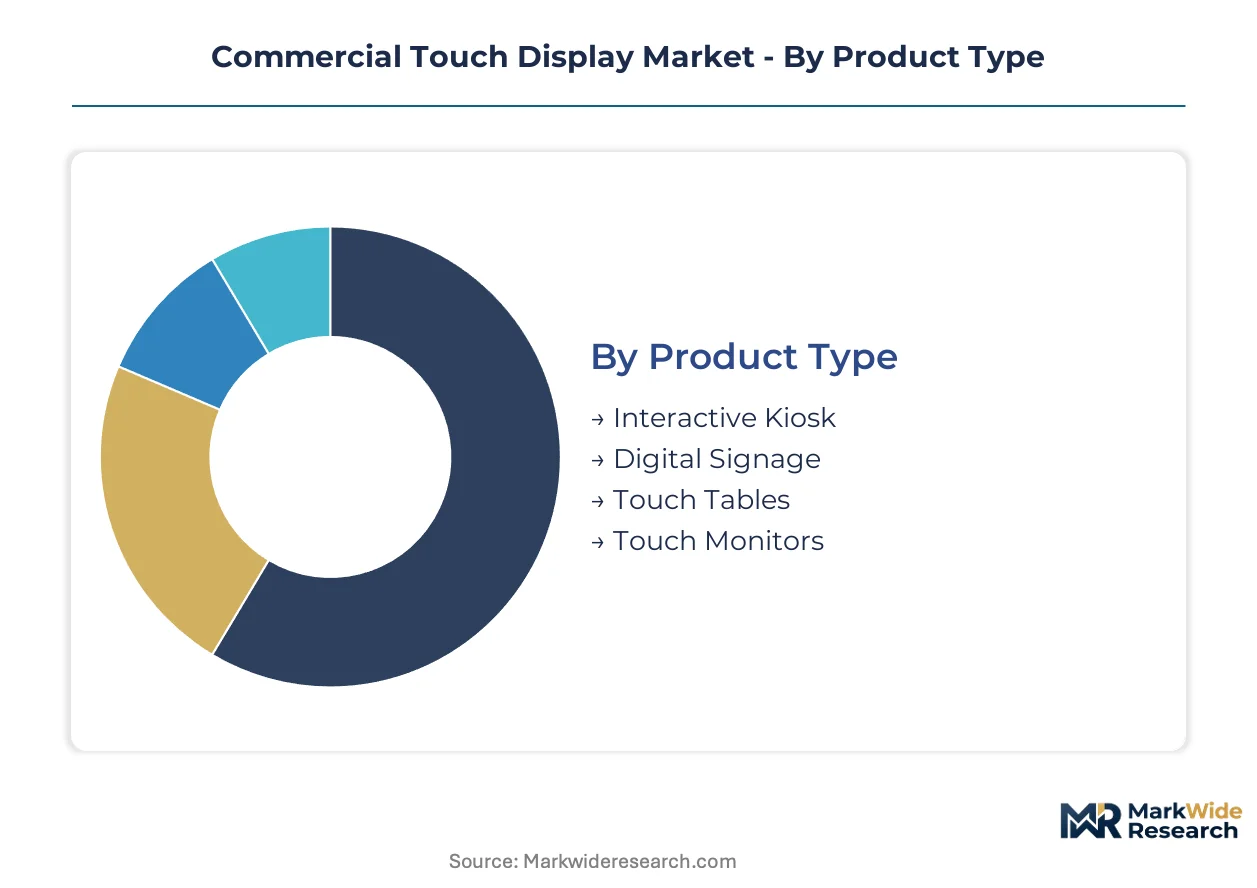
Commercial touch display procurement patterns diverge sharply across deployment contexts, with durability specifications and interface complexity driving segment selection. Component sourcing strategies and regulatory compliance burdens vary materially by product architecture and installation environment.
Product Type:
Substitution pressure from alternative interface technologies—voice activation, gesture control, mobile device tethering—threatens freestanding formats more severely than integrated display systems.
- Interactive Kiosk:Self-contained units combining display, compute, and enclosure for unattended public operation. Retail self-service checkout lanes in Germany and France are compressing replacement cycles to 36 months as 24/7 durability becomes mandatory.
- Digital Signage:Large-format displays designed for passive or lightly interactive content delivery. EU Ecodesign Directive standby power limits are accelerating LED backlight retrofits across existing estates in Italy and Spain.
- Touch Tables:Horizontal collaborative surfaces with multi-user simultaneous input capability. Corporate workspace deployments in London and Frankfurt are integrating haptic feedback for premium positioning.
- Touch Monitors:Modular display panels without integrated compute or enclosure. Education procurement in India's Maharashtra state is driving volume through national digital classroom mandates.
Digital signage retains volume leadership; touch tables hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium precision sensing from economy-grade alternatives, with material inputs and fabrication complexity determining price positioning.
- Capacitive:Electric field disruption detection enabling multi-touch precision with glass overlay durability. Hospitality point-of-sale terminals in Dubai and Singapore are displacing resistive layers where gesture complexity matters.
- Resistive:Pressure-activated membrane layers requiring physical deformation for input registration. Industrial handheld devices in Japan maintain adoption where stylus precision and glove compatibility outweigh responsiveness requirements.
- Infrared:Optical bezel arrays detecting beam interruption across display perimeter. Outdoor installations in Australia face palm rejection limitations below 15-inch diagonals, capping penetration in compact form factors.
- Optical:Camera-based or sensor fusion architectures enabling object recognition beyond touch. Ruggedized hospitality deployments in Saudi Arabia leverage Panasonic's optical systems for harsh environment navigation.
Capacitive dominates unit economics across mid-range applications; infrared maintains defensible share in weather-exposed large formats.
End User:
Application-specific durability and certification requirements fragment vendor qualification pathways, with procurement centralization accelerating in regulated verticals.
- Retail:High-traffic self-service and point-of-sale environments demanding 50,000-hour backlight lifespans. Walmart and Carrefour procurement committees are compressing vendor evaluation cycles from eighteen to nine months.
- Education:Price-sensitive bulk procurement with interactive whiteboard and flat panel specifications. Karnataka state tenders in India are opening secondary school volumes exceeding 10,000 units per award.
- Healthcare:Infection control and electromagnetic compatibility mandates under FDA and CE-MDR frameworks. North American hospital systems are centralizing procurement through value-added distributors with integration capabilities.
- Hospitality:Aesthetic integration and spill resistance priorities in restaurant and hotel deployments. Dubai's outdoor digital signage deployers are adopting silver nanowire conductors for 55-inch-plus weather-resistant kiosks.
Retail commands the widest deployment footprint; healthcare exhibits the most stringent qualification barriers.
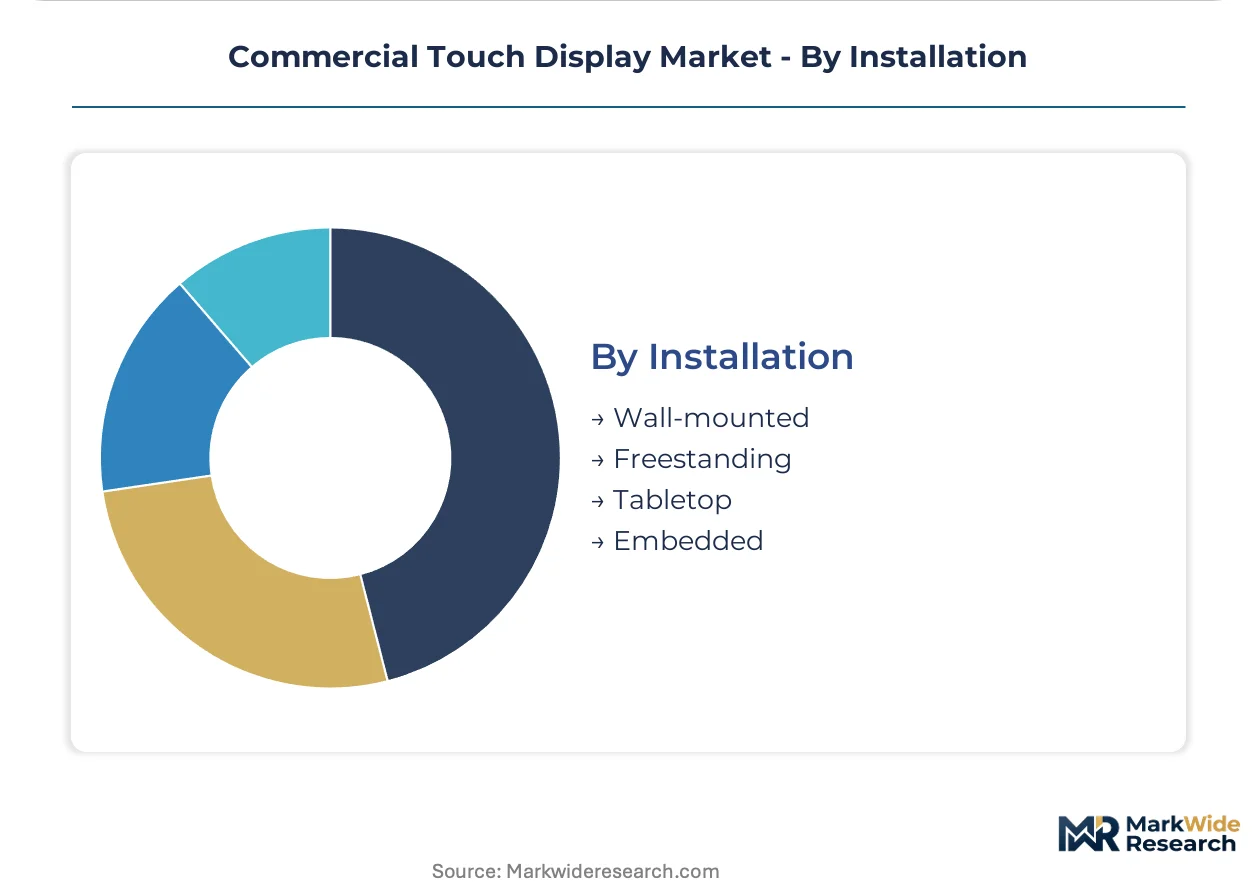
Installation:
Customer type differentiation separates fixed infrastructure investments from flexible deployment models, with total cost of ownership calculations varying by mobility requirements.
- Wall-mounted:Permanent fixture integration with building electrical and network infrastructure. Municipal government facilities in the US are leveraging IRA efficiency credits for ENERGY STAR-certified display upgrades.
- Freestanding:Self-supporting units with integrated cable management and stability engineering. Airport and transit hubs in Singapore prioritize rapid relocation capability for seasonal traffic reconfiguration.
- Tabletop:Horizontal surfaces for collaborative or dining contexts requiring spill resistance and edge durability. Corporate workspace buyers in Frankfurt are specifying haptic feedback integration for premium positioning.
- Embedded:Integration into OEM equipment such as medical devices or industrial machinery. Automotive-grade modules for commercial fleet dashboards face REACH substance restriction requalification burdens under ECHA pressure.
Wall-mounted installations anchor replacement demand; embedded formats are climbing fastest as OEM integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's Guangdong corridor where Gen 10.5 fab scale compresses unit costs, while German buyers absorb premiums for EU Ecodesign-compliant LED retrofits. This asymmetry fragments procurement strategies across installation footprints.
China
Guangdong province hosts the densest concentration of panel fabrication and touch monitor assembly, with Shenzhen's electronics corridor shortening logistics legs for capacitive stack producers. GB standards enforced through SAMR mandate electromagnetic compatibility testing that extends foreign product launch timelines. BOE Technology Group Co., Ltd. anchors massive substrate production near the Pearl River Delta.
Germany
Retail self-service checkout lanes in Berlin and Munich compress replacement cycles to 36 months as 24/7 durability becomes mandatory. The EU Ecodesign Directive's standby power limits accelerate LED backlight retrofits across existing digital signage estates. Industrial clusters in Baden-Württemberg specialize in automotive-grade touch module qualification.
United States
Municipal government facilities leverage IRA efficiency credits for ENERGY STAR-certified display upgrades, particularly in Illinois and California procurement pools. FDA electromagnetic compatibility mandates constrain healthcare vertical qualification pathways. Corporate IT buying committees in North American financial services compress vendor evaluation cycles from eighteen to nine months.
India
Maharashtra and Karnataka state tenders open secondary school volumes exceeding 10,000 interactive flat panel units per award under national digital classroom mandates. BIS certification requirements enforce safety testing through the national standardization administration. Panel assembly operations concentrate near Delhi-NCR to serve education procurement.
Japan
Industrial handheld device manufacturers in Nagoya maintain resistive layer adoption where stylus precision outweighs responsiveness requirements. METI efficiency guidelines shape commercial building retrofit specifications. METI's technical standards for display luminance efficiency filter into procurement criteria for hospitality point-of-sale terminals.
Commercial Touch Display Market Vendor Landscape
Concentration sits with Asian display conglomerates wielding captive semiconductor supply chains. The vendor base stratifies across three tiers: premium interactive kiosk specialists, cost-optimized education suppliers, and ruggedized hospitality operators. Strategic moves center on backward integration into sensor fabrication and geographic expansion through value-added distributor partnerships.
Within the premium-tier vector, Samsung Electronics Co., Ltd. exemplifies captive OLED supply chain leverage, while BOE Technology Group Co., Ltd. anchors scale-driven cost leadership through massive substrate fabrication. Panasonic Connect Co., Ltd. occupies a position within ruggedized optical touch system specialization.
| Leading Market Players |
|---|
| Sharp Corporation |
| ViewSonic Corporation |
| Samsung Electronics Co., Ltd. |
| Barco NV |
| BenQ Corporation |
| LG Electronics Inc. |
| BOE Technology Group Co., Ltd. |
| Christie Digital Systems, Inc. |
| Panasonic Connect Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for indium tin oxide transparent conductors tether pricing volatility to rare earth mining jurisdictions, compressing margin buffers for display manufacturers while amplifying cost leadership for those with backward integration into sensor fabrication.
Pricing Analysis
The customization-premium spread between standard touch monitors and configured-to-order interactive kiosks reaches three-to-one multiples, with project-based pricing dominating large-format deployments. Price differentiation stems from certification grade—ENERGY STAR and EU Ecodesign tiers command fifteen to twenty percent premiums—and volume scale, where education procurement lots exceeding ten thousand units extract steep discounts. Pricing pressure intensifies in the mid-range segment as BOE's Gen 10.5 fab scale compresses unit economics. Education buyers in India exhibit the highest price sensitivity, while healthcare systems in North America absorb premiums for FDA electromagnetic compatibility compliance.
Supply Chain Analysis
Inventory compression to sixty-day cover for cover glass and sensor stack components reflects just-in-time pressures from retail deployment schedules, exposing manufacturers to logistics disruption. Supply concentrates in China, South Korea, and Taiwan, with Guangdong province hosting the densest panel fabrication cluster. Raw material dependencies include indium tin oxide, silver nanowire alternatives, and optical clear adhesives facing REACH reformulation. Single-source vulnerability sits with three Asian suppliers controlling Gen 10.5 glass substrate production for displays exceeding sixty-five inches. Distribution runs through value-added distributors with in-house integration capabilities, displacing direct OEM relationships in North American healthcare and financial services verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—GB standards, FDA electromagnetic compatibility, EU Ecodesign—creates switching costs that cement incumbent positions.
For Market Incumbents: Fortify captive supply chains through backward integration into metal mesh transparent conductor production, insulating against indium price volatility. Deepen channel control by acquiring value-added distributors in North America to capture specification influence from centralizing procurement committees. The threat of silver nanowire substitution in large-format outdoor signage demands R&D investment in weather-resistant bonding processes.
For New Entrants and Emerging Players: Anchor in India's education procurement corridor, where national digital classroom mandates in Maharashtra and Karnataka generate tender volumes exceeding ten thousand units with limited incumbent saturation. Target touch table deployments in European corporate workspaces, where haptic feedback integration creates premium positioning away from commoditized monitor competition. A direct-to-institution go-to-market model bypasses distributor margin extraction.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because optical bonding cleanroom capabilities and certification backlogs create capability scarcity that favors scaled operators. Acquisition targets should display backward integration into sensor fabrication and established ENERGY STAR compliance pathways. The signal to watch is REACH substance restriction enforcement on optical clear adhesives, which would trigger requalification burdens favoring incumbent balance sheets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transparent Conductors | Captive metal mesh production insulates Samsung and BOE from indium supply shocks. |
| Cleanroom Capability Acquisition | Optical bonding expertise in Shenzhen commands wage premiums that scale entrants cannot match. |
| EU Ecodesign Certification Fast-Track | Early LED retrofit positioning captures German and French retail replacement cycles. |
| Value-Added Distributor Partnership | Integration capabilities capture influence from compressing corporate IT evaluation timelines. |
| Silver Nanowire Qualification Program | Weather-resistant conductivity enables Dubai and Singapore outdoor kiosk deployment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with display procurement managers at retail chains, cleanroom engineering directors at panel assembly facilities, and regulatory compliance leads at OEMs. Secondary validation drew from SAMR GB standards documentation, EPA ENERGY STAR certification databases, EU Ecodesign Directive implementing measures, and customs records for transparent conductor imports. Bottom-up unit economics modeling triangulated against top-down market sizing across technology and end-use segments.
Across the analysis window, forecasts employed a volume-value reconciliation framework segmented by product architecture, sensing technology, installation type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating replacement cycle compression in retail environments and education procurement ramp rates. Industry-specific inputs included Gen 10.5 fab capacity utilization rates and REACH substance restriction phase-in timelines.
Decision-makers should treat outputs as directional under assumptions of stable rare earth supply from concentrated mining jurisdictions and sustained EU Ecodesign enforcement; material deviation in indium tin oxide availability or regulatory delay would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Multi-Function Display Market
Display Technologies
Smartphone Display Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Global Transparent Display Market
Display Technologies
Smart Display Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Touch Screen Display Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
Plasma Display Module Market
Display Technologies
Field Emission Display Market
Display Technologies
4K Technology Market
Display Technologies
Touch Screen Film Market
Display Technologies
OLED Panel Market