
 Temperature and Pressure Switches Market | 2026-2036
Temperature and Pressure Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature and Pressure Switches Market Outlook
HVAC system modernization is repositioning demand toward electronic and smart switch platforms across commercial and industrial installations. Honeywell International sustains technology leadership in building automation integration, while Danfoss A/S dominates refrigeration and climate control applications through its specialized sensor portfolio. Parker Hannifin competes in process-intensive segments with ruggedized mechanical switch designs that serve upstream oil and gas operations.
Temperature and pressure switches are electromechanical or solid-state devices that open or close electrical contacts at preset thermal or pneumatic thresholds, typically rated for operating ranges from -40°C to 400°C and pressures from vacuum to 15,000 psi depending on construction. These components protect equipment from thermal runaway, overpressure events, and refrigerant system failures across continuous-process environments. Electronic and smart product types are capturing margin pools as facilities prioritize predictive maintenance and remote diagnostics, while mechanical variants retain share in cost-sensitive process control and chemical applications where simplicity outweighs connectivity requirements. Digital and wireless technologies are expanding fastest in manufacturing end-use settings where Industry 4.0 architectures demand real-time data feeds from distributed assets.
EPA refrigerant management rules, EU F-Gas Regulation phase-down schedules, and OSHA process safety management standards collectively shape product certification requirements and replacement cycles for switch manufacturers serving regulated industries. IEC 60947 and UL 508 standards govern electrical endurance and environmental sealing, creating compliance thresholds that filter marginal suppliers from specification-driven procurement channels. Stakeholders must monitor evolving refrigerant chemistries and associated pressure-temperature envelopes to ensure switch portfolios align with next-generation thermal systems before retrofit waves lock in component selections.
Market Dynamics
The transition from mechanical to electronic sensing architectures is restructuring procurement specifications across process industries, as facility operators prioritize predictive diagnostics over simple threshold detection in capital equipment.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates in Europe are forcing HVAC system retrofits that require compatible pressure-temperature sensing components for new thermal envelopes.
- Industrial automation:Manufacturing facilities in Germany, China, and the United States are deploying Industry 4.0 architectures that demand real-time data feeds from distributed switch assets.
- Smart building integration:Electronic switch platforms with digital output and wireless connectivity are capturing specification preference in commercial building automation projects.
Market Restraints
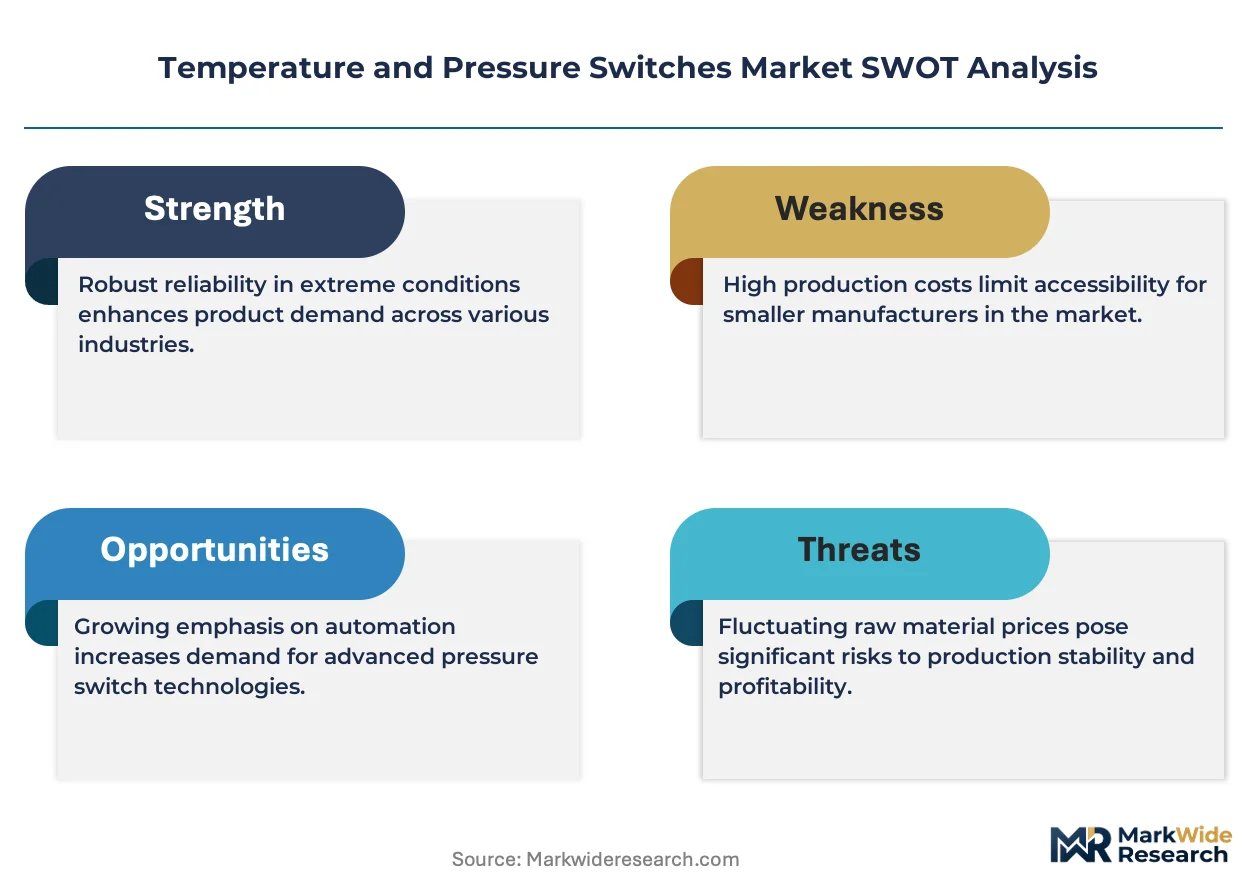
- Input cost volatility:Stainless steel and specialized elastomer prices fluctuate with energy markets, compressing margins for mechanical switch manufacturers serving price-sensitive process control segments.
- Technical limitation:Solid-state designs face temperature range constraints above 150°C in high-heat industrial applications where bimetallic mechanical switches retain performance advantages.
- Substitution threat:Distributed sensor networks with programmable logic controllers are displacing discrete switches in some continuous-process monitoring applications.
Strategic Opportunities
- Underpenetrated application:Hydrogen infrastructure buildout in Germany and the Netherlands requires specialized high-pressure switches for fueling station and pipeline safety systems.
- Regulatory tailwind:OSHA process safety management standards in the United States are mandating redundant sensing architectures in chemical processing facilities.
- Technology convergence:Integration of MEMS pressure sensing with IoT communication protocols is opening service-contract revenue streams for switch manufacturers.
Industry Challenges
- Certification timeline:IEC 60947 and UL 508 testing protocols require 12-18 month validation cycles that delay product launches and compress competitive windows.
- Integration complexity:Legacy mechanical switch installations in upstream oil and gas facilities resist retrofit with electronic alternatives due to wiring infrastructure replacement costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature and Pressure Switches Market |
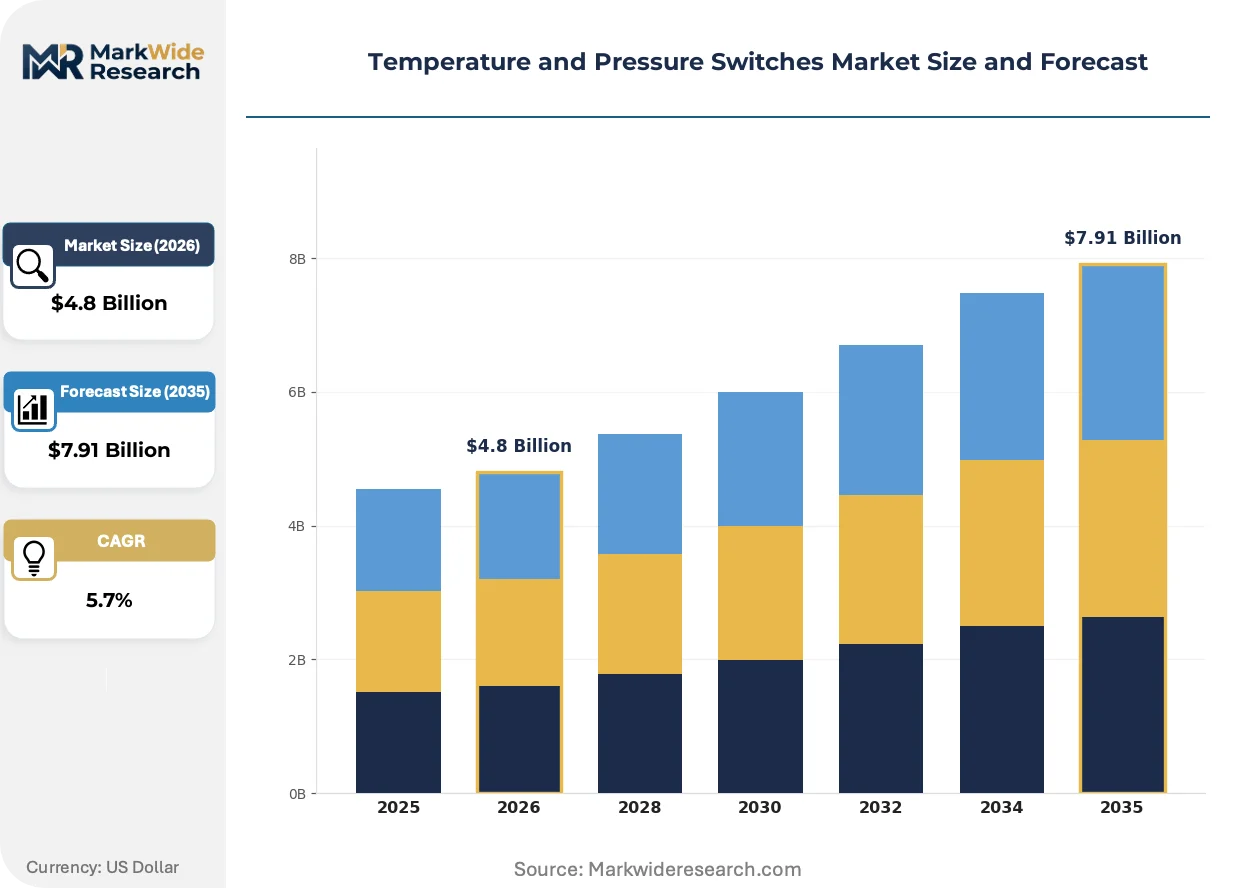
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Smart, Differential Application: HVAC, Process Control, Chemical, Oil & Gas End User: Manufacturing, Automotive, Aerospace, Pharmaceuticals Technology: Analog, Digital, Wireless, Hybrid |
| Companies Covered | ABB Ltd., Eaton Corporation, Danfoss A/S, Honeywell International Inc., Parker Hannifin Corporation, Schneider Electric, SMC Corporation, Baumer Holding AG, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature and Pressure Switches Market Strategic Shifts
Digital sensing architectures are displacing electromechanical designs across temperature and pressure monitoring applications, with facility operators demanding remote diagnostic capabilities that reduce unplanned downtime in distributed assets.
MEMS-based pressure transducers are automating condition monitoring in rotating equipment and hydraulic systems. Pulp and paper mills in Finland and Sweden are adopting these solid-state platforms at accelerated pace. The technology is automating the shift from scheduled maintenance to predictive intervention models that compress total cost of ownership.
EPA refrigerant management rules are tightening leak detection and repair requirements for commercial refrigeration systems. Equipment owners must install compatible sensing components that monitor pressure-temperature relationships for regulated chemistries. Supermarket chains in California and New York are responding with system-wide retrofit programs that specify electronic switch platforms.
After-sales service unbundling is fragmenting traditional distribution relationships in the industrial sector. End-users in Texas and Louisiana petrochemical corridors are sourcing switches directly from manufacturers while contracting calibration and replacement services to third-party maintenance providers. This pattern is most visible in continuous-process environments where uptime guarantees override brand loyalty in supplier selection.
Temperature and Pressure Switches Market Segmentation
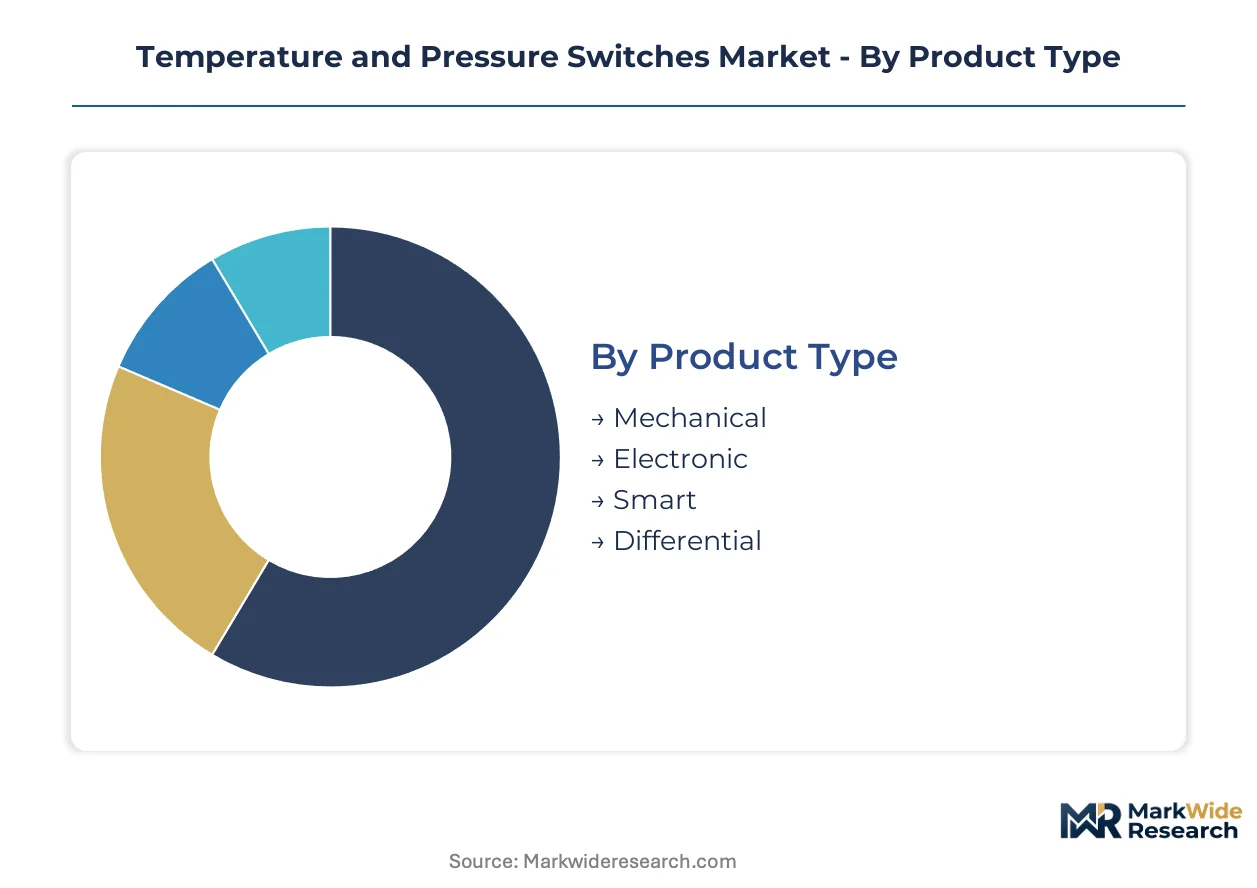
Switch architecture choices determine integration complexity across standalone safety systems versus embedded IoT networks. Procurement patterns diver sharply between facilities modernizing toward predictive maintenance and those maintaining legacy electromechanical infrastructures.
Product Type:
Mechanical variants operate as discrete threshold detectors without external power requirements, while electronic and smart platforms embed signal conditioning and communication protocols for distributed control architectures.
- Mechanical:Bimetallic and bourdon tube constructions achieve setpoint accuracy within 2-5% across temperature ranges exceeding 300°C. Chemical processing facilities in Texas and Louisiana specify these for intrinsic safety in hazardous area classifications where spark-free operation is mandatory.
- Electronic:Solid-state designs with 4-20mA or digital outputs enable programmable setpoints and remote configuration. HVAC retrofit programs in Germany and California are specifying these for F-Gas compliant refrigeration systems requiring precise superheat monitoring.
- Smart:MEMS-based sensors with embedded microprocessors and wireless connectivity support edge computing and cloud-based analytics. These command premium positioning in manufacturing facilities deploying Industry 4.0 architectures.
- Differential:Dual-sensing elements measure pressure or temperature deltas across filters, pumps, or heat exchangers. These serve filtration monitoring in pharmaceutical cleanrooms and compressor protection in natural gas processing.
Mechanical switches lead volumes today; smart platforms are gaining share fastest.
Application:
Specification intensity varies with process criticality, from comfort control in commercial buildings to safety instrumented systems in hydrocarbon processing.
- HVAC:Refrigeration and climate control applications specify pressure-temperature switches for compressor cycling, defrost initiation, and high-pressure cutout protection. EU F-Gas Regulation compliance is accelerating replacement cycles across supermarket chains and cold storage facilities.
- Process Control:Continuous manufacturing environments demand redundant sensing for pump protection, tank level indication, and thermal runaway prevention. Pulp and paper mills in Finland are adopting digital architectures for condition-based maintenance.
- Chemical:Aggressive media compatibility requirements favor hermetically sealed mechanical designs or corrosion-resistant electronic housings. OSHA process safety management standards mandate redundant architectures for high-hazard processes.
- Oil & Gas:Upstream production and midstream pipeline operations specify ruggedized switches for wellhead protection, separator level control, and compressor station safety. These applications prioritize mechanical reliability over connectivity in remote locations.
HVAC commands the largest installed base; process control applications are climbing the fastest.
End User:
Capital intensity and automation maturity shape procurement preferences across industrial sectors with varying equipment lifecycle horizons.
- Manufacturing:Discrete and process manufacturers deploy switches for machine tool coolant monitoring, hydraulic system protection, and oven temperature control. German automotive suppliers are specifying smart platforms for predictive maintenance integration.
- Automotive:Vehicle and component production facilities use pressure switches for pneumatic system monitoring and temperature switches for paint curing ovens. Electric vehicle battery manufacturing is creating demand for precision thermal management sensing.
- Aerospace:Commercial aviation and defense applications specify MIL-qualified switches for fuel system monitoring, environmental control, and engine bleed air management. Certification requirements limit supplier qualification to established aerospace specialists.
- Pharmaceuticals:FDA-regulated manufacturing demands calibrated, traceable sensing for autoclave validation, cleanroom differential pressure, and bioreactor temperature control. These applications prioritize documentation and audit trails over unit cost.
Manufacturing dominates current procurement; pharmaceutical applications show the steepest expansion trajectory.
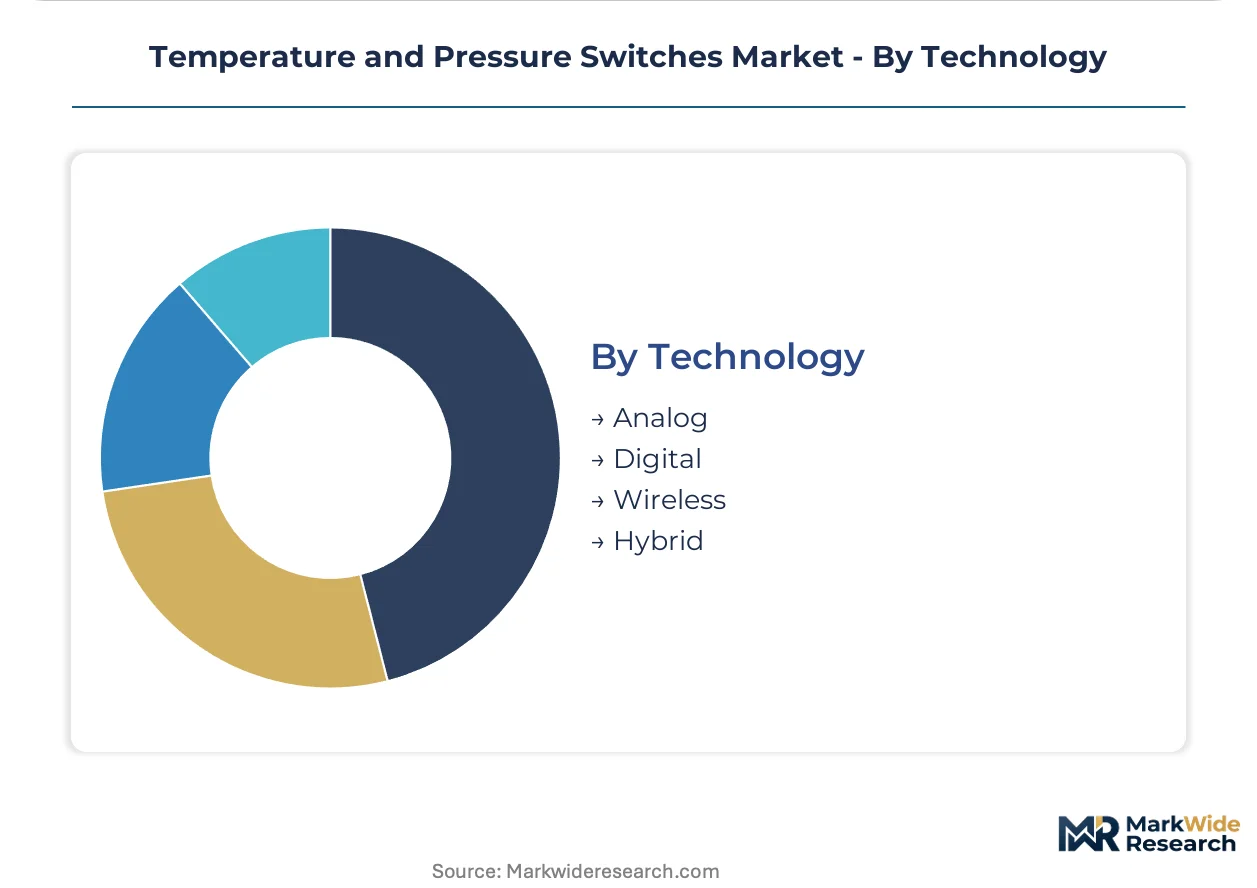
Technology:
Signal output format determines compatibility with existing control infrastructure and data architecture upgrade paths.
- Analog:Continuous 4-20mA or voltage outputs provide proportional signaling for process variable indication. These bridge legacy control systems and modern distributed control architectures during facility modernization.
- Digital:Discrete on/off outputs with solid-state relays or open-collector configurations integrate directly with programmable logic controllers. These dominate new installations in automated manufacturing environments.
- Wireless:Battery-powered or energy-harvesting designs with Bluetooth, LoRa, or proprietary protocols eliminate wiring infrastructure in retrofit applications. These are penetrating asset monitoring in rotating equipment and remote tank farms.
- Hybrid:Combined analog and digital outputs with local display and network connectivity serve transitional installations. These accommodate facilities migrating from mechanical to fully electronic architectures.
Analog technologies retain the largest installed base; wireless platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing manufacturing capacity as producers seek jurisdictions with streamlined certification timelines and lower compliance burdens. The EU F-Gas Regulation and OSHA process safety mandates create divergent cost structures that influence facility siting decisions.
United States
OSHA process safety management standards mandate redundant sensing architectures in Gulf Coast petrochemical corridors. Texas and Louisiana facilities specify ruggedized mechanical switches for intrinsic safety in hazardous area classifications. Houston anchors the largest concentration of upstream oil and gas switch procurement.
Germany
Industrial automation investments in automotive and machinery sectors drive specification of smart switch platforms with predictive diagnostics. The EU F-Gas Regulation accelerates HVAC retrofit cycles across commercial building stock. Bavaria's manufacturing clusters prioritize Industry 4.0 integration for distributed asset monitoring.
China
MIIT industrial internet initiatives propel digital sensing adoption in Yangtze River Delta manufacturing hubs. Dual carbon goals tighten energy-efficiency codes for commercial building automation. Shanghai and Shenzhen lead procurement of electronic pressure-temperature switches for refrigeration system modernization.
Japan
METI energy conservation standards elevate specification thresholds for HVAC components in commercial facilities. Automotive production lines in Aichi Prefecture deploy precision thermal management sensing for electric vehicle battery manufacturing. Nagoya industrial clusters emphasize predictive maintenance integration.
India
PLI scheme incentives attract component manufacturing for process industries serving domestic and export markets. BIS certification requirements filter supplier qualification in pharmaceutical and chemical processing applications. Gujarat's chemical corridors specify corrosion-resistant switch housings for aggressive media environments.
Temperature and Pressure Switches Market Competitive Environment
Portfolio diversification dominates the current landscape as established electromechanical suppliers layer electronic and smart platforms atop legacy mechanical foundations. The market structures around three tiers: diversified industrial conglomerates with building automation integration capabilities, specialized climate control component houses, and regional mechanical switch fabricators serving price-sensitive process segments. Strategic archetypes include full-stack automation providers, refrigeration-focused specialists, and ruggedized upstream oil and gas suppliers. Technology licensing and backward integration into MEMS sensing elements represent the dominant competitive vectors.
Among diversified industrial conglomerates, ABB Ltd. and Eaton Corporation exemplify the automation-integrated archetype with broad sensing portfolios spanning discrete threshold detection through predictive analytics platforms. Danfoss A/S occupies a specialist position within climate control applications, while Honeywell International Inc. anchors building automation integration capabilities. Parker Hannifin Corporation represents the ruggedized mechanical segment serving process-intensive environments where reliability overrides connectivity requirements.
| Leading Market Players |
|---|
| ABB Ltd. |
| Eaton Corporation |
| Danfoss A/S |
| Honeywell International Inc. |
| Parker Hannifin Corporation |
| Schneider Electric |
| SMC Corporation |
| Baumer Holding AG |
| Emerson Electric |
| Others |
Value Chain & Pricing Dynamics
Stainless steel price indices cascade through temperature and pressure switch manufacturing tiers, compressing margins for mechanical fabricators serving price-sensitive process control segments while reinforcing premium positioning for electronic platforms with MEMS sensing elements. Input cost volatility in specialized elastomers and bourdon tube alloys feeds into three-tier pricing stratification across premium smart switches, standard electronic variants, and economy mechanical designs.
Pricing Analysis
Distributor markups spanning 25-40 percent separate OEM direct procurement from aftermarket channel sales, with volume discounts compressing this spread for hyperscale buyers in automotive and HVAC sectors. Price differentiation hinges on UL 508 certification tier and after-sales service bundling, with unbundled calibration contracts commanding premium positioning in pharmaceutical cleanroom applications. Cost compression in mechanical switch tiers is intensifying because stainless steel price volatility erodes fabricator margins in Texas and Louisiana petrochemical corridors. Chemical processing facilities exhibit highest price sensitivity due to commoditized safety instrumented system specifications, while pharmaceutical end-users prioritize audit trail documentation over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German automotive suppliers and Chinese HVAC equipment manufacturers, while authorized distributors serve fragmented maintenance-replacement-organized procurement in upstream oil and gas operations. Manufacturing concentrates in Germany, China, and the United States, with component sourcing drawing from Taiwan for MEMS sensing elements and Japan for precision bimetallic materials. Supply chain risk centers on single-source vulnerability for IEC 60947-certified switch housings, where 12-18 month validation timelines lock in supplier relationships. Distribution runs through regional industrial distributors in North America, integrated automation vendors in Europe, and direct manufacturer relationships in Asia-Pacific manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Temperature and pressure switches constitute a late-cycle quality story as facility operators prioritize predictive maintenance specifications over threshold-detection commoditization. Specification preference for smart platforms with embedded diagnostics is concentrating procurement power with suppliers offering integrated service contracts.
For Market Incumbents: Hedge mechanical switch margin erosion by accelerating MEMS sensing backward integration and capturing IEC 60947 certification capacity before retrofit waves lock in component selections. Channel control through direct calibration service contracts protects positioning against third-party maintenance provider fragmentation in Gulf Coast petrochemical corridors. Capacity addition in Bavaria and Shanghai manufacturing clusters reinforces proximity to automotive and HVAC OEM specification centers. For New Entrants and Emerging Players: E-commerce procurement platforms targeting MRO replacement demand in Texas and Louisiana petrochemical facilities bypass entrenched distributor relationships. Hydrogen infrastructure buildout in Germany and the Netherlands offers the most penetrable white-space target, with specialized high-pressure switch requirements unmet by incumbent refrigeration-focused portfolios. Aftermarket service unbundling creates direct manufacturer engagement opportunities with uptime-guarantee contracting. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing MEMS sensing IP and IoT protocol integration capabilities. Long-term viability over a 5-10 year horizon favors platforms with recurring revenue from predictive maintenance service contracts rather than transactional hardware sales. Watch for inflection signals in OSHA process safety management enforcement intensity, which would accelerate redundant sensing architecture mandates across chemical processing facilities.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Sensing Backward Integration | Captive supply of pressure transducer elements protects margin structure against Taiwan foundry concentration. |
| Wireless Protocol Certification | Bluetooth and LoRa module qualification opens retrofit demand in rotating equipment monitoring applications. |
| Hydrogen Pressure Switch Development | Specialized 700-bar sensing platforms capture German and Dutch fueling station safety system specifications. |
| Aftermarket Service Unbundling | Direct calibration contracts with Texas petrochemical operators bypass traditional distributor relationships. |
| EU F-Gas Compliance Portfolio Expansion | Electronic switch platforms with superheat monitoring align with refrigerant-phase-down retrofit cycles. |
Study Parameters
Bottom-up HVAC and process control modeling reconciled against top-down sensor manufacturer shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors at pulp and paper mills, OEM procurement teams in automotive tier-1 suppliers, and aftermarket service heads in Gulf Coast petrochemical facilities combined with secondary validation from SEC 10-K filings, IEC certification databases, and customs trade data. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity across mechanical, electronic, and smart switch architectures.
Historical trendline analysis of refrigerant regulation compliance cycles and industrial automation capex patterns informs the projection framework. The model segments by switch architecture, application intensity, and end-user automation maturity across the analysis window, with CAGR derivation anchored in F-Gas Regulation retrofit timelines and OSHA process safety enforcement trajectories. Industry-specific inputs include MIIT industrial internet adoption curves and METI energy conservation standard revision schedules.
The model assumes a particular technology adoption path; alternative pathways for solid-state sensing above 150°C would alter the outlook for mechanical switch retention in high-heat industrial applications. Forecasts reflect base-case assumptions regarding refrigerant chemistry transitions and Industry 4.0 deployment rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Transfer Switch Market
Switches
Membrane Switch Market
Switches
Antenna Switch Module Market
Switches
High-Voltage Disconnect Switch Market
Switches
Miniature-Circuit Breaker Market
Switches
Mexico Rocker Switch Market
Switches
Rotary Limit Switches Market
Switches
Japan Reed Sensors Switches Market
Switches
Asia Pacific Transfer Switches Market
Switches
Push Button Dropper Market
Switches
Low Voltage Disconnect Switch Market
Switches
In-Wall Smart Switch Market
Switches
South Korea Reed Sensors Switches Market
Switches
Europe Switchgear Market
Switches
Electronic Shift-By-Wire Selector Modules Market
Switches
Safety Limit Switches Market