
 Safety Limit Switches Market | 2026-2036
Safety Limit Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Limit Switches Market Outlook
Asset-light leasing models for industrial automation components is fragmenting competitive dynamics among safety switch suppliers. Rockwell Automation leverages its integrated safety portfolio to capture recurring service revenue from leased equipment fleets. Siemens anchors its position through captive financing arms that lower upfront barriers for mid-sized European manufacturers. Schneider Electric differentiates by bundling limit switches with energy management software under subscription contracts.
Safety limit switches are electromechanical or electronic position-sensing devices with actuating forces typically rated between 5 N and 50 N, designed to interrupt power circuits when mechanical travel exceeds predetermined thresholds. They serve as the final physical safeguard in automated machinery, preventing crushing, shearing, or entanglement hazards at conveyor endpoints, press brakes, and robotic work envelopes. Electromechanical variants still occupy the largest installed base due to proven resilience in high-vibration forging and stamping environments, though non-contact magnetic and smart technologies with IO-Link diagnostics represent the fastest-growing margin pools as predictive maintenance contracts expand. Contact-based installations dominate legacy retrofit volumes, while flush-mounted configurations gain share in cleanroom pharmaceutical packaging lines where surface contamination risks override accessibility priorities.
OSHA machine guarding standards and the EU Machinery Directive, enforced by national bodies like Germany's KBA and France's ANSM for workplace safety coordination, mandate redundant limit switch circuits on equipment with automatic restart hazards. IEC 60947-5-1 certification from ISO-notified bodies gates market access for exports into European manufacturing supply chains. Stakeholders must weigh the capital intensity of smart switch migration against the contractual liability reductions that diagnostic-enabled architectures offer in litigation-prone jurisdictions.
Market Dynamics
Retrofit cycles across automotive stamping plants are compressing replacement timelines for electromechanical limit switches, as EV platform conversions demand higher-positioning accuracy and faster diagnostic feedback loops than legacy mechanical designs can deliver.
Growth Catalysts
- OSHA machine guarding enforcement:Inspection intensity at US metal fabrication facilities has doubled since 2022, forcing overdue upgrades on mechanical presses and shearing equipment. Plants in Michigan and Ohio now budget for redundant limit switch circuits as a standard line item.
- Steel processing automation:Chinese blast furnace modernization programs specify heavy-duty roller lever switches rated for 50 N actuating force in high-temperature slag handling zones. Procurement volumes from Baowu Steel and Shagang Group anchor regional demand.
- IO-Link diagnostic integration:Smart limit switches with predictive maintenance capabilities command premium positioning in German automotive supply chains. Tier-1 suppliers embed these devices into leased equipment fleets to minimize unplanned downtime penalties.
Market Restraints
- Copper and silver contact material costs:Electromechanical switch manufacturing faces input volatility from precious metal markets. Contact plating thickness specifications from IEC 60947-5-1 prevent material substitution without recertification.
- Single-source magnetic sensor dependence:Rare-earth magnet supply concentrates in Chinese processing facilities. Non-contact magnetic limit switch producers face concentration risk from export quota fluctuations.
- CE marking timeline friction:EU Machinery Directive conformity assessment delays average 14-18 months for new smart switch architectures. Notified body backlog gates market entry for innovative diagnostic-enabled designs.
Strategic Opportunities
- India PLI scheme for industrial automation:Domestic manufacturing incentives for automotive component production create first-mover positioning for limit switch suppliers establishing local assembly. Tamil Nadu and Gujarat industrial corridors offer tax holiday structures.
- Pharmaceutical cleanroom packaging:Flush-mounted limit switches with IP69K sealing penetrate aseptic filling line retrofits. Surface contamination elimination overrides maintenance accessibility in FDA-regulated biologics facilities.
- Wireless and energy harvesting convergence:Battery-free magnetic switches eliminate cable routing in mobile robotic work envelopes. Integration with industrial wireless protocols opens retrofit applications where conduit installation is cost-prohibitive.
Industry Challenges
- Functional safety engineer scarcity:IEC 61508 SIL certification expertise concentrates in German and Swiss engineering consultancies. System integrators in emerging manufacturing regions face 6-9 month hiring timelines for qualified safety system designers.
- Legacy 24V DC integration complexity:Smart switches with IO-Link outputs require gateway infrastructure incompatible with existing PLC architectures. Brownfield automotive plants face rip-and-replace decisions on control cabinet investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Limit Switches Market |
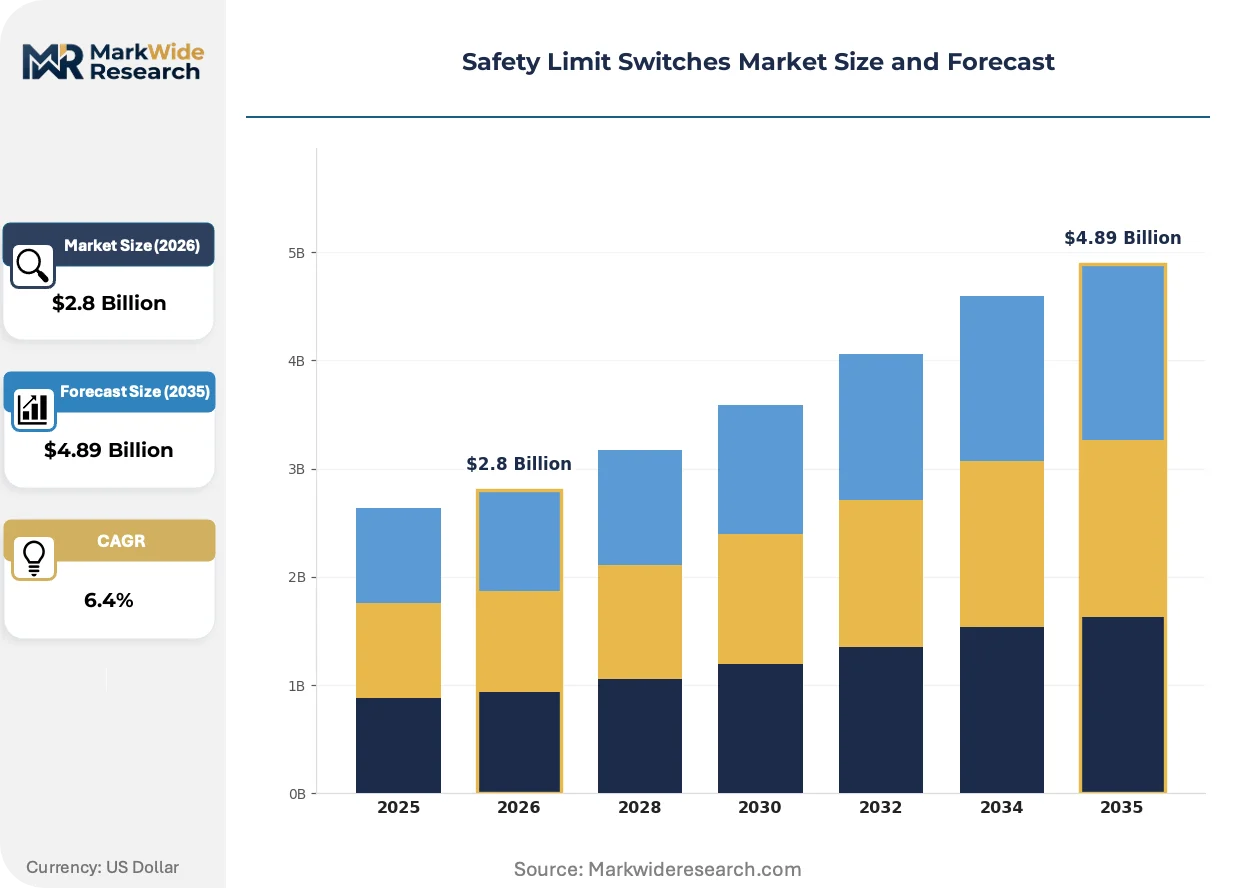
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Electronic, Pneumatic, Hydraulic Technology: Contact, Non-contact, Smart, Magnetic End User: Manufacturing, Oil & Gas, Automotive, Aerospace Installation: Panel-mounted, Surface-mounted, Flush-mounted, Recessed |
| Companies Covered | Rockwell Automation, Honeywell International, Omron, SICK AG, Siemens, ABB, Schneider Electric, Eaton, Schmersal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Limit Switches Market Strategic Shifts
Diagnostic-enabled architectures are redefining value capture in industrial position sensing, compressing hardware margins while expanding recurring service revenue pools through predictive maintenance contracts and remote monitoring subscriptions.
Non-contact magnetic sensing is migrating from niche cleanroom applications into mainstream metal stamping environments. Tier-2 automotive suppliers in Stuttgart and Wolfsburg now specify magnetic limit switches for press brake guarding to eliminate mechanical wear points. The technology is migrating from premium positioning toward volume replacement of roller lever designs in moderate-vibration applications.
REACH substance restrictions on nickel compounds are forcing contact material reformulations for electromechanical switches exported into European supply chains. ECHA authorization requirements now cover specific plating chemistries used in high-cycle industrial applications. Switch manufacturers with German Notified Body relationships gain accelerated market access versus competitors dependent on third-party testing laboratories.
Leasing structures for automated equipment are unbundling safety component procurement from capital equipment purchases. German mid-sized manufacturers now acquire limit switches through captive financing arms rather than direct ownership. This behavioral shift concentrates specification authority with fleet managers rather than plant engineering departments, privileging suppliers with integrated service portfolios.
Safety Limit Switches Market Segmentation
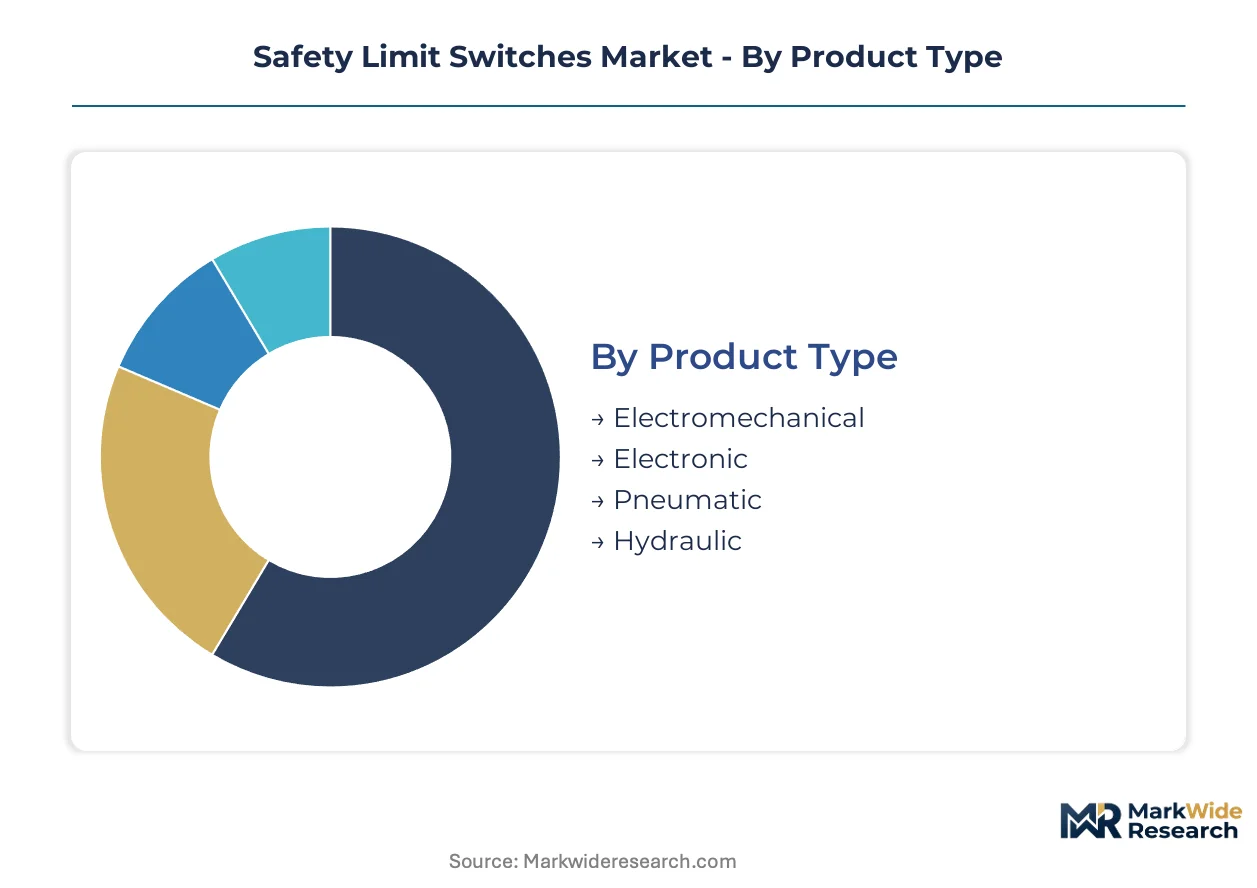
Segmentation in safety limit switches determines service contract structures and replacement cycle economics. After-sales intensity varies sharply across electromechanical versus smart architectures, reshaping supplier revenue models and customer lifetime value calculations.
Product Type:
After-sales-service intensity diverges fundamentally across product categories, with electromechanical variants demanding scheduled contact replacement while electronic designs shift revenue toward firmware updates and calibration services.
- Electromechanical:Physical contact mechanisms with copper-silver alloy plating require periodic replacement in high-cycle forging environments. Demand concentrates in Chinese steel processing corridors where Baowu Steel and Shagang Group specify heavy-duty roller lever designs rated for 50 N actuating force in slag handling zones.
- Electronic:Solid-state position sensing eliminates mechanical wear points and enables diagnostic feedback loops. German automotive stamping plants specify these for EV platform conversions requiring positioning accuracy beyond legacy mechanical tolerances.
- Pneumatic:Compressed-air actuation suits explosive atmosphere applications in petrochemical facilities.
- Hydraulic:High-force actuation for heavy press guarding in shipbuilding and metal forming.
Electromechanical holds the largest share; momentum sits with electronic variants.
Technology:
Cost tier stratification separates premium diagnostic-enabled architectures from commodity contact-based installations, with margin pools concentrating in IO-Link-enabled predictive maintenance contracts.
- Contact:Physical circuit interruption through mechanical actuator movement remains the installed base majority. US metal fabrication facilities facing intensified OSHA inspection protocols specify redundant contact circuits on mechanical presses and shearing equipment in Michigan and Ohio industrial corridors.
- Non-contact:Magnetic and capacitive sensing eliminates mechanical wear and enables sealed enclosures. Tier-2 automotive suppliers in Stuttgart and Wolfsburg specify magnetic limit switches for press brake guarding to remove mechanical failure points from high-vibration environments.
- Smart:IO-Link diagnostic integration enables predictive maintenance and remote monitoring subscriptions.
- Magnetic:Rare-earth magnet dependence creates supply concentration risk from Chinese processing quotas.
Contact technology dominates installed value; smart architectures are climbing the fastest.
End User:
Application-specific durability requirements drive specification divergence, with automotive and oil & gas demanding divergent certification standards and replacement protocols.
- Manufacturing:Broad deployment across packaging, material handling, and assembly automation with varying cycle frequency requirements.
- Oil & Gas:Explosion-proof and corrosion-resistant specifications for offshore platforms and refinery environments.
- Automotive:EV platform retrofit cycles compress replacement timelines as electromechanical designs fail to deliver diagnostic feedback speeds required for battery assembly automation. OEMs in Germany and the United States anchor procurement for high-precision variants.
- Aerospace:MIL-spec certification and traceability requirements for airframe assembly and test equipment.
Manufacturing captures the broadest deployment base; automotive delivers the steepest expansion trajectory.
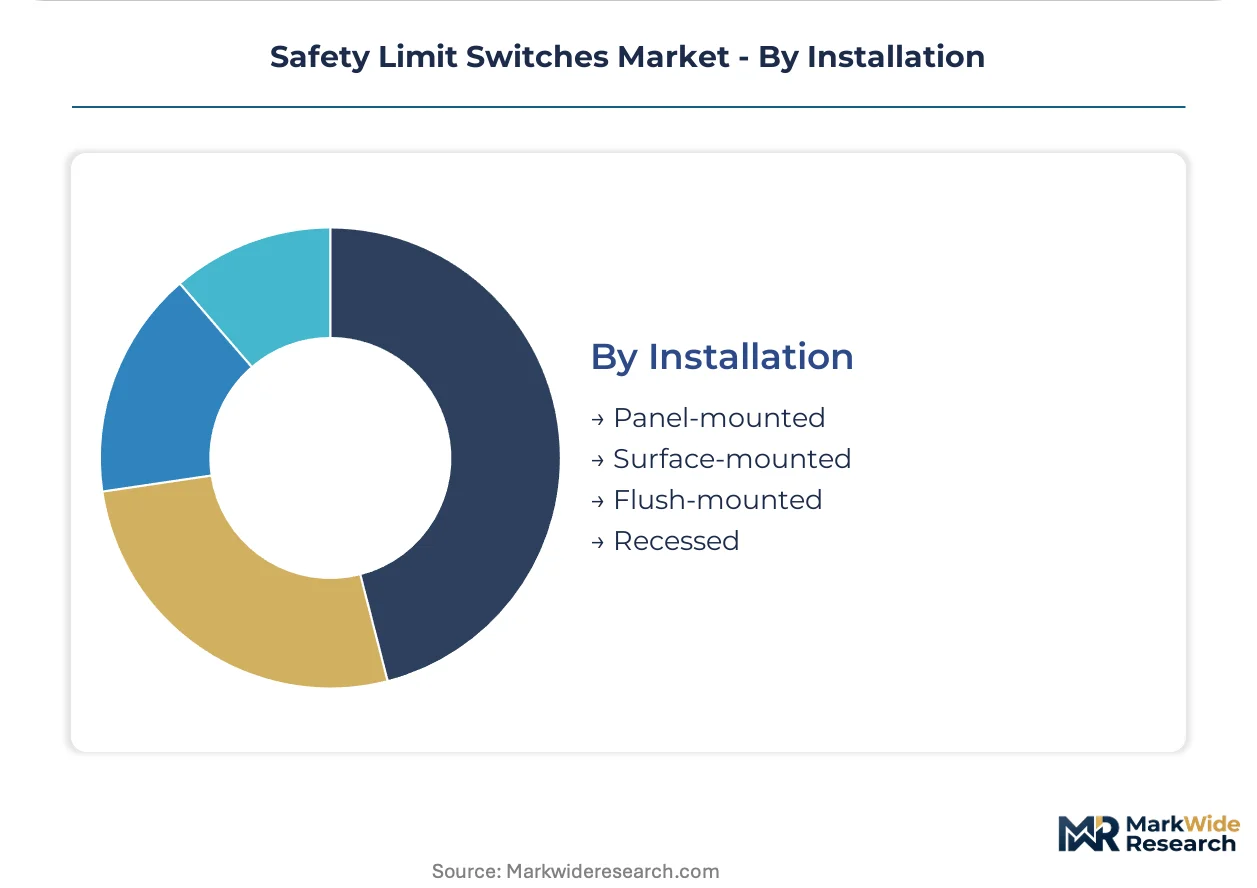
Installation:
Volume concentration favors surface-mounted configurations in brownfield retrofits, while flush-mounted designs command premium positioning in contamination-sensitive environments.
- Panel-mounted:Standard control cabinet integration for centralized safety system architectures.
- Surface-mounted:External machinery attachment dominates legacy equipment retrofit volumes across industrial facilities.
- Flush-mounted:Sealed surface continuity for cleanroom pharmaceutical packaging lines where IP69K rating eliminates contamination risks. FDA-regulated biologics facilities in North Carolina and Massachusetts specify these for aseptic filling line retrofits where surface integrity overrides maintenance accessibility.
- Recessed:Embedded protection for mobile equipment and robotic work envelopes.
Surface-mounted holds the largest share; flush-mounted is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics concentrate safety limit switch procurement in manufacturing powerhouses with heavy industrial bases, while regulatory divergence across jurisdictions fragments certification requirements for suppliers serving multiple markets.
China
Baowu Steel and Shagang Group anchor blast furnace modernization programs specifying heavy-duty roller lever switches rated for 50 N actuating force in high-temperature slag handling zones. GB standards administered by SAMR govern domestic certification, though IEC 60947-5-1 compliance remains mandatory for European-bound exports. Yangtze River Delta industrial clusters drive procurement volume for steel processing automation.
Germany
Automotive stamping plants in Stuttgart and Wolfsburg compress replacement timelines as EV platform conversions demand diagnostic feedback speeds beyond legacy mechanical tolerances. KBA enforces EU Machinery Directive workplace safety coordination alongside CE marking requirements. Tier-2 automotive suppliers specify magnetic limit switches for press brake guarding to eliminate mechanical wear points.
United States
Metal fabrication facilities in Michigan and Ohio face doubled OSHA inspection intensity since 2022, forcing redundant limit switch circuits onto mechanical presses and shearing equipment. Michigan and Ohio industrial corridors now budget compliance upgrades as standard line items. FDA-regulated biologics facilities in North Carolina and Massachusetts specify flush-mounted IP69K designs for aseptic filling line retrofits.
India
Domestic manufacturing incentives under the PLI scheme for automotive component production create first-mover positioning for suppliers establishing local assembly. Tamil Nadu and Gujarat industrial corridors offer tax holiday structures for industrial automation component manufacturing. BIS standards govern domestic certification while exporters maintain IEC compliance for European market access.
Japan
Automotive OEMs and precision machinery manufacturers specify high-reliability variants for robotic work envelope applications. METI coordinates industrial safety standards with JIS certification requirements. Kanto and Chubu industrial regions concentrate demand for cleanroom-compatible designs in semiconductor packaging equipment.
Safety Limit Switches Market Competitive Environment
On the supply side, the industry is consolidating around integrated automation portfolios that bundle hardware with recurring service revenue streams. Electromechanical specialists compete against diversified industrial conglomerates with captive financing arms. Three strategic archetypes dominate: integrated safety portfolio providers, component specialists with regional manufacturing footprints, and diversified electrification conglomerates. M&A activity targets diagnostic software capabilities, while geographic expansion focuses on PLI-linked jurisdictions in South Asia.
Among diversified industrial conglomerates, Rockwell Automation, Siemens, and Schneider Electric exemplify the integrated portfolio archetype. Rockwell Automation leverages recurring service revenue from leased equipment fleets. Siemens anchors positioning through captive financing arms lowering upfront barriers for mid-sized European manufacturers. Schneider Electric differentiates through subscription-contract bundling with energy management software.
| Leading Market Players |
|---|
| Rockwell Automation |
| Honeywell International |
| Omron |
| SICK AG |
| Siemens |
| ABB |
| Schneider Electric |
| Eaton |
| Schmersal |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion amplifies freight cost volatility for electromechanical switch imports, compressing margins on standard-grade products while premium diagnostic-enabled variants absorb logistics premiums through subscription bundling. This corridor's cost dynamics concentrate pricing power with integrated suppliers possessing captive regional assembly, forcing transactional competitors toward material substitution or extended payment concessions.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with IO-Link diagnostic integration and SIL certification grade serving as the primary price differentiation drivers. Cost compression in economy-tier electromechanical variants is intensifying because copper-silver contact plating specifications from IEC 60947-5-1 prevent material downsizing without recertification. Tier-2 automotive suppliers in Germany exhibit the highest price sensitivity due to EV platform conversion budget constraints, while FDA-regulated pharmaceutical OEMs accept premium positioning for IP69K flush-mounted designs where contamination liability overrides procurement cost discipline.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement negotiations as captive financing arms at Siemens and Schneider Electric leverage balance-sheet capacity to lock in specification authority. Manufacturing concentrates in China, Germany, and the United States, with rare-earth magnet processing for non-contact sensors drawing from Chinese facilities subject to export quota volatility. Single-source vulnerability in neodymium supply chains feeds tariff exposure for magnetic switch architectures. Distribution runs through authorized industrial automation distributors with regional service capabilities, though direct OEM relationships are gaining share in automotive leasing-fleet structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
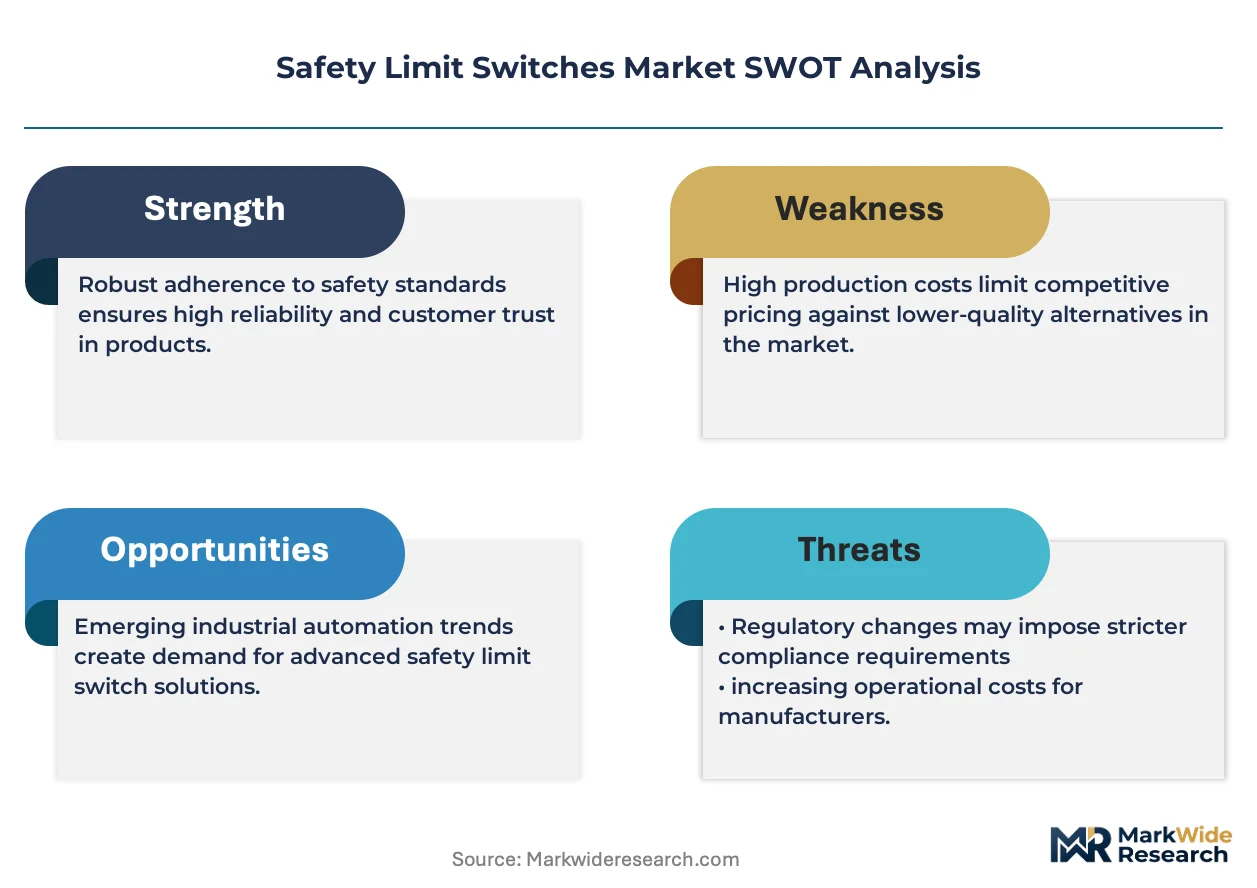
IO-Link diagnostic integration is compressing hardware replacement cycles while expanding recurring service revenue pools, creating a high-growth disruption window as predictive maintenance contracts displace transactional component sales.
For Market Incumbents: Entrench specification authority through captive financing arms that embed limit switches into leased equipment fleets, neutralizing price competition from component specialists. Defend margin position by accelerating SIL certification acquisition for smart switch architectures before CE marking backlogs lengthen further. Prioritize backward integration into contact material plating to offset precious metal cost volatility from IEC 60947-5-1 specifications. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-linked Tamil Nadu and Gujarat industrial corridors where domestic assembly requirements create first-mover positioning ahead of incumbent localization. Target wireless energy-harvesting magnetic switches for mobile robotic applications where cable routing costs block legacy electromechanical retrofit. Pursue pharmaceutical cleanroom packaging as the most penetrable vertical, leveraging flush-mounted IP69K designs to bypass entrenched automotive supply chain relationships. For Investors and Strategic Acquirers: Diagnostic software specialists with FDA-validated predictive maintenance platforms represent the most attractive acquisition archetype for long-term viability across the 5-10 year service revenue expansion window. Monitor CE marking timeline friction at German Notified Bodies as the critical inflection signal—accelerated conformity assessment relationships will separate winners from gated market entrants in smart switch architectures.| Strategic Initiative | Industry Significance |
|---|---|
| IO-Link Diagnostic Integration | Enables predictive maintenance subscriptions that displace transactional hardware margins in German automotive supply chains. |
| Captive Financing Arm Expansion | Siemens and Schneider Electric leverage balance-sheet capacity to lower upfront barriers for mid-sized European manufacturers. |
| India PLI Localization | Tamil Nadu and Gujarat tax holiday structures create first-mover positioning for domestic assembly of automotive-grade switches. |
| REACH-Compliant Contact Reformulation | ECHA nickel compound restrictions force plating chemistry redesigns that favor suppliers with German Notified Body relationships. |
| Wireless Energy-Harvesting Development | Battery-free magnetic switches eliminate cable routing costs in mobile robotic work envelopes for brownfield retrofit applications. |
Study Parameters
A spread of perspectives from plant engineers at steel processing facilities, OEM procurement teams in automotive stamping operations, aftermarket service directors, and regulatory compliance officers at notified bodies converged on the working assumptions shaping demand projections. Primary fieldwork combined with secondary validation from IEC certification databases, OSHA enforcement records, SAMR GB standard filings, and trade customs data for electromechanical component flows. Bottom-up unit economics triangulated against top-down industrial automation capex surveys to anchor volume estimates.
Demand-supply balance dynamics across the projection horizon modeled product type segmentation by electromechanical, electronic, pneumatic, and hydraulic architectures alongside technology tiers spanning contact, non-contact, smart, and magnetic implementations. End-user segmentation captured manufacturing, oil and gas, automotive, and aerospace application patterns with installation format differentiation across panel, surface, flush, and recessed mounting. CAGRs derived from replacement cycle compression rates in EV platform conversions and enforcement intensity trajectories at OSHA and KBA. Raw material cost indices for copper-silver alloys and rare-earth magnets fed price elasticity assumptions.
Sensitivities concentrate around CE marking timeline extensions at notified bodies, rare-earth export quota fluctuations from Chinese processing facilities, and functional safety engineer scarcity elongating SIL certification procurement. Forecasts reflect documented assumptions on regulatory enforcement trajectories and industrial automation capex cycles. Macroeconomic contraction, Machinery Directive reinterpretation, or wireless diagnostic protocol standardization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
ASEAN Switchgear Market
Switches
South America Low Voltage Switchgear Market
Switches
China Reed Sensors Switches Market
Switches
Rotary Limit Switches Market
Switches
Optical Switches Market
Switches
Australia Switchgear Market
Switches
Smart Home Switches Market
Switches
Mexico Rocker Switch Market
Switches
Global Safety Switches Market
Switches
Electronic Shift-By-Wire Selector Modules Market
Switches
United States X by Wire Systems Market
Switches
Matrix Switches Market
Switches
Saudi Arabia Switchgear Market
Switches
Brazil Switchgear Market
Switches
Optical Cross Connect (OXC) Switches Market
Switches
Transfer Switch Market