
 Disconnect Switch Market | 2026-2036
Disconnect Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Disconnect Switch Market Intelligence
Utility-scale buyer consolidation is decoupling from traditional distributor channels as direct procurement by renewable energy developers reshapes volume allocation. ABB leverages its IEC-certified manufacturing footprint to anchor European utility contracts. Schneider Electric sustains competitive intensity through R&D investment in smart disconnect architectures. Eaton Corporation dominates North American industrial specifications with its NEMA-rated product portfolio.
A disconnect switch is an electromechanical safety device engineered to isolate electrical circuits under load conditions, typically rated between 16A and 6300A with visible blade contacts and positive break indication. The device serves critical protection functions in power distribution networks, manufacturing plants, and renewable energy installations by enabling maintenance personnel to verify zero-energy states before equipment servicing. Load break switches command the largest revenue pool within product type segmentation due to their dual capability for routine switching and fault isolation. Electromechanical technology leads absolute unit shipments while magnetic actuation variants capture premium positioning in arc-flash mitigation applications. Outdoor installation configurations are expanding fastest, driven by solar farm and substation buildouts requiring IP65-rated enclosures.
IEC 60947-3 governs international switch-disconnector performance benchmarks while UL 98 governs North American enclosed and dead-front switch constructions, with both frameworks mandating visible contact separation as a core safety requirement. The EPA's evolving stance on SF6 gas insulation in electrical equipment is pressuring manufacturers toward vacuum-interruption alternatives. India's BIS certification requirements for low-voltage switchgear create non-tariff barriers that favor domestic producers like Havells India. Stakeholders must weigh regional certification divergence against platform standardization economics when configuring global product lineups.
Market Dynamics
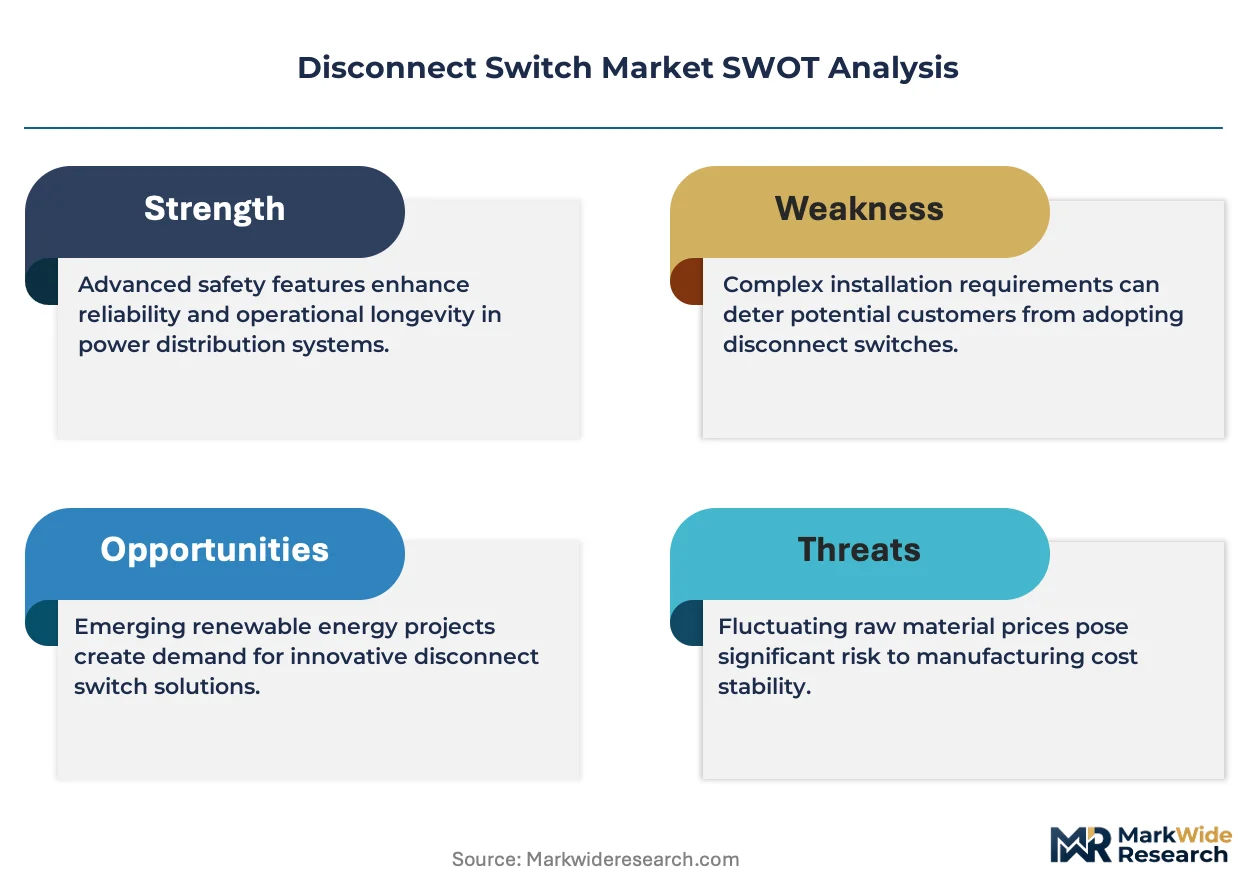
Data center power distribution infrastructure is accelerating procurement of high-amperage disconnect solutions, redirecting manufacturer capacity toward 1600A–6300A rated products with arc-flash containment features.
Growth Catalysts
- IEC 60947-3 Certification:European Union mandates for visible contact separation in switch-disconnectors are driving replacement cycles across German and French utility fleets.
- Solar Farm Deployment:India's National Solar Mission targets are pulling outdoor-rated load-break switches into Rajasthan and Gujarat project pipelines.
- SF6 Phase-Down:EPA scrutiny of gas-insulated switchgear is compressing timelines for vacuum-interruption technology adoption in US substation upgrades.
Market Restraints
- Copper Price Volatility:Raw material cost swings for conductive alloys are compressing margin buffers for mid-tier manufacturers serving price-sensitive industrial buyers.
- Domestic Content Requirements:India's BIS certification for low-voltage switchgear creates non-tariff barriers that disadvantage import-dependent distributors.
- Technical Substitution:Solid-state circuit breakers with integrated isolation functions threaten traditional electromechanical disconnect switch volumes in premium data center segments.
Strategic Opportunities
- Smart Grid Integration:IEC 61850 protocol compatibility opens retrofit potential in aging European substation infrastructure.
- Microgrid Buildouts:Remote industrial sites in Australia and Canada are creating demand for self-contained disconnect switchgear with integrated monitoring.
- Channel Disintermediation:Direct procurement by renewable energy developers is opening manufacturer-direct relationships previously locked behind electrical distributors.
Industry Challenges
- Arc-Flash Engineering Talent:Shortage of certified protection engineers is delaying custom specification approvals for high-amperage installations.
- Multi-Standard Certification Burden:Simultaneous UL 98, IEC 60947-3, and CSA compliance requirements are extending product launch timelines by 8–14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disconnect Switch Market |
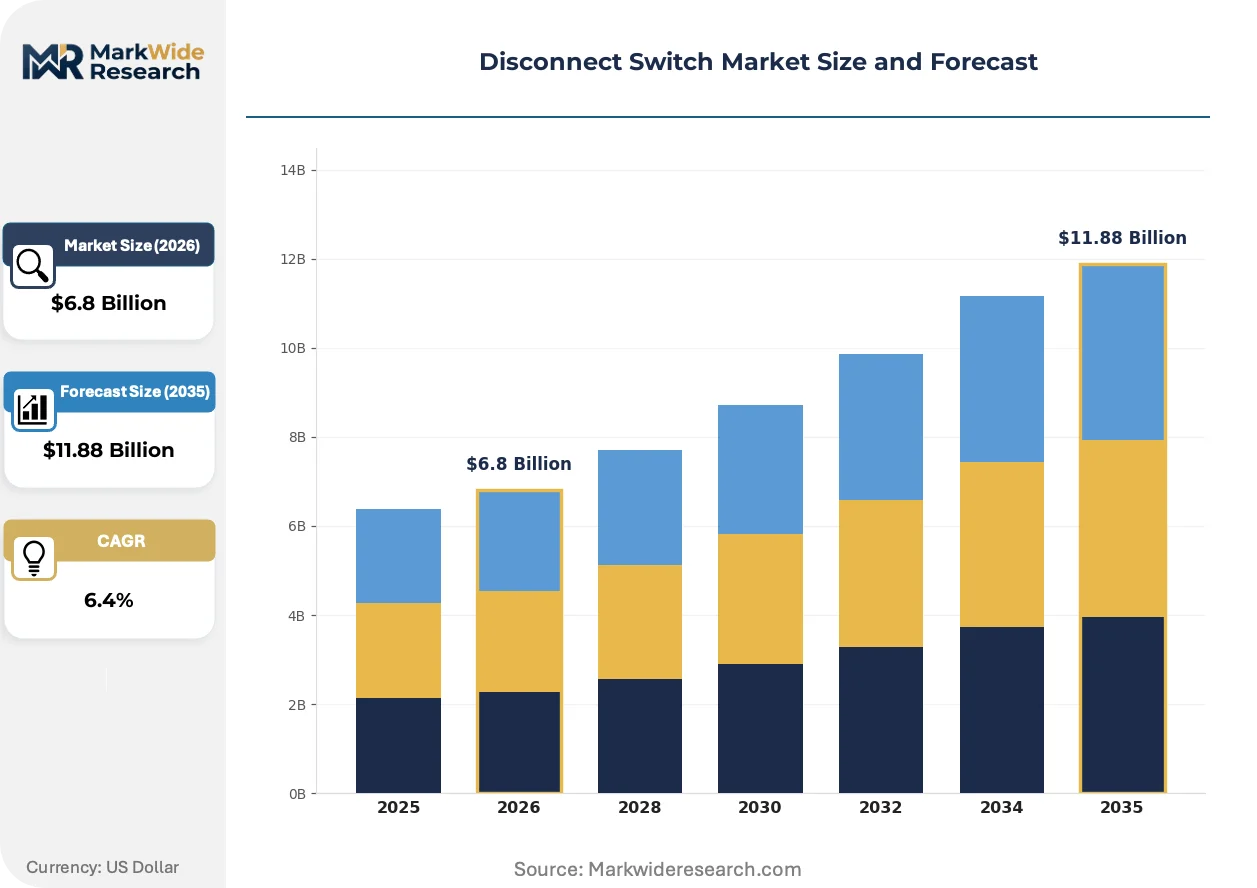
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Disconnects, Automatic Disconnects, Load Break Switches, Switch Disconnector Fuses Technology: Electromechanical, Magnetic, Pneumatic, Hydraulic Application: Residential, Commercial, Industrial, Utility Installation: Indoor, Outdoor, Rack-mounted, Portable |
| Companies Covered | ABB, Schneider Electric, Eaton Corporation, Siemens, General Electric, Havells India, Littelfuse, Rockwell Automation, Socomec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disconnect Switch Market Strategic Shifts & Innovations
Electromechanical safety devices are undergoing functional expansion as arc-flash mitigation, remote monitoring, and modular architecture requirements reshape baseline specifications across power distribution applications.
Vacuum-interruption technology is expanding into medium-voltage disconnect applications previously dominated by air-break designs. US utility engineers are specifying vacuum bottles for 15kV–38kV substation upgrades to preempt EPA restrictions on SF6-insulated equipment. This shift is compressing the addressable market for traditional blade-style disconnects above 1000V while creating premium positioning for sealed-contact architectures.
The EPA's evolving stance on SF6 gas insulation is forcing manufacturers to requalify product lines under accelerated timelines. Equipment suppliers serving North American utilities are redirecting R&D budgets toward vacuum and dry-air alternatives ahead of anticipated rulemakings. Load-break switch categories face the steepest compliance burden, as these products historically relied on gas-insulated arc quenching for ratings above 3000A.
Consolidated procurement by hyperscale data center operators is compressing vendor qualification cycles and unbundling traditional distributor service packages. Amazon Web Services and Microsoft Azure infrastructure teams are issuing direct RFQs for 4000A-rated disconnect assemblies with factory-integrated current transformers. This pattern is most visible in Northern Virginia and Frankfurt, where cluster density permits single-source contracting at volumes that bypass electrical wholesale channels.
Disconnect Switch Market Segmentation
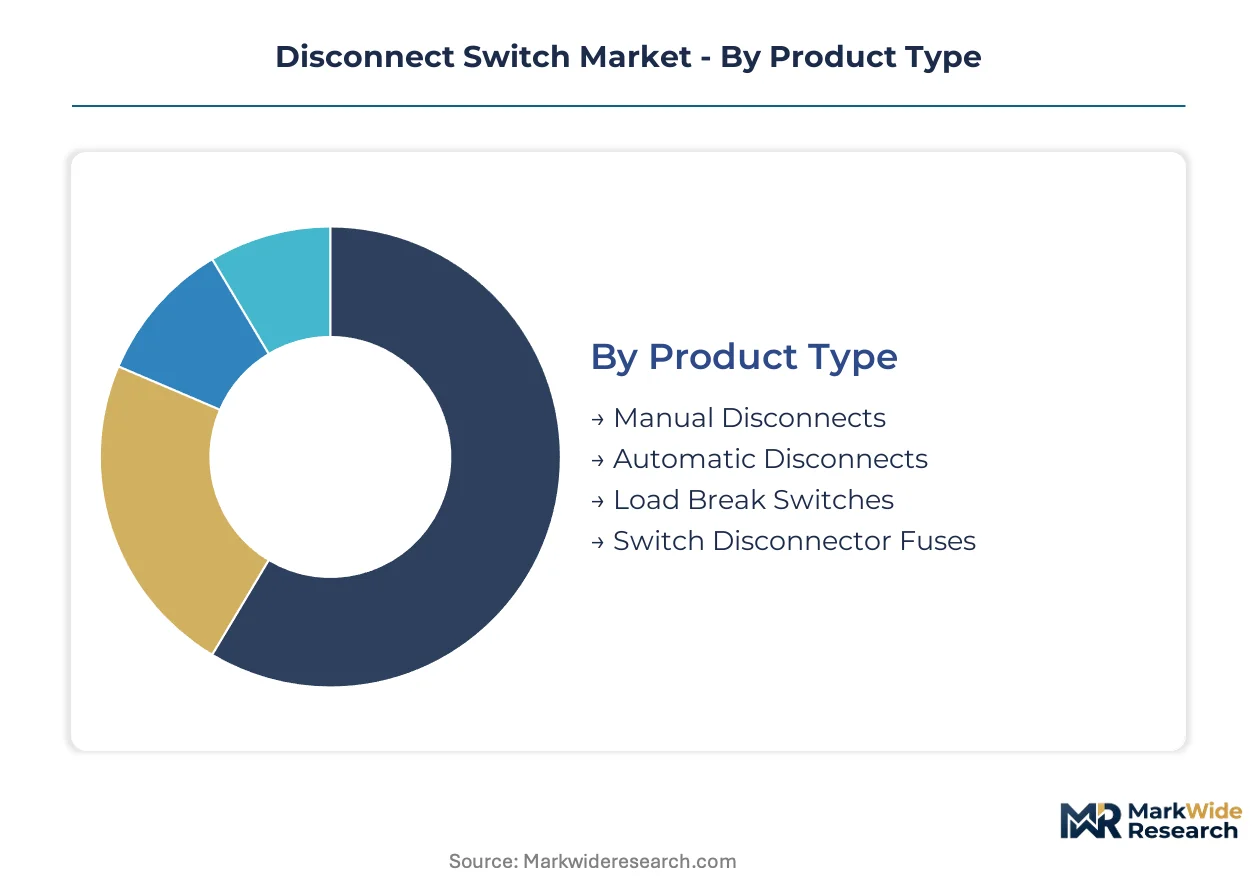
Disconnect switch procurement patterns diverge sharply across installation environments and duty cycles, with capital deployment strategies varying by whether the application demands routine switching or emergency isolation capabilities. Manufacturers configure production lines around these segment boundaries, as electromechanical and solid-state architectures require entirely different supply chains and certification pathways.
Product Type:
Capital intensity peaks with load break switches, where arc-quenching engineering and multi-kiloampere ratings demand dedicated testing infrastructure and metallurgical precision.
- Load Break Switches:Dual-function devices combine routine circuit switching with fault isolation through visible blade contacts and positive break indication. Data center operators in Northern Virginia and Frankfurt are specifying 4000A-rated assemblies with factory-integrated current transformers, bypassing traditional distributor channels for direct manufacturer procurement.
- Manual Disconnects:Hand-operated mechanisms with visible contact separation serve maintenance safety protocols in manufacturing plants and renewable installations. German and French utility fleets are driving replacement cycles as IEC 60947-3 mandates for visible contact separation take effect across European distribution networks.
- Automatic Disconnects:Motorized or solenoid-actuated units respond to remote control signals in smart grid architectures.
- Switch Disconnector Fuses:Integrated overcurrent protection reduces component count in compact substation designs.
Most installed capacity flows through load break switches. Expansion is steepest in manual disconnects as European replacement cycles accelerate.
Technology:
Margin profiles stratify by actuation mechanism, with magnetic and pneumatic systems commanding premium positioning in arc-flash mitigation applications where personnel safety justifies higher unit economics.
- Electromechanical:Spring-loaded or direct-acting mechanisms dominate absolute unit shipments across power distribution networks. EPA scrutiny of SF6 gas insulation is compressing timelines for vacuum-interruption alternatives in US substation upgrades, redirecting R&D budgets toward dry-air and vacuum bottle architectures.
- Magnetic:Electromagnetic actuation delivers millisecond response times for arc-flash containment in high-amperage industrial installations. Premium positioning in data center segments faces technical substitution pressure from solid-state circuit breakers with integrated isolation functions.
- Pneumatic:Compressed-air systems serve heavy-duty mining and marine applications requiring explosion-proof ratings.
- Hydraulic:Fluid-power actuation manages extreme fault currents in utility-scale switchgear.
Electromechanical systems anchor volume production. Magnetic variants are gaining share fastest in premium safety-critical installations.
Application:
Customer procurement scale determines specification complexity, with utility and industrial buyers issuing consolidated RFQs that reshape manufacturer capacity allocation.
- Utility:Grid-scale switch-disconnectors rated 1000A–6300A serve substation busbar isolation and feeder protection. India's National Solar Mission targets are pulling outdoor-rated load-break switches into Rajasthan and Gujarat project pipelines, creating demand for IP65-rated enclosures in desert environments.
- Industrial:Manufacturing plants specify NEMA-rated enclosures for motor control centers and production line distribution. Copper price volatility for conductive alloys is compressing margin buffers for mid-tier manufacturers serving price-sensitive industrial buyers.
- Commercial:Building infrastructure deploys lower-amperage units for tenant electrical room isolation.
- Residential:Single-family and multi-family construction uses compact fused disconnects for HVAC and solar inverter isolation.
Utility procurement commands the largest project values. Industrial retrofit activity is expanding most quickly as aging manufacturing infrastructure requires safety upgrades.
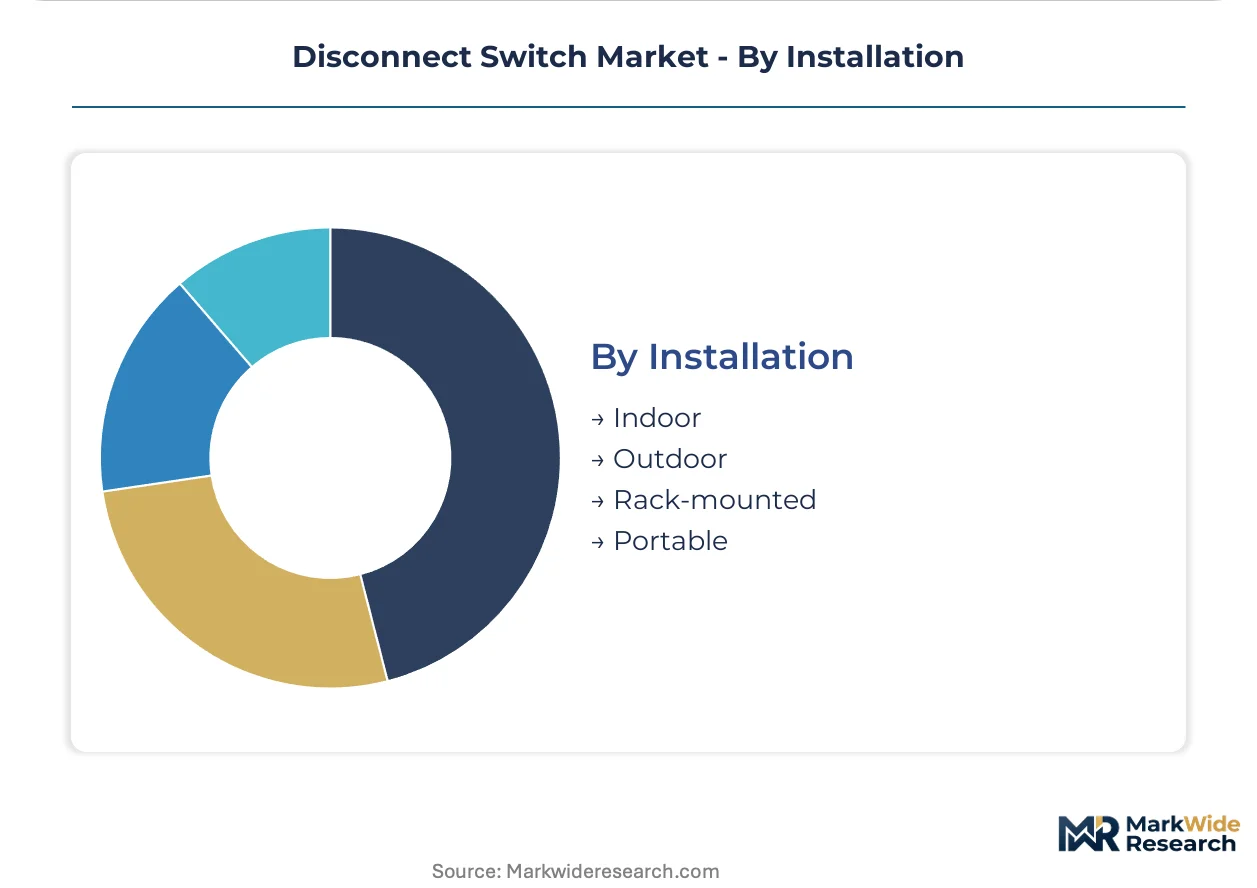
Installation:
Environmental protection ratings drive enclosure cost structures, with outdoor and rack-mounted configurations requiring specialized sealing and thermal management engineering.
- Outdoor:IP65-rated housings with corrosion-resistant finishes serve solar farms, substations, and remote industrial sites. Rajasthan and Gujarat solar deployment is accelerating procurement of weatherproof disconnect assemblies with UV-stabilized polymers and gasketing systems rated for sand infiltration.
- Rack-mounted:Compact form factors integrate into data center power distribution units and server rack busways. AWS and Azure infrastructure teams are unbundling traditional distributor service packages through direct RFQs for high-density configurations.
- Indoor:Standard NEMA 1 or IEC IP30 enclosures serve controlled electrical room environments.
- Portable:Temporary power applications use wheeled or skid-mounted units for construction and event infrastructure.
Indoor installations retain the largest installed base. Outdoor configurations are climbing the fastest as renewable energy buildouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified protection engineers cluster in German industrial zones and Northern Virginia data center corridors, anchoring specification authority for high-amperage installations. Their concentration shapes procurement patterns and compliance interpretation across three continents.
United States
Hyperscale data center operators in Northern Virginia issue direct RFQs for 4000A-rated disconnect assemblies, bypassing electrical wholesale channels. EPA scrutiny of SF6 gas insulation compresses timelines for vacuum-interruption adoption in substation upgrades. Dallas-Fort Worth industrial corridors drive NEMA-rated specification demand for manufacturing plant retrofits.
Germany
Utility fleets across Bavaria and North Rhine-Westphalia accelerate replacement cycles as IEC 60947-3 mandates for visible contact separation take effect. REACH compliance requirements shape material selection for conductive alloys in switchgear manufacturing. Stuttgart industrial clusters anchor specification engineering for arc-flash containment systems.
India
Rajasthan and Gujarat solar deployment pulls outdoor-rated load-break switches into desert project pipelines requiring IP65-rated enclosures. BIS certification for low-voltage switchgear creates non-tariff barriers favoring domestic producers. Maharashtra manufacturing zones concentrate assembly capacity for export-qualified switchgear.
China
Dual carbon goals redirect state grid procurement toward vacuum-interruption alternatives in 15kV–38kV substation upgrades. GB standards alignment with IEC frameworks streamlines export qualification for domestic manufacturers. Yangtze River Delta industrial zones concentrate electromechanical component supply chains.
Japan
METI efficiency standards accelerate smart grid architecture adoption in aging substation infrastructure. JIS certification requirements maintain technical barriers for imported switchgear in utility applications. Kansai manufacturing corridors specialize in precision-actuated disconnect mechanisms for premium industrial segments.
Disconnect Switch Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across certification-tiered market segments. The vendor base stratifies into three tiers: integrated electrical majors with multi-standard manufacturing footprints, regional champions dominating domestic certification regimes, and component specialists supplying contact assemblies and actuation systems to tier-one assemblers. Dominant competitive moves include backward integration into contact metallurgy and strategic partnerships with hyperscale data center developers for direct procurement relationships.
Within the integrated electrical major tier, ABB and Schneider Electric exemplify archetypes of multi-standard global suppliers. ABB anchors European utility contracts through IEC-certified manufacturing footprints. Schneider Electric occupies a position defined by R&D investment in smart disconnect architectures. Havells India represents the regional champion archetype, leveraging BIS certification advantages in domestic procurement cycles.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Eaton Corporation |
| Siemens |
| General Electric |
| Havells India |
| Littelfuse |
| Rockwell Automation |
| Socomec |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between IEC 60947-3 and UL 98 compliance tiers drives parallel pricing ladders and geographically segregated supply configurations. Premium-tier manufacturers anchor production in Germany and Switzerland for European utility contracts, while commodity-grade assemblers concentrate in India and China to serve price-sensitive industrial procurement.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for standard-grade electromechanical disconnects. Three-tier pricing structure across premium, standard, and economy levels separates arc-flash-rated magnetic actuation systems from basic manual disconnects. Price differentiation hinges on certification tier and volume scale, with hyperscale data center buyers negotiating direct manufacturer contracts that bypass distributor markups. Cost compression in the mid-tier is intensifying because copper alloy volatility erodes margin buffers for import-dependent distributors serving Indian industrial markets.
Supply Chain Analysis
Refurbishment flows for high-amperage switchgear create secondary supply channels in North American utility markets. Manufacturing concentration centers on China, India, and Germany, with the Yangtze River Delta anchoring electromechanical component supply chains and Maharashtra housing export-qualified assembly capacity. Raw material dependencies draw from copper conductive alloys, silver-contact metallurgy, and UV-stabilized polymer enclosures. Single-source vulnerability in vacuum-bottle interruption technology creates procurement risk for US substation upgrades. Distribution runs through electrical wholesale channels, though renewable energy developers increasingly pursue direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by hyperscale data center procurement shifting toward 4000A-rated assemblies with integrated monitoring and arc-flash containment specifications.
For Market Incumbents: Cement multi-standard certification dominance by accelerating IEC 61850 protocol integration ahead of European smart grid retrofits. Deepen backward integration into silver-contact metallurgy to offset raw material volatility. Prioritize direct procurement relationships with AWS and Azure infrastructure teams in Northern Virginia and Frankfurt to defend against distributor disintermediation. For New Entrants and Emerging Players: Digital-channel routes through manufacturer-direct portals offer the lowest-friction entry path for Rajasthan and Gujarat solar farm projects requiring IP65-rated outdoor assemblies. Target India's National Solar Mission pipeline where BIS certification barriers disadvantage import-dependent incumbents. Pursue white-label partnerships with domestic Indian assemblers to circumvent non-tariff barriers while building brand recognition. For Investors and Strategic Acquirers: Asymmetric upside sits with vacuum-interruption technology specialists positioned ahead of EPA SF6 phase-down enforcement. Five-to-ten year viability favors manufacturers with dual IEC-UL manufacturing footprints capable of serving both European utility replacement cycles and North American data center buildouts. Monitor FERC filings and EPA rulemaking dockets as the critical inflection signal for vacuum-technology adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61850 Protocol Integration | Enables retrofit positioning in aging German and French substation infrastructure. |
| Vacuum-Interruption Technology Transition | Preempts EPA restrictions on SF6-insulated equipment in US utility upgrades. |
| Direct Procurement Channel Development | Bypasses electrical distributors for hyperscale data center contracts in Northern Virginia. |
| Backward Integration into Contact Metallurgy | Captures margin from silver-alloy and copper conductive component supply. |
| BIS Certification Investment | Unlocks domestic procurement preference in India's National Solar Mission pipeline. |
Research Approach
Direct dialogue with utility planning officers, data center infrastructure directors, OEM procurement teams, and aftermarket service heads grounded the qualitative foundation. Secondary validation drew from FERC interconnection filings, EIA power distribution data, IEC certification registries, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-checked segment-level unit economics against aggregate market sizing.
Bottom-up modeling aggregated product-type, technology, application, and installation configuration dimensions across the projection horizon. Top-down validation stress-tested CAGRs against utility capital expenditure patterns and renewable energy deployment trajectories. Forecast inputs incorporated arc-flash engineering talent availability and multi-standard certification timeline assumptions.
Copper price volatility, EPA regulatory acceleration, and solid-state circuit breaker substitution are the dominant revision risks to baseline projections. Forecasts reflect documented assumptions regarding certification harmonization timelines and data center buildout density. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Asia Pacific Safety Switches Market
Switches
North America Medium Voltage Switchgear Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Dual Power Transfer Switches Market
Switches
Smart Pole-Mounted Switch Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
China Switchgear Market
Switches
Differential Pressure Switches Market
Switches
Off-Road Machine Ruggedized Switch and Indicator Systems Market
Switches
Ethernet Switch Market
Switches
Europe Switchgear Market
Switches
In-Wall Smart Switch Market
Switches
Campus Switches Market
Switches
Power Load Switches Market
Switches
Vibration Level Switch Market