
 Gigabit Ethernet Test Equipment Market | 2026-2036
Gigabit Ethernet Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Gigabit Ethernet Test Equipment Market Foresight
The gap between laboratory-grade precision and field-portable economy tiers is repositioning vendor strategy across the Gigabit Ethernet Test Equipment landscape. Keysight Technologies leverages deep calibration ecosystems to dominate high-speed signal integrity benches. Viavi Solutions Inc. competes through modular platforms that bridge lab-to-field workflows. Spirent Communications anchors its position in protocol conformance suites for hyperscale data center qualification.
Gigabit Ethernet Test Equipment encompasses instruments that verify electrical, optical, and protocol-layer performance across copper and fiber physical media at speeds from 1 Gbps through 400 Gbps and beyond, employing bit error rate detection, time-domain reflectometry, and packet-capture analytics to certify network element compliance. Protocol analyzers and bit error rate testers command premium margin pools as 112 Gbps PAM4 signaling complexity intensifies validation requirements; fiber optic testing outpaces copper testing in absolute growth as single-mode deployments scale in backbone and intra-data center links. Network performance validation applications absorb disproportionate capital allocation from telecommunication providers certifying 5G transport backhaul.
FCC equipment authorization rules and IEEE 802.3 standards frameworks govern US market access and interoperability benchmarks, while CE marking under EU radio equipment directives shapes European product compliance pathways. NIST-traceable calibration requirements and ISO 17025 laboratory accreditation constrain supplier qualification for government and defense procurement channels. Stakeholders must monitor IEEE 802.3df and 802.3dj task force timelines to align R&D roadmaps with next-generation 800G/1.6T test specifications before standard ratification locks in instrument architecture decisions.
Market Dynamics
The transition from NRZ to PAM4 modulation at 112 Gbps lane rates is compressing test equipment refresh cycles and forcing capital reallocation toward signal integrity instrumentation capable of validating eye diagrams under severe noise conditions.
Growth Catalysts
- IEEE 802.3ck standardization:The ratification of 800G Ethernet specifications creates mandatory upgrade paths for data center qualification labs and carrier network acceptance testing.
- Hyperscale facility buildouts:Cloud infrastructure operators in the United States, China, and Germany are expanding validation budgets to certify 400G/800G port densities.
- 5G transport backhaul certification:Telecommunication providers require bit error rate testing and protocol analysis to verify timing synchronization and latency budgets.
Market Restraints
- Precision instrumentation cost structure:High-speed oscilloscopes and arbitrary waveform generators with bandwidth exceeding 70 GHz command six-figure price points that limit fleet expansion.
- Calibration ecosystem concentration:NIST-traceable calibration services cluster in North America and Western Europe, extending downtime for Asia-Pacific operators.
- ASIC development timelines:Custom silicon for 224 Gbps PAM4 SerDes validation requires three-to-four-year design cycles that lag standard ratification schedules.
Strategic Opportunities
- India data center market penetration:The country's PLI scheme for electronics manufacturing is attracting hyperscale investments that require local test equipment partnerships.
- Multi-physics simulation convergence:Integration of electromagnetic, thermal, and channel simulation tools creates bundled validation workflows for signal integrity engineers.
- Subscription-based calibration services:Equipment vendors are introducing annual service contracts that reduce capital burden and lock in recurring revenue streams.
Industry Challenges
- PAM4 signal analysis expertise scarcity:The shift from NRZ to four-level signaling demands specialized training in non-linear equalization and noise injection methods that outpaces university curricula.
- Legacy 10G/25G test asset stranding:Carriers face write-down pressure on depreciated copper and fiber field testers that lack firmware upgrade paths to 100G+ protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gigabit Ethernet Test Equipment Market |
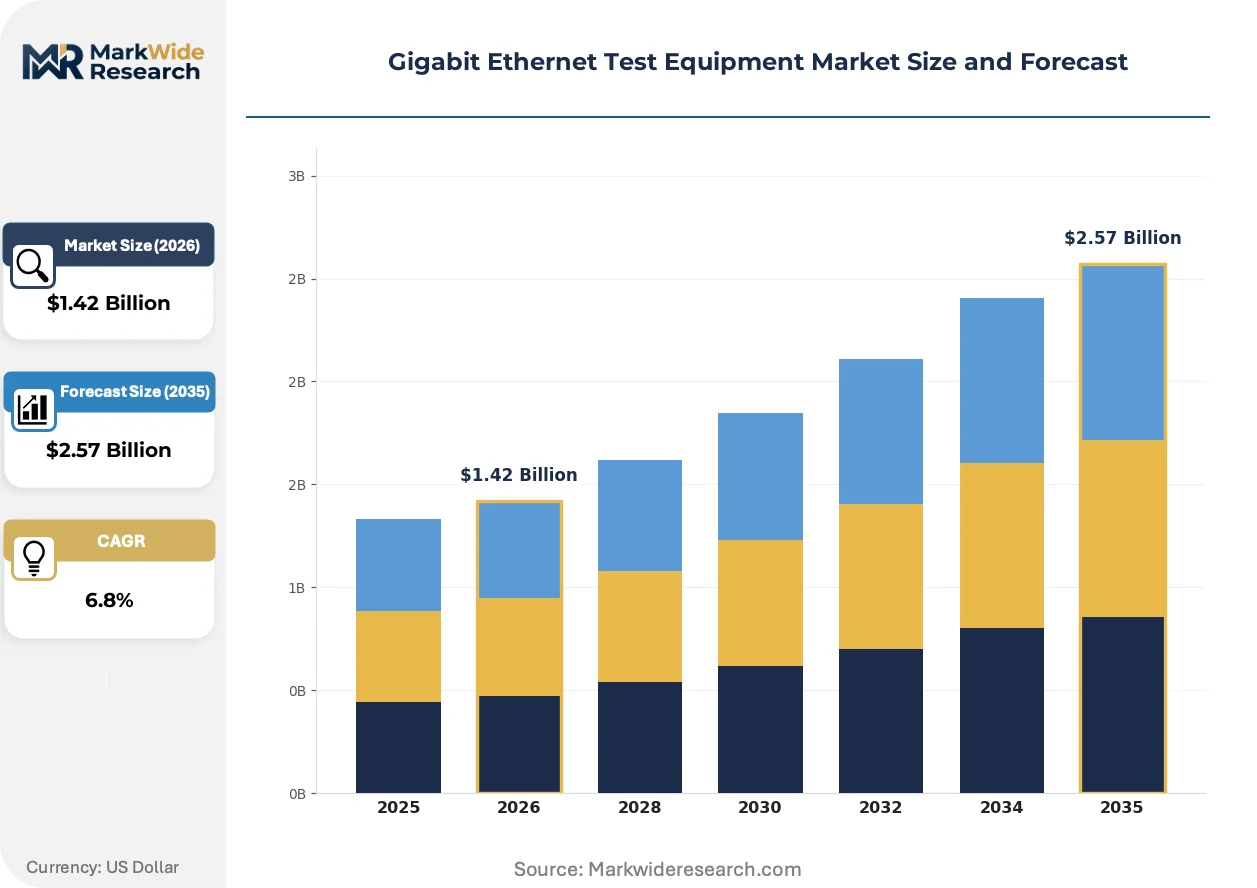
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protocol Analyzers, Bit Error Rate Testers, Time Domain Reflectometers, Cable Analyzers, Network Emulators Technology: Copper Testing, Fiber Optic Testing, Wireless Link Testing, Electrical Signal Testing, Optical Signal Testing Application: Network Performance Validation, Equipment Manufacturing, Field Deployment, Quality Assurance, Research & Development End User: Telecommunication Providers, Data Center Operators, System Integrators, Network Consultants, Government Agencies |
| Companies Covered | Keysight Technologies, Viavi Solutions Inc., Spirent Communications, EXFO Inc., Anritsu Corporation, Rohde & Schwarz, NetScout Systems, Yokogawa Electric Corporation, Teledyne LeCroy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gigabit Ethernet Test Equipment Market Shifts & Advancements
Instrumentation architecture is pivoting from discrete box instruments toward software-defined platforms that decouple measurement hardware from analysis algorithms, enabling faster adaptation to evolving IEEE 802.3 physical layer specifications.
Co-packaged optics test methodologies are rewriting how signal integrity engineers validate electrical-optical interfaces. Data center operators deploying 51.2 Tbps switch chips with integrated silicon photonics now require combined electrical and optical probing systems. This convergence is compressing the traditional separation between electrical characterization labs and fiber optic certification teams.
FCC equipment authorization rules under Part 15 and Part 18 are tightening electromagnetic compatibility verification requirements for test equipment itself. Manufacturers must now self-certify that their instruments do not interfere with adjacent spectrum users. This regulatory friction disproportionately affects portable field testers operating in unlicensed 6 GHz bands.
Cloud-native test orchestration platforms are displacing on-premises measurement software in hyperscale qualification environments. Buyers now expect browser-based instrument control and centralized data lakes for regression analysis. This behavioral shift is most visible among United States-based cloud operators managing distributed validation labs across multiple time zones.
Gigabit Ethernet Test Equipment Market Segmentation
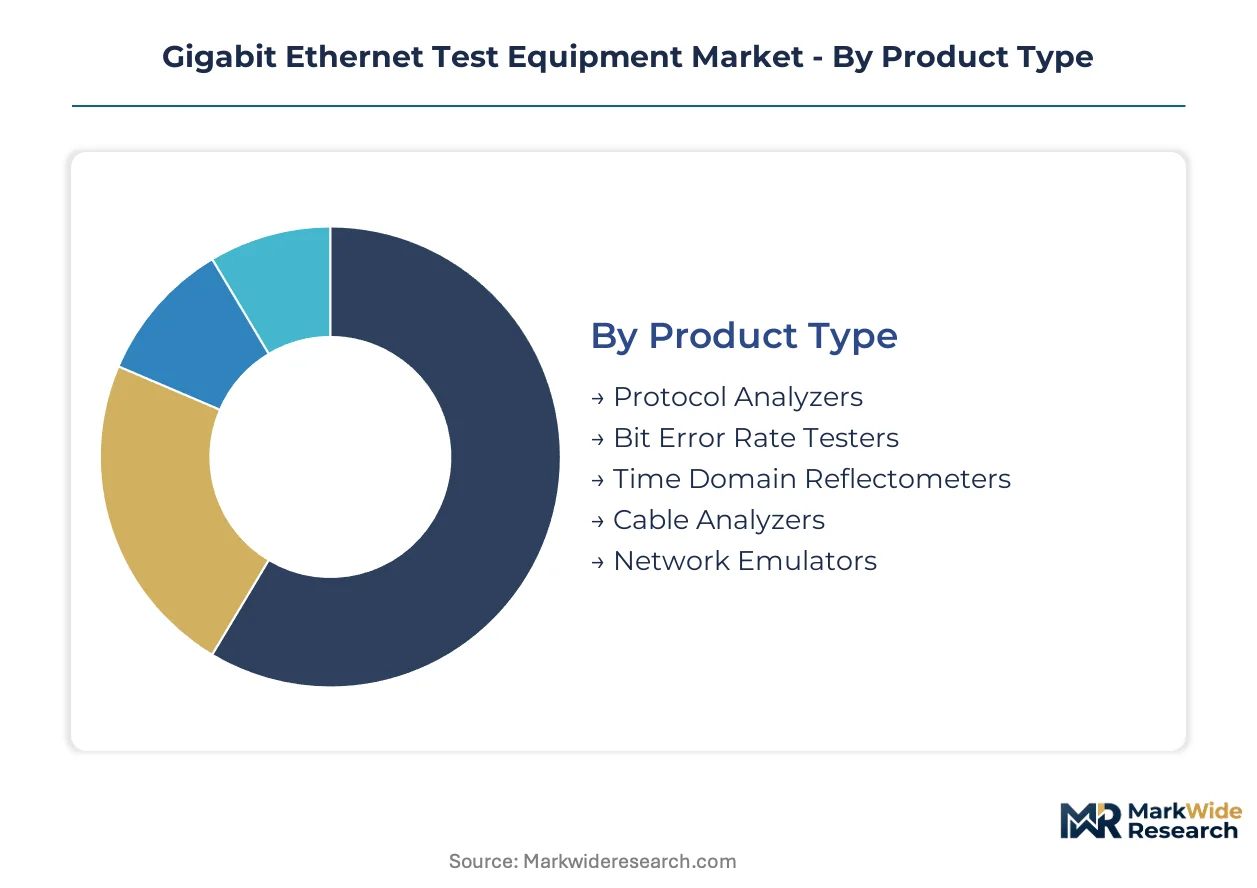
Segmentation in the Gigabit Ethernet Test Equipment Market reveals divergent capital deployment patterns across validation workflows. Equipment specifications, physical media requirements, and end-user procurement authority collectively determine margin capture and vendor positioning strategies.
Product Type:
Capital intensity escalates sharply with signal bandwidth requirements, separating laboratory-grade precision instruments from field-deployable economy tiers.
- Protocol Analyzers:Deep packet inspection engines decode 400G/800G Ethernet frames with nanosecond timestamp resolution. Hyperscale data center operators in the United States deploy these for switch qualification. IEEE 802.3ck compliance verification drives replacement cycles.
- Bit Error Rate Testers:Pattern generators and error detectors validate PAM4 signaling integrity at 112 Gbps lane rates. Carrier labs in Germany utilize these for 5G transport backhaul certification. NIST-traceable calibration requirements constrain supplier qualification.
- Time Domain Reflectometers:Impulse response analysis locates impedance discontinuities in copper cabling plant. Field technicians employ portable units for enterprise network troubleshooting.
- Cable Analyzers:Certification instruments verify Category 8 and fiber channel insertion loss budgets. Structured cabling contractors purchase these for installation sign-off.
- Network Emulators:Latency and jitter injection tools replicate WAN conditions in lab environments. Software-defined platforms enable scenario scripting for application stress testing.
Bit Error Rate Testers absorb the bulk of installed capacity; Protocol Analyzers are expanding most quickly.
Technology:
Physical layer validation requirements split procurement between electrical characterization and optical certification domains, with fiber deployments commanding premium instrumentation.
- Copper Testing:Time-domain and frequency-domain measurements certify twisted-pair and twinaxial assemblies. Enterprise LAN refresh cycles sustain demand for 10G/25G field testers.
- Fiber Optic Testing:Optical time-domain reflectometry and spectral analysis validate single-mode backbone links. Intra-data center fiber scaling in China absorbs high-end modular platforms.
- Wireless Link Testing:Millimeter-wave and Wi-Fi 6E verification instruments address unlicensed spectrum deployments. FCC Part 15 compliance requirements shape instrument feature sets.
- Electrical Signal Testing:High-bandwidth oscilloscopes and arbitrary waveform generators characterize SerDes performance. ASIC development timelines lag standard ratification schedules.
- Optical Signal Testing:Co-packaged optics qualification demands combined electrical-optical probing. Data center operators deploying 51.2 Tbps switch chips drive methodology convergence.
Fiber Optic Testing commands the largest share of qualification budgets; Optical Signal Testing is gaining share fastest.
Application:
Procurement authority concentrates with network operators certifying production infrastructure versus manufacturing lines performing design validation.
- Network Performance Validation:End-to-end latency, throughput, and jitter measurement under loaded conditions. Telecommunication providers allocate disproportionate capital to 5G transport verification.
- Equipment Manufacturing:Production line testing of switches, routers, and NICs at volume scale. Burn-in and functional test stations integrate automated handling systems.
- Field Deployment:Acceptance testing and troubleshooting in live network environments. Portability requirements trade measurement depth for operational convenience.
- Quality Assurance:Regression testing and supplier qualification protocols. Firmware upgrade paths determine asset depreciation schedules.
- Research & Development:Pre-standard silicon characterization and architecture exploration. University and corporate labs acquire bleeding-edge bandwidth ahead of commercial deployment.
Network Performance Validation absorbs the bulk of installed capacity; Research & Development is climbing the fastest.
End User:
Budget authority and technical sophistication determine instrument specification tiers, separating hyperscale self-qualification from outsourced consulting engagements.
- Telecommunication Providers:Carrier network labs and central offices performing equipment acceptance. Timing synchronization and latency budget verification dominate 5G backhaul requirements.
- Data Center Operators:Hyperscale cloud infrastructure owners with internal qualification teams. Custom test harnesses and regression data lakes differentiate operational maturity.
- System Integrators:Third-party deployment and commissioning services for enterprise networks. Rental and lease arrangements reduce capital burden on project-based revenue.
- Network Consultants:Independent advisory and troubleshooting engagements. Portable multi-function instruments support diverse client technology stacks.
- Government Agencies:Defense and research laboratories with NIST-traceable calibration mandates. ISO 17025 accreditation requirements constrain supplier pools.
Telecommunication Providers absorb the bulk of installed capacity; Data Center Operators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley and the broader San Francisco Bay Area concentrate the densest cluster of hyperscale data center qualification labs and test equipment R&D facilities in the world.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth are expanding 400G/800G validation budgets as AI training clusters scale. FCC equipment authorization rules under Part 15 govern electromagnetic compatibility verification for test instruments. Chicago and Phoenix data center corridors absorb modular protocol analyzers for switch qualification workflows.
China
Intra-data center fiber deployments in Beijing and Shanghai are driving demand for combined electrical-optical probing systems. MIIT standards frameworks and GB certification requirements shape product compliance pathways for domestic equipment vendors. The Yangtze River Delta manufacturing belt anchors production of high-speed oscilloscopes for export markets.
Germany
Carrier network labs in Munich and Frankfurt require bit error rate testing for 5G transport backhaul timing synchronization. CE marking under EU radio equipment directives constrains European market access for non-compliant instruments. The Stuttgart automotive-electronics corridor is adopting Ethernet test equipment for connected vehicle validation.
India
PLI scheme incentives for electronics manufacturing are attracting hyperscale data center investments in Mumbai and Chennai. TRAI spectrum regulations and BIS certification requirements create dual compliance burdens for imported test equipment. The Delhi-NCR corridor is emerging as a hub for third-party network commissioning services.
Japan
Co-packaged optics development in Tokyo and Osaka is rewriting signal integrity validation methodologies for 51.2 Tbps switch chips. METI technology roadmaps and JIS standards frameworks guide R&D investment priorities. The Nagoya precision manufacturing belt supplies calibration-grade components for NIST-traceable instrument ecosystems.
Gigabit Ethernet Test Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Gigabit Ethernet Test Equipment landscape. The vendor base stratifies into three tiers: integrated measurement conglomerates with deep calibration ecosystems, modular platform specialists bridging lab-to-field workflows, and regional component suppliers serving price-sensitive enterprise segments. Dominant competitive moves include strategic partnerships for co-packaged optics test methodologies and portfolio diversification into cloud-native test orchestration platforms.
Within the integrated measurement tier, Keysight Technologies and Rohde & Schwarz exemplify archetypes with calibration-grade precision positioning. Viavi Solutions Inc. represents the modular platform specialist bridging lab-to-field workflows. Among Japan-based instrumentation groups, Anritsu Corporation and Yokogawa Electric Corporation occupy positions emphasizing signal integrity expertise for high-speed SerDes validation.
| Leading Market Players |
|---|
| Keysight Technologies |
| Viavi Solutions Inc. |
| Spirent Communications |
| EXFO Inc. |
| Anritsu Corporation |
| Rohde & Schwarz |
| NetScout Systems |
| Yokogawa Electric Corporation |
| Teledyne LeCroy |
| Others |
Supply & Pricing Matrix
CE marking under EU radio equipment directives gates qualified supply access and premium-tier pricing power, as calibration-grade precision instruments require ISO 17025 laboratory accreditation that only established vendors can sustain. Buyers in Germany and France face extended lead times for NIST-traceable equipment, compressing margins for distributors lacking direct manufacturer relationships.
Pricing Analysis
Yield-based pricing anchors premium tiers, where bit error rate testers command six-figure price points tied to PAM4 signal validation throughput. Three-tier pricing structure across premium, standard, and economy levels separates laboratory-grade precision benches from field-portable units and rental fleet equipment. Cost compression in the economy tier is intensifying because hyperscale operators are consolidating procurement volumes. Data center operators show the least price sensitivity due to AI cluster validation budgets, while structured cabling contractors absorb the most pressure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, bypassing distribution layers for 400G/800G protocol analyzers and bit error rate testers. Manufacturing concentrates in the United States, Germany, and Japan, with the Yangtze River Delta supplying high-speed oscilloscope components. Production draws from indium phosphide semiconductors, precision microwave connectors, and calibration-grade reference standards. Single-source vulnerability in 70 GHz+ bandwidth oscilloscope ASICs creates chokepoints. Distribution runs through authorized calibration service networks that extend equipment lifecycle value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gigabit Ethernet Test Equipment Market functions as a cost-of-compliance story, where FCC Part 15 equipment authorization rules create a barrier-to-entry moat that rewards incumbents with established electromagnetic compatibility verification capabilities.
For Market Incumbents: To counter modular platform specialists bridging lab-to-field workflows, deepen calibration ecosystem control through NIST-traceable service center expansion in Asia-Pacific. Lock in hyperscale data center operators with subscription-based firmware upgrade contracts that strand legacy test assets.
For New Entrants and Emerging Players: PLI scheme incentives in India open a window for local manufacturing partnerships serving Mumbai and Chennai hyperscale buildouts. Target third-party network commissioning services in the Delhi-NCR corridor with portable multi-function instruments. Pursue cloud-native test orchestration platforms as the go-to-market angle to bypass capital-intensive hardware development.
For Investors and Strategic Acquirers: IEEE 802.3dj task force timeline acceleration is the leading indicator that 1.6T test specification demand will concentrate procurement with calibration-grade vendors. Over the projection horizon, acquisition value accrues to modular platform specialists with software-defined architectures. Monitor standard ratification schedules for early signals of instrument refresh cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | NIST-traceable centers in Asia-Pacific reduce downtime for China-based operators. |
| Cloud-Native Test Orchestration Platform | Browser-based instrument control aligns with United States hyperscale buyer expectations. |
| Co-Packaged Optics Test Methodology Partnership | Combined electrical-optical probing addresses 51.2 Tbps switch chip validation. |
| Subscription-Based Firmware Upgrade Program | Recurring revenue streams reduce capital burden for carrier network labs. |
| Regional Manufacturing Footprint Establishment | PLI scheme compliance in India enables local supply to Mumbai data centers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with signal integrity engineers, data center qualification managers, carrier network lab directors, and test equipment procurement officers combined with IEEE standards documentation, FCC equipment authorization databases, SEC 10-K instrument manufacturer disclosures, and hyperscaler capex reports. Bottom-up equipment unit economics and top-down addressable market sizing underwent triangulation validation.
Data-stream reconciliation across product type, technology, application, and end-user segmentation dimensions shaped the analytical framework. CAGRs were derived from installed base replacement cycles and standard ratification timelines. PAM4 lane rate transitions and co-packaged optics deployment curves served as industry-specific forecast inputs throughout the modeling period.
The model assumes a particular technology adoption path; alternative pathways for 224 Gbps PAM4 SerDes validation would alter the outlook. Forecasts reflect assumptions regarding IEEE 802.3 standards ratification schedules and hyperscale facility buildout cadence. Practitioners should monitor FCC Part 15 rule revisions and MIIT standards updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Hipot Tester Market
Test and Measurement
Automated Optical Inspection (AOI) System Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Scuff Tester Market
Test and Measurement
LAN Tester Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
Semiconductor Assembly and Testing Services Market
Test and Measurement
Hour Meter Market