
 High-Voltage Disconnect Switch Market | 2026-2036
High-Voltage Disconnect Switch Market Size, Share, and Industry Trends Forecast 2026-2036
High-Voltage Disconnect Switch Market Insights
The capital-intensity divergence between integrated manufacturers and component assemblers is unwinding competitive stability in the high-voltage disconnect switch landscape. Siemens Energy leverages captive casting and machining operations to sustain margin control across European transmission tenders. Hitachi ABB Power Grids anchors its position through deep vertical integration in disconnector blade forging and contact systems. Shandong Taikai Disconnector dominates domestic procurement channels within China's state-backed grid infrastructure programs.
A high-voltage disconnect switch is an electromechanical device rated for circuits above 1 kV that provides visible isolation of energized conductors, typically employing silver-plated copper contacts and porcelain or composite polymer insulators to withstand switching surges up to 145 kV and beyond. Its primary purpose is to secure maintenance access on transmission lines and substation busbars by creating a verifiable open gap that load-breaking equipment cannot guarantee. Outdoor disconnect switches occupy the largest revenue pool given their exposure to environmental cycling and corresponding replacement cycles across aging substations. Renewable integration applications represent the fastest-expanding demand segment as offshore wind and solar farms require specialized switches for fault isolation and grid synchronization. Pole-mounted installations retain entrenched share in rural distribution networks where terrain constraints prevent pad or ground-mounted alternatives.
IEC 62271-102 governs switching and isolation performance for high-voltage disconnectors across markets adopting international standards, while the EU F-Gas Regulation and REACH restrictions on SF6 insulation are redirecting R&D investment toward vacuum and dry air insulation technologies. The EPA enforces NESHAP standards on electrical equipment manufacturing emissions in the United States, affecting insulator glazing and metal finishing processes for suppliers serving North American utilities. Stakeholders must monitor evolving material compliance deadlines and insulation medium transitions to avoid stranded inventory in procurement pipelines.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale insulation medium transition across European transmission infrastructure, compressing SF6-dependent supply chains while elevating vacuum and dry air alternatives in procurement specifications.
Growth Catalysts
- Renewable Interconnection Mandates:State Grid Corporation's ultra-high-voltage corridor buildouts in China require specialized disconnect switches for solar and wind farm synchronization, pulling demand from conventional thermal generation replacement cycles.
- IEC 62271-102 Certification:International standardization of switching and isolation performance is harmonizing procurement specifications across export markets, reducing compliance fragmentation for manufacturers serving multiple jurisdictions.
- Substation Modernization:Aging outdoor installations across rural distribution networks in India and Brazil are entering replacement windows, creating visible isolation upgrade demand where pole-mounted infrastructure dominates terrain-constrained regions.
Market Restraints
- Silver Price Volatility:Silver-plated copper contact systems face input cost pressure from precious metal commodity swings, compressing margin predictability for component assemblers lacking captive plating operations.
- Ceramic Insulator Supply Concentration:High-purity alumina and porcelain insulator manufacturing clusters in specific Chinese provinces create geographic concentration risk for European and North American switch fabricators.
- SF6 Phase-Out Stranded Assets:Utilities holding inventories of gas-insulated disconnect switches face accelerated depreciation under REACH restrictions and national climate legislation, constraining capital release for replacement procurement.
Strategic Opportunities
- Offshore Wind Farm Isolation:North Sea and Baltic Sea offshore wind clusters require marine-grade disconnect switches with corrosion-resistant composite polymer housings, opening premium product tiers where salt spray specifications exceed terrestrial standards.
- Digital Twin Integration:Convergence of electromechanical switching hardware with IoT condition monitoring enables predictive maintenance service models, shifting revenue from equipment sales to lifecycle performance contracts.
- India Transmission Expansion:Central Electricity Authority directives for national grid strengthening are expanding tender volumes for 145 kV and above ratings, creating entry points for manufacturers with BIS certification pathways.
Industry Challenges
- IEC Type Test Timeline Compression:Certification laboratories face backlog congestion for 62271-102 dielectric and mechanical endurance validation, extending product launch lead times for new insulation medium variants.
- Legacy Substation Integration:Retrofit installations must interface with existing busbar configurations and control systems, requiring custom engineering that erodes standardization economies for smaller project batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Voltage Disconnect Switch Market |
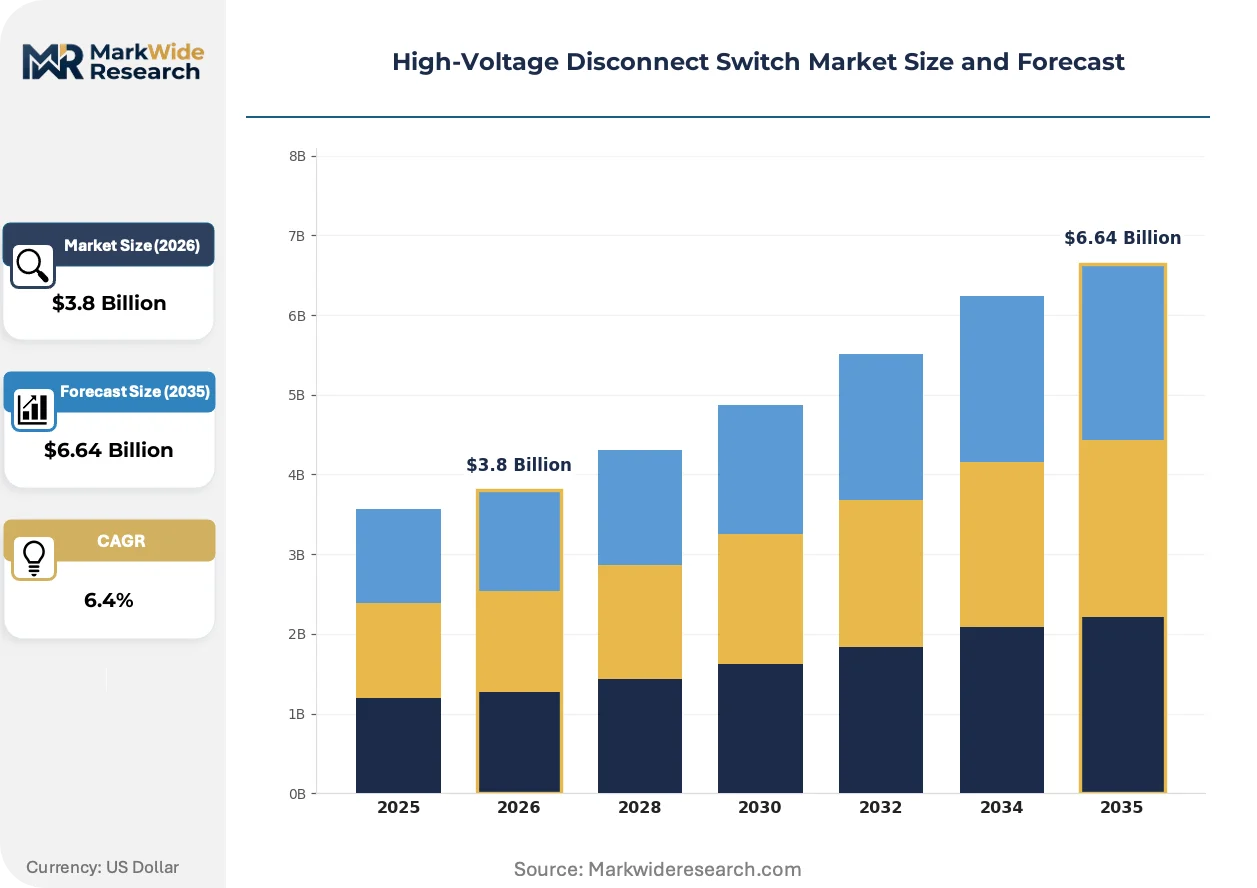
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outdoor Disconnect Switches, Indoor Disconnect Switches, Enclosed Disconnect Switches, Manual Disconnect Switches End User: Utilities, Industrial Plants, Renewable Energy, Commercial Buildings Installation: Wall-Mounted, Pole-Mounted, Pad-Mounted, Ground-Mounted Application: Power Distribution, Grid Interconnection, Renewable Integration, Voltage Regulation |
| Companies Covered | Hitachi ABB Power Grids, Siemens Energy, GE, MESA, SDCEM, EMSPEC, Insulect, Shandong Taikai Disconnector, Pinggao Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Voltage Disconnect Switch Market Trends and Innovations
Vacuum interrupter technology is bifurcating competitive positioning in high-voltage isolation, while regulatory chemistry restrictions and procurement digitization reshape how specifications travel from utility engineering departments to factory floors.
Dry air and vacuum insulation technologies are displacing SF6-dependent designs in disconnect switch applications above 72.5 kV. European transmission utilities are specifying these alternatives in renewable interconnection tenders to preempt F-Gas compliance exposure. The technology is bifurcating supplier capabilities, separating manufacturers with in-house vacuum chamber fabrication from those dependent on external interrupter sourcing.
REACH restrictions on fluorinated greenhouse gases are redirecting European R&D investment toward alternative insulation media. The regulation compresses SF6 inventory values while elevating dry air system engineering priorities in product development pipelines. Disconnect switch specifications in Germany, France, and the Netherlands now routinely exclude gas-insulated options for new substation construction.
Utility engineering departments are consolidating vendor qualification lists around certified sustainable product lines. Long-term framework agreements are displacing project-by-project tendering for transmission-grade disconnect switches, concentrating procurement volume with pre-approved manufacturers. This concentration is most visible in Nordic markets where state-owned grid operators have published explicit SF6-free procurement roadmaps.
High-Voltage Disconnect Switch Market Segmentation
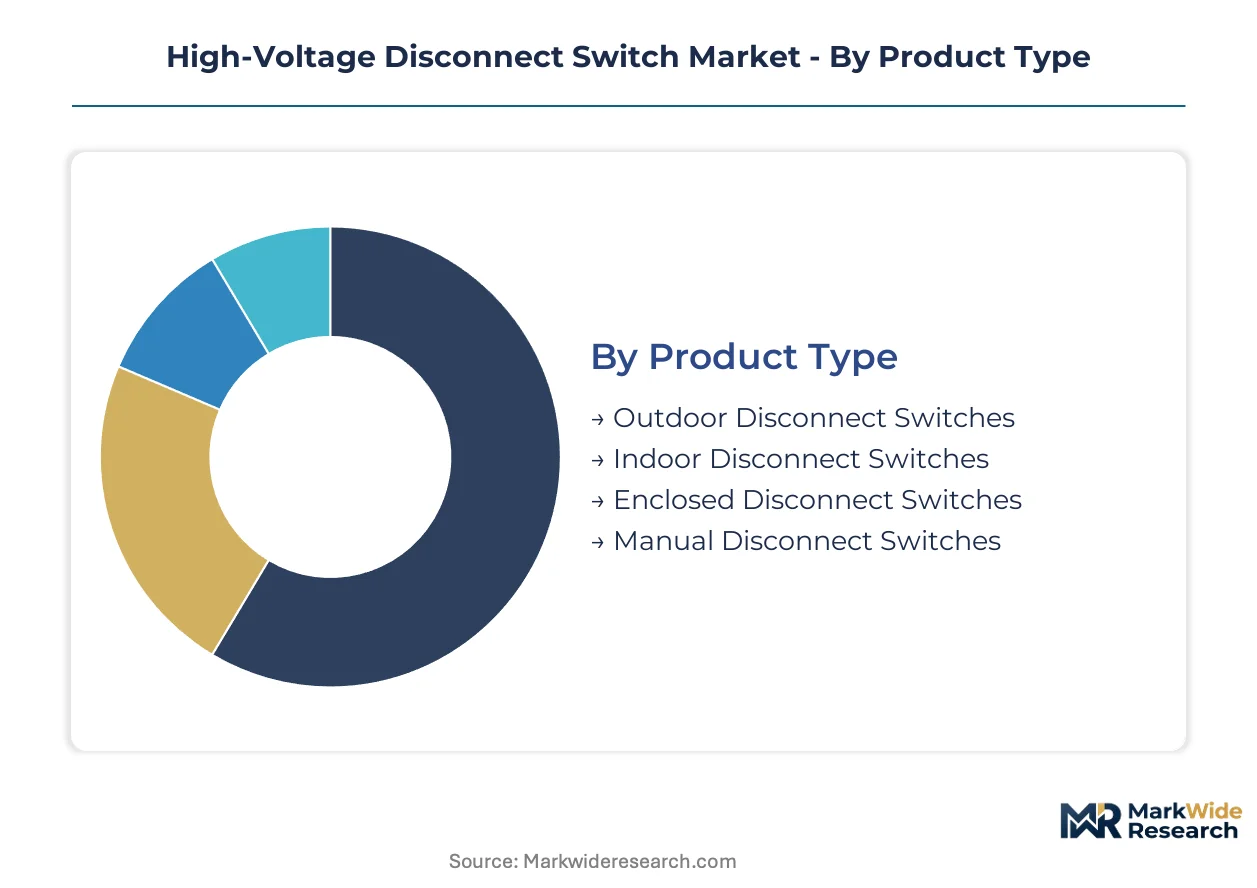
Segmentation in high-voltage disconnect switches reveals how margin pools shift between standardized outdoor installations and specialized marine-grade configurations. Procurement specifications diverge sharply across utilities, industrial facilities, and renewable developers, each demanding distinct insulation technologies and mechanical endurance ratings.
Product Type:
Margin concentration favors outdoor-rated designs exposed to environmental cycling and replacement demand, while enclosed variants command premium positioning in corrosive industrial environments.
- Outdoor Disconnect Switches:These units employ porcelain or composite polymer insulators rated for switching surges above 145 kV and silver-plated copper contacts to withstand thermal cycling across decades of service. Demand concentrates in China's State Grid ultra-high-voltage corridor buildouts and India's rural distribution network upgrades where aging substations require visible isolation hardware. Pole-mounted outdoor configurations dominate terrain-constrained regions across Brazil and Southeast Asia.
- Indoor Disconnect Switches:Designed for gas-insulated switchgear and controlled substation environments, these switches prioritize compact footprint and reduced maintenance access requirements. European utilities are specifying SF6-free indoor alternatives under F-Gas Regulation mandates, redirecting procurement toward vacuum interrupter designs in Germany, France, and the Netherlands.
- Enclosed Disconnect Switches:Marine-grade composite housings protect contact systems in offshore wind farm installations across the North Sea and Baltic Sea clusters.
- Manual Disconnect Switches:Mechanical actuation without motor operators serves backup isolation roles in distribution networks with limited automation infrastructure.
Outdoor Disconnect Switches hold installed capacity across legacy transmission infrastructure. Enclosed Disconnect Switches are rotating up the share rankings as offshore wind interconnection specifications harden.
End User:
Volume distribution tracks capital deployment cycles across power sector stakeholders, with renewable developers exhibiting steepest specification evolution as grid codes tighten.
- Utilities:State-owned grid operators in China, India, and Brazil drive procurement volume through centralized tendering for 145 kV and above ratings. These entities specify IEC 62271-102 certified designs with documented mechanical endurance cycles, prioritizing long-term framework agreements over project-by-project purchasing to consolidate vendor qualification lists.
- Renewable Energy:Solar and wind farm developers require specialized disconnect switches for fault isolation and grid synchronization at interconnection points. Offshore wind clusters in European waters specify corrosion-resistant composite polymer housings with salt spray ratings exceeding terrestrial standards, opening premium product tiers for manufacturers with marine certification pathways.
- Industrial Plants:Heavy manufacturing facilities deploy enclosed disconnect switches in environments with particulate contamination and chemical exposure.
- Commercial Buildings:On-site generation and microgrid installations create demand for compact indoor-rated isolation hardware.
Utilities retain dominant procurement volume through transmission expansion programs. Renewable Energy is climbing the fastest as interconnection queues lengthen and grid codes mandate visible isolation.
Installation:
Configuration selection reflects terrain constraints, maintenance access economics, and seismic or wind-loading requirements that vary by geography.
- Pole-Mounted:Elevated installation on utility poles dominates rural distribution networks across India, Brazil, and Southeast Asia where ground space is constrained or flooding risks prevent pad-mounted alternatives. These configurations require lightweight insulator assemblies and simplified maintenance access procedures suited to distributed field crews.
- Pad-Mounted:Ground-level enclosures with tamper-resistant housings serve urban and suburban distribution circuits where aesthetic and safety considerations restrict pole-mounted hardware.
- Wall-Mounted:Compact indoor substations and industrial control rooms utilize wall-mounted disconnect switches to maximize floor space utilization.
- Ground-Mounted:Heavy-duty foundations support high-voltage ratings above 245 kV in transmission substations with seismic isolation requirements.
Pole-Mounted configurations retain entrenched share in developing distribution networks. Pad-Mounted designs are gaining share fastest as urban undergrounding programs accelerate.
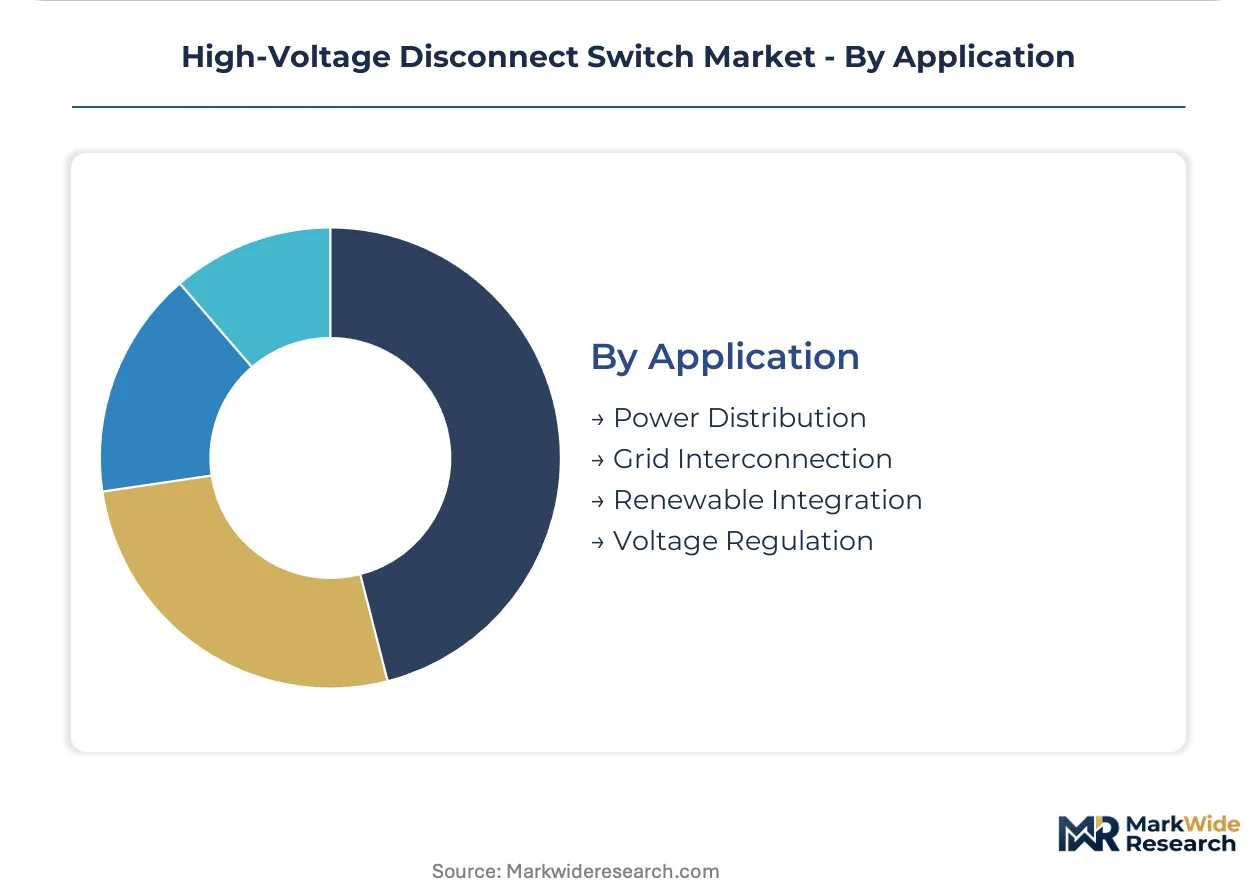
Application:
Functional segmentation separates replacement-driven maintenance applications from growth-oriented interconnection and integration use cases.
- Power Distribution:Routine substation maintenance and line sectionalization create steady replacement demand across aging infrastructure in North America and Europe. These applications prioritize proven mechanical endurance and compatibility with existing busbar configurations to minimize custom engineering requirements.
- Renewable Integration:Solar and wind farm interconnection requires disconnect switches capable of handling variable power flows and fault isolation under dynamic grid conditions. Chinese ultra-high-voltage corridors and European offshore wind clusters are driving specification evolution toward higher voltage ratings and faster switching capabilities.
- Grid Interconnection:Transmission tie-lines between regional grids demand synchronized isolation capabilities with remote monitoring integration.
- Voltage Regulation:Capacitor bank and reactor switching applications require specialized contact systems rated for frequent operation cycles.
Power Distribution anchors revenue through replacement cycles across mature grids. Renewable Integration exhibits the steepest expansion trajectory as clean energy interconnection mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes high-voltage disconnect switches through massive ultra-high-voltage corridor buildouts, while European utilities prioritize SF6-free alternatives and Indian procurement concentrates on rural distribution pole-mounted configurations.
China
State Grid Corporation drives procurement volume through centralized tenders for 800 kV and above ratings. The National Energy Administration mandates visible isolation hardware for renewable interconnection points. Shandong Province hosts concentrated manufacturing clusters where domestic fabricators supply blade forging and contact systems for corridor infrastructure.
Germany
Transmission system operators specify dry air and vacuum insulation in renewable interconnection tenders. The EU F-Gas Regulation and national climate legislation compress SF6 inventory values. Industrial clusters in North Rhine-Westphalia fabricate composite polymer housings for offshore wind farm specifications.
United States
Utilities replace aging outdoor installations across rural substations in the Midwest and Southeast. The EPA enforces NESHAP standards on electrical equipment manufacturing emissions. Texas and California concentrate demand through renewable integration mandates and transmission expansion programs.
India
The Central Electricity Authority directs national grid strengthening through 145 kV and above tender volumes. BIS certification requirements harmonize procurement specifications for domestic and import suppliers. Maharashtra and Gujarat host manufacturing capacity serving state transmission utility programs.
Brazil
Pole-mounted configurations dominate terrain-constrained distribution networks in the Amazon basin and northeastern states. ANEEL regulates transmission expansion through concession auctions. São Paulo and Minas Gerais concentrate industrial demand from heavy manufacturing facilities requiring enclosed isolation hardware.
High-Voltage Disconnect Switch Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in high-voltage disconnect switch supply. Captive casting and machining operations separate margin-sustainable manufacturers from component assemblers exposed to silver price volatility. Three archetypes dominate: vertically integrated European-Japanese conglomerates, Chinese state-backed domestic champions, and regional specialists focused on marine-grade or retrofit applications. Competitive moves concentrate on insulation medium transitions and framework agreement consolidation with state-owned grid operators.
Among integrated conglomerates, Hitachi ABB Power Grids and Siemens Energy occupy positions defined by in-house production of critical components. Shandong Taikai Disconnector exemplifies the state-backed domestic champion archetype serving China's procurement channels. These three anchors represent distinct competitive vectors: technology leadership through vacuum interrupter fabrication, margin control via captive supply chains, and volume concentration through national infrastructure programs.
| Leading Market Players |
|---|
| Hitachi ABB Power Grids |
| Siemens Energy |
| GE |
| MESA |
| SDCEM |
| EMSPEC |
| Insulect |
| Shandong Taikai Disconnector |
| Pinggao Electric |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month lead times for IEC 62271-102 type testing compress procurement flexibility and concentrate pricing power with certified manufacturers holding validated insulation medium portfolios. This temporal bottleneck interacts with silver-plated copper contact sourcing and porcelain insulator manufacturing clusters to stratify margin capture across integrated and assembly-dependent suppliers.
Pricing Analysis
Long-term framework agreements dominate utility procurement, displacing project-by-project tendering and locking in volume commitments with pre-approved manufacturers. Price differentiation rests on IEC 62271-102 certification tier and captive plating operations versus external silver sourcing. Cost compression in standard outdoor configurations intensifies as Chinese domestic champions expand export pricing pressure. Industrial facilities and renewable developers exhibit lowest price sensitivity, prioritizing marine-grade specifications and SF6-free compliance over unit economics.
Supply Chain Analysis
High-purity alumina processing in Shandong Province and contact system forging in Henan Province create dual chokepoints for European and North American switch fabricators. Raw material flows draw from silver concentrate markets, copper rod mills, and composite polymer resin suppliers. Single-source vulnerability concentrates in vacuum interrupter chamber fabrication, where in-house capability separates tier-one suppliers from component assemblers. Distribution runs through state-owned grid operator tender platforms and EPC contractor specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house vacuum chamber fabrication capability now separates margin-sustainable manufacturers from commodity assemblers, creating acquisition premiums for integrated operations and stranded inventory risk for SF6-dependent suppliers.
For Market Incumbents: Consolidate framework agreement coverage with State Grid Corporation and other state-owned operators before certification laboratory backlogs extend competitor launch timelines. Acquire vacuum interrupter fabrication capacity to preempt technology bifurcation that threatens SF6-dependent product lines. Deepen captive silver plating operations to insulate margins from precious metal volatility compressing component assembler economics. For New Entrants and Emerging Players: Anchor in India's 145 kV and above tender expansion, where BIS certification pathways remain less congested than European F-Gas compliance requirements. Target marine-grade composite housing specifications for North Sea offshore wind clusters, where salt spray ratings exceed terrestrial standards and premium positioning sustains margins. Pursue digital twin integration partnerships to shift revenue toward predictive maintenance service models. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum interrupter fabrication, favoring acquisition targets with validated dry air and vacuum insulation portfolios over SF6-dependent legacy assets. Prioritize manufacturers with captive casting and machining operations in Shandong or North Rhine-Westphalia industrial clusters. Monitor IEC 62271-102 certification laboratory backlog durations as inflection indicator for competitive launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Interrupter Fabrication Investment | In-house chamber production separates tier-one suppliers from external sourcing dependency in dry air transitions. |
| Marine-Grade Composite Housing Certification | Offshore wind specifications in North Sea clusters open premium tiers above terrestrial corrosion standards. |
| Framework Agreement Consolidation | Long-term utility contracts displace project tendering and concentrate volume with pre-approved manufacturers. |
| Digital Twin Integration Partnership | IoT condition monitoring enables predictive maintenance revenue streams beyond equipment sales. |
| Silver Plating Operation Captivity | Backward integration into contact systems insulates margins from precious metal commodity volatility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with transmission planning officers, EPC contractor procurement leads, insulator manufacturing plant managers, and aftermarket service heads; and secondary validation through IEC certification databases, State Grid Corporation tender disclosures, EU F-Gas Regulation implementation trackers, and customs trade flow records. Bottom-up demand modeling across installation configurations and voltage ratings triangulated against top-down utility capital expenditure allocations.
Across the analysis window, the forecasting framework modeled product type evolution, end-user procurement pattern shifts, installation configuration preferences, and application-specific insulation medium transitions. CAGRs were derived from utility interconnection queue data and renewable integration mandate trajectories. Forecast inputs incorporated silver price band assumptions and certification laboratory capacity constraints.
Material uncertainties — regulatory acceleration of SF6 phase-out timelines, precious metal commodity spikes, and certification backlog extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding infrastructure investment continuity and standardization harmonization. Practitioners should keep alternative scenarios live as F-Gas Regulation enforcement intensity and ultra-high-voltage corridor completion schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Solid State Relay Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Australia Switchgear Market
Switches
Asia Pacific Transfer Switches Market
Switches
India Reed Sensors Switches Market
Switches
Differential Pressure Switches Market
Switches
Global Disconnector Switch Market
Switches
Proximity Switches Market
Switches
Global Switchgear Market
Switches
Antenna Switch Module Market
Switches
Touchpad Market
Switches
UK Reed Sensors Switches Market
Switches
UAE Switchgear Market
Switches
DC Switchgear Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
Smart Dimmer Switch Market