
 North America Push Buttons & Signaling Devices Market | 2026-2036
North America Push Buttons & Signaling Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Push Buttons & Signaling Devices Market Insights
Mexico's maquiladora belt is fragmenting as new electronics assembly capacity comes online across Baja California and Chihuahua. Rockwell Automation Inc. leverages its integrated architecture platforms to dominate North American factory automation channels. Schneider Electric SE anchors its position through extensive distributor networks spanning Canadian provinces and U.S. industrial hubs. Eaton Corporation competes on ruggedized signaling portfolios purpose-built for oil and gas extraction environments.
Push buttons and signaling devices comprise electromechanical and solid-state interfaces that convert human or machine input into electrical control signals, typically rated for voltages from 24V DC to 600V AC with ingress protection grades spanning IP65 to IP69K. These components serve as the primary human-machine interface in industrial control panels, enabling start-stop functions, status indication, and emergency shutdown sequences across manufacturing floors. Illuminated push buttons and signal towers command premium positioning due to their visibility requirements in high-noise industrial environments where auditory alerts fail. Electronic technology segments are displacing mechanical counterparts as programmable logic controllers demand digital feedback loops, while wireless technology remains nascent outside material handling applications. Panel-mounted installation dominates capital equipment builds, though modular installation gains traction in retrofit scenarios where downtime minimization drives purchasing decisions.
OSHA machine guarding standards mandate conspicuous emergency-stop devices with specific color coding and touch-force parameters, compelling manufacturers to certify products under UL 508 and CSA C22.2 No. 14 protocols. NHTSA regulations for commercial vehicle operator alertness systems create parallel demand for dashboard-integrated signaling devices in heavy trucking applications. FCC Part 15 compliance governs wireless-enabled push button deployments, adding certification layers that filter smaller competitors from premium segments. Stakeholders must weigh the capital intensity of dual-certification strategies against the revenue protection that UL and CSA marks provide across the U.S.-Canada trade corridor.
Market Dynamics
Electronic push buttons are displacing mechanical actuators across North American factory floors as programmable logic controllers demand digital feedback loops, tightening integration requirements between human-machine interfaces and industrial automation systems.
Growth Catalysts
- OSHA Machine Guarding Standards:Federal mandates for conspicuous emergency-stop devices with specific color coding and touch-force parameters compel manufacturers to certify products under UL 508 protocols, driving replacement cycles in legacy equipment.
- NHTSA Commercial Vehicle Alertness Mandates:Heavy trucking operators face tightening compliance requirements for dashboard-integrated signaling devices, expanding the addressable market beyond traditional industrial applications.
- Great Lakes Manufacturing Corridor:Automotive assembly plants across Michigan, Ohio, and Illinois are expanding capital equipment budgets, concentrating demand for illuminated push buttons and signal towers in high-noise production environments.
Market Restraints
- Copper and Rare Earth Input Volatility:Electromechanical contact materials face price swings that compress margin structures for mid-tier manufacturers lacking long-term supply agreements.
- Dual-Certification Capital Intensity:UL 508 and CSA C22.2 No. 14 compliance requirements create fixed cost barriers that filter smaller competitors from premium segments serving the U.S.-Canada trade corridor.
- Wireless Substitution Constraints:FCC Part 15 certification layers and reliability concerns in high-interference environments limit wireless push button penetration outside material handling niches.
Strategic Opportunities
- Baja California Electronics Assembly:Mexico's maquiladora belt expansion creates localized demand for panel-mounted signaling devices in new electronics manufacturing capacity coming online.
- Modular Retrofit Channel:Downtime-sensitive buyers in aging industrial infrastructure favor modular installation formats that minimize production line interruption during component replacement.
- IP69K-Rated Oil and Gas Applications:Ruggedized signaling portfolios purpose-built for extraction environments command premium positioning in Canadian oil sands and Permian Basin operations.
Industry Challenges
- Legacy System Integration Complexity:Electronic push buttons with digital outputs face protocol-matching friction when retrofitting 24V DC mechanical control circuits in decades-old industrial infrastructure.
- Mechatronics Skill Scarcity:Maintenance technicians fluent in both solid-state electronics and electromechanical troubleshooting remain concentrated in automotive hubs, creating service coverage gaps in secondary industrial markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Push Buttons & Signaling Devices Market |
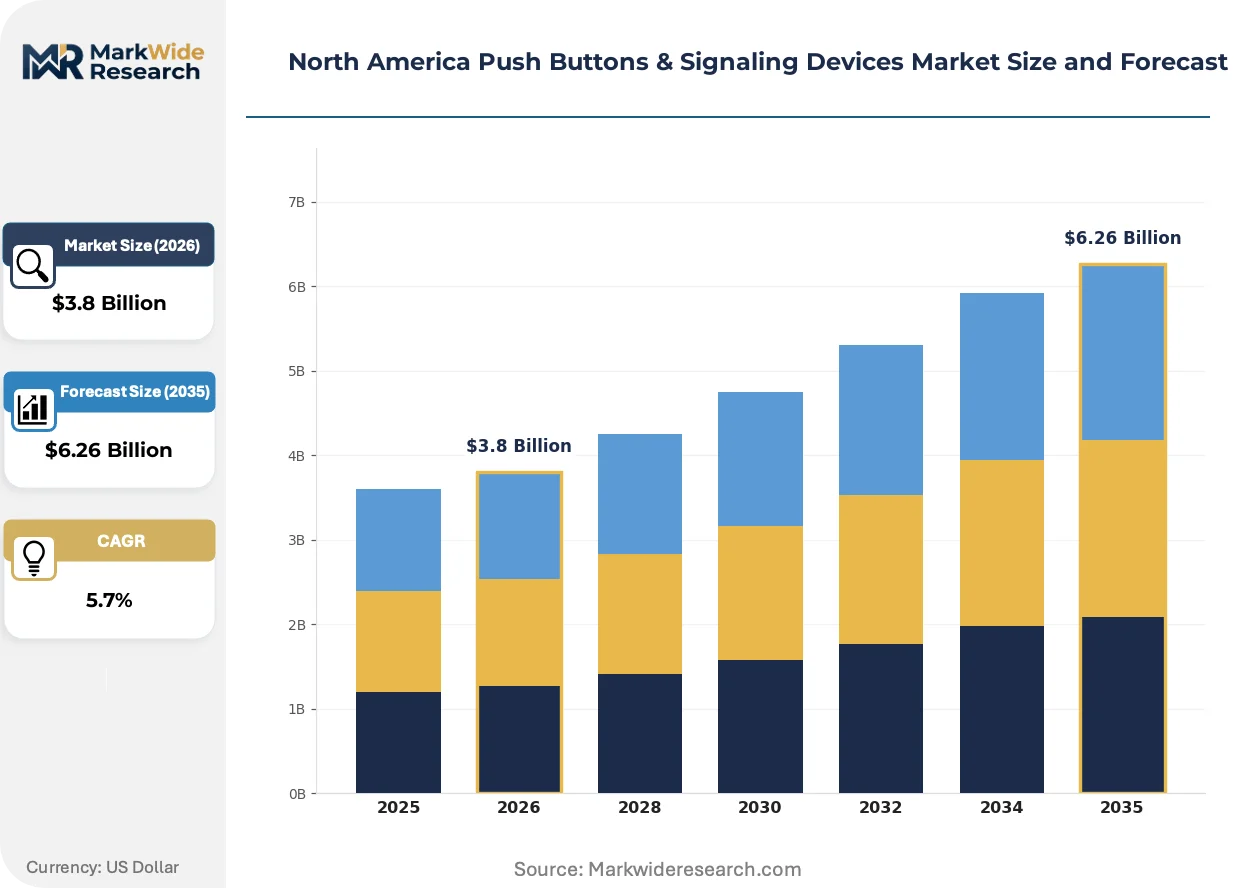
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Illuminated Push Buttons, Non-Illuminated Push Buttons, Signal Towers, Indicator Lights Technology: Mechanical Technology, Electronic Technology, Wireless Technology, Hybrid Technology End User: Industrial Automation, Consumer Electronics, Automotive Systems, Telecommunications Installation: Panel-Mounted, Surface-Mounted, Flush-Mounted, Modular Installation |
| Companies Covered | Rockwell Automation Inc., Schneider Electric SE, ABB Ltd, Siemens AG, Eaton Corporation, Honeywell International Inc., Federal Signal Corporation, General Electric, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Push Buttons & Signaling Devices Market Trends and Innovations
Human-machine interface technology is converging with industrial IoT architectures, compressing the boundary between physical actuation and digital control networks across North American manufacturing operations.
Capacitive touch sensing technology is virtualizing the physical button experience in cleanroom and food processing environments where mechanical crevices harbor contamination risks. Pharmaceutical manufacturers and semiconductor fabs are adopting these interfaces at accelerated paces to satisfy FDA and ISO 14644 hygiene protocols. The technology is virtualizing traditional supply chains by collapsing the distinction between switch hardware and embedded software, forcing component suppliers to develop firmware competencies or cede margin to integrated platform vendors.
NHTSA regulations for commercial vehicle operator alertness systems are mandating dashboard-integrated haptic and visual signaling devices in heavy trucking applications. Fleet operators must retrofit existing vehicles or specify compliant equipment in new orders, expanding the addressable market beyond factory automation into transportation infrastructure. Canadian provincial transport authorities are harmonizing with U.S. standards, creating unified certification pathways for cross-border equipment suppliers.
Buyer preference is compressing toward distributor-managed inventory programs that guarantee four-hour replacement availability for critical signaling components. Automotive assembly plants and petrochemical refineries are displacing spot purchasing with vendor-managed stock agreements that shift carrying costs upstream. This behavioral shift is most visible in the Great Lakes corridor, where just-in-sequence production tolerances leave minimal buffer for component failure.
North America Push Buttons & Signaling Devices Market Segmentation
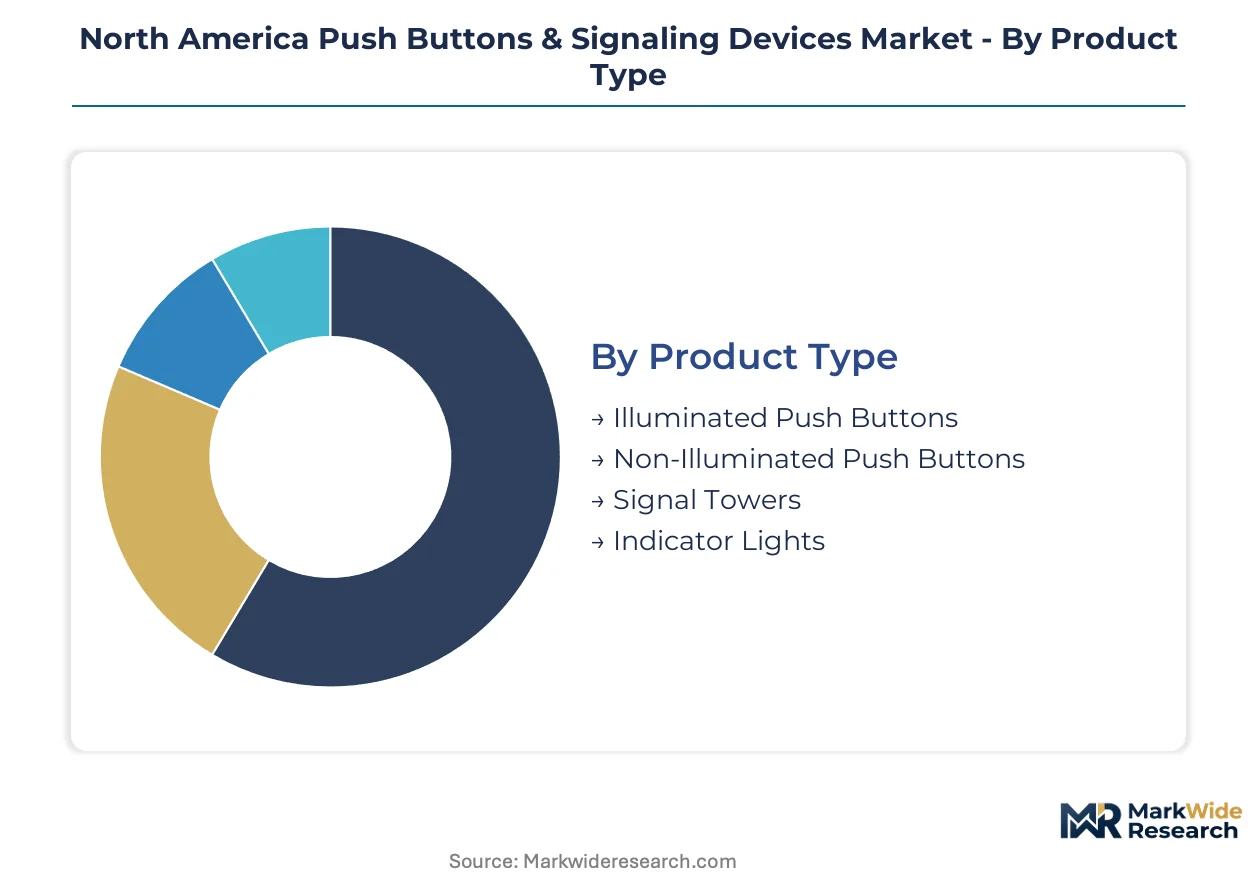
Push buttons and signaling devices fragment across four structural dimensions that shape procurement patterns and margin profiles. Product type and technology choices determine certification requirements and integration complexity. Installation format and end-use vertical dictate channel access and replacement cycle timing.
Product Type:
The use-case spectrum spans visibility-critical safety applications to basic control functions, with illumination status serving as the primary price discriminator.
- Illuminated Push Buttons:LED-integrated actuators with voltage ratings from 24V to 230V provide visual state confirmation in high-noise automotive assembly environments. Demand concentrates in Michigan and Ohio manufacturing corridors where OSHA machine guarding mandates require conspicuous emergency-stop visibility.
- Signal Towers:Multi-segment stack lights with IP65+ enclosures enable hierarchical status indication across sprawling production floors. Petrochemical refineries in Texas and Louisiana specify these for process state visualization where auditory alerts fail.
- Non-Illuminated Push Buttons:Basic electromechanical actuators serve cost-sensitive auxiliary control circuits in legacy equipment retrofits.
- Indicator Lights:Standalone visual signaling elements supplement panel diagnostics in distributed control architectures.
Established volume favors non-illuminated push buttons; emerging adoption favors illuminated variants.
Technology:
Cost tier separation runs from commodity mechanical components to firmware-dependent electronic platforms requiring integration engineering.
- Electronic Technology:Solid-state actuators with digital output protocols enable direct PLC integration without intermediary relay logic. Automotive assembly plants across the Great Lakes corridor specify these for Industry 4.0 retrofit programs.
- Mechanical Technology:Electromechanical contact assemblies with silver-nickel alloys dominate legacy 24V DC control circuits in decades-old infrastructure.
- Wireless Technology:Battery-powered or energy-harvesting actuators eliminate conduit runs in material handling applications.
- Hybrid Technology:Mechanical actuation with electronic signal conditioning bridges retrofit scenarios requiring physical feedback with digital system compatibility.
Mechanical technology retains installed-base dominance; electronic platforms are climbing the fastest.
End User:
Application maturity varies from saturated factory automation to nascent transportation integration.
- Industrial Automation:Control panel builders and system integrators specify push buttons across discrete manufacturing, process industries, and packaging machinery.
- Automotive Systems:NHTSA alertness mandates are driving dashboard-integrated signaling device specifications for heavy trucking operators.
- Consumer Electronics:Appliance manufacturers source compact tactile switches for interface panels.
- Telecommunications:Network equipment builders specify sealed actuators for outdoor enclosure applications.
Procurement concentration sits with industrial automation; regulatory tailwinds favor automotive systems.
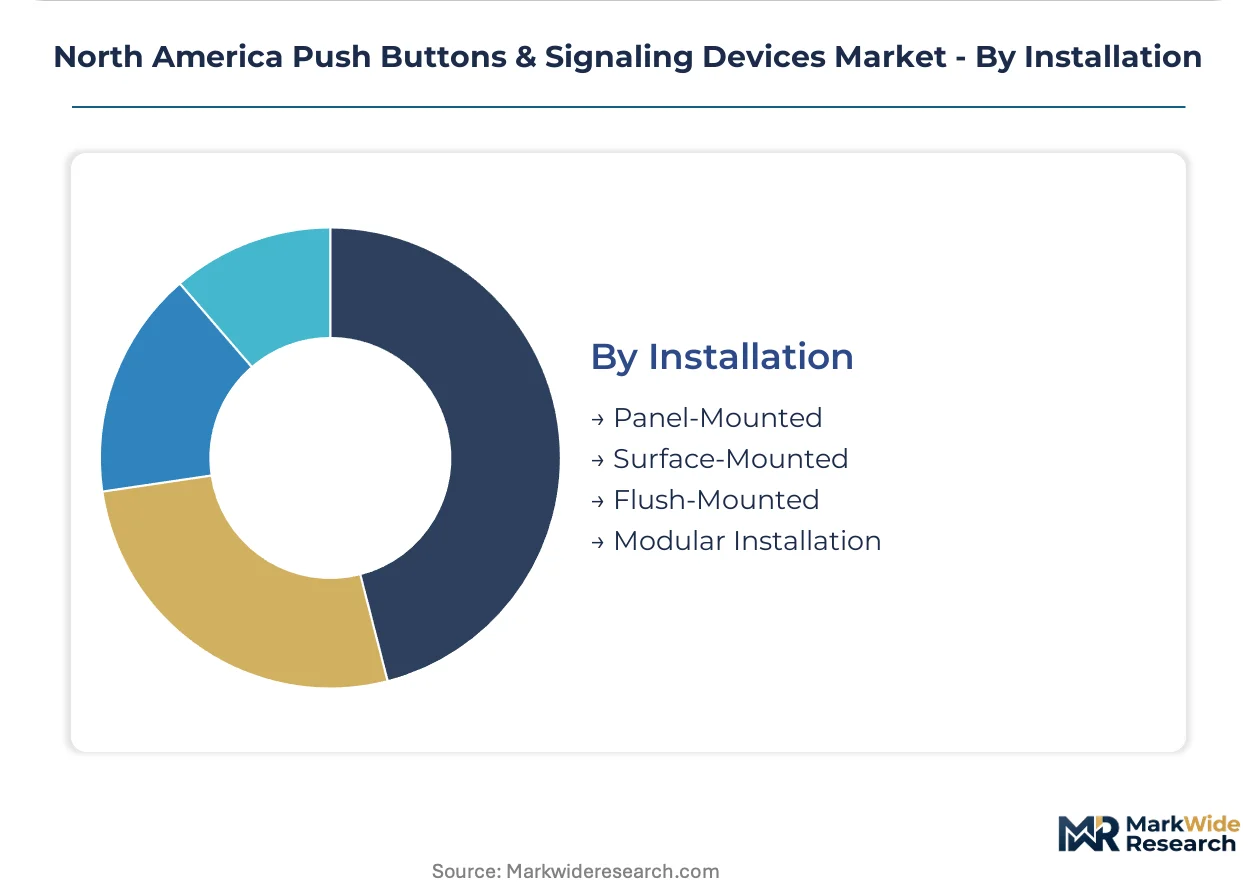
Installation:
Customer type splits between OEM panel builders favoring standardized formats and maintenance departments prioritizing swap speed.
- Panel-Mounted:Threaded or snap-in actuators dominate new capital equipment builds where design-for-manufacturing optimizes assembly labor.
- Modular Installation:Tool-free replacement formats with standardized contact blocks minimize downtime in just-in-sequence production environments.
- Surface-Mounted:Box-mounted configurations serve field-constructed control stations in extraction and construction applications.
- Flush-Mounted:Recessed actuators with membrane overlays satisfy hygiene protocols in food processing and pharmaceutical cleanrooms.
Panel-mounted formats capture OEM volume; modular formats gain share in aftermarket channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply chains for push buttons and signaling devices concentrate in industrial corridors where factory automation adoption runs deepest. Component manufacturers locate near OEM panel builders to compress lead times for just-in-sequence production environments.
United States
OSHA machine guarding mandates drive replacement cycles across aging industrial infrastructure in Michigan, Ohio, and Illinois. NHTSA commercial vehicle alertness regulations expand demand for dashboard-integrated signaling devices in heavy trucking fleets. The Great Lakes manufacturing corridor anchors demand concentration, with automotive assembly plants specifying illuminated push buttons for high-noise production floors.
Canada
CSA C22.2 No. 14 certification requirements filter suppliers serving the U.S.-Canada trade corridor, favoring manufacturers with dual UL and CSA marks. Health Canada harmonizes with U.S. transport safety standards for cross-border commercial vehicle equipment. Alberta's oil sands operations specify IP69K-rated signaling devices for extraction environments where ruggedized portfolios command premium positioning.
Mexico
Maquiladora belt expansion across Baja California and Chihuahua creates localized demand for panel-mounted signaling devices in new electronics assembly capacity. The country's federal labor regulations tighten machine safety requirements in export-oriented manufacturing zones. Mexico City Metro and Nuevo León industrial parks concentrate procurement from distributors with four-hour replacement availability guarantees.
North America Push Buttons & Signaling Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower portfolios. The vendor base spans multinational automation conglomerates and regional electromechanical fabricators. Three archetypes dominate: architecture-platform vendors with integrated control systems, ruggedized-environment specialists with extraction-grade certifications, and distributor-anchored suppliers with managed inventory programs. Competitive moves center on certification stacking for cross-border trade and modular format development for retrofit channels.
Among North American automation conglomerates, Rockwell Automation Inc. and Eaton Corporation exemplify contrasting strategic positions. Rockwell occupies the architecture-platform tier with integrated control system offerings. Eaton sits within the ruggedized-specialist archetype with purpose-built signaling portfolios. Schneider Electric SE anchors the distributor-network tier with extensive coverage across Canadian provinces and U.S. industrial hubs. These three represent the dominant competitive vectors without exhausting the competitive set.
| Leading Market Players |
|---|
| Rockwell Automation Inc. |
| Schneider Electric SE |
| ABB Ltd |
| Siemens AG |
| Eaton Corporation |
| Honeywell International Inc. |
| Federal Signal Corporation |
| General Electric |
| Omron Corporation |
| Others |
Pricing and Supply Chain Analysis
The I-35 freight corridor linking Laredo to Detroit compresses logistics costs for electromechanical component flows, concentrating supply-side leverage among dual-certified manufacturers while forcing price stratification between UL 508-compliant premium tiers and uncertified economy alternatives in the North American push buttons and signaling devices market.
Pricing Analysis
OSHA machine guarding standards dictate the pricing tier structure across the North American push buttons and signaling devices market, separating UL 508-certified premium products from standard CSA-marked alternatives and uncertified economy imports. Certification grade and volume scale serve as the primary price differentiation drivers, with automotive OEMs commanding contract-based long-term offtake discounts unavailable to aftermarket maintenance buyers. Pricing pressure stems from copper and rare earth input volatility that compresses margins for mid-tier manufacturers lacking captive supply agreements. Aftermarket maintenance departments exhibit the highest price sensitivity due to unplanned replacement cycles, while Great Lakes automotive assembly plants prioritize four-hour availability guarantees over unit cost.
Supply Chain Analysis
Silver-nickel contact alloys, LED illumination modules, and thermoplastic enclosure resins anchor upstream feedstock dependencies for North American push button manufacturing. Component sourcing concentrates in Mexico, China, and Taiwan, with maquiladora facilities in Baja California and Chihuahua providing final assembly proximity to U.S. industrial corridors. Single-source vulnerability in rare earth magnet supply for electronic actuator variants creates structural risk exposure during trade policy shifts. Distribution runs through authorized distributor networks with vendor-managed inventory programs dominating procurement channels for downtime-sensitive automotive and petrochemical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against touchscreen HMI substitution in cleanroom applications while electronic push buttons displace mechanical actuators across factory floors, requiring certification stacking and firmware competency investments to maintain pricing power.
For Market Incumbents: Build certification moats around dual UL 508 and CSA C22.2 No. 14 marks that filter smaller competitors from premium segments serving the U.S.-Canada trade corridor. Backward integration into silver-nickel contact material supply hedges against copper price volatility compressing margin structures. Channel control through distributor-managed inventory programs with four-hour replacement guarantees locks in automotive assembly plant procurement decisions against modular retrofit specialists. For New Entrants and Emerging Players: Build out IP69K-rated signaling portfolios targeting Canadian oil sands and Permian Basin extraction environments where ruggedized certifications command premium positioning unavailable to generalist competitors. Baja California electronics assembly capacity expansion creates the most penetrable geography for panel-mounted installation formats in new maquiladora facilities. Go-to-market execution should anchor on direct relationships with OEM panel builders rather than competing for aftermarket retrofit share dominated by incumbent distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core electromechanical component divisions lacking firmware integration capabilities required for Industry 4.0 retrofit programs. Long-term viability over the next decade hinges on electronic technology segment capture as programmable logic controllers demand digital feedback loops. Watch for NHTSA enforcement acceleration on commercial vehicle operator alertness mandates as the inflection signal signaling transportation infrastructure market expansion beyond traditional factory automation applications.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | UL 508 and CSA C22.2 No. 14 stacking protects revenue across the U.S.-Canada trade corridor. |
| Firmware Competency Development | Embedded software capabilities prevent margin capture by integrated platform vendors like Rockwell Automation. |
| Modular Format Expansion | Tool-free replacement designs capture aftermarket retrofit share in downtime-sensitive production environments. |
| Maquiladora Proximity Sourcing | Baja California and Chihuahua assembly capacity compresses lead times for just-in-sequence automotive procurement. |
| Ruggedized Portfolio Extension | IP69K-rated extraction-grade certifications command premium positioning in Alberta oil sands and Permian Basin operations. |
Research Methodology
A standing panel of maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided ongoing calibration across primary interview cycles, cross-checked against customs trade records, SEC 10-K filings, OSHA enforcement databases, and NHTSA regulatory dockets. Bottom-up demand aggregation from automotive assembly plants, petrochemical refineries, and electronics manufacturing facilities triangulated against top-down supply-side capacity assessments from electromechanical component fabricators.
Scenario-bracketing around copper price volatility, maquiladora expansion timing, and NHTSA enforcement intensity framed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, installation format, and end-use vertical with specific weighting for automotive systems regulatory tailwinds. CAGRs derived from historical replacement cycle analysis, capital equipment budget trajectories in the Great Lakes corridor, and electronics assembly capacity buildout in northern Mexico.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese electronic component manufacturers or accelerated touchscreen HMI substitution in food processing applications would shift outcomes beyond modeled ranges. Cross-checking against IHS Markit industrial automation equipment forecasts and ACC plastics demand indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Italy Reed Sensors Switches Market
Switches
5G Solid State Switches Market
Switches
Japan Reed Sensors Switches Market
Switches
Micro Switch Market
Switches
Transfer Switch Market
Switches
Navigation Switches Market
Switches
Global Smart Switch Panel Market
Switches
North America MV Switchgear Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Canada Switch Gear Market
Switches
United States Circuit Breaker Market
Switches
Dual Power Transfer Switches Market
Switches
Membrane Switch Market
Switches
India Switchgear Market
Switches
South America Low Voltage Switchgear Market
Switches
Global Switchgear Market