
 Edible Fiber Market | 2026-2036
Edible Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Fiber Market Analytics
Precision fermentation and enzymatic extraction is narrowing the cost gap between plant-derived and microbially produced soluble fibers. Cargill Incorporated leverages its integrated agricultural supply chain to control input costs across corn and wheat fiber streams. Tate & Lyle PLC anchors its positioning in resistant starch and soluble corn fiber through dedicated R&D facilities in Europe and North America. BENEO GmbH differentiates via chicory root inulin specialization, sustaining premium pricing in prebiotic applications.
Edible fiber comprises carbohydrate polymers resistant to digestion in the human small intestine, with soluble variants dissolving in water to form viscous gels while insoluble types retain structural integrity to promote bowel regularity. Soluble fiber commands the largest volume share due to its functional versatility in texture modification and sugar reduction across processed foods. Insoluble fiber competes primarily on cost in bakery and cereal applications where water-binding capacity drives formulation value. Functional fiber, including psyllium and resistant dextrins, captures expanding demand from nutraceutical and pharmaceutical channels seeking clinically substantiated digestive health claims.
The FDA's dietary fiber definition under 21 CFR 101.9, the EFSA health claims framework for bowel function, and Health Canada's fiber fortification guidelines collectively determine which ingredients qualify for labeled fiber content and associated health messaging. These regulatory gatekeeping functions create compliance barriers that favor established suppliers with clinical dossiers over commodity entrants. Stakeholders must monitor evolving qualification criteria as jurisdictions tighten evidentiary standards for novel fiber sources.
Market Dynamics
Precision fermentation is compressing production economics for microbial-derived soluble fibers, forcing incumbent plant-based suppliers to defend margin positions through supply chain restructuring and clinical dossier investments.
Growth Catalysts
- Prebiotic Health Claims:EFSA's pending favorable opinions on chicory inulin and resistant starch are unlocking label permissions across functional dairy and beverage categories in Europe.
- Sugar Reduction Mandates:Processed food manufacturers in the United States are substituting soluble corn fiber for sucrose to meet FDA-added sugar disclosure thresholds without sacrificing texture.
- Enzymatic Extraction Scale-Up:Continuous processing technology is lowering energy inputs for beta-glucan isolation from oat and barley streams.
Market Restraints
- Clinical Evidence Burden:FDA's 21 CFR 101.9 definition requires isolated non-digestible carbohydrates to demonstrate physiological benefits, excluding many novel candidates from labeled fiber content.
- Chicory Root Supply Concentration:Northern Belgian and Dutch agricultural zones control 70% of global inulin raw material, exposing processors to weather-driven crop volatility.
- Resistant Maltodextrin Substitution:Japanese manufacturers of resistant dextrins are capturing share in Asian functional beverage markets through lower price positioning.
Strategic Opportunities
- Precision Fermentation Expansion:Microbial cellulose and exopolysaccharide production via bacterial fermentation is opening synthetic biology pathways independent of agricultural feedstocks.
- Clean-Label Bakery Applications:Insoluble wheat fiber with modified particle size is displacing methylcellulose in gluten-free bread formulations seeking shorter ingredient decks.
- India FSSAI Fiber Fortification Guidelines:The regulator's proposed minimum fiber content thresholds for packaged foods are creating first-mover advantages for suppliers establishing local blending operations.
Industry Challenges
- Clinical Trial Design Complexity:Substantiating specific digestive health claims requires randomized controlled trials with biomarker endpoints, extending time-to-market for novel fiber sources by 18-24 months.
- Formulation Integration Expertise:Bakery and extruded snack applications demand specialized hydrocolloid knowledge to manage water activity and shelf stability when replacing conventional texturizers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Fiber Market |
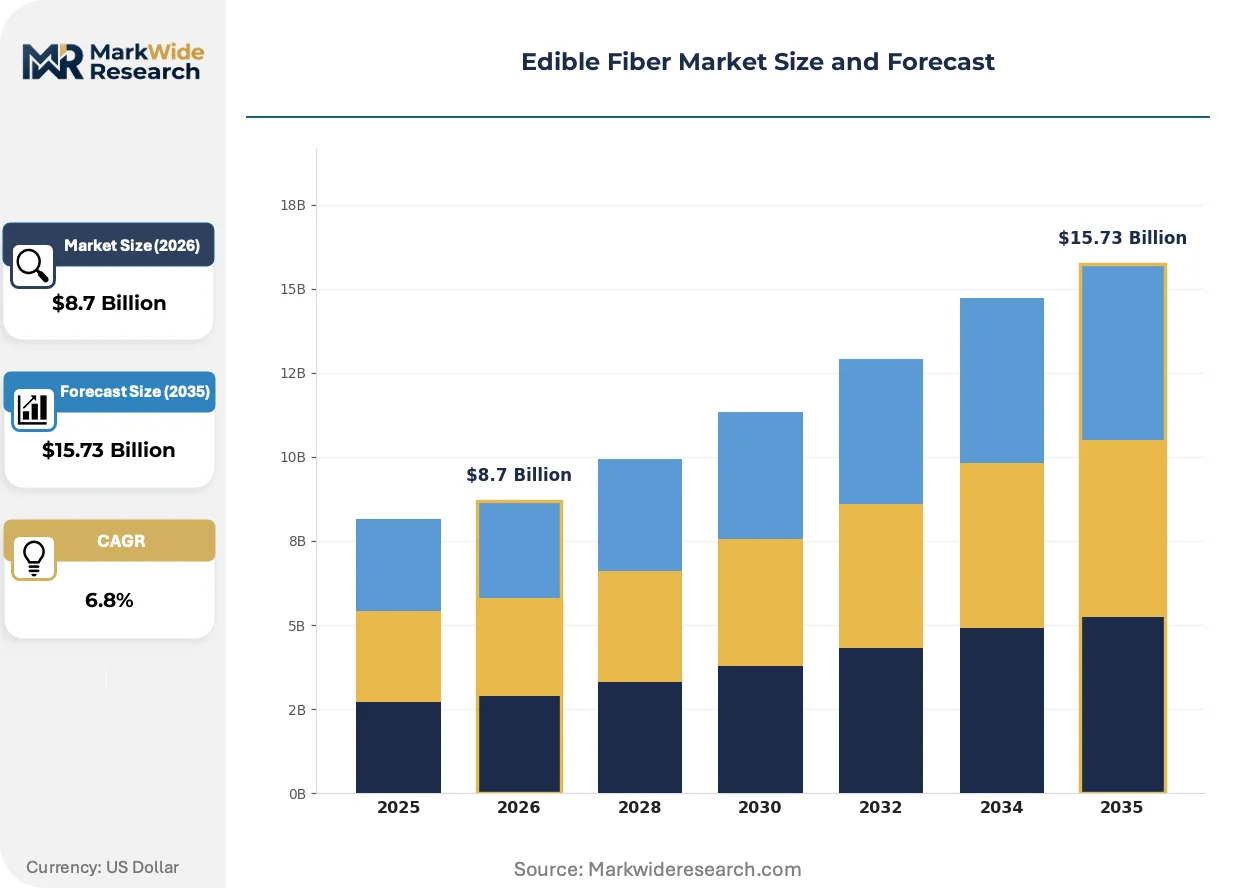
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soluble Fiber, Insoluble Fiber, Functional Fiber, Psyllium Fiber Application: Food & Beverages, Nutraceuticals, Pharmaceuticals, Dietary Supplements Form: Powder, Flakes, Capsules, Granules Customer Type: Health-conscious Individuals, Fitness Enthusiasts, Medical Patients, Nutritionists |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Ingredion Incorporated, Tate & Lyle PLC, BENEO GmbH, Roquette Frères, Kerry Group plc, DuPont de Nemours Inc., Nexira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Fiber Market Evolving Landscape
Digital process control and biosynthetic production methods are converging to transform how fiber ingredients are manufactured, characterized, and specified across food system supply chains.
Near-infrared spectroscopy coupled with machine learning is digitizing real-time compositional analysis of incoming agricultural raw materials. Major grain processors are deploying inline sensors to standardize arabinoxylan and beta-glucan content across wheat and oat lots before enzymatic extraction begins. This capability is compressing batch-to-batch variation and enabling forward contract pricing based on verified functional specifications rather than generic commodity grades.
EFSA's updated guidance on health claim substantiation for bowel function is tightening evidentiary requirements for resistant starch and oligosaccharide ingredients. The framework now mandates human intervention studies with validated outcome measures, disqualifying many existing literature reviews. European prebiotic suppliers are responding by commissioning new clinical trials while repositioning existing products toward less regulated "source of fiber" claims.
Direct specification between ingredient suppliers and retail brand R&D teams is displacing traditional distributor-mediated procurement in North American clean-label segments. Large CPG manufacturers are building captive fiber development partnerships with single-source suppliers to secure exclusive access to novel resistant dextrin variants. This pattern is most visible in the United States, where private-label growth at specialty retailers is compressing formulation cycle times and rewarding agile supplier relationships.
Edible Fiber Market Segmentation
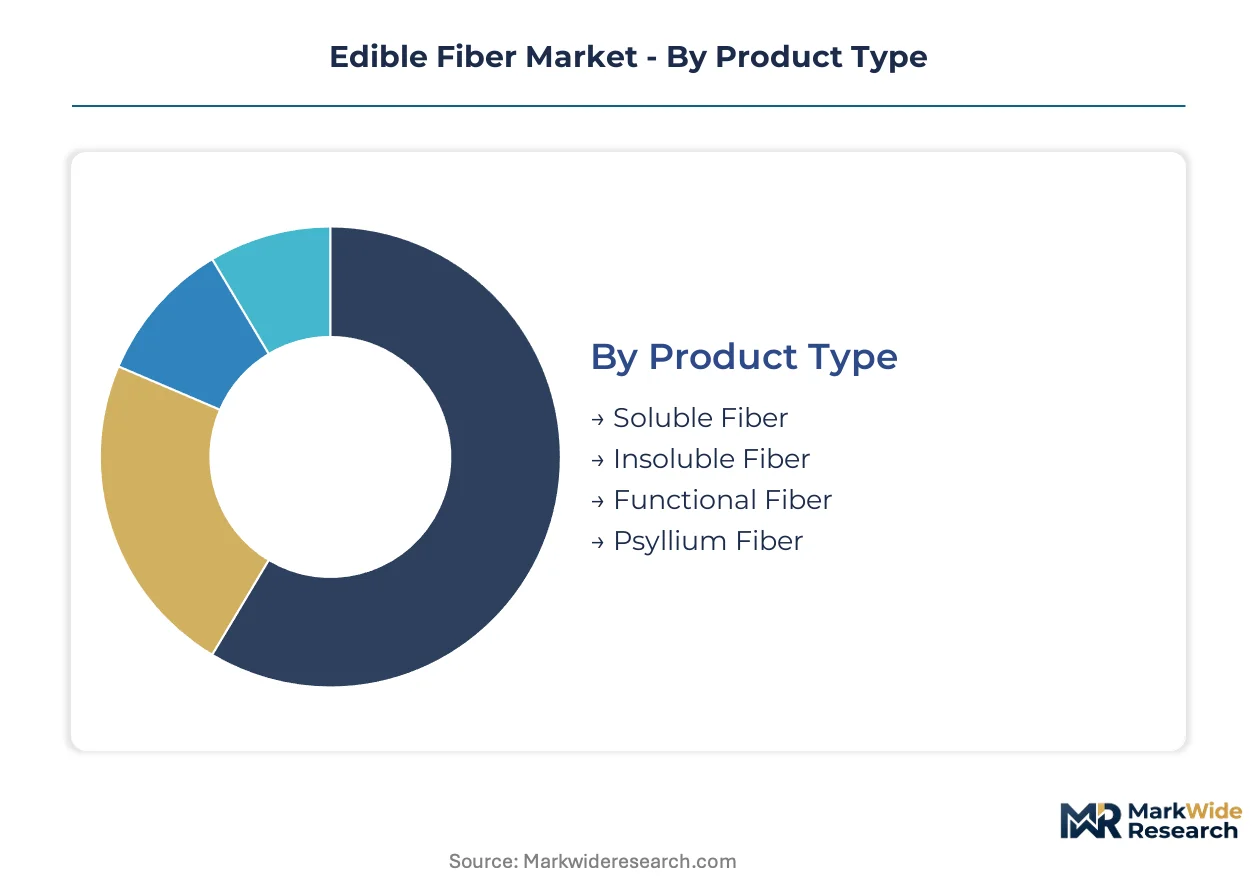
Edible fiber procurement cycles vary dramatically across product categories, with soluble fiber formulations turning over quarterly for beverage applications while pharmaceutical-grade psyllium contracts extend across multi-year supply agreements. Understanding these velocity differentials helps suppliers align inventory positions with actual consumption patterns rather than aggregated demand signals.
Product Type:
Soluble fiber commands the shortest procurement cycles among all categories, with food manufacturers rotating specifications seasonally to match formulation requirements for functional beverages and sugar-reduced baked goods. Insoluble fiber contracts typically span annual frameworks tied to wheat and corn harvest calendars, while functional fiber and psyllium fiber operate on extended validation timelines due to clinical substantiation requirements.
- Soluble Fiber:Dissolves in water to form viscous gels, enabling texture modification and sugar replacement in processed foods. Food and beverage manufacturers in the United States are accelerating incorporation into clean-label functional beverages driven by FDA-added sugar disclosure thresholds.
- Insoluble Fiber:Retains structural integrity through the digestive tract, promoting bowel regularity through mechanical bulk. Bakery and cereal applications concentrate demand where water-binding capacity drives formulation economics and cost competition dominates supplier selection.
- Functional Fiber:Includes resistant dextrins and oligosaccharides with clinically substantiated prebiotic properties. Nutraceutical channels seek these ingredients for digestive health positioning.
- Psyllium Fiber:Derived from Plantago ovata seed husks with established cholesterol-lowering claims. Pharmaceutical and medical nutrition applications require extensive clinical dossiers.
Soluble fiber anchors the volume base while functional fiber gains share at the steepest rate.
Application:
Application segmentation reveals divergent margin structures, with pharmaceutical and nutraceutical channels commanding premium pricing against standardized food and beverage procurement. Dietary supplements occupy an intermediate position, blending volume scale with some functional differentiation.
- Food & Beverages:Largest consumption channel spanning bakery, dairy, beverages, and extruded snacks. Manufacturers leverage soluble corn fiber and inulin for sugar reduction and texture optimization.
- Nutraceuticals:Prebiotic supplements and functional foods with explicit gut-health positioning. EFSA health claim frameworks determine which ingredients qualify for labeled benefits.
- Pharmaceuticals:Laxative formulations, cholesterol management products, and medical foods. FDA 21 CFR 101.9 compliance requirements extend development timelines significantly.
- Dietary Supplements:Capsule, tablet, and powder formats targeting health-conscious consumers. Clean-label positioning favors single-ingredient fiber sources over blends.
Food and beverages generate the highest absolute volume, though pharmaceuticals deliver superior unit economics.
Form:
Form selection directly determines manufacturing compatibility, with powder and granule formats integrating into high-throughput food processing while capsules and flakes serve specialized nutritional applications. Powder dominates industrial procurement due to handling efficiency and dosing precision.
- Powder:Fine-milled fiber with standardized particle size distribution for homogeneous dispersion in dry mixes. Food manufacturers prefer this form for beverage and bakery integration.
- Flakes:Coarse structural fiber retaining visual identity in finished products. Cereal and granola applications concentrate demand.
- Capsules:Pre-measured unit doses for supplement and pharmaceutical channels. Consumer convenience drives preference.
- Granules:Intermediate particle size offering flowability advantages for tableting operations. Nutraceutical manufacturers specify this form for compression efficiency.
Powder forms command the broadest addressable market, while capsules expand most quickly in direct-to-consumer channels.
Customer Type:
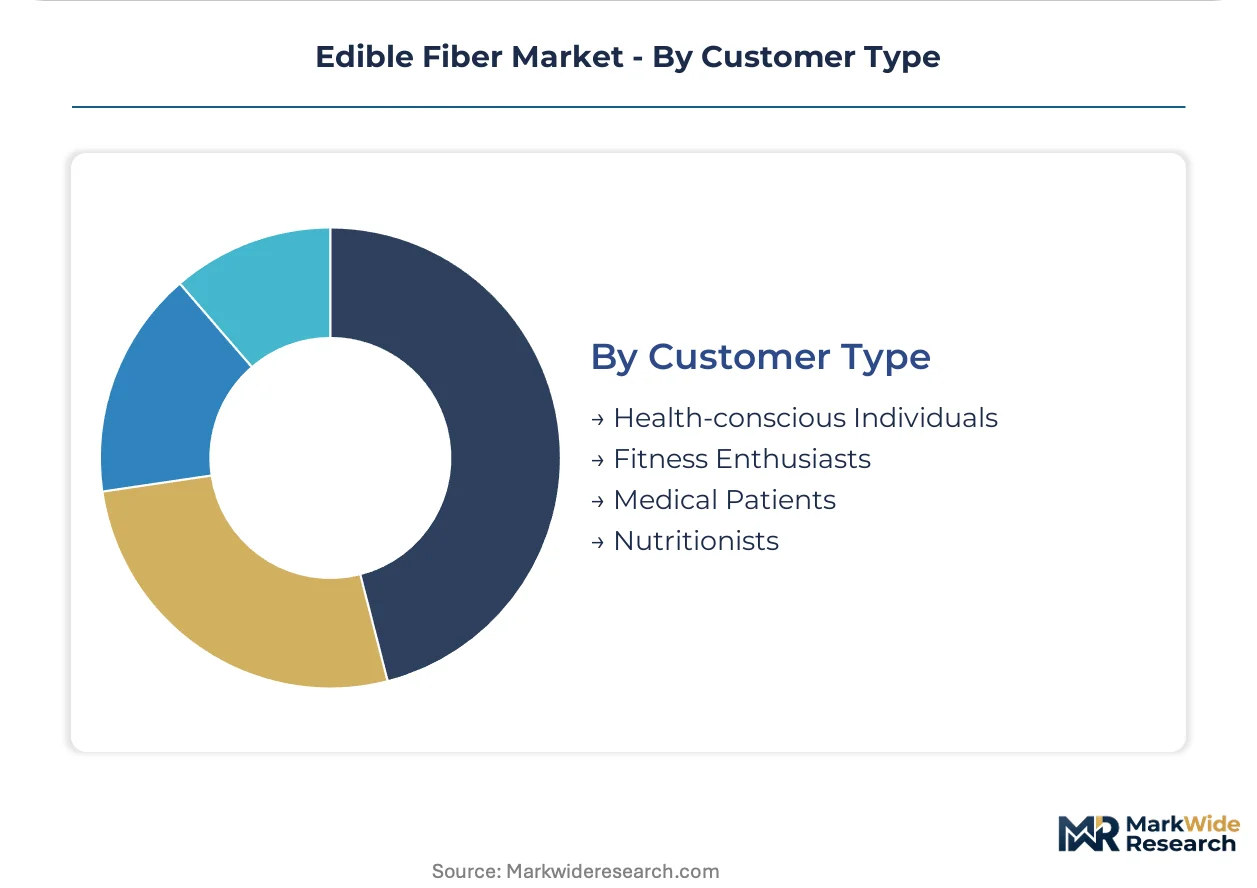
Customer segmentation maps directly to distribution architecture, with health-conscious individuals purchasing through retail and e-commerce while medical patients access fiber through prescription and clinical nutrition pathways. Fitness enthusiasts represent a high-engagement segment with strong brand loyalty potential.
- Health-conscious Individuals:Mass-market consumers seeking preventive wellness through fortified foods and basic supplements. Clean-label claims strongly influence purchase decisions.
- Fitness Enthusiasts:Performance-oriented consumers prioritizing macronutrient optimization and gut health for recovery. Prebiotic fiber integration into protein supplements concentrates demand.
- Medical Patients:Individuals with diagnosed digestive conditions, metabolic syndrome, or cholesterol management needs. Physician and dietitian recommendations guide selection.
- Nutritionists:Professional advisors influencing institutional and individual procurement. Evidence-based positioning determines recommendation patterns.
Health-conscious individuals provide the foundational demand base, with fitness enthusiasts climbing the fastest as sports nutrition brands expand fiber fortification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large CPG procurement teams in the United States drive premium soluble fiber specifications, while European manufacturers prioritize EFSA-compliant health claims and Asian processors seek cost-optimized resistant dextrin sources.
United States
Clean-label bakery reformulations and FDA-added sugar disclosure thresholds accelerate soluble corn fiber procurement. FDA's 21 CFR 101.9 dietary fiber definition filters ingredient qualification. Chicago and Minneapolis-St. Paul host major grain processor headquarters where R&D teams co-develop fiber blends with CPG partners.
Germany
EFSA health claim substantiation requirements shape prebiotic ingredient selection in functional dairy. BfR (Federal Institute for Risk Assessment) coordinates with EFSA on novel fiber safety assessments. Hamburg and Frankfurt concentrate ingredient distributor networks serving Central European manufacturers.
Belgium
Northern Belgian agricultural zones supply 70% of global chicory root for inulin extraction. FASFC (Federal Agency for the Safety of the Food Chain) enforces EU hygiene standards on fiber processing facilities. Tienen and Oreye host specialized extraction plants serving pharmaceutical-grade specifications.
India
FSSAI's proposed fiber fortification guidelines for packaged foods create compliance-driven procurement shifts. CDSCO regulates psyllium husk exports for pharmaceutical applications. Gujarat and Rajasthan dominate psyllium cultivation with processing clusters in Sidhpur and Unjha.
Japan
Resistant dextrin manufacturers capture functional beverage share through lower price positioning than Western suppliers. PMDA oversees FOSHU (Foods for Specified Health Uses) fiber claim approvals. Osaka and Tokyo metropolitan areas concentrate beverage R&D facilities developing fiber-fortified formulations.
Edible Fiber Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated agribusiness conglomerates leverage backward grain supply control against dedicated fiber extractors with clinical dossier depth. Strategic archetypes include: (1) diversified grain processors with captive starch-to-fiber conversion, (2) chicory root specialists with prebiotic claim exclusivity, and (3) enzymatic technology licensors enabling second-tier manufacturer entry. Dominant competitive moves center on clinical trial investments for regulatory qualification and exclusive supply partnerships with major CPG brand R&D teams.
Within the diversified processor tier, Cargill Incorporated and Archer Daniels Midland Company represent integrated supply chain control from agricultural procurement through ingredient specification. Tate & Lyle PLC exemplifies the technology-specialist archetype with dedicated resistant starch and soluble corn fiber R&D infrastructure spanning European and North American facilities. BENEO GmbH anchors the botanical-specialist position through chicory root inulin concentration and associated prebiotic health claim substantiation.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| BENEO GmbH |
| Roquette Frères |
| Kerry Group plc |
| DuPont de Nemours Inc. |
| Nexira |
| Others |
Value Network & Pricing Analysis
Chicory root supply concentration in northern Belgium and the Netherlands determines both pricing tier spreads and supply chain shape, as processors face weather-driven crop volatility that compresses margins on inulin derivatives while forcing diversification into microbial fermentation alternatives. FDA 21 CFR 101.9 qualification requirements add regulatory chokepoint risk, bifurcating the market between clinically substantiated premium grades and commodity fiber streams that compete primarily on cost.
Pricing Analysis
Cost-plus contracts with corn and wheat futures indexation dominate soluble fiber procurement, linking processor margins to agricultural commodity swings. Price differentiation rests on clinical dossier depth and FDA qualification status, with pharmaceutical-grade psyllium commanding substantial premiums over food-grade alternatives. Pricing pressure stems from precision fermentation scale-up narrowing the cost gap between plant-derived and microbially produced fibers. Large CPG manufacturers exhibit lowest price sensitivity due to clean-label positioning requirements, while private-label retailers drive hardest bargain negotiations.
Supply Chain Analysis
Export-control regimes on enzymatic extraction technology limit technology transfer to second-tier manufacturers, concentrating advanced processing capability among established Western suppliers. Raw material flows draw from Belgian chicory cultivation, United States corn belt harvests, and Indian psyllium farming regions. Supply chain risk centers on single-source dependency for inulin raw material where northern Belgian zones control 70% of global output. Distribution runs through direct specification partnerships between ingredient suppliers and CPG R&D teams, displacing traditional distributor mediation in North American clean-label segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The edible fiber market sits at early-cycle expansion driven by FDA-added sugar disclosure thresholds accelerating soluble fiber incorporation across reformulated beverage and bakery portfolios. Functional health claim substantiation remains underpenetrated relative to addressable food and beverage applications.
For Market Incumbents: Build clinical dossier moats through randomized controlled trials with biomarker endpoints that satisfy EFSA's tightened health claim substantiation requirements. Defend margin positions by securing captive supply partnerships with major CPG brand R&D teams in Chicago and Minneapolis-St. Paul clusters, while investing in precision fermentation capacity to offset chicory root supply volatility. For New Entrants and Emerging Players: Establish a beachhead in India FSSAI fiber fortification compliance services, where proposed minimum fiber content thresholds for packaged foods create first-mover advantages for local blending operations. Target clean-label bakery applications where insoluble wheat fiber with modified particle size displaces methylcellulose in gluten-free formulations. Pursue enzymatic technology licensing agreements to bypass capital-intensive extraction infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors clinical-trial-capable specialists over commodity processors. Long-term viability hinges on regulatory qualification depth rather than scale alone. Acquisition targets should demonstrate EFSA or FDA dossier completion for specific digestive health claims. Watch for EFSA pending opinions on resistant starch as inflection indicator unlocking label permissions across European functional dairy.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Investment | Randomized controlled trials with biomarker endpoints satisfy EFSA's tightened health claim substantiation framework. |
| Precision Fermentation Scale-Up | Microbial cellulose production via bacterial fermentation opens synthetic biology pathways independent of agricultural feedstocks. |
| Direct Specification Partnership | Exclusive R&D relationships with CPG brands compress formulation cycle times and lock out distributor competitors. |
| Backward Integration into Chicory Cultivation | Captive agricultural supply in Belgian zones mitigates weather-driven raw material volatility exposure. |
| Enzymatic Technology Licensing | Continuous processing technology transfer enables second-tier manufacturer entry into beta-glucan extraction markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR filings, EFSA health claim opinions, and customs trade data covering chicory root and psyllium husk flows. Primary interviews engaged ingredient procurement managers at CPG manufacturers, extraction plant technical directors, regulatory affairs specialists navigating qualification pathways, and clinical research coordinators managing digestive health trials. Secondary sources included FSSAI draft fortification guidelines, BfR novel fiber safety assessments, and SEC 10-K disclosures from diversified grain processors. Bottom-up demand modeling triangulated against top-down supply capacity estimates.
Forecast inputs incorporate soluble versus insoluble fiber segmentation, food and beverage versus pharmaceutical application splits, powder versus capsule form factors, and customer archetype differentiation across health-conscious individuals and medical patients. CAGRs derive from annualized growth rate calculations across the projection horizon. Industry-specific variables include EFSA opinion timelines, FDA qualification success rates, and precision fermentation cost curves.
Stress conditions across chicory root yield volatility, resistant dextrin substitution rates, and clinical trial failure frequencies were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory approval trajectories and technology adoption curves. Material shifts in FDA dietary fiber definition interpretation or EFSA health claim evidentiary requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United States Wheat Protein Market
Ingredients
All Purpose Flour Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Mirepoix Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
South America Clean Ingredients Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Sugared Egg Yolk Market
Ingredients
Camelina Oil Market
Ingredients
Corn Oil Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Halal Ingredients Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Palm Mid-Fraction Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Organic Edible Oil Market