
 Europe Feed Yeast Market | 2026-2036
Europe Feed Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Yeast Market Foresight
EU Green Deal is rebalancing capital allocation across the Europe feed yeast value chain by embedding climate-performance criteria into subsidy eligibility and procurement standards. Lesaffre leverages its century-old fermentation infrastructure to sustain cost advantages in live yeast propagation across French and Belgian facilities. ADM anchors its position through backward integration into molasses sourcing and grain processing networks spanning Eastern Europe. Lallemand Inc. competes on specialized ruminant and aquaculture strains, differentiating its catalog through documented rumen pH stabilization and gut microbiome modulation outcomes.
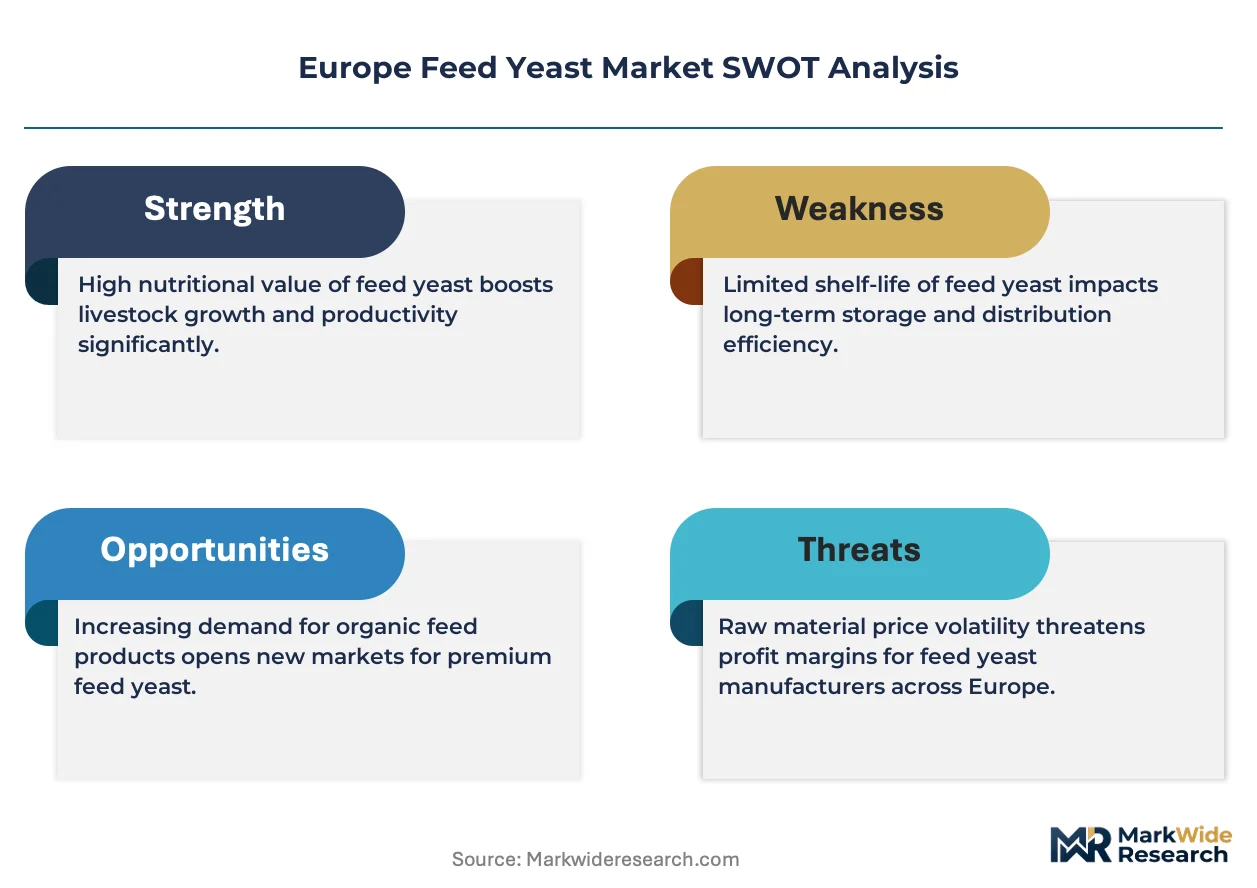
Feed yeast comprises Saccharomyces cerevisiae and related species cultivated on molasses or grain substrates, then processed as live active cultures, killed whole cells, or extracted cell-wall fractions rich in mannan-oligosaccharides and beta-glucans; manufacturers typically achieve viable counts between 10 billion and 200 billion CFU per gram depending on strain and drying protocol, with primary purpose centered on improving feed conversion ratios, supporting immune function, and stabilizing gastrointestinal flora in production animals. Yeast derivatives command margin concentration due to their higher processing intensity and premium positioning in antibiotic-free and organic feed programs, while aquaculture feed represents the fastest-expanding feed type as salmon and shrimp producers in Norway and Scotland adopt yeast-based alternatives to fishmeal protein. Inactive yeast retains volume leadership across poultry and swine applications where cost-sensitive compound feed manufacturers prioritize consistent supply over live-cell functionality.
EMA and EFSA jointly govern feed additive safety assessments through the centralized EU Register of Feed Additives, with ECHA's REACH protocols extending to yeast production chemicals and processing aids, creating a multi-layered compliance architecture that favors established players with dedicated regulatory affairs teams. The EU F-Gas Regulation and national ammonia emission ceilings in the Netherlands and Denmark further shape product development priorities by rewarding yeast applications that demonstrate measurable nitrogen excretion reduction in livestock operations. Stakeholders must monitor how the EU Deforestation Regulation reshapes molasses and grain substrate sourcing requirements, as traceability mandates could disqualify yeast fermented on non-compliant feedstock origins.
Market Dynamics
EU Green Deal implementation is compressing feed additive approval timelines while embedding climate-performance criteria directly into subsidy eligibility, forcing manufacturers to restructure R&D pipelines around documented sustainability outcomes rather than traditional efficacy metrics alone.
Growth Catalysts
- Enteric methane reduction mandates:The EU F-Gas Regulation and national ammonia emission ceilings in the Netherlands and Denmark reward yeast applications demonstrating measurable nitrogen excretion reduction in dairy and beef operations.
- Antibiotic-free feed transition:Poultry and swine producers across Germany and France are expanding yeast inclusion rates to stabilize gastrointestinal flora without antimicrobial growth promoters.
- Aquaculture protein substitution:Salmon and shrimp producers in Norway and Scotland are adopting yeast-based alternatives to fishmeal protein, accelerating demand for specialized fermentation-derived ingredients.
Market Restraints
- Molasses supply concentration:Yeast substrate sourcing depends on captive sugar beet and cane processing networks concentrated in Eastern European agricultural zones, exposing margins to harvest volatility.
- EFSA approval bottlenecks:The centralized EU Register of Feed Additives imposes multi-year safety assessment timelines that freeze product launches and strain working capital for mid-scale manufacturers.
- Enzyme and probiotic substitution:Direct-fed microbials and phytase enzymes compete for the same gut-health positioning in compound feed formulations, compressing yeast price premiums in cost-sensitive swine applications.
Strategic Opportunities
- Organic certification expansion:The EU Farm to Fork Strategy is tightening organic livestock standards, opening premium positioning for yeast derivatives in certified antibiotic-free and organic feed programs.
- Rumen pH stabilization specialization:Dairy cooperatives in Germany and the Netherlands are contracting for custom Saccharomyces cerevisiae strains with documented fiber digestibility outcomes, creating service-based revenue streams beyond commodity yeast sales.
- Blockchain-enabled traceability:The EU Deforestation Regulation is forcing substrate provenance documentation, rewarding early adopters of digital supply chain verification with preferred supplier status from multinational feed compounders.
Industry Challenges
- Regulatory affairs talent scarcity:The multi-layered compliance architecture spanning EMA, EFSA, and ECHA REACH protocols requires specialized scientific and legal expertise that mid-cap yeast manufacturers struggle to recruit and retain.
- Live-cell viability maintenance:Achieving stable counts between 10 billion and 200 billion CFU per gram through drying protocols demands capital-intensive fermentation infrastructure upgrades that strain balance sheets.
- Cross-border strain registration:Divergent national interpretations of EU-wide feed additive approvals create friction when deploying identical yeast products across German, French, and Dutch operational territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Yeast Market |
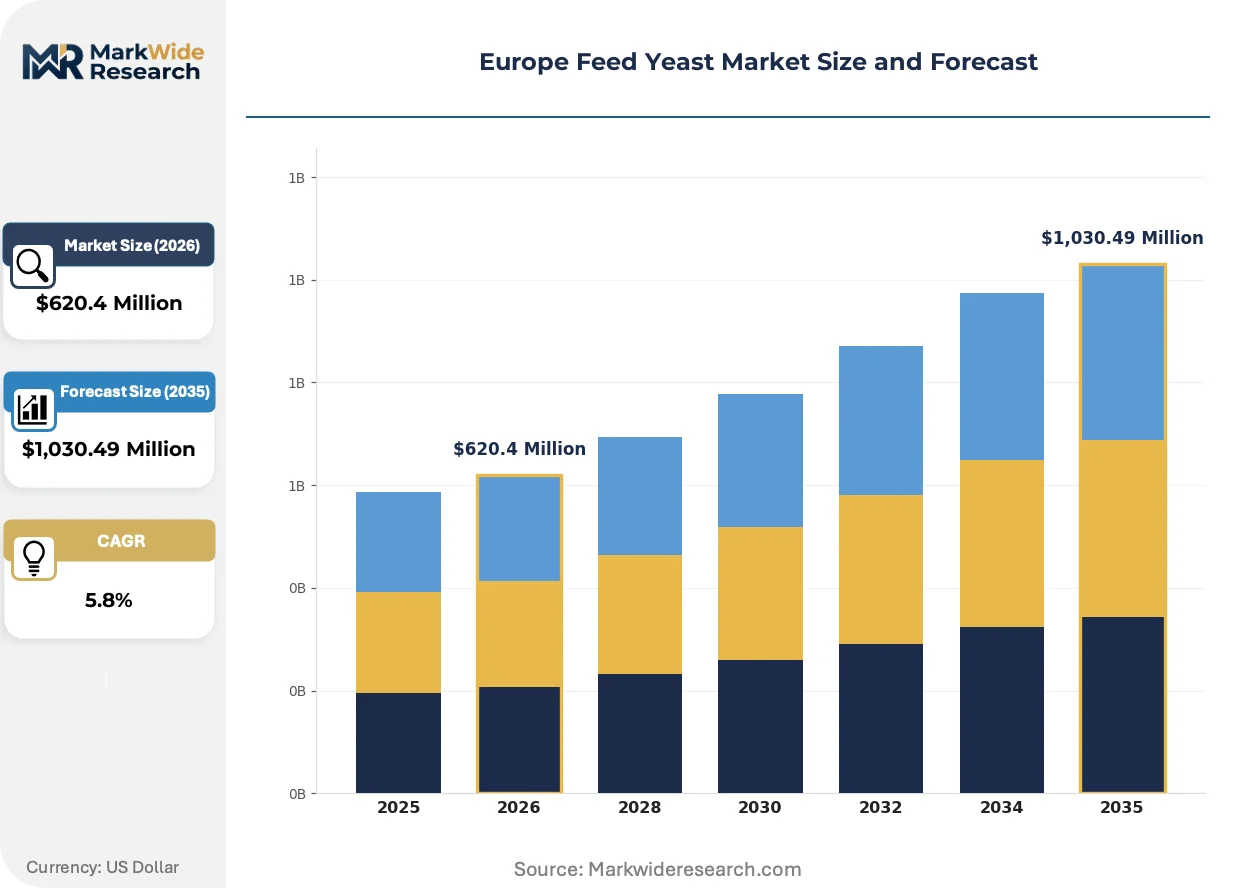
| Market Size in 2026 | $620.4 Million |
| Market Size in 2035 | $1,030.49 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Yeast, Inactive Yeast, Yeast Derivatives, Nutritional Yeast Feed Type: Poultry Feed, Ruminant Feed, Aquaculture Feed, Swine Feed Application: Dietary Supplement, Fermentation Aid, Enzyme Production, Probiotic Supplement Distribution Channel: Online Retail, Offline Retail, Wholesalers, Direct Sales |
| Companies Covered | Alltech, Inc., ADM, Associated British Foods plc, Cargill Inc., DSM-Firmenich, Lesaffre, Lallemand Inc., Leiber GmbH, Chr. Hansen Holding A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Yeast Market Shifts & Advancements
Live-cell propagation technology is advancing alongside precision fermentation analytics, enabling manufacturers to tailor yeast strain functionality to specific ruminant, poultry, and aquaculture microbiome outcomes rather than selling undifferentiated commodity cultures.
Continuous bioprocessing technology is integrating real-time metabolite monitoring with automated nutrient feeding systems to maintain optimal yeast cell viability throughout fermentation. Large-scale dairy cooperatives in Germany are adopting these systems to secure consistent rumen pH stabilization performance across seasonal feed variations. The technology is compressing batch-to-batch variability and reducing rejection rates from quality-sensitive compound feed manufacturers.
REACH protocols governing yeast production chemicals are extending compliance obligations to processing aids and cleaning agents used in fermentation facilities. Manufacturers must now document substance safety across the entire production chain, not just final feed additive formulations. French and Belgian facilities are responding by consolidating supplier relationships and pre-qualifying chemical inputs against ECHA substance databases.
Compound feed manufacturers are consolidating procurement volumes through long-term offtake agreements with single-source yeast suppliers, displacing spot-market purchasing and multi-vendor qualification programs. This concentration pattern is most visible in the Netherlands, where industrial pig operations and large-scale poultry integrators are locking in three-to-five-year supply contracts to secure price stability and dedicated technical support services.
Europe Feed Yeast Market Segmentation
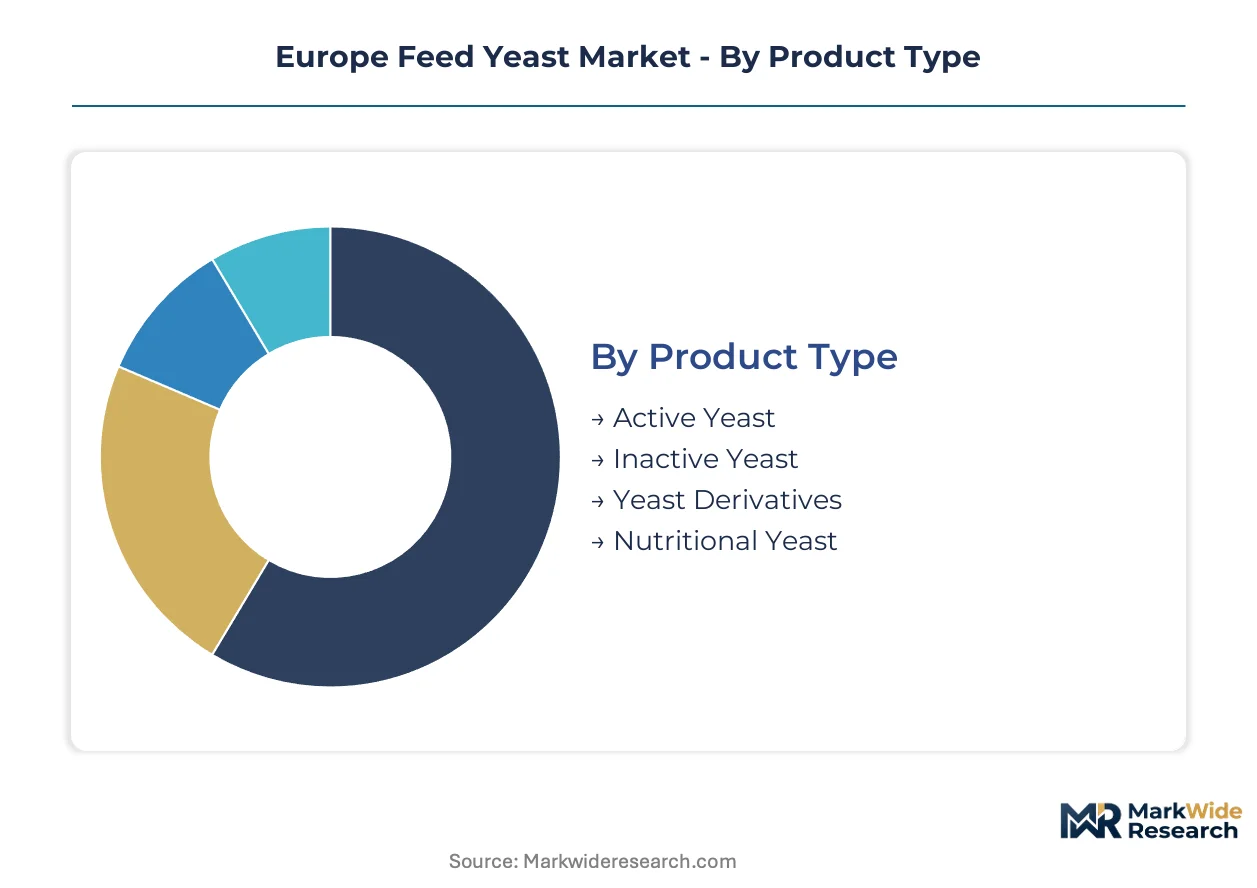
Feed yeast manufacturers structure product portfolios around fermentation state, animal physiology, and functional claims to capture value across divergent buyer requirements. Segmentation discipline separates commodity volume plays from premium positioning in regulated European markets.
Product Type:
Live-cell viability and processing intensity define the technology hierarchy from active cultures to extracted fractions.
- Active Yeast:Live Saccharomyces cerevisiae cultures maintained at 10-200 billion CFU per gram through controlled drying protocols. Demand concentrates in German dairy cooperatives seeking documented rumen pH stabilization during high-starch feeding periods.
- Inactive Yeast:Heat-killed whole cells retaining cell-wall integrity and nutritional protein content. Poultry and swine compound feed manufacturers across France and the Netherlands prioritize this segment for cost-sensitive antibiotic-free formulations.
- Yeast Derivatives:Purified cell-wall fractions rich in mannan-oligosaccharides and beta-glucans extracted through mechanical and enzymatic processing. Organic certification programs in Denmark and Austria drive premium uptake.
- Nutritional Yeast:Dried inactive yeast fortified with B-vitamin complexes and selenium for specialty feed applications. Niche positioning in equine and pet nutrition segments across Belgium and Switzerland.
Mature deployment sits with Inactive Yeast. Newer deployment is concentrated in Yeast Derivatives.
Feed Type:
Animal physiology and digestive system complexity determine strain selection and inclusion rate economics.
- Ruminant Feed:Specialized Saccharomyces cerevisiae strains targeting fiber digestibility and enteric methane suppression. Dutch and Danish beef operations under F-Gas Regulation compliance pressure anchor volume demand.
- Aquaculture Feed:Fermentation-derived protein fractions substituting for fishmeal in salmon and shrimp diets. Norwegian and Scottish producers expanding marine yeast inclusion rates fastest.
- Poultry Feed:Gut flora stabilization applications replacing antimicrobial growth promoters in German and French broiler operations. EFSA-approved strains dominate procurement specifications.
- Swine Feed:Post-weaning diarrhea prevention through yeast cell-wall binding of pathogenic bacteria. Industrial pig integrators in the Netherlands consolidate procurement through multi-year supply contracts.
Volume concentration remains with Ruminant Feed. Steepest expansion trajectory belongs to Aquaculture Feed.
Application:
Functional claims separate commodity feed ingredients from regulated additive categories with documented efficacy requirements.
- Probiotic Supplement:Live yeast cultures qualifying under EU Register of Feed Additives with dossier-submitted safety and efficacy data. German compounders demand strain-specific rumen microbiome modulation documentation.
- Dietary Supplement:Nutritional yeast applications emphasizing B-vitamin and protein content without live-cell functionality claims. Organic livestock programs across Austria and Italy absorb premium volumes.
- Fermentation Aid:Yeast derivatives accelerating silage preservation and aerobic stability. French dairy cooperatives integrate these products into seasonal forage management protocols.
- Enzyme Production:Yeast biomass as fermentation substrate for exogenous enzyme manufacturing. Eastern European grain processors backward-integrate into captive yeast production.
Regulatory complexity concentrates in Probiotic Supplement. Price compression pressure is strongest in Fermentation Aid.
Distribution Channel:
Buyer scale and technical service requirements shape channel selection across fragmented and consolidated customer bases.
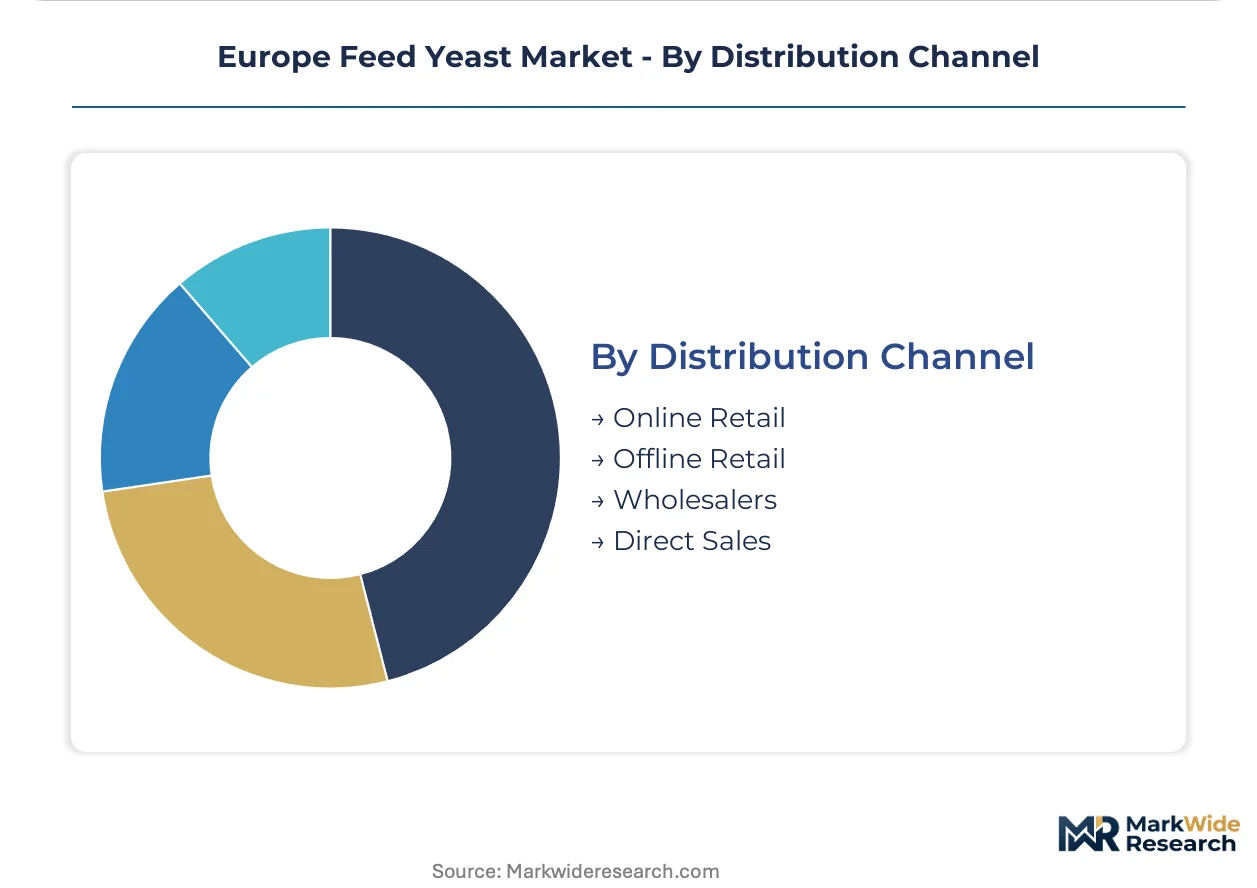
- Direct Sales:Manufacturer-to-compounder relationships with embedded technical support and custom strain development. Large Dutch poultry integrators and German dairy cooperatives lock in three-to-five-year offtake agreements.
- Wholesalers:Regional distributors aggregating demand from mid-scale independent feed mills across Poland, Hungary, and Romania. Inventory pooling reduces working capital strain for smaller compounders.
- Offline Retail:Agricultural supply cooperatives and farm service centers serving livestock producers in France, Spain, and Italy. Seasonal purchasing patterns align with breeding and fattening cycles.
- Online Retail:E-commerce platforms targeting smallholder and specialty livestock producers with packaged yeast supplements. Traceability documentation requirements under EU Deforestation Regulation constrain substrate sourcing transparency.
Margin capture concentrates in Direct Sales. Channel development investment is flowing toward Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux special economic zones for bio-based manufacturing concentrate fermentation capacity near Antwerp and Rotterdam port complexes. German and French tax incentives for circular economy investments pull substrate processing into Rhine-Ruhr and Grand Est corridors. Dutch ammonia emission trading schemes accelerate yeast adoption in livestock-dense provinces.
Germany
Dairy cooperatives in Lower Saxony and Bavaria expand live yeast contracts for rumen pH stabilization during high-starch feeding periods. The F-Gas Regulation mandates documented enteric methane reduction in beef operations. Industrial pig integrators around Münsterland lock in multi-year supply agreements with compound feed manufacturers.
Netherlands
Poultry and swine operations in Gelderland and North Brabant consolidate procurement through three-to-five-year offtake contracts. National ammonia emission ceilings under EU Nitrates Directive reward yeast applications demonstrating nitrogen excretion reduction. Feed compounders in the Randstad cluster embed technical support services into direct sales relationships.
France
Beef producers in Brittany and Normandy adopt specialized Saccharomyces cerevisiae strains for fiber digestibility improvement. The EU Farm to Fork Strategy tightens organic livestock certification standards, opening premium positioning for yeast derivatives. Grand Est fermentation facilities leverage century-old infrastructure for cost advantages in live yeast propagation.
Denmark
Dairy operations under strict national ammonia caps integrate yeast into seasonal forage management protocols. EFSA approval requirements for probiotic feed additives concentrate regulatory expertise in Copenhagen-based manufacturer offices. Organic certification programs in Jutland absorb premium volumes of mannan-oligosaccharide fractions.
Norway
Salmon and trout producers along the Norwegian coast accelerate marine yeast inclusion rates as fishmeal protein substitutes. Aquaculture feed manufacturers near Bergen and Trondheim contract for specialized fermentation-derived ingredients. National sustainability mandates for aquaculture operations reward documented gut microbiome modulation outcomes.
Europe Feed Yeast Market Competitive Landscape
French and Belgian producers anchor one tier through captive fermentation infrastructure; German and Dutch specialists hold differentiated positions in custom strain development. The vendor base separates into three archetypes: diversified nutrition conglomerates with backward-integrated substrate networks, dedicated yeast propagators with century-old fermentation expertise, and mid-scale regional compounders serving national feed markets. Consolidation pressure manifests through long-term offtake agreements displacing spot purchasing, while capacity expansion concentrates in port-proximate facilities for molasses logistics optimization.
Within the diversified nutrition tier, ADM and DSM-Firmenich represent integrated players with upstream control over grain processing and substrate sourcing networks spanning Eastern Europe. Lesaffre exemplifies the dedicated fermentation specialist archetype, leveraging Belgian and French facility bases. Lallemand Inc. occupies a position emphasizing documented rumen microbiome outcomes and aquaculture strain specialization. These three anchors illustrate how competitive positioning separates substrate-integrated conglomerates from functionality-focused propagators.
| Leading Market Players |
|---|
| Alltech, Inc. |
| ADM |
| Associated British Foods plc |
| Cargill Inc. |
| DSM-Firmenich |
| Lesaffre |
| Lallemand Inc. |
| Leiber GmbH |
| Chr. Hansen Holding A/S |
| Others |
Supply & Pricing Matrix
Continuous bioprocessing technology adoption is compressing batch-to-batch variability costs while simultaneously concentrating production capacity in port-proximate Belgian and Dutch facilities. This dual shift rewards manufacturers with legacy fermentation infrastructure and penalizes mid-scale competitors facing capital-intensive viability maintenance requirements.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Dutch poultry integrators and German dairy cooperatives lock in three-to-five-year offtake agreements with dedicated technical support. Contract-based long-term offtake structures separate premium live-cell products from spot-market inactive yeast, with price differentiation driven by EFSA certification tier and volume scale. Cost compression in inactive yeast runs through Eastern European compound feed manufacturers prioritizing consistent supply over live-cell functionality. Industrial pig operations in the Netherlands exhibit highest price sensitivity, while organic-certified yeast derivatives in Denmark command sustained premium positioning.
Supply Chain Analysis
Regional distribution centers near Antwerp and Rotterdam port complexes anchor hub-and-spoke patterns serving compound feed manufacturers across Germany, France, and the Netherlands. Raw material dependencies draw from molasses networks concentrated in Eastern European sugar beet zones, grain substrates from Rhine-Ruhr processing corridors, and specialized nutrient formulations from Belgian chemical suppliers. Single-source vulnerability in molasses sourcing exposes margins to harvest volatility and EU Deforestation Regulation traceability mandates. Distribution runs through direct manufacturer-to-compounder relationships for large integrators, with wholesaler channels pooling mid-scale demand across Poland, Hungary, and Romania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe feed yeast market functions as a vertical-integration race where substrate control and regulatory dossier depth determine sustainable margin capture. Players are pursuing backward integration into molasses and grain processing networks as the decisive downstream lever.
For Market Incumbents: Deploy captive fermentation infrastructure upgrades to maintain live-cell viability advantages against probiotic and enzyme substitutes threatening gut-health positioning. Consolidate supplier relationships against REACH protocol extensions to processing aids, while securing EFSA-approved strain registrations ahead of national interpretation divergences across German, French, and Dutch territories. For New Entrants and Emerging Players: The premium-to-economy price-point gap in organic-certified yeast derivatives offers accessible white-space targeting for mid-scale regional compounders. Aquaculture feed applications in Norway and Scotland present the most penetrable segment given fishmeal substitution mandates. Pursue blockchain-enabled substrate traceability as a differentiated go-to-market angle under EU Deforestation Regulation compliance pressure. For Investors and Strategic Acquirers: Re-rating potential sits with dedicated fermentation specialists possessing century-old facility bases given EFSA approval bottleneck constraints on new capacity. Long-term viability over a five-to-ten-year window favors archetypes with established regulatory affairs teams and port-proximate logistics advantages. Monitor ammonia emission trading scheme expansions across livestock-dense jurisdictions as the inflection indicator for yeast adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Networks | Molasses and grain sourcing control secures margin stability against EU Deforestation Regulation traceability mandates. |
| EFSA Dossier Investment for Live-Cell Strains | Regulatory approval pathways freeze competitor launches and create multi-year competitive moats in probiotic segments. |
| Port-Proximate Capacity Expansion | Antwerp and Rotterdam logistics optimization reduces working capital strain from molasses inventory holding costs. |
| Blockchain Supply Chain Verification | Digital provenance documentation unlocks preferred supplier status from multinational feed compounders under tightening sustainability standards. |
| Custom Strain Development Services | Service-based revenue streams beyond commodity yeast sales deepen relationships with German dairy cooperatives seeking documented rumen pH outcomes. |
Research Methodology
Document review covered EFSA feed additive registrations, EU customs trade data, and REACH substance databases, complemented by interviews with fermentation plant managers, regulatory affairs specialists at feed additive manufacturers, procurement leads at Dutch poultry integrators, and technical directors at German dairy cooperatives. Bottom-up volume modeling triangulated against top-down value estimates derived from compound feed production statistics and yeast inclusion rate assumptions.
Segment-level outputs across the projection horizon reflect fermentation state, animal physiology, and functional claim dimensions, with CAGRs derived from elasticity-adjusted adoption curves and regulatory timeline impacts. Modeled inputs incorporated F-Gas Regulation compliance trajectories, ammonia emission ceiling trajectories in livestock-dense provinces, and aquaculture protein substitution elasticity estimates for Norwegian salmon operations.
Inputs from EFSA submission databases and national feed industry associations were available through the study window; gaps in real-time molasses inventory pricing and confidential contract terms introduce uncertainty bands around margin structure assumptions. Forecasts reflect documented regulatory timelines and stated technology adoption assumptions; decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Isoamyl Laurate Market
Ingredients
Baobab Ingredient Market
Ingredients
Ingredients Market
Ingredients
Potato Granules Market
Ingredients
Hydrolyzed Animal Protein Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Tapioca Pearls Market
Ingredients
Apple Extract Market
Ingredients
Bean Flour Market
Ingredients
Zero-Calorie Oil Market
Ingredients
Stock Cubes Market
Ingredients
Gluten-Free Flour Market
Ingredients
Marine Ingredients Market
Ingredients
Global Malt Ingredients Market
Ingredients
Coconut Cream Powder Market
Ingredients
Black Seed Oil Market