
 Heart Health Ingredients Market | 2026-2036
Heart Health Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Health Ingredients Market Analysis
Functional food applications is shifting toward fortified dairy and bakery matrices as CPG brands reformulate for cardiovascular positioning. BASF SE leverages its Algalin algal omega-3 platform to anchor supply security for plant-based DHA demands. Kerry Group plc differentiates through taste-masked microencapsulation systems that sustain clean-label claims in beverage applications. Aker BioMarine competes via Antarctic krill oil traceability, controlling vertical supply from catch to capsule.
Heart health ingredients comprise bioactive compounds—omega-3 fatty acids, phytosterols, coenzyme Q10, and soluble fibers—delivered at standardized potencies typically ranging from 500 mg to 2 g per serving unit, manufactured through cold-press extraction, fermentation, or molecular distillation processes to preserve oxidative stability and bioavailability. These ingredients function as preventive nutritional interventions targeting lipid metabolism, endothelial function, and inflammatory modulation in consumer products and clinical nutrition protocols. Omega-3 fatty acids occupy the largest value pool due to EPA/DHA efficacy documentation, while phytosterols represent the fastest-growing category as EFSA-approved cholesterol-reduction claims drive European functional food integration. Dietary supplements dominate application value, though sports nutrition exhibits accelerated growth as endurance athletes adopt heart-rate-variability optimization protocols.
FDA New Dietary Ingredient notifications, EFSA health claim evaluations under Regulation (EC) 1924/2006, and WHO cardiovascular disease prevention guidelines collectively elevate clinical substantiation requirements above commodity ingredient standards. The EU Green Deal's Farm to Fork strategy further pressures sustainable sourcing credentials for marine-derived omega-3 supply chains. Stakeholders must monitor evolving pharmacovigilance frameworks that could reclassify certain bioactives as novel foods or borderline pharmaceuticals, fundamentally altering market access pathways and investment horizons.
Market Dynamics
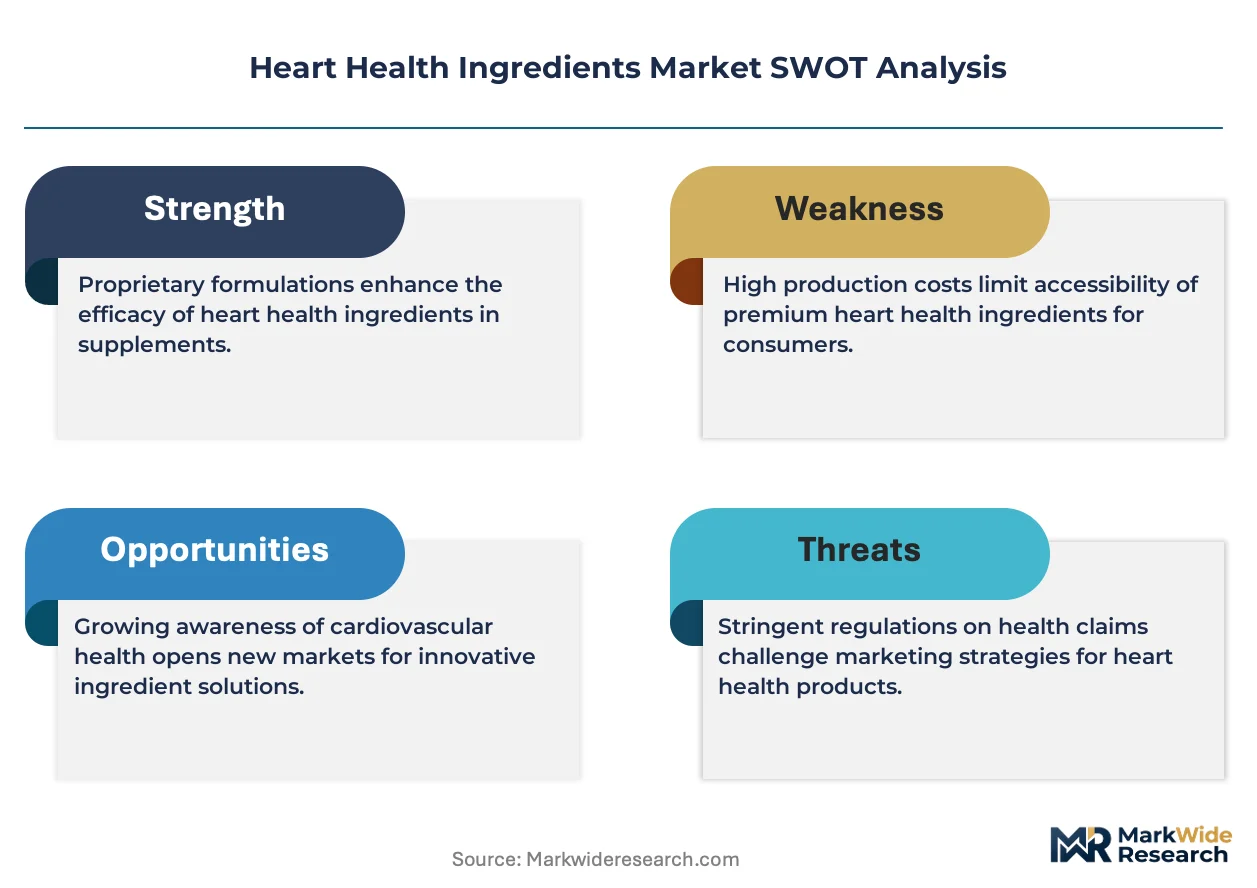
Clinically validated bioactive procurement is tightening supply chains as dietary supplement manufacturers demand EFSA-compliant substantiation dossiers for cholesterol-reduction and endothelial-function claims, compressing formulation timelines and elevating ingredient qualification costs.
Growth Catalysts
- EFSA Health Claim Authorization:Approved phytosterol cholesterol-reduction claims under Regulation (EC) 1924/2006 accelerate functional food integration across European bakery and dairy matrices.
- Endurance Sports Nutrition:Heart-rate-variability optimization protocols among triathletes and marathon runners expand omega-3 and CoQ10 demand beyond traditional cardiovascular risk populations.
- German Pharmacy-Channel Embeddedness:Preventive care routines structurally anchor supplement sales through Apotheken, creating stable demand pull for clinically positioned bioactives.
Market Restraints
- Marine-Derived Omega-3 Supply Concentration:Antarctic krill and Peruvian anchovy fisheries face climate volatility and quota restrictions that constrain EPA/DHA raw material security.
- FDA New Dietary Ingredient Notification Burden:Pre-market safety documentation requirements extend ingredient commercialization timelines by 12-18 months for novel bioactive formats.
- Algal DHA Production Cost Structure:Fermentation-based DHA from Schizochytrium strains carries 40-60% cost premiums versus fish oil equivalents, limiting mass-market penetration.
Strategic Opportunities
- Plant-Based DHA White Space:Algal omega-3 platforms address vegan and allergen-free positioning gaps in infant formula and maternal nutrition segments.
- Taste-Masked Microencapsulation:Clean-label beverage applications unlock functional drink categories previously inaccessible to oxidation-sensitive marine lipids.
- EU Green Deal Farm to Fork Alignment:Sustainable sourcing credentials for marine ingredients become procurement gatekeepers as retailer ESG mandates harden.
Industry Challenges
- Novel Food Reclassification Risk:Pharmacovigilance frameworks in Germany and France threaten to recategorize certain bioactives as borderline pharmaceuticals, disrupting market access pathways.
- Oxidative Stability Expertise Gap:Molecular distillation and cold-press extraction process engineering talent scarcity constrains manufacturer scale-up capabilities for high-potency omega-3 concentrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Health Ingredients Market |
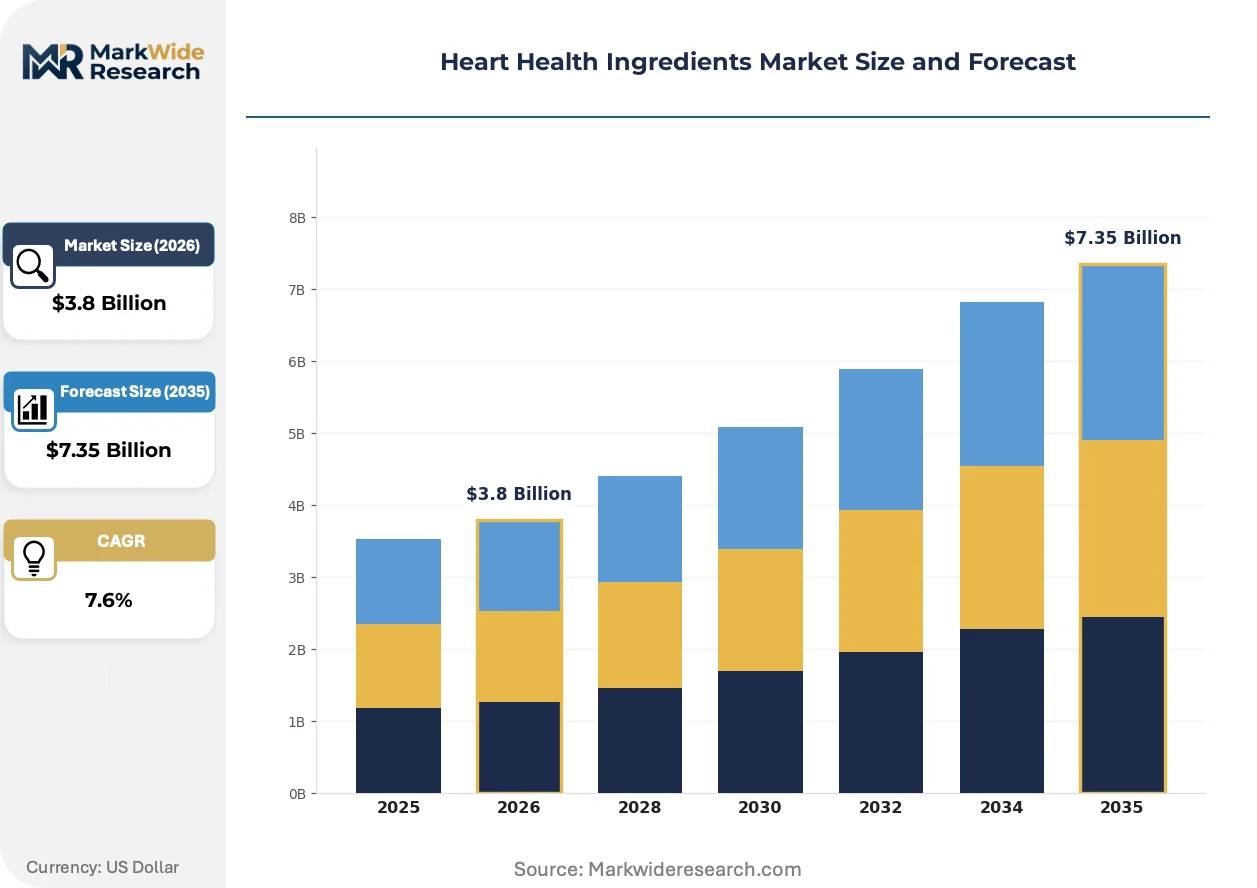
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omega-3 Fatty Acids, Phytosterols, Coenzyme Q10, Fiber Application: Dietary Supplements, Functional Foods, Beverages, Sports Nutrition End User: Consumers, Hospitals, Fitness Centers, Nutraceutical Companies Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Pharmacies |
| Companies Covered | BASF SE, Cargill Incorporated, Archer Daniels Midland Company, Kerry Group plc, DSM-Firmenich AG, DuPont de Nemours, Aker BioMarine, Nestlé Health Science, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Health Ingredients Market Emerging Trajectories
Formulation science is converging with traceability infrastructure to reshape competitive differentiation, as clean-label imperatives collide with clinical substantiation requirements across multiple delivery formats.
Algal fermentation technology is unifying sustainable sourcing with supply security for DHA production. Infant formula manufacturers in the Netherlands and Germany are adopting algal-derived lipids at accelerated procurement cycles. This convergence is compressing reliance on wild-capture marine fisheries while enabling vegan positioning claims previously impossible in pediatric nutrition.
EFSA's evolving guidance on Article 13.1 health claims is tightening evidentiary standards for cholesterol-reduction and blood-pressure positioning. Functional food brands now commission randomized controlled trials exceeding 200 participants to secure 14-month authorization timelines. German and French bakery CPGs are responding by consolidating supplier relationships with dossier-complete phytosterol providers.
Pharmacy-channel consolidation is redirecting preventive cardiovascular purchasing through digital consultation platforms. German Apotheken now integrate telehealth screening with personalized supplement recommendations, displacing traditional OTC self-selection. This channel evolution concentrates demand pull among clinically validated ingredient portfolios with pharmacist-education support infrastructure.
Heart Health Ingredients Market Segmentation
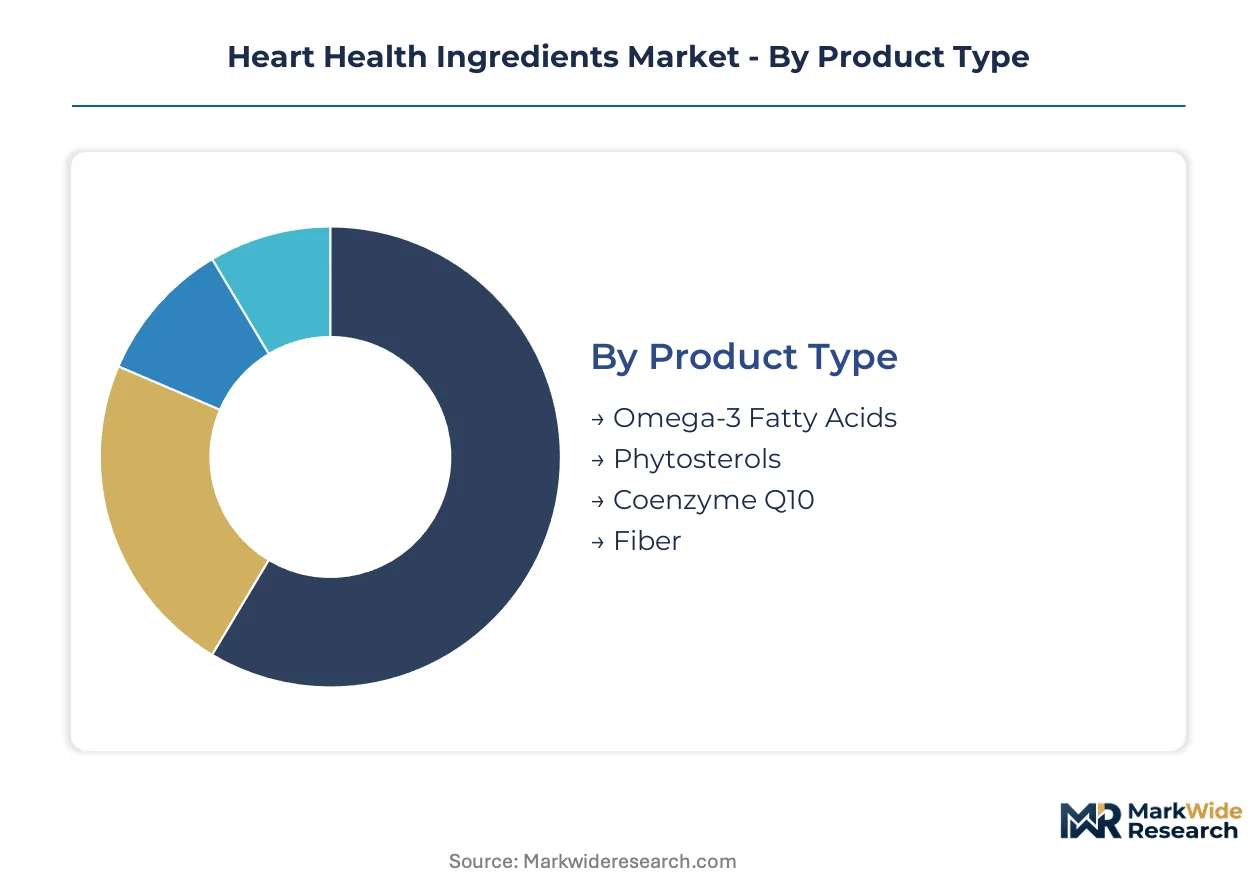
Ingredient manufacturers configure production assets around bioactive potency tiers and regulatory qualification burdens. Segment boundaries harden where EFSA health claim substantiation requirements create divergent investment thresholds between commodity and clinical-grade supply.
Product Type:
Capital deployment concentrates in fermentation infrastructure and molecular distillation capacity, with algal DHA platforms commanding the steepest upfront outlays.
- Omega-3 Fatty Acids:EPA and DHA concentrates manufactured through cold-press extraction or algal fermentation deliver standardized potencies from 500 mg to 2 g per serving. Demand clusters in German infant formula and maternal nutrition applications where vegan positioning commands procurement premiums.
- Phytosterols:Plant-derived sterols and stanols reduce intestinal cholesterol absorption through competitive inhibition mechanisms. EFSA-approved Article 14 claims accelerate functional food integration across French and German bakery matrices, compressing supplier qualification timelines.
- Coenzyme Q10:Lipid-soluble antioxidant synthesized via microbial fermentation supports mitochondrial ATP production in cardiac tissue.
- Fiber:Soluble beta-glucan and psyllium fractions modulate lipid metabolism through bile acid binding.
Most installed capacity flows through Omega-3 Fatty Acids. Expansion is steepest in Phytosterols.
Application:
Formulation complexity and oxidation stability requirements segment manufacturing capabilities across delivery formats.
- Dietary Supplements:Softgel, capsule, and tablet formats dominate value capture through pharmacy-channel distribution in Germany. Clinically validated bioactives with EFSA-compliant dossiers anchor preventive care purchasing routines.
- Functional Foods:Fortified dairy, bakery, and spreads matrices integrate phytosterols and omega-3 emulsions. Taste-masked microencapsulation from Kerry Group plc and similar suppliers unlocks clean-label beverage positioning previously inaccessible to marine lipids.
- Beverages:Ready-to-drink formats require advanced stabilization against lipid oxidation and sensory degradation.
- Sports Nutrition:Endurance athletes adopt heart-rate-variability optimization protocols, expanding CoQ10 and omega-3 demand beyond traditional cardiovascular risk populations.
Volume leadership sits with Dietary Supplements. Functional Foods is climbing the fastest as CPG brands reformulate for cardiovascular positioning.
End User:
Procurement sophistication varies sharply across customer types, from self-directed consumer purchasing to institutional specification requirements.
- Consumers:Direct purchasing through pharmacy and digital channels concentrates demand for clinically positioned bioactives with pharmacist-education support. German Apotheken telehealth integration redirects preventive cardiovascular purchasing toward validated portfolios.
- Hospitals:Clinical nutrition protocols specify standardized potencies for perioperative cardiac support and lipid management.
- Fitness Centers:Sports nutrition distribution partnerships target endurance athlete segments with heart-rate-variability optimization products.
- Nutraceutical Companies:Contract manufacturers demand EFSA-compliant substantiation dossiers, compressing supplier qualification to dossier-complete providers.
Consumer channels absorb the largest volume. Nutraceutical Companies show the steepest expansion trajectory as outsourcing concentrates.
Distribution Channel:
Channel economics fragment between high-touch pharmacy consultation and automated digital fulfillment.
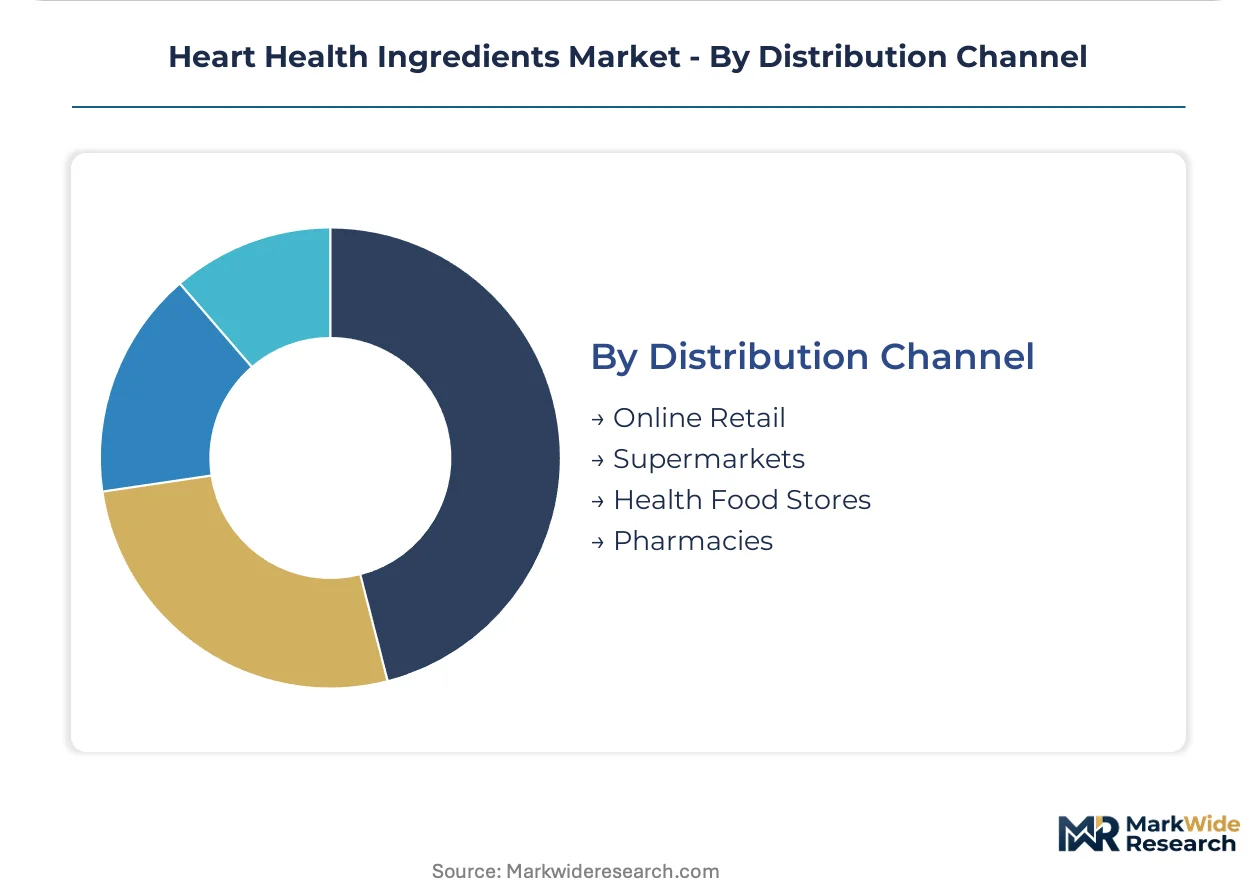
- Pharmacies:German Apotheken structurally embed preventive supplement sales through pharmacist consultation, creating stable demand pull for clinically validated ingredients. Digital consultation platforms now integrate telehealth screening with personalized recommendations.
- Online Retail:Direct-to-consumer platforms bypass traditional OTC self-selection with subscription models and algorithmic personalization.
- Supermarkets:Mass-market functional food placement depends on EFSA claim authorization for cholesterol-reduction positioning.
- Health Food Stores:Specialty retailers target vegan and allergen-free positioning gaps with algal omega-3 and plant-based formulations.
Pharmacies retain the deepest installed channel capacity. Online Retail is expanding most quickly as digital health integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmacy-channel infrastructure anchors European demand for clinically validated heart health bioactives, with Apotheken networks structurally embedding preventive supplement sales into routine care. Regulatory frameworks across multiple jurisdictions reshape procurement patterns and formulation strategies.
Germany
Apotheken telehealth integration redirects cardiovascular purchasing toward validated portfolios with pharmacist-education support. EFSA Article 14 health claim authorization under Regulation (EC) 1924/2006 compresses supplier qualification timelines for phytosterol providers. The Baden-Württemberg cluster concentrates fermentation infrastructure for CoQ10 and algal DHA production serving infant formula manufacturers.
United States
FDA New Dietary Ingredient notification requirements extend commercialization timelines for novel bioactive formats by 12-18 months. The agency's pre-market safety documentation burdens elevate ingredient qualification costs above commodity standards. Greater Boston anchors clinical research infrastructure supporting randomized controlled trials for cholesterol-reduction substantiation dossiers.
Netherlands
Infant formula manufacturers accelerate procurement cycles for algal-derived lipids enabling vegan positioning claims. The EU Green Deal Farm to Fork strategy pressures sustainable sourcing credentials for marine-derived omega-3 supply chains. The Randstad region concentrates taste-masked microencapsulation expertise for clean-label beverage applications.
China
SAMR novel food registration pathways govern algal DHA and phytosterol market access for functional food integration. Dual carbon goals accelerate fermentation-based production investments as alternatives to wild-capture fisheries. The Yangtze River Delta hosts expanding molecular distillation capacity for high-potency omega-3 concentrates.
France
ANSM pharmacovigilance frameworks threaten reclassification of certain bioactives as borderline pharmaceuticals, disrupting market access. EFSA guidance tightening evidentiary standards for Article 13.1 health claims drives bakery CPG consolidation around dossier-complete suppliers. The Île-de-France region anchors clinical nutrition protocol specification for perioperative cardiac support applications.
Heart Health Ingredients Market Vendor Landscape
Capacity expansion dominates the current landscape as fermentation infrastructure and molecular distillation assets attract capital deployment. The vendor base organizes around three strategic archetypes: diversified chemical conglomerates with algal platforms, specialized marine lipid harvesters controlling vertical supply chains, and ingredient technology providers with microencapsulation expertise. Competitive moves concentrate in backward integration into raw material security and technology licensing for oxidation-stable delivery formats.
Within the diversified chemical tier, BASF SE and DSM-Firmenich AG exemplify integrated bioactive platforms spanning omega-3 fermentation and phytosterol extraction. Kerry Group plc occupies a position among taste-masked delivery specialists enabling clean-label beverage applications previously inaccessible to marine lipids. Aker BioMarine represents the traceability-focused archetype with Antarctic krill supply chain control from catch to finished ingredient.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Kerry Group plc |
| DSM-Firmenich AG |
| DuPont de Nemours |
| Aker BioMarine |
| Nestlé Health Science |
| Tate & Lyle |
| Others |
Supply Flow & Price Mechanics
Fermentation energy costs for Schizochytrium-based DHA production cascade through three distinct pricing tiers, with algal platforms commanding 40-60% premiums over Peruvian anchovy-derived equivalents as German infant formula manufacturers absorb vegan positioning premiums.
Pricing Analysis
Pharmacy-channel margins in German Apotheken networks compress net-back pricing for ingredient suppliers while securing volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-dossier-complete phytosterol providers from commodity omega-3 traders. Cost compression in algal DHA is intensifying because fermentation scale-up investments outpace demand absorption. Mass-market functional food buyers exhibit highest price sensitivity; clinical nutrition procurement shows lowest elasticity due to protocol specification requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Nestlé Health Science and DSM-Firmenich AG formulation partnerships. Raw material security draws from Antarctic krill fisheries, Peruvian anchovy catches, and Schizochytrium fermentation tanks in Germany and the Netherlands. Marine lipid oxidation sensitivity creates single-source vulnerability around molecular distillation expertise concentrated in the Randstad region. Distribution runs through pharmacy wholesale cooperatives and CPG ingredient brokers serving bakery and dairy reformulation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA Article 14 health claim authorization under Regulation (EC) 1924/2006 functions as a regulatory compounder, with approved cholesterol-reduction claims accelerating phytosterol procurement cycles across French and German functional food manufacturers.
For Market Incumbents: To counter algal DHA cost compression from fermentation overcapacity, BASF SE and DSM-Firmenich AG should deepen backward integration into Schizochytrium strain development while locking long-term offtake agreements with Baden-Württemberg production facilities. Certification investment in EU Green Deal Farm to Fork alignment secures retailer ESG procurement gatekeeper status. For New Entrants and Emerging Players: Launch via Dutch infant formula OEM partnerships exploiting vegan positioning gaps in maternal nutrition segments. Taste-masked microencapsulation for clean-label beverage applications represents the most penetrable white space, with sports nutrition heart-rate-variability products offering secondary entry via fitness center distribution. For Investors and Strategic Acquirers: Roll-up economics work for specialized marine lipid harvesters because Antarctic krill quota restrictions create captive supply scarcity that rewards vertical control from catch to capsule. Long-term viability hinges on pharmacovigilance framework monitoring in Germany and France as borderline pharmaceutical reclassification risk. Watch ANSM regulatory guidance shifts as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Dossier Completion | Article 14 cholesterol-reduction claims compress supplier qualification timelines to 14 months for bakery CPGs. |
| Algal Fermentation Scale-Up | Schizochytrium capacity expansion in Baden-Württemberg reduces wild-capture fishery dependence for vegan positioning. |
| Pharmacy Channel Integration | Telehealth screening platforms in German Apotheken redirect preventive cardiovascular purchasing toward validated portfolios. |
| Taste-Masked Microencapsulation | Kerry Group plc delivery systems unlock clean-label beverage categories previously inaccessible to oxidation-sensitive marine lipids. |
| Antarctic Krill Traceability | Aker BioMarine vertical supply chain control from catch to capsule addresses EU Green Deal sustainable sourcing mandates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, EFSA regulatory affairs leads, German Apotheken procurement directors, and infant formula R&D heads with secondary validation through EFSA Article 13.1 and 14.1 health claim registers, EU customs trade data for omega-3 concentrates, and SEC filings from diversified chemical conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Comparable-period anchoring used historical phytosterol authorization timelines and algal DHA procurement cycle data to calibrate projection coefficients across the analysis window. Segmentation dimensions modeled include bioactive potency tier, EFSA dossier completeness status, delivery format oxidation stability requirements, and pharmacy versus mass-market channel mix. CAGRs derived from segment-level growth rate synthesis incorporating infant formula vegan transition velocity and sports nutrition adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pharmacovigilance reclassification events or Antarctic krill quota restrictions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Beverage Ingredients Market
Ingredients
Asia-Pacific Soy Protein Market
Ingredients
Potato Granules Market
Ingredients
South America Clean Ingredients Market
Ingredients
Baobab Powder Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
South America Fats and Oil Market
Ingredients
Olive Leaf Extract Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
Proteose Peptone Market
Ingredients
Functional Flours Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Food Minerals Market
Ingredients
Mexico Avocado Oil Market
Ingredients
South America Soy Protein Ingredients Market