
 Oat Fiber Market | 2026-2036
Oat Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Oat Fiber Market Outlook
Ingredient-as-a-service contracting is restructuring how oat fiber moves from mill to finished goods manufacturer. Cargill Incorporated leverages its grain origination network to secure supply continuity across North American processing facilities. Swedish Oat Fiber AB anchors premium positioning through specialized beta-glucan concentrates for nutraceutical customers. J. Rettenmaier & Söhne GmbH + Co KG competes on technical milling expertise, supplying customized particle-size distributions to European bakery formulators.
Oat fiber consists of the insoluble and soluble polysaccharide matrix extracted from oat hulls and bran, typically containing 85-95% total dietary fiber with variable beta-glucan content depending on source grain and processing intensity. Manufacturers employ mechanical separation, grinding, and air-classification to achieve target fiber concentrations for use as a texturizing agent, moisture binder, and calorie reducer across food systems. Sifted fiber leads volume shipments due to its compatibility with standard bakery equipment and clean-label positioning, while instant fiber represents the fastest-expanding category as beverage manufacturers seek rapid-hydration ingredients for ready-to-drink applications. Powder form dominates current procurement patterns, though flake and granule formats are gaining traction in snack and cereal applications where visual texture differentiation commands shelf-space premiums.
The FDA's Nutrition Facts labeling rules define isolated and synthetic non-digestible carbohydrates as dietary fiber only when accompanied by physiological benefits, compelling suppliers to substantiate health claims through clinical evidence. EFSA's health claim evaluation framework in Europe imposes similar evidentiary thresholds for beta-glucan cholesterol-reduction messaging, filtering market access to firms with validated study portfolios. USDA organic certification and Non-GMO Project verification further stratify supplier tiers, with certified product commanding sustained price premiums in North American retail channels. Stakeholders must monitor evolving fiber-definition rulings across FDA and EFSA jurisdictions to anticipate reformulation mandates and qualification barriers before contract renewal cycles.
Market Dynamics
The FDA's updated dietary fiber definition under Nutrition Facts labeling rules is forcing suppliers to rebuild qualification documentation around physiological benefit substantiation, compressing contract renewal cycles and elevating clinical evidence requirements.
Growth Catalysts
- Clean-label bakery reformulation:Food manufacturers are replacing modified starches with oat fiber to meet consumer transparency demands while maintaining moisture retention and texture profiles in commercial-scale production.
- EFSA beta-glucan health claims:Validated cholesterol-reduction messaging creates regulatory-backed differentiation for concentrated fiber ingredients in European nutraceutical applications.
- Upper Midwest processing cluster:Minnesota-based oat milling infrastructure provides supply continuity advantages for North American contract manufacturers seeking qualified ingredient sources.
Market Restraints
- Oat hull input cost volatility:Weather-driven grain yield fluctuations and biofuel diversion pressures create margin compression for mechanical separation processors.
- Supply concentration in Nordic beta-glucan specialists:Limited qualified suppliers for high-purity concentrates create qualification bottlenecks and contract negotiation leverage asymmetries.
- Psyllium husk substitution threat:Established digestive health positioning and lower price points in supplement applications divert formulator attention from oat-derived alternatives.
Strategic Opportunities
- Ready-to-drink beverage hydration:Instant fiber's rapid-dissolution properties address formulation gaps in functional drink systems where visual clarity and mouthfeel consistency command premium positioning.
- USDA organic certification arbitrage:Certified product commands sustained price premiums in North American retail channels as conventional supply commoditizes.
- Snack and cereal visual texture differentiation:Flake and granule formats create shelf-space premiums through physical form innovation rather than chemical modification.
Industry Challenges
- Clinical evidence generation timelines:FDA and EFSA physiological benefit requirements demand multi-year study investments that strain mid-tier supplier R&D budgets.
- Legacy equipment compatibility gaps:Standard bakery processing lines require particle-size distribution customization that extends technical service engagements and delays volume ramp.
- Cross-jurisdictional qualification fragmentation:Divergent fiber definition rulings between FDA and EFSA create dual-track compliance costs for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat Fiber Market |
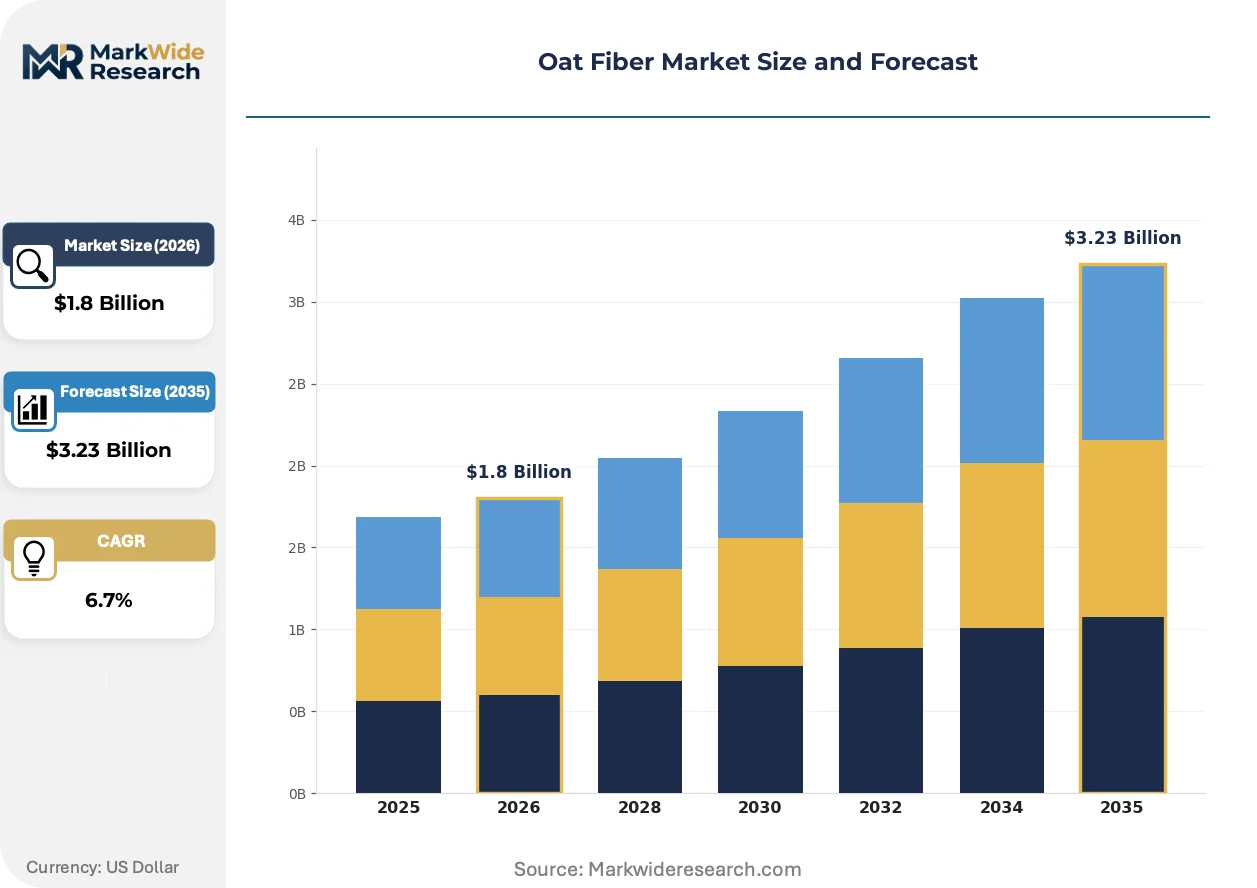
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sifted Fiber, Whole Fiber, Granulated Fiber, Instant Fiber End Use Industry: Bakery, Snacks, Beverages, Nutraceuticals Form: Powder, Flakes, Granules, Pellets Packaging Type: Bulk Bags, Sachets, Boxes, Canisters |
| Companies Covered | Tate & Lyle PLC, Cargill Incorporated, DuPont de Nemours Inc., Roquette Frères, Grain Millers Inc., SunOpta Inc., Avena Foods Limited, J. Rettenmaier & Söhne GmbH + Co KG, Swedish Oat Fiber AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat Fiber Market Strategic Shifts
Ingredient-as-a-service contracting is restructuring procurement relationships between oat fiber suppliers and finished goods manufacturers, embedding technical support and formulation collaboration into long-term supply agreements.
Air-classification milling technology is consolidating quality control across North American processing facilities. Multi-stage grinding and particle separation systems enable precise fiber concentration targeting for specific end-use applications. Bakery formulators are adopting these customized distributions to reduce reformulation iterations and accelerate product launch timelines.
EFSA's health claim evaluation framework is tightening evidentiary standards for beta-glucan cholesterol-reduction messaging. European suppliers must maintain validated study portfolios to retain market access, filtering participation to firms with sustained clinical investment capacity. Nutraceutical contract manufacturers are prioritizing qualified European sources to preempt regulatory disqualification risks.
Buyer concentration among multinational food manufacturers is compressing supplier switching cycles. Procurement teams are consolidating qualified vendor lists and demanding integrated technical service packages that span formulation support, regulatory documentation, and supply continuity guarantees. This pattern is most visible in United States bakery and snack applications where clean-label mandates have accelerated ingredient qualification velocity.
Oat Fiber Market Segmentation
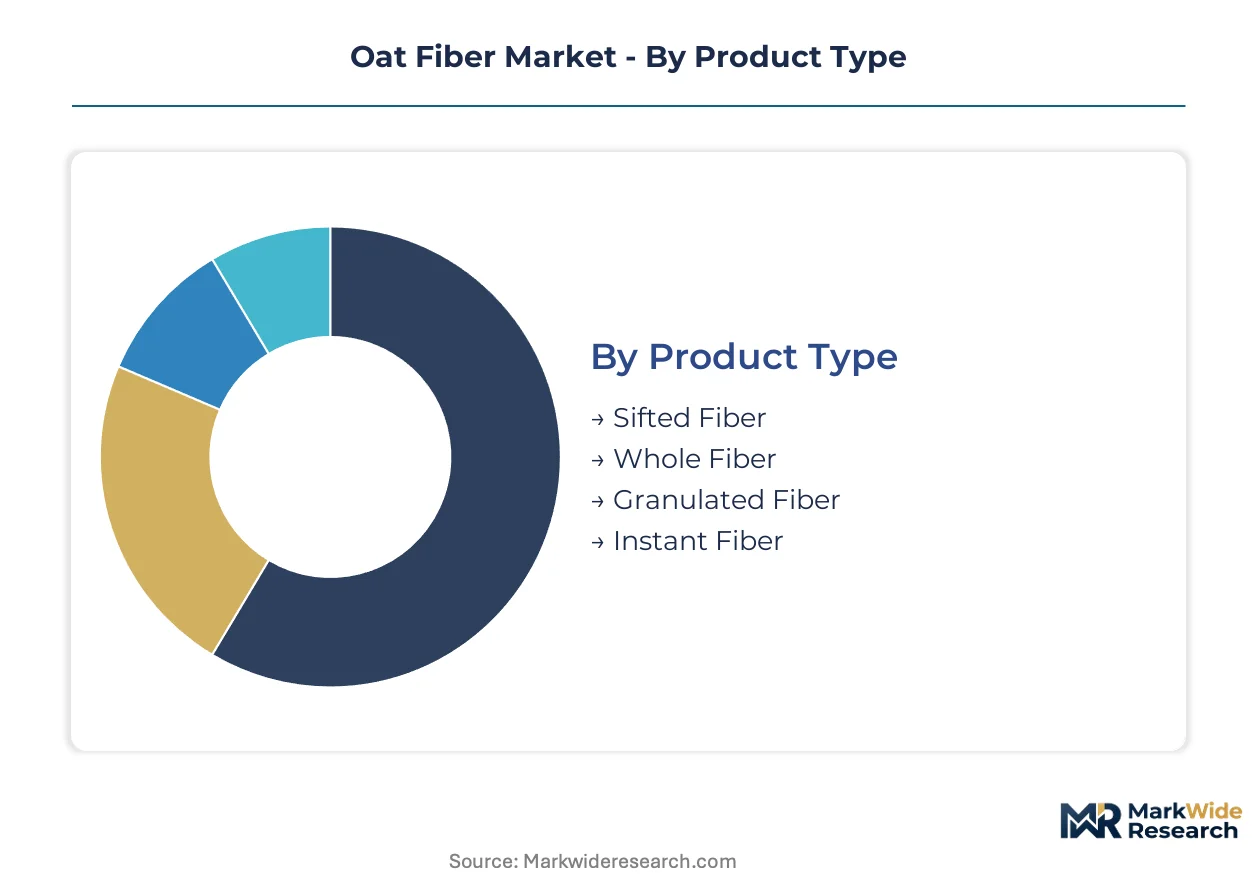
Oat fiber procurement decisions hinge on hydration kinetics, equipment compatibility, and clean-label positioning. Manufacturers segment demand across particle morphology, dissolution speed, and packaging scale to match specific formulation constraints.
Product Type:
Formulators prioritize hydration behavior and fiber concentration purity when selecting oat fiber grades for commercial-scale production.
- Sifted Fiber:Mechanically separated and air-classified to achieve uniform particle-size distributions between 80-200 microns. Bakery manufacturers in Minnesota processing clusters specify sifted grades for seamless integration into standard dough systems without equipment modification.
- Instant Fiber:Agglomerated or pre-gelatinized particles engineered for rapid cold-water dispersion. Beverage formulators seeking visual clarity in ready-to-drink applications specify instant grades to eliminate sedimentation and mouthfeel defects.
- Whole Fiber:Minimally processed hull and bran matrix retaining native structural integrity. Nutraceutical capsule manufacturers specify whole fiber for sustained-release formulations targeting digestive health positioning.
- Granulated Fiber:Roller-compacted particles with controlled density for direct-compression tableting. Supplement producers specify granulated grades to improve flow properties in high-speed encapsulation lines.
Volume sits with sifted fiber; growth tilts toward instant fiber.
End Use Industry:
Application-specific functional requirements determine fiber specification, particle engineering, and certification thresholds.
- Bakery:Moisture retention and crumb structure modification drive specification of medium-fiber concentrates in bread and pastry systems. Clean-label reformulation mandates across US retail channels are displacing modified starches with oat-derived alternatives.
- Nutraceuticals:Beta-glucan concentrates exceeding 30% purity command premium positioning for cholesterol-reduction claims under EFSA evaluation frameworks. Swedish and Finnish suppliers anchor supply concentration for validated clinical portfolios.
- Snacks:Extruded and puffed applications leverage oat fiber for caloric reduction and structural integrity. Savory snack manufacturers specify coarse fractions to maintain expansion ratios during high-shear processing.
- Beverages:Suspension stability and clarity specifications favor instantized or micro-milled grades. Functional drink brands specify cold-soluble fibers to avoid heat-processing steps that degrade heat-labile actives.
Revenue concentrates in bakery; nutraceuticals climb the fastest.
Form:
Physical morphology dictates handling characteristics, dosing precision, and visual differentiation opportunities.
- Powder:Dominant procurement format due to metering accuracy in automated batching systems and uniform dispersion in dry blends. Powder specifications span bulk density ranges from 0.3-0.6 g/cm³ to match pneumatic conveying infrastructure.
- Flakes:Visual texture differentiation commands shelf-space premiums in breakfast cereal and granola applications. Cereal manufacturers specify flake geometry to enhance bowl appearance and crunch retention in milk.
- Granules:Intermediate particle size reduces dusting during handling while maintaining rapid hydration kinetics. Snack seasoning applications specify granulated grades for adhesion to oil-coated surfaces.
- Pellets:Densified form for high-volume bulk shipment and reduced storage footprint. Ingredient distributors specify pellets for efficient container loading in export logistics to Asian contract manufacturers.
Procurement weight rests with powder; flake formats gain share fastest.
Packaging Type:
Scale economics and contamination control requirements shape container specification across supply chain tiers.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate ingredient-manufacturer procurement for production-scale bakery and snack operations. Minnesota milling clusters ship bulk bags to North American contract manufacturers on scheduled replenishment contracts.
- Sachets:Single-serve pouches address convenience positioning in direct-to-consumer nutraceutical channels. E-commerce brands specify sachet formats for portion-controlled subscription models.
- Boxes:Corrugated retail packaging for club-store and specialty grocery distribution. Organic-certified products command box specifications with tamper-evident closures for retail channel compliance.
- Canisters:Rigid packaging for countertop visibility in health-food retail. Nutraceutical brands specify canister formats with moisture-barrier properties to preserve beta-glucan potency through shelf life.
Shipment volume aggregates in bulk bags; canister formats expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American oat fiber processing through its concentration of grain milling infrastructure and proximity to Canadian oat supply corridors. The upper Midwest corridor dominates qualified ingredient output for US contract manufacturers.
United States
Clean-label bakery reformulation drives specification velocity across Minnesota and Wisconsin processing clusters. The FDA's updated dietary fiber definition under Nutrition Facts labeling rules compels suppliers to rebuild qualification documentation with physiological benefit substantiation. Minneapolis-St. Paul hosts the densest concentration of mechanical separation facilities serving North American contract manufacturers.
Sweden
Beta-glucan concentrate demand from nutraceutical formulators concentrates procurement attention on Nordic suppliers. EFSA's health claim evaluation framework filters market access to firms with validated cholesterol-reduction study portfolios. Stockholm-based specialists anchor premium positioning through clinical evidence-backed ingredient portfolios.
Germany
Technical milling expertise for customized particle-size distributions commands formulator loyalty in European bakery applications. REACH compliance requirements and EFSA fiber definition alignment create dual-track qualification barriers for imported ingredients. Bavarian processing facilities specialize in air-classification systems for precise fiber concentration targeting.
Canada
Organic oat production in Saskatchewan and Manitoba feeds certified-ingredient demand premiums in North American retail channels. The country's national food regulator maintains alignment with FDA fiber definition standards to facilitate cross-border supply continuity. Winnipeg serves as the primary collection point for organic oat hulls entering US processing facilities.
France
Extruded snack applications in the Auvergne-Rhône-Alpes region leverage oat fiber for caloric reduction and structural integrity. ANSM oversight of novel food ingredient safety creates pre-market consultation requirements for concentrated fiber launches. Lyon-based flavor houses integrate fiber specifications into savory seasoning systems for export to Mediterranean markets.
Oat Fiber Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the oat fiber supply base. The market structure tilts toward consolidation at the premium tier while commodity grades fragment across regional millers. Three archetypes dominate: integrated grain processors with origination networks, specialized beta-glucan concentrate refiners, and technical milling service providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification requirements compress contract renewal cycles.
Among integrated grain processors, Cargill Incorporated exemplifies the capital-heavy archetype through its North American origination infrastructure. Swedish Oat Fiber AB and J. Rettenmaier & Söhne GmbH + Co KG occupy positions within the specialization tier, with the former representing Nordic beta-glucan concentrate capabilities and the latter anchoring German technical milling expertise. These three firms illustrate the geographic and capability stratification that defines supplier qualification hierarchies.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Cargill Incorporated |
| DuPont de Nemours Inc. |
| Roquette Frères |
| Grain Millers Inc. |
| SunOpta Inc. |
| Avena Foods Limited |
| J. Rettenmaier & Söhne GmbH + Co KG |
| Swedish Oat Fiber AB |
| Others |
Value Chain & Pricing Dynamics
Oat hull input costs transmit directly from Saskatchewan grain elevators through Minnesota milling clusters to finished goods manufacturers, with weather-driven yield volatility compressing margins at mechanical separation processors while concentrating pricing power among Nordic beta-glucan specialists.
Pricing Analysis
Yield-linked pricing anchors contract structures, with beta-glucan concentration purity commanding premium tiers against standard dietary fiber grades. Price differentiation rests on USDA organic certification and EFSA-validated health claim portfolios, with certified product sustaining double-digit premiums over conventional supply. Cost compression in commodity sifted fiber intensifies because biofuel diversion pressures and grain yield fluctuations squeeze mechanical separation margins. Mid-tier bakery manufacturers exhibit highest price sensitivity, while nutraceutical formulators prioritize clinical evidence over unit economics.
Supply Chain Analysis
Skilled milling technicians in Minnesota, Bavaria, and southern Sweden constrain capacity expansion at air-classification facilities. Raw material flows draw from Canadian prairie oat production, Nordic grain cooperatives, and upper Midwest elevator networks. Single-source vulnerability concentrates in high-purity beta-glucan concentrate supply, where Swedish and Finnish specialists control validated clinical portfolios. Distribution runs through bulk flexible intermediate bulk containers to North American contract manufacturers, with scheduled replenishment contracts locking in qualified vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical evidence generation capacity bottlenecks prop pricing asymmetries, with FDA and EFSA qualification timelines filtering supplier participation to firms with sustained multi-year study investments.
For Market Incumbents: Anticipate psyllium husk substitution threats in supplement applications by deepening beta-glucan concentrate differentiation through cholesterol-reduction claim validation. Secure backward integration into Canadian organic oat origination to defend margin position against commodity grade price erosion. For New Entrants and Emerging Players: Launch via direct-to-consumer sachet distribution in nutraceutical channels, exploiting underpenetrated instant fiber demand in ready-to-drink beverage systems where rapid cold-water dispersion creates formulation value. Target USDA organic certification arbitrage in North American retail channels. For Investors and Strategic Acquirers: EFSA health claim disqualification events are the leading indicator that clinical evidence portfolios will stratify acquisition values across Nordic specialist targets. Five-to-ten year viability hinges on regulatory qualification durability rather than capacity scale. Watch for FDA fiber definition ruling divergence as the signal for dual-track compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Oat Origination | Captures Saskatchewan and Manitoba supply premiums while securing USDA certification continuity. |
| Clinical Evidence Portfolio Expansion | Locks EFSA cholesterol-reduction claim access against Nordic competitor disqualification risks. |
| Instant Fiber Capacity Addition | Addresses beverage manufacturer demand for rapid-hydration ingredients with visual clarity specifications. |
| Air-Classification Milling Technology Upgrade | Enables precise particle-size distribution customization for bakery equipment compatibility. |
| Long-Term Supply Agreement with Contract Manufacturers | Embeds technical service and formulation collaboration into ingredient-as-a-service procurement structures. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among grain origination managers, bakery formulation scientists, nutraceutical procurement directors, and mechanical separation plant engineers. FDA guidance documents, EFSA health claim evaluations, USDA organic certification databases, and North American oat milling association production statistics provided validation cross-checks. Bottom-up volume modeling triangulated against top-down value estimates across ingredient grade tiers.
Reconciliation of production volume disclosures, import-export flows, and end-use consumption patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include fiber concentration purity, hydration kinetics, particle morphology, end-use application, and geographic regulatory cluster. CAGRs derived from trend extrapolation of clean-label reformulation velocity and functional beverage launch pipelines, with oat hull supply elasticity and beta-glucan clinical study publication rates serving as industry-specific forecast inputs.
Regulatory ruling divergence, grain yield volatility events, and substitute fiber technology advances are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around FDA and EFSA fiber definition stability. Material deviation in qualification timelines or health claim evidentiary standards warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
China Protein Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Agar Market
Ingredients
North America Potato Starch Market
Ingredients
Europe Protein Market
Ingredients
Peanut Flour Market
Ingredients
France Soy Protein Market
Ingredients
Coconut Cream Powder Market
Ingredients
Rose Hips Extract Market
Ingredients
Fats and Oils Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Refined Coconut Oil Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Pomegranate Peel Polyphenol Complex Market
Ingredients
Terminalia Extract Market
Ingredients
Protein Trends and Technologies Market