
 North America Vegetable Oils Market | 2026-2036
North America Vegetable Oils Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vegetable Oils Market Intelligence
Direct procurement from large-scale food manufacturers is reshaping the competitive positioning among vegetable oil processors in North America. This shift favors vertically integrated giants like Archer Daniels Midland Company, which controls extensive crushing and refining infrastructure. Cargill Incorporated leverages its global logistics network to secure supply contracts, while Bunge Limited competes on specialized oil formulations for industrial food clients.
North American vegetable oils are lipids extracted from plant sources, primarily seeds, nuts, or fruits. These oils are defined by their fatty acid composition and are processed through methods like crushing and solvent extraction to meet specific functional requirements for food and industrial uses. Soybean oil continues to dominate the market by volume, driven by its use in food processing. However, canola oil and its application in biodiesel production represent the fastest-growing segments.
Regulatory oversight in North America is stringent, with the US Food and Drug Administration (FDA) setting standards for food-grade oils and the USDA managing organic certifications. In Canada, Health Canada imposes strict labeling requirements for allergens and nutritional content, shaping product formulation. Navigating the evolving standards for renewable fuels and food labeling will be critical for processors to maintain market access.
Market Dynamics
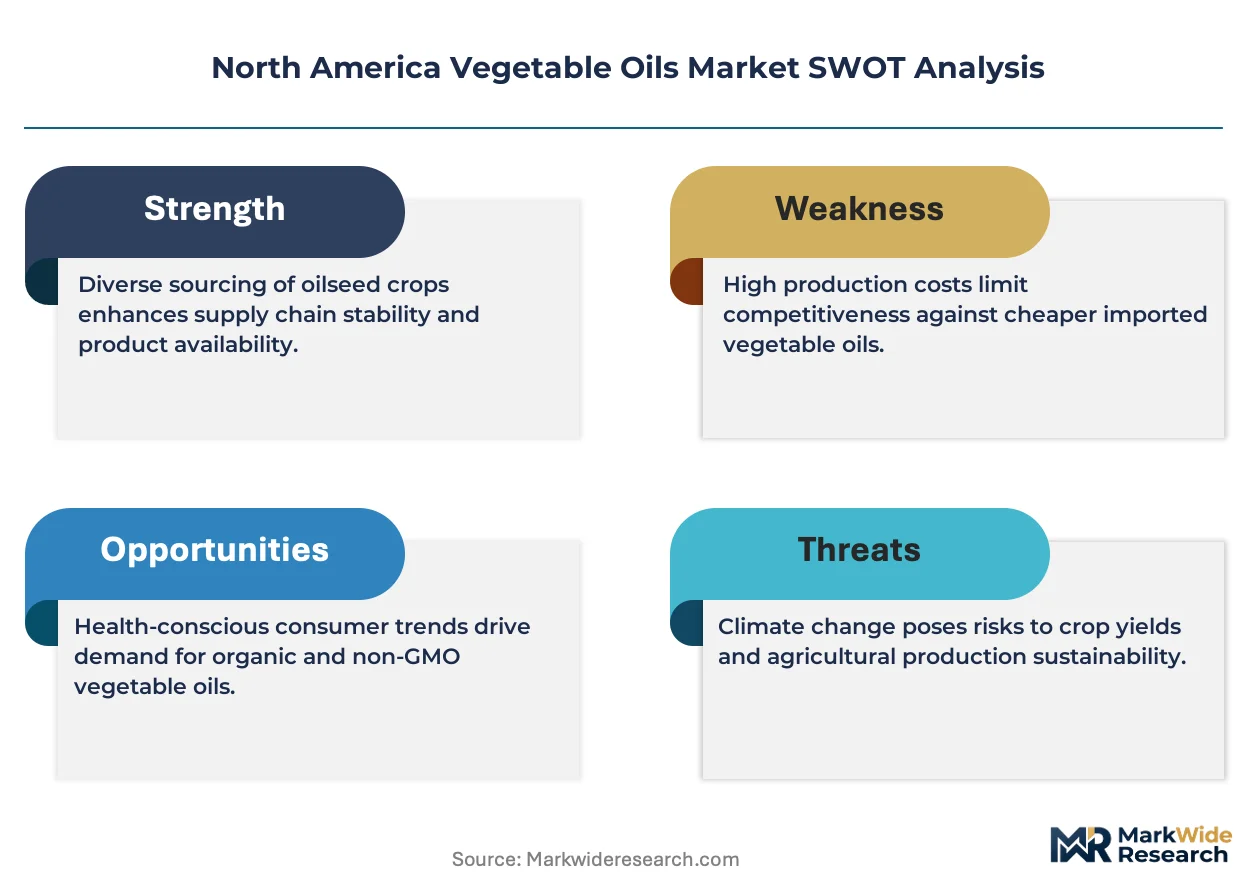
The North American vegetable oils market is shaped by the structural tension between its dual roles as a food ingredient and an industrial feedstock. Mandates for renewable fuels create a baseline demand for commodity oils, while consumer preferences for healthier, sustainably sourced products drive investment in specialized oil processing.
Growth Catalysts
- Biofuel Mandates:The US Renewable Fuel Standard (RFS) program requires the blending of biofuels into the national transportation fuel supply, creating consistent, large-scale demand for feedstocks like soybean and corn oil.
- Clean-Label Food Production:Demand from food manufacturers for non-GMO, organic, and expeller-pressed oils is expanding as consumers scrutinize ingredient lists, directly benefiting processors with certified supply chains.
- Agricultural Concentration:The geographic density of soybean and corn farming in the US Midwest provides processors in the region with significant logistical and cost advantages for sourcing raw materials.
Market Restraints
- Commodity Price Volatility:Processor margins are directly exposed to fluctuations in global soybean, corn, and canola prices, making cost management and hedging critical but challenging operational activities.
- Import Substitution Risk:Competition from lower-cost imported oils, particularly palm oil for non-food and industrial applications, places a ceiling on pricing for certain commodity vegetable oils.
- Divergent Regulatory Standards:Navigating differing food labeling requirements between the US FDA and Health Canada, especially concerning nutritional information and allergen declarations, adds complexity and cost for cross-border trade.
Strategic Opportunities
- High-Oleic Oil Expansion:Developing high-oleic versions of canola and soybean oils opens new markets in high-performance frying applications and as bio-based industrial lubricants, commanding premium pricing.
- Sustainable Agriculture Incentives:Canadian federal and provincial programs supporting sustainable farming practices create an opportunity for processors to develop and market oils with verifiable environmental credentials.
- Plant-Based Food Formulations:The rapid growth of the plant-based meat and dairy alternative sector creates a significant opportunity for oils that provide specific functional properties like texture and mouthfeel.
Industry Challenges
- Refinery Modernization Costs:The high capital expenditure needed to upgrade aging crushing and refining facilities to meet stricter environmental regulations and improve energy efficiency presents a significant barrier for smaller processors.
- Supply Chain Traceability:Implementing and maintaining robust, auditable traceability systems for certified organic or non-GMO oils from farm to finished product is operationally complex and costly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vegetable Oils Market |
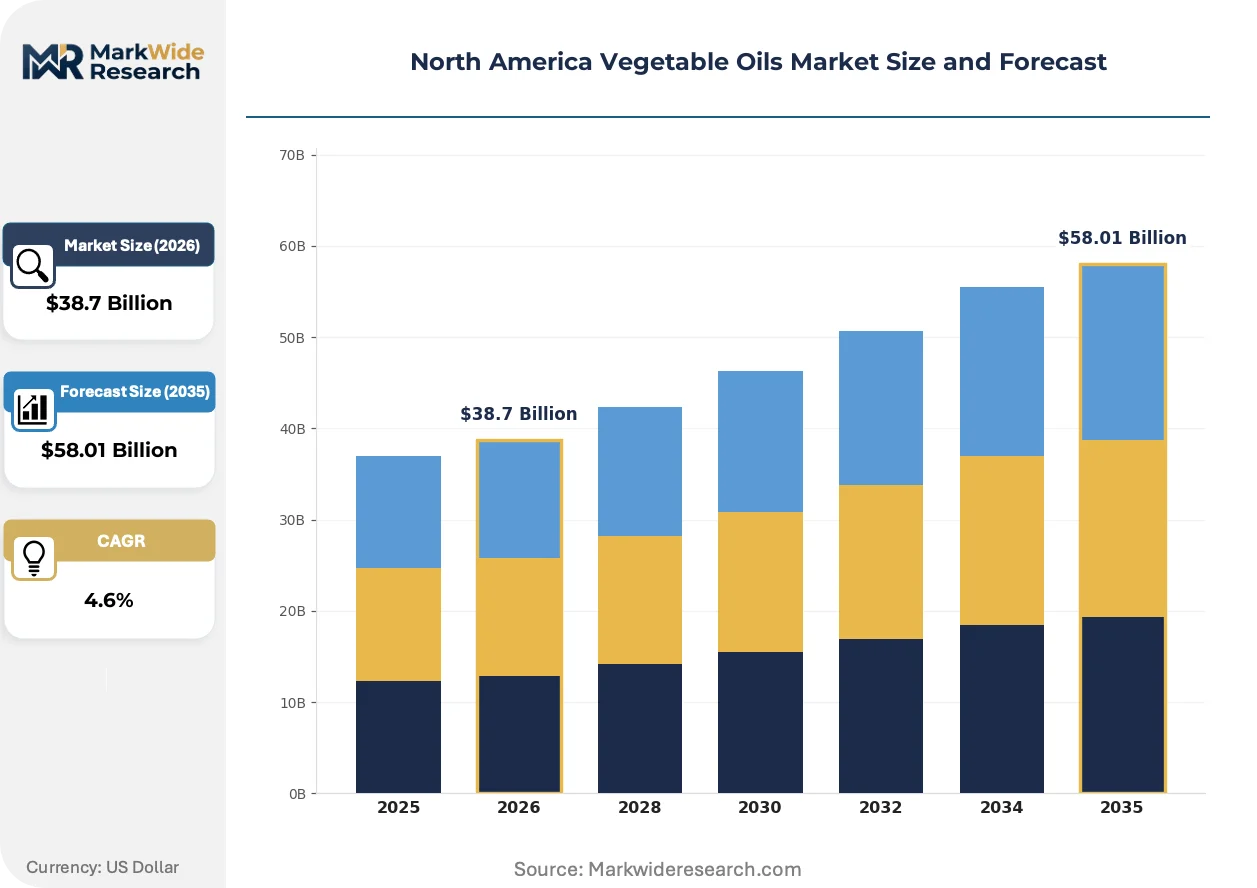
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybean Oil, Canola Oil, Sunflower Oil, Corn Oil, Coconut Oil Application: Food Processing, Animal Feed, Biodiesel Production, Personal Care, Industrial Lubricants Packaging Type: Bulk Containers, Bottled Oil, Pouches, Tins, Drums Customer Type: Food Manufacturers, Feed Producers, Cosmetic Companies, Renewable Energy Firms, Industrial Users |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Bunge Limited, Wilmar International Limited, CHS Inc., Louis Dreyfus Company, Conagra Brands, Inc., Fuji Oil Holding Inc., Olam International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vegetable Oils Market Strategic Shifts & Innovations
Technological advancements in agriculture and processing are enabling a shift from commodity-centric production toward value-added, specialized oils. This evolution is driven by specific regulatory pressures and a fundamental change in how end-users evaluate and source these ingredients, prioritizing functionality and origin transparency.
Precision agriculture technology, which uses sensors and data analytics to monitor crop health, is a key innovation. Large-scale farming cooperatives and agribusinesses are adopting these tools to optimize yields and resource inputs like water and fertilizer. This technology is digitizing the upstream supply chain, providing processors with unprecedented data on feedstock quality and origin before it arrives at the plant.
Regulatory actions, such as the FDA's ongoing re-evaluation of nutrient content claims for food labeling, are directly influencing product development. This pressure forces food manufacturers to reformulate products, increasing interest in oils with favorable fatty acid profiles, such as high-oleic canola oil. The specialty and functional food oil segments are responding by expanding capacity to meet this formulation-driven demand.
A notable behavioral shift is the rising demand for oils with third-party sustainability and ethical sourcing certifications. This disrupts traditional procurement models based purely on price, giving preference to suppliers who can provide identity-preserved oils with documented compliance. This trend is most visible within the consumer-packaged goods and foodservice sectors in the United States and Canada, where corporate ESG goals influence sourcing decisions.
North America Vegetable Oils Market Segmentation
Segmentation analysis for the North America vegetable oils market provides a granular view of demand drivers and supply chain dynamics. Understanding these distinct categories helps processors tailor product offerings, optimize logistics, and navigate the complex regulatory landscape across the United States and Canada.
Product Type:
The North America vegetable oils market exhibits varying production cycles across its product types, influencing inventory management and commodity trading.
- Soybean Oil:This product type dominates by volume, characterized by a versatile fatty acid profile suitable for diverse applications. Demand concentrates in food processing and is significantly bolstered by US Renewable Fuel Standard mandates, particularly from the US Midwest.
- Canola Oil:Known for its low saturated fat content and high oleic varieties, canola oil offers health-conscious benefits. Its demand is rapidly expanding in biodiesel production and clean-label food formulations across both the US and Canada.
- Sunflower Oil:This light-flavored oil offers high oleic varieties for high-performance frying and general cooking applications.
- Corn Oil:Primarily a byproduct of corn wet milling, corn oil finds application in both food processing and various industrial uses.
- Coconut Oil:Distinguished by its unique flavor and saturated fat profile, coconut oil serves specific niches in food and personal care products.
Soybean oil dominates the installed crushing and refining capacity. Canola oil is where expansion concentrates, particularly for renewable fuel applications.
Application:
Application segments in North America demonstrate distinct volume requirements, driving specialized processing and distribution networks.
- Food Processing:This segment utilizes a wide array of vegetable oils for frying, baking, emulsification, and ingredient formulation. Demand is shaped by evolving consumer preferences for healthier fats and clean-label products across the US and Canadian food industries.
- Biodiesel Production:This application converts commodity vegetable oils into renewable fuel for blending with conventional diesel. The US Renewable Fuel Standard (RFS) program creates consistent, large-scale feedstock demand from renewable energy firms.
- Animal Feed:Lower-grade vegetable oils serve as essential energy sources and fat supplements for livestock diets, particularly within the US agricultural sector.
- Personal Care:Specialized and refined vegetable oils are incorporated for their moisturizing, emollient, and functional properties in cosmetic and skincare product formulations.
- Industrial Lubricants:High-oleic vegetable oils are increasingly employed as bio-based alternatives in industrial lubricants, offering performance and environmental benefits.
The largest volume pools reside in food processing. Biodiesel production exhibits the most dynamic growth.
Packaging Type:
Packaging types in North America directly align with customer requirements, influencing logistics and distribution efficiency.
- Bulk Containers:This category includes tank trucks, rail cars, and large totes, designed for high-volume delivery to industrial clients. They are critical for efficient supply to food manufacturers and renewable energy firms across the US Midwest.
- Bottled Oil:Intended for retail consumers and smaller foodservice operations, bottled oils are subject to stringent labeling requirements from the US FDA and Health Canada, influencing product presentation.
- Pouches:This packaging format offers cost-effectiveness and convenience, gaining traction in specific consumer retail segments.
- Tins:Tins provide extended shelf life and product protection, traditionally utilized for certain specialty and imported oils.
- Drums:Drums serve as a medium-volume industrial packaging solution, suitable for various manufacturing and foodservice applications.
Logistical efficiency is paramount for bulk containers. Bottled oil allows for greater brand differentiation.
Customer Type:
Customer types in North America drive distinct supply chain configurations, from direct procurement to specialized distribution channels.
- Food Manufacturers:This diverse customer base demands specific oil properties for texture, flavor, and shelf life in their product formulations. Direct procurement from large-scale processors like Archer Daniels Midland Company is common across the US.
- Renewable Energy Firms:These firms primarily purchase commodity oils like soybean and canola oil for biofuel production. Their demand is concentrated near agricultural hubs in the US Midwest, driven by government mandates.
- Feed Producers:Feed producers source cost-effective vegetable oils as energy supplements for animal feed formulations, supporting livestock industries.
- Cosmetic Companies:These companies require highly refined and often specialized oils for their personal care product formulations, emphasizing purity and functional properties.
- Industrial Users:This segment utilizes vegetable oils for various non-food applications, including bio-based lubricants and chemical intermediates.
The largest purchasing power resides with food manufacturers. Renewable energy firms represent a growing, mandated demand segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for vegetable oil producers often centralizes in the US Midwest, contrasting with more distributed cost structures in other North American regions. This asymmetry influences raw material procurement strategies for processors across the continent. Divergent regulatory landscapes between the United States and Canada also impact market dynamics.
United States
Demand for soybean oil in the United States is significantly bolstered by food processing applications and Renewable Fuel Standard mandates. The US Food and Drug Administration (FDA) sets comprehensive standards for food-grade oils, guiding product development. Major crushing and refining operations are concentrated in the US Midwest, benefiting from the region's vast soybean and corn cultivation.
Canada
Canola oil demand in Canada is rapidly expanding, driven by its use in biodiesel production and clean-label food formulations. Health Canada imposes strict labeling requirements for allergens and nutritional content, influencing product formulation. Key canola cultivation and processing facilities are found in provinces like Alberta and Saskatchewan.
Mexico
Mexico's growing food processing sector drives demand for a diverse array of vegetable oils, including soybean and sunflower oil. The country's health regulations are continuously evolving for food products, impacting import and local production standards. Processing facilities near major population centers such as Mexico City cater to the substantial domestic consumption of edible oils.
US Midwest
Biofuel mandates create consistent, large-scale demand for feedstocks like soybean and corn oil within the US Midwest. The US Renewable Fuel Standard (RFS) program directly impacts feedstock sourcing and processing capacity in this region. The US Midwest holds a significant density of soybean and corn cultivation, supporting extensive crushing and refining infrastructure in states like Illinois and Iowa.
Ontario
Clean-label food production is a expanding segment in Ontario, driving demand for certified organic and non-GMO vegetable oils. Health Canada's allergen labeling requirements directly influence product formulations and ingredient sourcing for food manufacturers. Food manufacturers in the Greater Toronto Area and surrounding regions drive demand for specialized and sustainably sourced oils.
North America Vegetable Oils Market Key Industry Players
Vertically integrated giants and specialized ingredient providers split the North American vegetable oils market, creating a tiered competitive environment. Scale players dominate the bulk commodity segments, while niche firms focus on high-value applications like organic or high-oleic oils. Competitive moves often involve significant capacity expansion in crushing and refining facilities, alongside strategic partnerships aimed at securing sustainable and traceable raw material sourcing. Geographic expansion within the continent also remains a key strategy for market penetration.
At the scale-driven end, Archer Daniels Midland Company, a Chicago-based firm, exemplifies extensive crushing and refining infrastructure, anchoring significant market share in commodity oils. Cargill Incorporated, with its global presence, occupies a position leveraging vast logistics networks for securing supply contracts across multiple regions. Bunge Limited, a St. Louis-headquartered corporation, sits within the archetype of specialized oil formulators, catering to industrial food clients with tailored product solutions. These corporations collectively demonstrate the market's reliance on integrated operations and sophisticated supply chain management to meet diverse customer demands.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Bunge Limited |
| Wilmar International Limited |
| CHS Inc. |
| Louis Dreyfus Company |
| Conagra Brands, Inc. |
| Fuji Oil Holding Inc. |
| Olam International Limited |
| Others |
Cost & Logistics Intelligence
Commodity price volatility in global soybean, corn, and canola markets determines both pricing tier spreads and supply chain shape across North America. This market's structure reflects a balance between large-volume commodity sales and specialized, value-added product offerings.
Pricing Analysis
Configured-to-order pricing for specialized oil formulations commands a premium over standard, bulk commodity oils. The dominant pricing model is a hybrid of commodity spot pricing for bulk volumes and contract-based long-term offtake agreements for industrial clients. Price differentiation stems from certification levels, such as organic or non-GMO, and the degree of oil customization for specific industrial applications. Pricing pressure stems from global commodity fluctuations, particularly for standard soybean and canola oils. Food manufacturers seeking clean-label ingredients exhibit lower price sensitivity compared to renewable energy firms focused on feedstock cost.
Supply Chain Analysis
Upstream feedstock sourcing for North American vegetable oils heavily relies on agricultural production in the US Midwest and Canadian Prairies. The supply chain draws from vast soybean and corn cultivation in states like Illinois and Iowa, and canola farming in Alberta and Saskatchewan. Raw material dependencies include oilseeds like soybeans, canola, and corn. A structural risk is commodity price volatility, which impacts processor margins directly. Distribution runs through bulk containers for industrial users and bottled oil for retail, with logistics optimized for efficient delivery from agricultural hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American vegetable oils market faces a capability gap in advanced processing technologies for high-value, specialized oil derivatives. This gap presents both challenges and opportunities for market participants.
For Market Incumbents:
Pre-empt competitive threats from specialized oil producers by investing in advanced fractionation and hydrogenation capabilities. Focus on deepening vertical integration into high-oleic oil production to capture premium markets in industrial lubricants and high-performance frying. Expand crushing and refining capacity in the US Midwest, leveraging existing agricultural concentration. Invest in sustainable agriculture incentives to meet evolving corporate ESG goals from consumer-packaged goods clients.
For New Entrants and Emerging Players:
Build out certified supply chains for organic, non-GMO, and expeller-pressed oils, targeting the clean-label food production segment. The most penetrable segment is specialized oils for plant-based food formulations, offering specific functional properties like texture. A clear go-to-market angle involves direct partnerships with food manufacturers seeking transparent, identity-preserved ingredients. Focus on regions like Ontario where clean-label demand is expanding rapidly.
For Investors and Strategic Acquirers:
Specialized processors with proprietary technology for high-oleic oils or robust traceability systems represent attractive acquisition targets for long-term viability. The market favors firms that can command premium pricing through product differentiation and verifiable sustainability credentials. A signal to watch is the increasing adoption of bio-based industrial lubricants, indicating a broader shift towards higher-value applications for vegetable oils.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in High-Oleic Processing | Secures market share in premium industrial and food applications, driving higher profit margins for processors. |
| Investment in Sustainable Sourcing Certifications | Meets rising demand from consumer-packaged goods and foodservice sectors for verifiable environmental credentials. |
| Development of Plant-Based Food Formulations | Captures significant growth opportunities within the rapidly expanding alternative protein and dairy sectors. |
| Modernization of Crushing and Refining Facilities | Enhances energy efficiency and compliance with stricter environmental regulations, reducing operational costs. |
| Strategic Partnerships for Supply Chain Traceability | Ensures transparent and auditable sourcing for certified organic and non-GMO oils, building buyer trust. |
Research Approach
Cross-validation between primary interviews and extensive secondary research anchors the qualitative findings and quantitative market sizing. The analysis involved in-depth discussions with agricultural cooperative managers, food processing procurement leads, renewable energy firm executives, and regulatory affairs specialists. Secondary data sources included USDA and Health Canada reports, industry association publications, and company financial filings.
The market forecast framework integrates a calibrated analytical approach across the projection horizon. Segmentation dimensions modeled include product type, application, packaging type, and customer type, alongside regional regulatory frameworks. Compound annual growth rates were derived from historical growth patterns, future demand projections, and anticipated technological advancements. Key industry-specific forecast inputs included biofuel blending mandates and consumer preference shifts towards healthier fats.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large vertically integrated giants or significant regulatory shifts would alter outcomes. The analysis reflects assumptions regarding stable commodity markets and consistent policy enforcement across North America. Cross-checking against government agricultural outlooks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Macleaya Cordata Extract Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Corn Peptide Market
Ingredients
Karaya Gum Market
Ingredients
US Plant-Based Oils Market
Ingredients
Agar Agar Flakes Market
Ingredients
North America Carrageenan Market
Ingredients
Edible Fiber Market
Ingredients
Confectionery Ingredients Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Zea Mays Starch Market
Ingredients
Yeast Autolysates Market
Ingredients
Shortening Powder Market
Ingredients
Chickpea Protein Market
Ingredients
Black Seed Oil Market
Ingredients
South America Feed Yeast Market