
 Licorice Root Market | 2026-2036
Licorice Root Market Size, Share, and Industry Trends Forecast 2026-2036
Licorice Root Market Analysis
The split between pharmaceutical-grade extracts and commodity food-grade powder is shifting procurement criteria across the value chain. Maruzen Pharmaceuticals Co. Ltd. leverages its glycyrrhizin purification technology to dominate high-specification segments. Mafco Worldwide LLC anchors North American supply through backward integration into Iranian and Azerbaijani raw material sourcing. Naturex (Givaudan Active Botanicals) differentiates via botanical traceability platforms that satisfy pharmaceutical audit requirements.
Licorice root comprises the dried rhizome and stolon of Glycyrrhiza glabra and Glycyrrhiza uralensis species, containing triterpenoid saponins (glycyrrhizin) at 2-25% concentration by dry weight depending on cultivar and extraction method; processors deploy either aqueous extraction for conventional applications or supercritical CO2 methods for pharmaceutical-grade isolates. The extract segment leads value generation due to concentrated active content and premium pricing in pharmaceutical and dietary supplement channels, while powder maintains volume dominance in food and beverage formulations where lower purity thresholds apply. Application concentration in pharmaceuticals reflects tightening pharmacopeial standards and expanded clinical validation of anti-inflammatory and demulcent properties.
EFSA glycyrrhizin exposure limits, FDA GRAS self-affirmation requirements, and REACH substance registration obligations collectively elevate compliance costs for entrants while reinforcing incumbent quality systems. European EMA monographs and USP-NF standards create divergent specification regimes that fragment formulation requirements across Atlantic supply corridors. Stakeholders must monitor evolving pharmacopeial harmonization discussions and glycyrrhizin residue testing protocols to anticipate specification-driven sourcing reallocations.
Market Dynamics
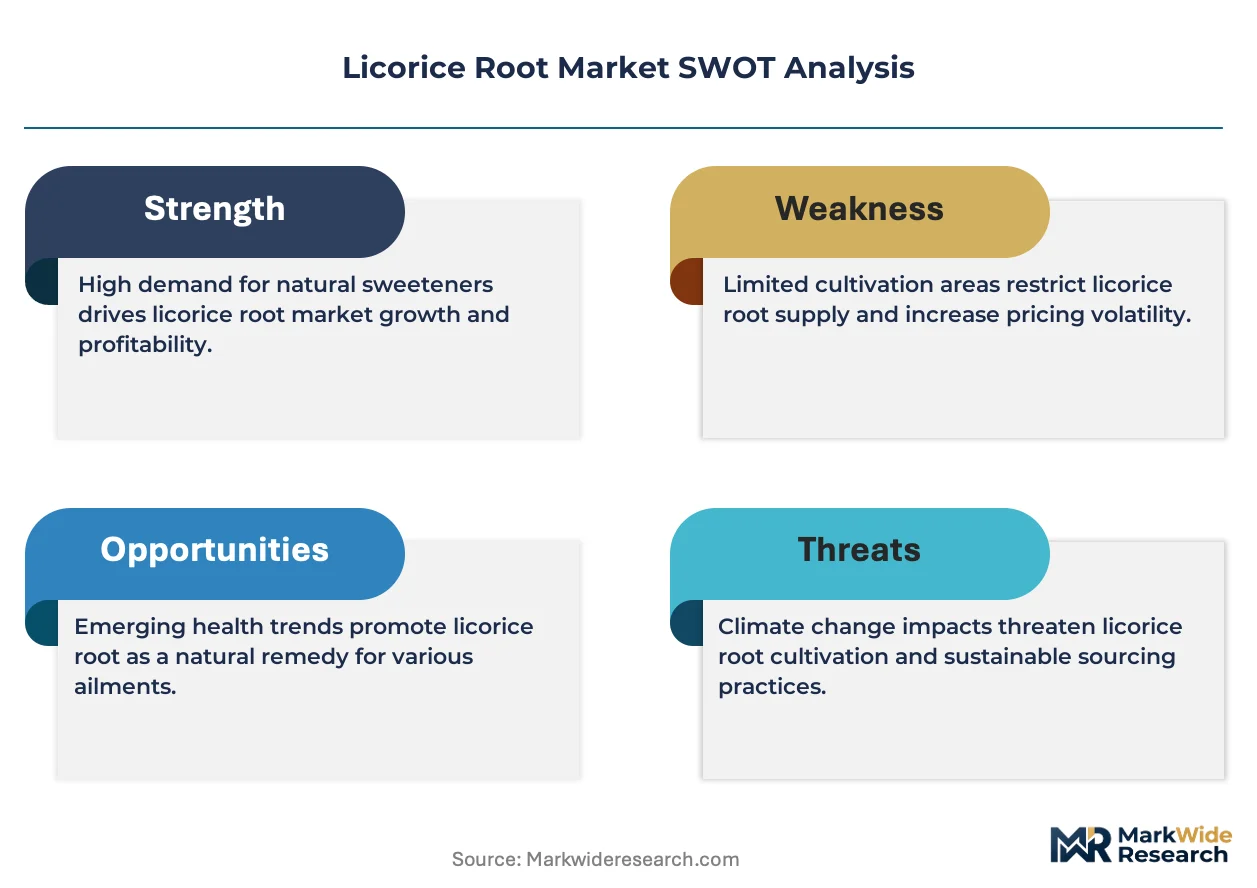
Pharmaceutical-grade glycyrrhizin purification is bifurcating procurement standards, forcing extractors to choose between capital-intensive supercritical CO2 infrastructure and commoditized aqueous processing. This technical divergence is redrawing competitive boundaries across the value chain.
Growth Catalysts
- EMA monograph harmonization:Unified pharmacopeial standards across European member states are consolidating quality benchmarks, reducing formulation fragmentation for cross-border pharmaceutical contracts.
- Deglycyrrhizinated licorice (DGL) clinical validation:Expanded therapeutic evidence for gastric mucosal protection is pulling demand from gastroenterology prescription channels into preventive wellness segments.
- Iran-Azerbaijan raw material corridors:Concentrated wild harvesting in these cultivation zones is anchoring supply security for processors seeking glycyrrhizin-rich rootstock above 15% dry weight concentration.
Market Restraints
- Wild licorice depletion in Central Asian harvest zones:Unsustainable extraction rates in traditional gathering regions are compressing raw material availability and elevating spot price volatility.
- REACH substance registration burdens:ECHA compliance costs for novel glycyrrhizin derivatives are creating structural barriers for mid-scale entrants lacking dedicated regulatory affairs infrastructure.
- Stevia and monk fruit substitution:Natural high-intensity sweeteners are displacing licorice extract in confectionery and beverage formulations where glycyrrhizin's lingering aftertaste limits application.
Strategic Opportunities
- Cosmeceutical topical delivery systems:Melanin-inhibiting and anti-inflammatory properties are opening dermatology channels through licensed cosmeceutical partnerships with Korean and Japanese skincare formulators.
- Carbon-negative extraction certification:EU Green Deal-aligned supercritical CO2 processing with renewable energy sourcing qualifies for preferential procurement under CSRD supply chain disclosure mandates.
- Traceability platform monetization:Blockchain-verified botanical provenance systems are commanding premium positioning in pharmaceutical audit trails, converting compliance cost into differentiation revenue.
Industry Challenges
- Phytochemical standardization expertise scarcity:Analytical chemists capable of validating glycyrrhizin content variance across harvest batches command compensation premiums that compress processor margins.
- Multi-jurisdiction pharmacopeial reconciliation:Divergent USP-NF and EMA monograph specifications for residual solvent limits force dual-track quality systems that extend certification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Licorice Root Market |
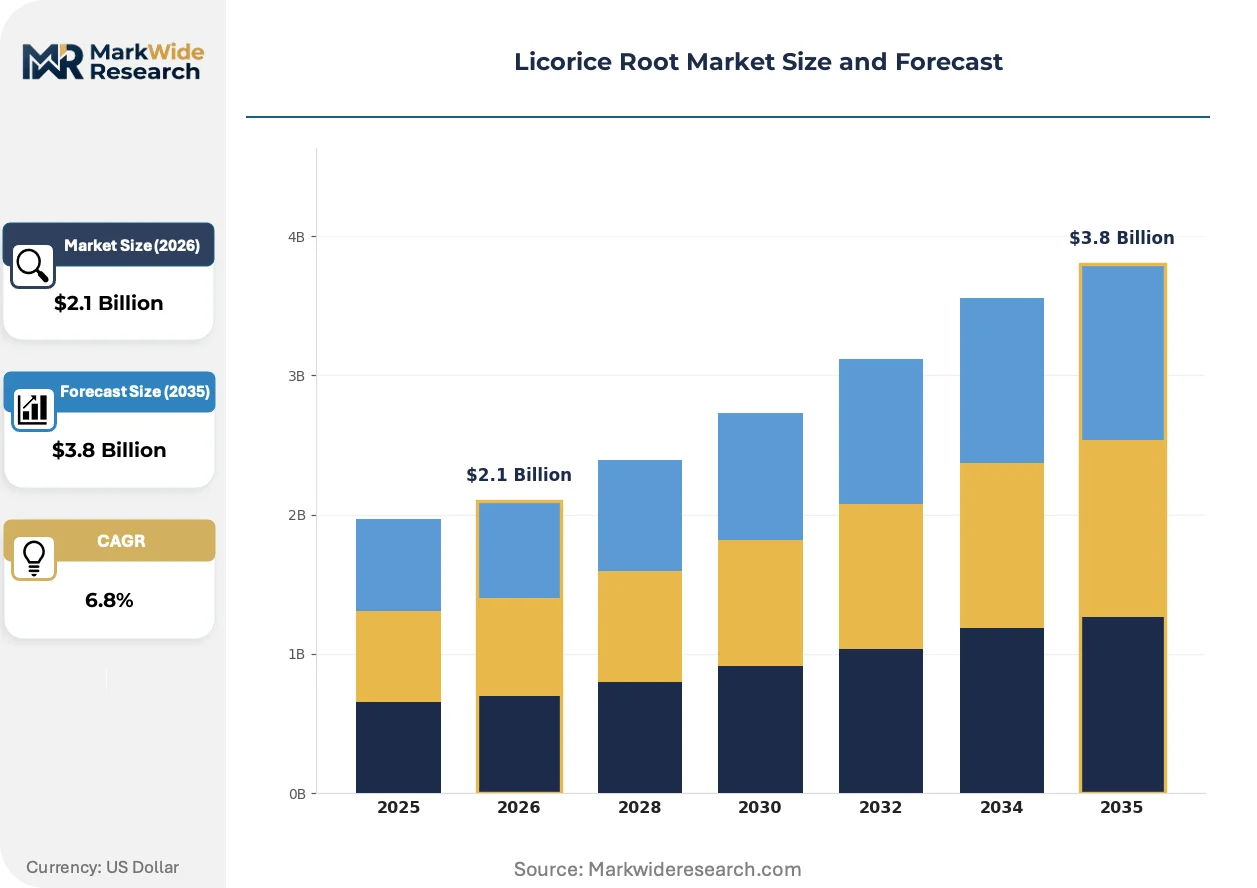
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extract, Powder, Granules, Whole Root Application: Food & Beverage, Pharmaceuticals, Cosmetics, Dietary Supplements Form: Liquid, Solid, Syrup, Capsule End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | Maruzen Pharmaceuticals Co. Ltd., Sarv Biolabs Pvt Ltd, Mafco Worldwide LLC, Naturex (Givaudan Active Botanicals), Ransom Naturals Ltd., Norevo GmbH, S.r Organic, Martin Bauer Group, Finzelberg GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Licorice Root Market Emerging Trajectories
Supercritical CO2 extraction infrastructure is expanding into pharmaceutical-grade isolate production, compressing traditional solvent-based methods while enabling precise glycyrrhizin fractionation. This technical transition is reshaping capital allocation and competitive positioning simultaneously.
Supercritical fluid extraction deploys pressurized carbon dioxide at 31°C and 74 bar to selectively isolate glycyrrhizin without thermal degradation or residual solvent contamination. European pharmaceutical formulators are adopting this technology fastest, driven by EMA purity thresholds that conventional aqueous methods struggle to satisfy. The process is expanding into mid-scale processing facilities previously locked out of high-specification supply contracts by capital barriers.
REACH substance registration obligations now encompass glycyrrhizin derivatives used in novel therapeutic applications, elevating documentation requirements for importers and compounders. ECHA's 2023 updated guidance on botanical substance characterization is forcing reformulation of existing dossiers. Pharmaceutical extractors with established regulatory affairs teams are consolidating market position while smaller competitors defer derivative development.
Pharmaceutical buyers are consolidating supplier relationships around dual-source qualification models, reducing approved vendor lists from 8-12 to 3-4 strategic partners. This concentration is displacing transactional spot purchasing in glycyrrhizin procurement. German and Swiss formulation houses are driving this behavioral shift most aggressively, leveraging volume commitments to secure dedicated processing capacity and priority batch scheduling.
Licorice Root Market Segmentation
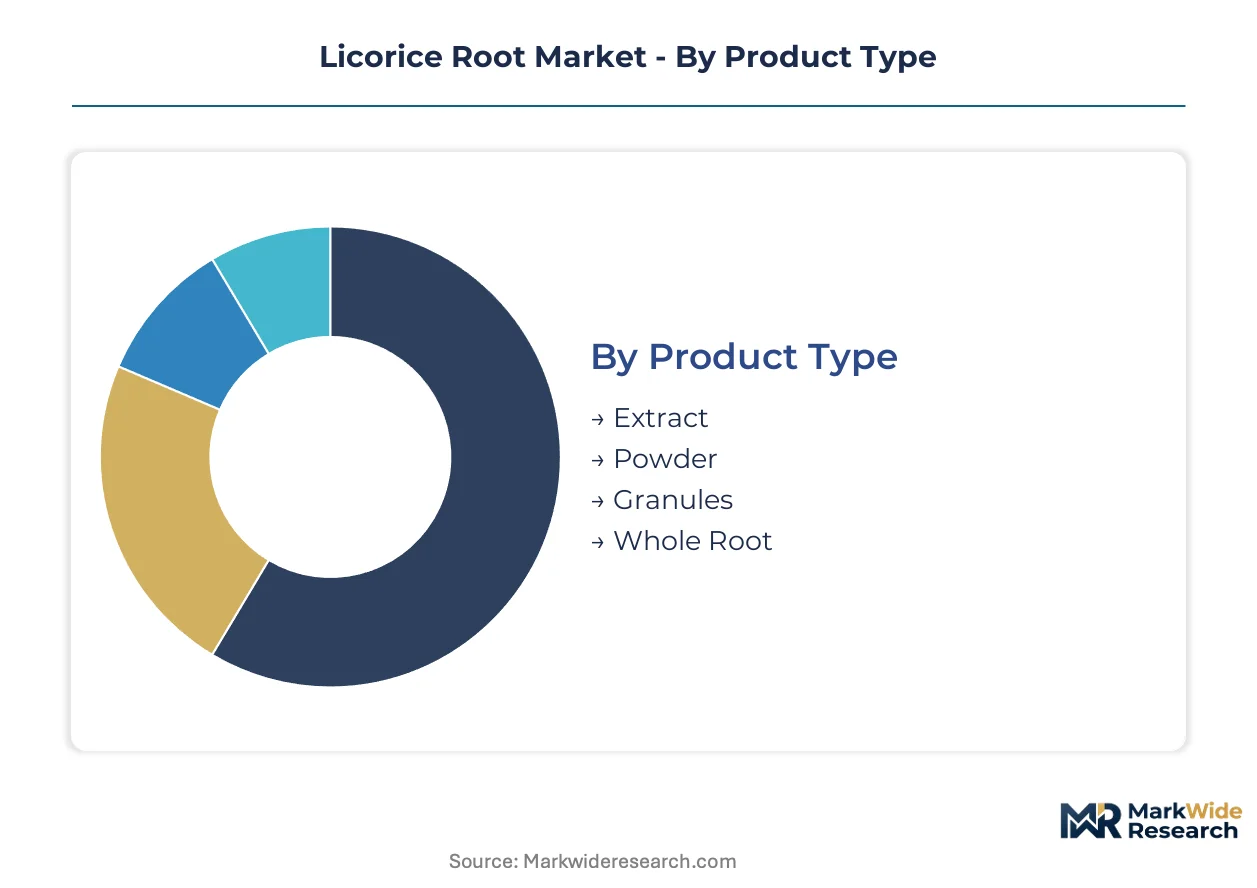
Licorice root processors face divergent technical specifications across pharmaceutical, food, and cosmetic channels. Each segment demands distinct glycyrrhizin concentration thresholds, extraction methods, and compliance documentation that reshape procurement and margin structures.
Product Type:
Upgrade cycles from commodity powder to high-specification extracts are compressing aqueous processing margins while rewarding supercritical CO2 infrastructure investments.
- Extract:Concentrated glycyrrhizin isolates at 20-98% purity serve EMA-compliant pharmaceutical formulators and deglycyrrhizinated licorice manufacturers. German processors anchor demand for supercritical CO2-derived isolates that satisfy REACH substance registration thresholds.
- Powder:Standardized at 2-10% glycyrrhizin content, this segment supplies confectionery and beverage manufacturers where EFSA exposure limits constrain application rates. Iranian wild-harvested rootstock dominates raw material sourcing.
- Granules:Intermediate processing format for tea and traditional medicine applications, primarily serving East Asian distributors.
- Whole Root:Unprocessed dried rhizome for traditional herbal practitioners and small-scale compounders, concentrated in Central Asian harvest zones.
Powder sits at the top of the volume ranking, with Extract climbing the fastest.
Application:
Cost tier stratification separates premium pharmaceutical contracts from commoditized food-grade procurement, with compliance documentation costs driving supplier consolidation.
- Food & Beverage:Confectionery, chewing gum, and beverage applications leverage glycyrrhizin's sweetening properties at 50x sucrose intensity. FDA GRAS self-affirmation requirements and lingering aftertaste constraints limit formulation flexibility.
- Pharmaceuticals:Prescription demulcents, anti-inflammatory compounds, and gastric mucosal protectants command premium pricing. EMA monograph harmonization is consolidating quality benchmarks across European member states.
- Cosmetics:Melanin-inhibiting and anti-inflammatory properties drive Korean and Japanese skincare formulator demand. Topical delivery systems require specialized extraction protocols.
- Dietary Supplements:Capsule and tablet formulations for adrenal support and respiratory health, positioned between pharmaceutical and food-grade specification tiers.
Food & Beverage retains volume leadership, though Pharmaceuticals is gaining share fastest on clinical validation expansion.
Form:
Customer type preferences bifurcate between industrial bulk processors and finished goods manufacturers with divergent handling and stability requirements.
- Liquid:Aqueous or hydroalcoholic solutions for beverage fortification and pharmaceutical syrups, requiring cold chain logistics for glycyrrhizin stability.
- Solid:Dried extracts and powders for tablet compression and powder blending operations, dominating pharmaceutical contract manufacturing.
- Syrup:High-viscosity formulations for cough suppressants and traditional medicine preparations, concentrated in Middle Eastern and South Asian markets.
- Capsule:Pre-measured unit doses for dietary supplement channels, with gelatin and vegetable shell variants.
Solid form commands the highest volume throughput, with Capsule formats expanding most quickly on preventive wellness channel growth.
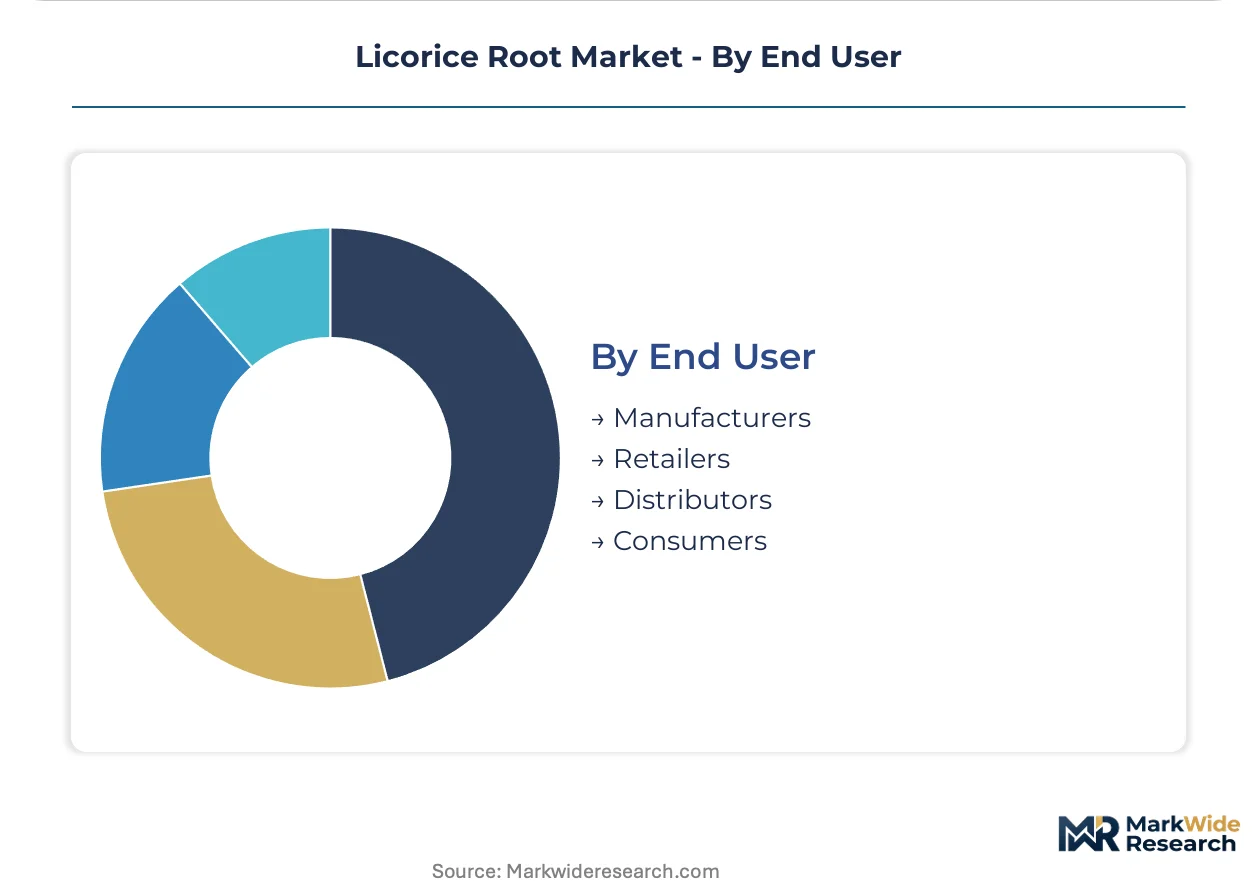
End User:
Supply concentration among German and Swiss formulation houses is concentrating procurement power upstream, marginalizing spot-market transactional relationships.
- Manufacturers:Pharmaceutical compounders, food processors, and cosmetic formulators with dedicated quality systems and audit capabilities. Dual-source qualification models are reducing approved vendor lists from 8-12 to 3-4 strategic partners.
- Retailers:Health food chains, pharmacies, and specialty botanical shops with private-label sourcing requirements. Blockchain traceability platforms are becoming mandatory for shelf placement.
- Distributors:Regional wholesalers bridging harvest zones in Iran and Azerbaijan with European and North American processors. Inventory carrying costs are compressing margins on spot price volatility.
- Consumers:Direct-to-purchaser channels through e-commerce and traditional medicine practitioners, smallest volume tier with highest per-unit pricing.
Manufacturers represent the dominant volume channel, with Retailers showing the steepest expansion trajectory on traceability-premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized phytochemists and analytical validation specialists concentrate in German processing clusters and Japanese pharmaceutical corridors, anchoring quality-intensive supply chains.
Germany
EMA monograph harmonization and REACH substance registration obligations drive pharmaceutical-grade procurement concentration. Martin Bauer Group and Finzelberg GmbH anchor processing clusters in Bavaria and Rhineland-Palatinate, deploying supercritical CO2 infrastructure for glycyrrhizin isolates.
United States
FDA GRAS self-affirmation requirements and expanded DGL clinical validation pull demand through gastroenterology and preventive wellness channels. Mafco Worldwide LLC maintains backward integration into Iranian and Azerbaijani raw material sourcing to secure supply security.
Japan
PMDA pharmacopeial standards and melanin-inhibiting cosmeceutical applications concentrate demand in Kanto and Kansai formulation corridors. Maruzen Pharmaceuticals Co. Ltd. leverages glycyrrhizin purification technology to dominate high-specification segments.
China
Glycyrrhiza uralensis wild harvesting in Gansu and Xinjiang provinces supplies domestic pharmaceutical compounders and export processors. NMPA botanical substance characterization standards are tightening documentation requirements for glycyrrhizin derivatives.
Switzerland
Swissmedic purity thresholds and pharmaceutical audit requirements concentrate high-value extraction contracts around Basel and Zurich processing nodes. Naturex (Givaudan Active Botanicals) differentiates via botanical traceability platforms satisfying pharmaceutical compliance mandates.
Licorice Root Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the licorice root value chain. Supercritical CO2 infrastructure owners face off against toll processors and brand-holding traders. Three archetypes dominate: integrated harvester-processors with captive raw material supply, technology-specialized isolators with purification IP, and platform-integrated botanical houses with traceability systems. Consolidation pressures favor dual-source qualification models that reduce approved vendor lists, while regulatory compliance costs fragment mid-scale competitors.
Among Asia-Pacific-based pharmaceutical specialists, Maruzen Pharmaceuticals Co. Ltd. exemplifies technology-driven isolator positioning. German processing clusters anchor European supply through Martin Bauer Group and Finzelberg GmbH, representing integrated harvester-processor archetypes with backward control over raw material corridors. These three entities occupy positions across distinct competitive vectors—purification technology, captive supply security, and regional regulatory proximity.
| Leading Market Players |
|---|
| Maruzen Pharmaceuticals Co. Ltd. |
| Sarv Biolabs Pvt Ltd |
| Mafco Worldwide LLC |
| Naturex (Givaudan Active Botanicals) |
| Ransom Naturals Ltd. |
| Norevo GmbH |
| S.r Organic |
| Martin Bauer Group |
| Finzelberg GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Backward integration into Iranian and Azerbaijani wild-harvesting corridors anchors supply security for North American processors while compressing spot-market pricing power for non-integrated competitors. This captive sourcing model enables Mafco Worldwide LLC and similar integrated players to buffer pharmaceutical buyers against glycyrrhizin content volatility that aqueous extractors cannot match.
Pricing Analysis
Bundled supercritical CO2 extraction services with dedicated batch scheduling command 40-60% premiums over unbundled toll processing. Three-tier pricing structure across pharmaceutical-grade isolates, food-grade extracts, and commodity powder reflects glycyrrhizin concentration thresholds and REACH documentation depth. Cost compression in food-grade powder runs through stevia substitution pressure in confectionery channels. Small-scale traditional medicine practitioners show highest price sensitivity; pharmaceutical formulators with dual-source qualification requirements show least.
Supply Chain Analysis
Single-source vulnerability sits with Iranian wild-harvesting zones where unsustainable extraction rates deplete glycyrrhizin-rich rootstock. Supply draws from Iran, Azerbaijan, and China's Gansu province for Glycyrrhiza uralensis. Raw material dependencies center on 15%+ dry weight glycyrrhizin concentration thresholds, supercritical CO2 equipment components, and analytical validation chemists. Regulatory restriction risk intensifies through ECHA's updated botanical substance characterization guidance. Distribution runs through German and Swiss formulation houses with consolidated approved vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The licorice root market functions as a stable compounder anchored by pharmaceutical-grade glycyrrhizin purification demand that resists cyclical downturns through EMA-mandated quality tiering.
For Market Incumbents: Deploy supercritical CO2 capacity expansion in Bavaria and Rhineland-Palatinate processing clusters to capture pharmaceutical contract consolidation. Deepen captive supply relationships in Azerbaijan before wild depletion accelerates. Counter stevia substitution in food channels through deglycyrrhizinated licorice clinical validation expansion. For New Entrants and Emerging Players: Blockchain-verified traceability platforms offer technology-first entry into pharmaceutical audit-trail segments where incumbents treat compliance as cost center. White-space concentrates in Korean and Japanese cosmeceutical topical delivery partnerships. Go-to-market leverage rests on carbon-negative extraction certification qualifying for CSRD preferential procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration burdens fragment mid-scale competitors lacking dedicated regulatory affairs infrastructure. Five-to-ten-year viability favors technology-specialized isolators with purification IP over commodity aqueous processors. Target acquisition archetype: supercritical CO2-equipped European processors with EMA monograph dossiers. Signal to monitor: pharmacopeial harmonization progress between USP-NF and EMA residual solvent specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables EMA-compliant glycyrrhizin isolate production that aqueous methods cannot satisfy. |
| Backward Integration into Harvest Zones | Secures 15%+ dry weight glycyrrhizin rootstock before Central Asian depletion accelerates. |
| Blockchain Traceability Platform Launch | Converts REACH compliance cost into premium positioning for pharmaceutical audit trails. |
| DGL Clinical Validation Expansion | Pulls demand from prescription gastroenterology into preventive wellness channels. |
| Carbon-Negative Extraction Certification | Qualifies processors for EU Green Deal preferential procurement under CSRD mandates. |
Methodological Framework
Coverage spans Germany, Japan, the United States, China, and Switzerland, with primary inputs from each pharmaceutical processing cluster. The approach combines interviews with extraction plant managers, pharmaceutical procurement leads, regulatory affairs directors, and wild-harvesting cooperative representatives with secondary validation from EMA monograph databases, ECHA substance registration filings, USP-NF standards documentation, and customs trade records. Bottom-up capacity utilization data triangulates against top-down pharmaceutical formulation demand estimates.
Rate-of-change decomposition separates volume growth from value mix shift across the analysis window. Segmentation dimensions include product type tier, application channel, extraction method, and regional regulatory cluster. CAGRs derive from glycyrrhizin isolate pricing trajectories, supercritical CO2 capacity buildout schedules, and pharmaceutical buyer consolidation patterns. Industry-specific inputs encompass wild-harvesting yield estimates from Iranian and Azerbaijani corridors and EMA pharmacopeial harmonization timelines.
The model holds under steady EMA monograph implementation and sustained pharmaceutical-grade demand; deviation in wild licorice depletion rates or stevia substitution acceleration would shift trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
China Corn Glucose Market
Ingredients
Edible Halal Gelatin Market
Ingredients
Cheese Cultures Market
Ingredients
Marine Protein Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
South America Vegetable Oil Market
Ingredients
Bovine Gelatin Market
Ingredients
Terminalia Extract Market
Ingredients
Fruit Pectin Market
Ingredients
Native Starch Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Caramel Ingredient Market
Ingredients
Feed Ingredients Market
Ingredients
Global Edible Oil Market
Ingredients
Europe BBQ Charcoal Market