
 Edible Animal Fat Market | 2026-2036
Edible Animal Fat Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Animal Fat Market Intelligence
Sustainability and origin certification programs are restructuring how bulk edible animal fats are procured and marketed. JBS S.A. leverages its extensive meat processing operations to secure a consistent supply of raw materials. Darling Ingredients specializes in rendering and converting animal by-products into value-added fat ingredients. Meanwhile, Tyson Foods, Inc. competes through its large-scale production and integrated supply chain for poultry and pork fats.
Edible animal fat refers to lipids derived from animal tissues through rendering, characterized by a high saturated fatty acid profile. Its primary purpose is to act as a cooking medium or functional ingredient, providing flavor and texture in food manufacturing. Within product types, lard and tallow represent mature segments that are finding renewed interest as natural alternatives to processed fats. The baking and frying applications command the largest share of consumption, where the functional properties of these fats are critical for product quality.
Regulatory frameworks established by bodies like the United States' FDA and the European Food Safety Authority (EFSA) govern purity, labeling, and contaminant levels. In China, compliance with GB standards for food safety is mandatory for market access, shaping production protocols for both domestic and imported fats. Navigating the divergent consumer perceptions of animal fats versus plant-based alternatives will be a central strategic challenge for producers.
Market Dynamics
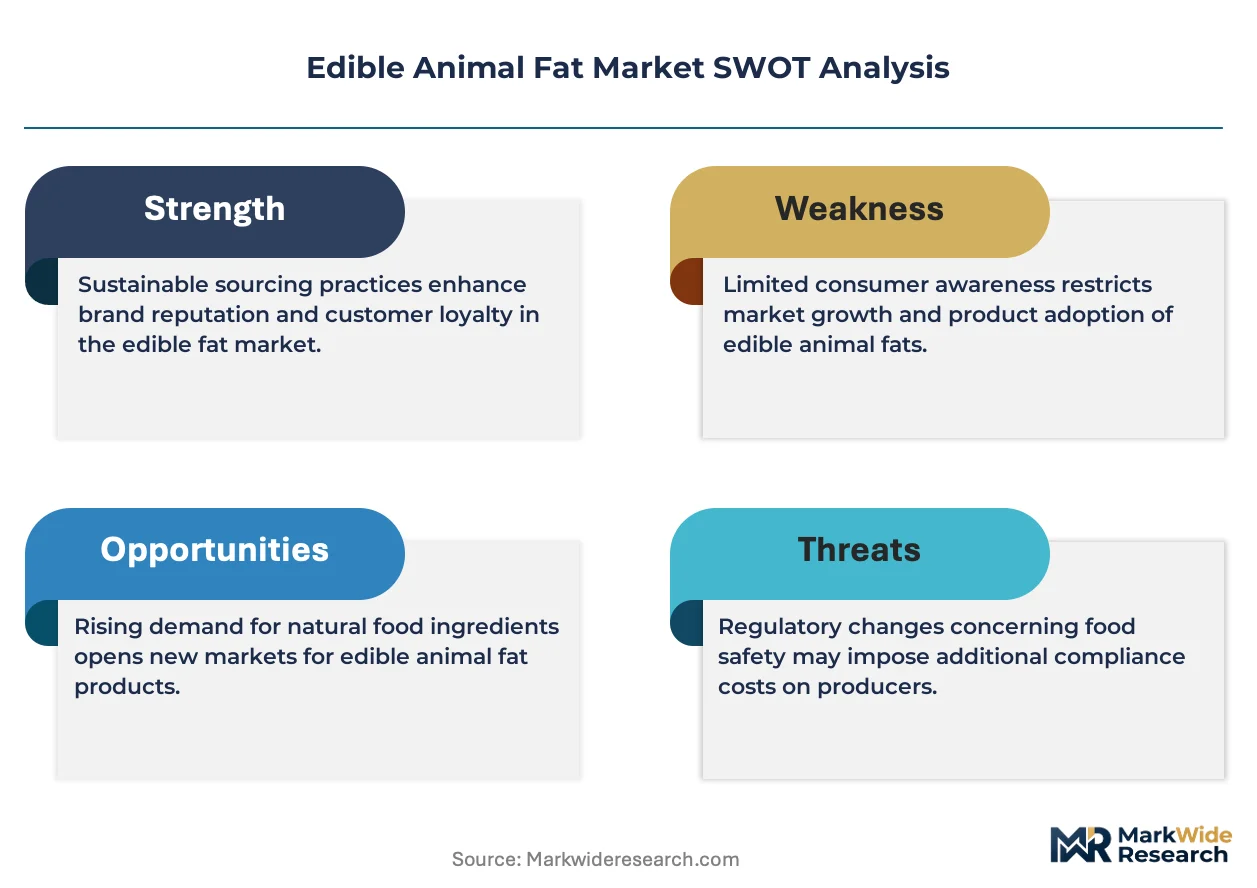
The central structural force shaping the edible animal fat market is the conflict between its traditional role as a functional ingredient and modern consumer and regulatory pressures favoring plant-based alternatives and healthier lipid profiles.
Growth Catalysts
- Regulatory Action Against Trans Fats:The FDA's ban on partially hydrogenated oils in the United States creates a functional ingredient vacuum, prompting food manufacturers to reformulate products using natural fats like lard and tallow.
- Baking Sector Functionality:The unique crystallization properties of lard and tallow provide flakiness and texture in baked goods that are difficult for many plant-based shortenings to replicate, sustaining demand from industrial and artisanal bakeries.
- Cultural Dietary Staples:In China, lard remains a fundamental component of many regional cuisines, providing a distinct flavor and mouthfeel, which ensures a large, stable, and culturally embedded consumption base.
Market Restraints
- Direct Substitution by Plant-Based Oils:The widespread availability and lower cost of vegetable oils like palm, soy, and canola, often promoted with a healthier image, present a significant substitution threat in frying and manufacturing applications.
- Livestock Market Volatility:The supply of raw material is directly tied to the health of the livestock industry, making it vulnerable to disruptions from animal diseases, feed costs, and culling cycles, which creates price volatility.
- Negative Health Perceptions:Lingering consumer concerns about high saturated fat content and cholesterol, heavily publicized for decades, act as a structural barrier to wider acceptance in health-conscious segments across Western markets.
Strategic Opportunities
- Premium "Clean Label" Products:There is an opportunity to market minimally processed, single-source fats like grass-fed tallow or heritage-breed lard to consumers seeking natural, unprocessed ingredients for culinary use.
- Geographic Culinary Exploration:Niche but growing interest in traditional and "nose-to-tail" cooking in North American and European culinary scenes opens new channels for high-quality, traceable animal fats in restaurants and specialty retail.
- Sustainability Certification:Developing and marketing products with origin and sustainability certifications, such as those from regenerative agriculture programs, can attract premium pricing and appeal to environmentally conscious buyers.
Industry Challenges
- Navigating Divergent Global Standards:Producers face the operational challenge of meeting disparate international food safety and labeling regulations, such as complying with both the USDA's requirements and China's GB standards for market access.
- Overcoming Negative Consumer Bias:Significant marketing and educational investment is required to counter the long-standing negative health image of animal fats, particularly when targeting younger or more health-aware demographics.
- Implementing Full Traceability:The capital expenditure and logistical complexity of establishing robust farm-to-fork traceability systems are substantial, yet increasingly demanded by major food service and retail clients for transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Animal Fat Market |
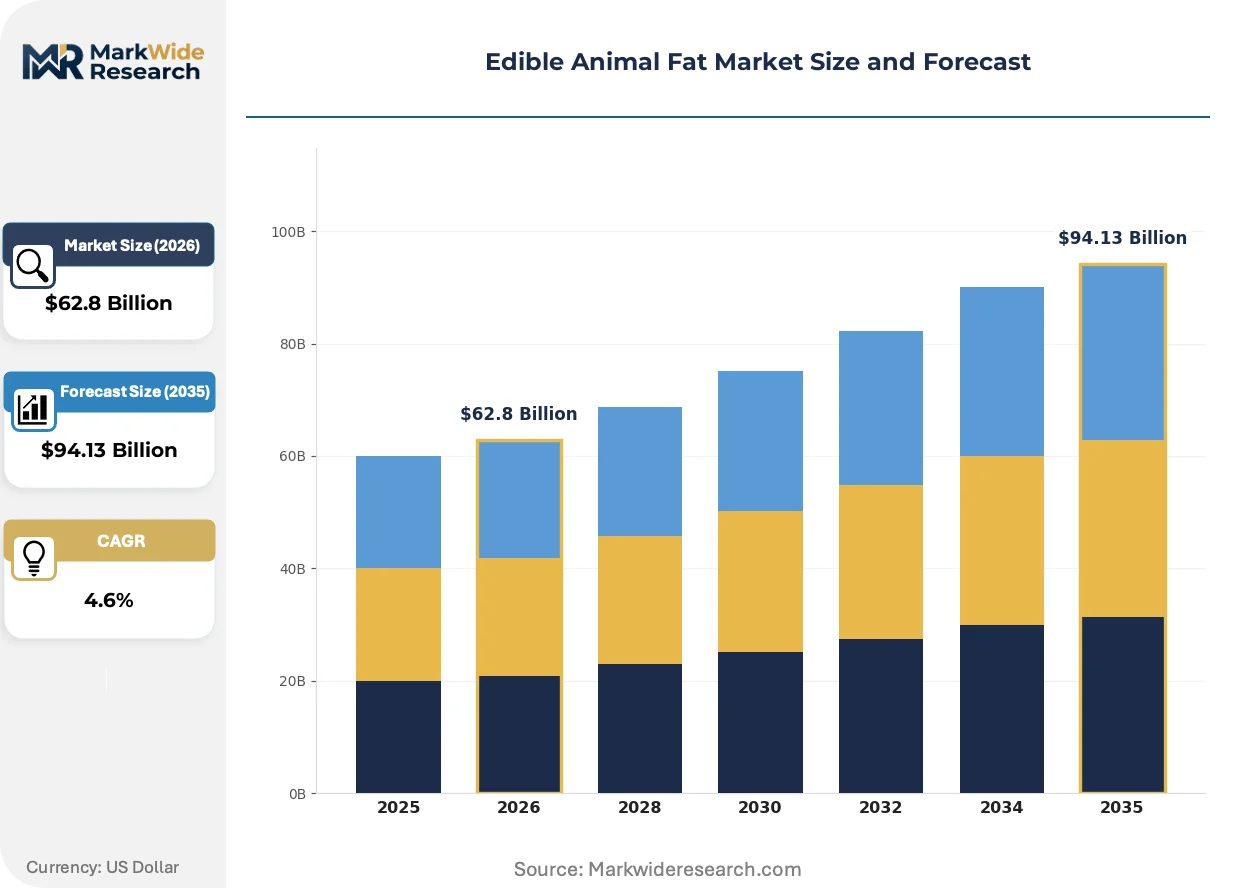
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $94.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lard, Tallow, Fish Oil, Butter, Suet Application: Baking, Confectionery, Frying, Meat Processing, Cosmetic Production End User: Food Manufacturers, Cosmetic Producers, Pharmaceuticals, Animal Feed Manufacturers, Soap Makers Packaging Type: Bulk Containers, Drums, Pails, Retail Packs, Tankers |
| Companies Covered | JBS S.A., Archer Daniels Midland Company, Darling Ingredients, Sanimax, Coast Packing Company, Tyson Foods, Inc., Bunge Limited, Ten Kate Vetten B.V., Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Animal Fat Market Strategic Shifts & Innovations
Modernization is reshaping the edible animal fat sector, as technological advancements in processing and a renewed focus on provenance challenge its commodity status. This evolution is driven by regulatory pressures on food safety and a clear demand-side shift toward ingredient transparency.
Advanced fractionation and rendering methods are creating new product tiers. These processes, such as low-temperature rendering, preserve delicate flavor compounds and create fats with specific melting points for specialized applications. High-end food manufacturers and culinary professionals are the primary adopters of these premium-grade fats. This technology is integrating with real-time quality monitoring to differentiate functional properties, turning a bulk commodity into a portfolio of specialty ingredients.
European Union food safety regulations, enforced by bodies like the EFSA, are setting a high bar for market participants. These rules mandate stringent limits on contaminants and require detailed country-of-origin labeling, increasing compliance costs for producers. The tallow and poultry fat segments supplying the EU are most affected, compelling investment in sophisticated purification technologies and comprehensive supply chain documentation to maintain market access.
A notable behavioral shift is the growing consumer and chef-led search for ingredient authenticity. This is disrupting traditional bulk-procurement models by creating a market for smaller-batch, single-origin products like Mangalitsa pork lard or Wagyu beef tallow. The trend is most pronounced in the artisanal food scenes of North America and Western Europe, where provenance is a key purchasing driver for high-end bakeries and restaurants.
Edible Animal Fat Market Segmentation
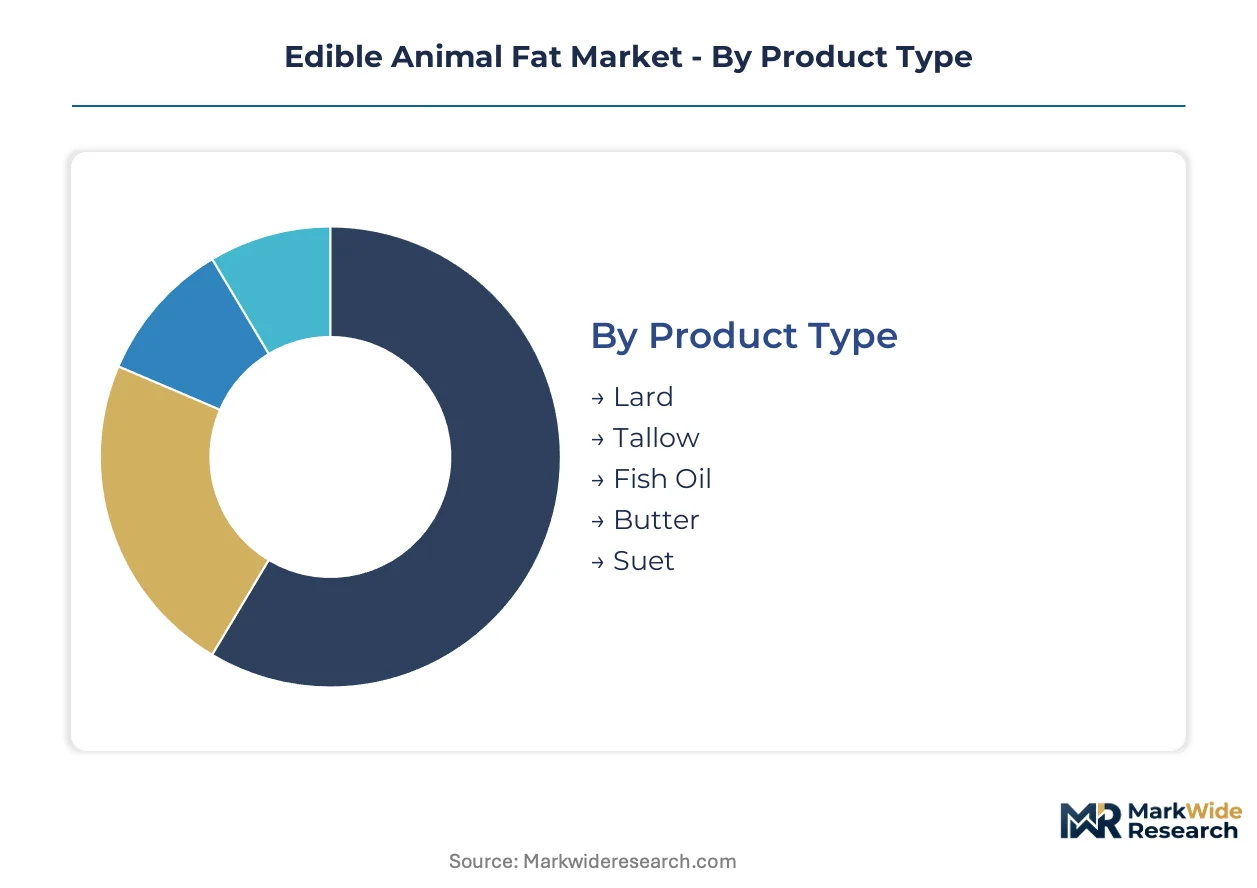
The edible animal fat market segments across diverse product types, applications, end users, and packaging formats. Understanding these distinct segments clarifies the varying demand drivers and supply chain requirements for producers. Each segment presents unique processing demands and market access strategies for manufacturers.
Product Type:
Capital investment in rendering facilities largely dictates the supply capabilities for different animal fat product types. Large-scale operations are essential for efficient production.
- Lard:This fat derived from pigs offers unique crystallization properties, providing flakiness and texture in baked goods. Demand concentrates in China, where it is integral to traditional cuisines.
- Tallow:Obtained from beef or mutton, tallow boasts a high smoke point, making it suitable for deep frying and industrial applications. European food manufacturers increasingly adopt tallow for its natural profile.
- Fish Oil:Sourced from fatty fish, this oil contains omega-3 fatty acids, primarily used in nutritional supplements and some food applications. Pharmaceutical companies in Japan utilize specific fish oil fractions.
- Butter:A dairy product, butter is consumed directly and used in baking and confectionery for its distinct flavor and rich mouthfeel. Confectionery producers in the United States value its creamy texture.
- Suet:This hard, white fat found around the kidneys of beef or lamb is traditionally used in British and Irish puddings and pastries. Artisanal bakeries in the United Kingdom use suet for authentic recipes.
Most installed capacity flows through Tallow. Expansion is steepest in Lard.
Application:
The cost tier of animal fats varies significantly by application, with high-volume industrial uses typically demanding more economical options. Specialized applications often command premium pricing for specific functional attributes.
- Baking:Animal fats like lard and butter are critical for achieving desired textures, such as flakiness in pastries and tenderness in cakes. Industrial bakeries in the United States prioritize these fats for product quality.
- Frying:Fats with high smoke points, particularly tallow, are favored for deep frying due to their stability and ability to impart flavor. Fast-food chains in India rely on animal fats for cost-effective frying.
- Confectionery:Fats contribute to the mouthfeel, texture, and flavor of chocolates, candies, and other sweet treats. European chocolate makers utilize specific animal fats for bloom control.
- Meat Processing:Animal fats are incorporated into sausages, processed meats, and spreads to enhance flavor, moisture, and binding properties. German meat processors use lard in traditional sausage recipes.
- Cosmetic Production:Lanolin and other animal fats serve as emollients, emulsifiers, and conditioning agents in skin creams, soaps, and hair care products. French cosmetic brands incorporate high-purity animal fats.
Demand volume concentrates in Baking. Market penetration is climbing the fastest in Cosmetic Production.
End User:
The customer type for edible animal fats ranges from large industrial processors to niche pharmaceutical companies, each with distinct volume and specification needs.
- Food Manufacturers:These entities represent the largest consumers, utilizing bulk animal fats in processed foods, baked goods, and convenience meals. Food manufacturers in China drive substantial bulk purchases.
- Cosmetic Producers:Companies in the beauty and personal care sector integrate animal fats for their emollient and skin-conditioning properties. Cosmetic brands in France demand highly purified fat derivatives.
- Pharmaceuticals:Specific animal fats, especially fish oils, are processed for their therapeutic fatty acid content in supplements and medicinal formulations. Pharmaceutical firms in Germany focus on omega-3 rich oils.
- Animal Feed Manufacturers:Rendered animal fats provide essential energy and nutrients in livestock and pet feed formulations. Brazilian animal feed producers are major users of by-product fats.
- Soap Makers:Tallow and lard are traditional ingredients in soap production due to their saponification properties, yielding hard, long-lasting bars. Artisanal soap makers in the United States value these fats.
The largest procurement volumes originate from Food Manufacturers. Niche adoption is gaining momentum among Cosmetic Producers.
Packaging Type:
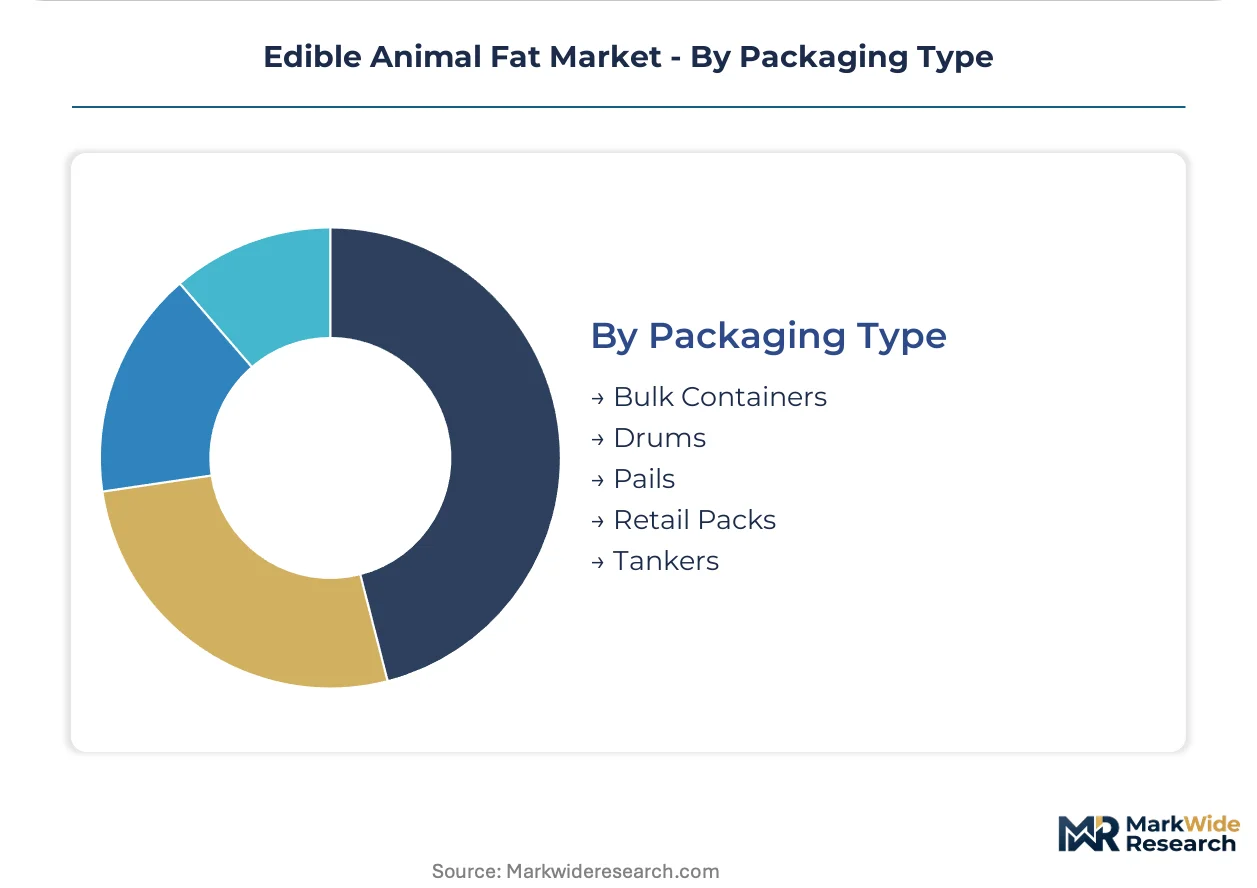
The volume of procurement dictates the preferred packaging type, ranging from massive tankers for industrial users to smaller retail packs for direct consumer sales.
- Bulk Containers:These large containers, often intermediate bulk containers (IBCs), facilitate the transport of substantial quantities of fat for industrial clients. Food ingredient suppliers in the United States use bulk containers extensively.
- Drums:Steel or plastic drums offer a mid-range volume solution for commercial kitchens and smaller manufacturing operations. European bakeries frequently receive fats in drum packaging.
- Pails:Smaller than drums, pails provide convenient handling for smaller commercial users or specialized culinary applications. Specialty restaurants in Canada procure fats in pail formats.
- Retail Packs:Designed for direct consumer purchase, these smaller packages typically include tubs, jars, or blocks for home cooking. Consumers in the United Kingdom purchase butter and suet in retail packs.
- Tankers:The largest volume option, tankers transport edible animal fats in liquid form for major food processing plants and rendering facilities. Large-scale processors in Brazil utilize tankers for inter-plant transfers.
Industrial procurement heavily favors Tankers. Growth in direct consumer sales is most evident in Retail Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's demand for edible animal fats is deeply rooted in cultural dietary staples, contrasting with the United States where regulatory shifts against trans fats drive renewed interest. European markets, particularly Germany, focus on high-purity fats for specialized applications. Brazil's large livestock industry supports significant fat production for animal feed.
China
Demand for lard in China remains robust, driven by its integral role in traditional regional cuisines and extensive use in food manufacturing. Compliance with GB standards for food safety is mandatory for all edible fat products entering the market. Major food manufacturers in Shanghai and Guangzhou drive substantial bulk purchases for local consumption.
United States
The United States market for edible animal fats benefits from the FDA's ban on partially hydrogenated oils, creating opportunities for natural alternatives like lard and tallow. USDA regulations ensure purity and labeling standards for domestically produced and imported fats. Industrial bakeries across the Midwest prioritize these fats for product quality and texture.
Germany
Germany demonstrates a growing focus on high-purity animal fats, particularly for pharmaceutical applications and specialized food manufacturing. EFSA regulations set stringent limits on contaminants and require detailed country-of-origin labeling for market access. Pharmaceutical firms in Bavaria concentrate on omega-3 rich fish oils for medicinal formulations.
Brazil
Brazilian animal fat consumption is largely driven by its significant livestock industry, providing abundant raw material for rendering into fats for animal feed. ANVISA oversees food safety and quality for edible fats, impacting both domestic production and exports. Animal feed producers in São Paulo are major users of by-product fats from meat processing.
India
India's market for edible animal fats sees significant demand from fast-food chains and food manufacturers for cost-effective frying applications. The FSSAI establishes food safety standards and guidelines for fat content and purity in processed foods. Food processing hubs like those in Gujarat and Maharashtra rely on animal fats for industrial-scale frying.
Edible Animal Fat Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining a market structure that is moderately consolidated at the large-scale industrial level but fragmented in niche artisanal sectors. Key strategic archetypes include integrated meat processors, specialized rendering companies, and ingredient suppliers. Competitive moves often involve capacity expansion to meet bulk demand and strategic partnerships for sourcing raw materials. Portfolio diversification into value-added fat ingredients also shapes the competitive landscape.
At the scale-driven end, integrated meat processors like JBS S.A. (a Brazilian multinational) and Tyson Foods, Inc. (a US-based company) represent major suppliers, leveraging their extensive meat processing operations for consistent raw material supply. These companies anchor the market through their large-scale production and integrated supply chains for various animal fats. Specialized rendering companies, such as Darling Ingredients (a US corporation), exemplify the focus on converting animal by-products into value-added fat ingredients. These entities highlight the industry's drive towards efficiency and product differentiation from commodity fats.
| Leading Market Players |
|---|
| JBS S.A. |
| Archer Daniels Midland Company |
| Darling Ingredients |
| Sanimax |
| Coast Packing Company |
| Tyson Foods, Inc. |
| Bunge Limited |
| Ten Kate Vetten B.V. |
| Cargill, Incorporated |
| Others |
Cost & Logistics Intelligence
Regulatory actions against trans fats in Western markets compel food manufacturers to reformulate, influencing procurement choices and creating new pricing dynamics for natural animal fats. This shift impacts the entire supply chain, from rendering facilities to end-user segments.
Pricing Analysis
Capacity additions in Brazilian rendering facilities are reshaping price floors for bulk animal fats, particularly those derived from beef and poultry. The dominant pricing structure operates as a hybrid model, combining commodity spot pricing for bulk orders with contract-based long-term offtake agreements for specialized grades. Price differentiation stems from origin certification programs and specific purity levels for pharmaceutical applications. Pricing pressure stems from the widespread availability of lower-cost plant-based alternatives. Fast-food chains represent the most price-sensitive buyers, while pharmaceutical firms prioritize purity over cost.
Supply Chain Analysis
Compliance with GB standards and EFSA regulations gates market access for edible animal fats, demanding rigorous purification and documentation. Geographic supply concentration draws from key livestock-producing nations like Brazil and the United States, alongside China's extensive pork industry. Raw material dependencies center on animal by-products from beef, pork, and poultry processing, alongside fish as a source for omega-3 oils. A structural risk is commodity price volatility, directly tied to global livestock market fluctuations. Distribution runs through a dual model, with tankers and bulk containers serving industrial users, and retail packs targeting direct consumer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The edible animal fat market functions as a stable compounder, driven by the enduring functional necessity of its products in traditional baking and culinary applications.
For Market Incumbents: Lock in long-term supply contracts with large food manufacturers to counter price volatility and competition from plant-based alternatives. Invest in advanced rendering technologies to produce specialized, high-purity fats that meet stringent regulatory standards. Deepen supply chain integration to secure consistent raw material access and control quality. Leverage origin certification as a lever against emerging niche players.
For New Entrants and Emerging Players: Begin with specialized, single-origin fat products targeting the growing "nose-to-tail" culinary movement. The artisanal food scene in North America and Western Europe presents a penetrable segment for premium, traceable fats. A direct-to-consumer go-to-market angle, emphasizing provenance and traditional culinary benefits, can build brand loyalty. Focus on smaller-batch production with transparent sourcing.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized rendering companies capable of producing high-purity, certified fats for pharmaceutical and premium food applications. The long-term viability of this market rests on the irreplaceable functional properties of animal fats in specific culinary uses. Target vertically integrated processors with strong certifications and established distribution channels into high-value segments. A signal to watch is increased M&A activity focused on companies with advanced fractionation capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Secures raw material supply for regional food manufacturers. |
| Sustainability Certification Program | Attracts premium pricing from environmentally conscious buyers. |
| Advanced Fractionation Investment | Creates specialized fat ingredients for high-end food manufacturers. |
| Partnership with Artisanal Bakeries | Expands reach into niche markets for premium lard products. |
| Research into Health Benefits | Counters negative consumer perceptions in Western markets. |
Research Approach
Bottom-up application-specific modeling reconciled against top-down raw material supply tracking forms the analytical core of this study. Primary interviews with food R&D directors, rendering plant managers, regulatory compliance officers, and purchasing managers at industrial bakeries provided qualitative insights. This was validated against secondary data from FDA filings, EFSA reports, China's GB standards, and global customs/trade records.
An input-output matrix captures the interdependencies between raw material availability and processed fat demand across the analysis window. Segmentation dimensions modeled include product type, application, end user, packaging format, and regional consumption patterns. Compound annual growth rates were derived from historical trends and projected market dynamics. Key industry-specific forecast inputs include global livestock production volumes and anticipated regulatory changes impacting fat utilization.
Several conditions sit outside the modeled scope, including unpredictable global economic downturns and rapid shifts in consumer health perceptions. Forecasts reflect assumptions regarding stable regulatory environments and consistent raw material supply. A model refresh is warranted upon material change in global livestock health or major trade policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Stock Cubes Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Savory Ingredients Market
Ingredients
African Brewing Enzymes Market
Ingredients
Non-GMO Oil Market
Ingredients
Europe Vegetable Oil Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Encapsulated Salt Market
Ingredients
Europe Feed Yeast Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Dairy Ingredients Market
Ingredients
Pet Food Premix Market
Ingredients
Orange Powder Market
Ingredients
Specialty Yeast Market
Ingredients
North America Protein Ingredients Market
Ingredients
Egg Replacement Ingredients Market