
 Meat Starter Culture Market | 2026-2036
Meat Starter Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Starter Culture Market Outlook
The EU Green Deal is repositioning raw material sourcing standards across European meat processing. Chr. Hansen A/S leverages its strain collection depth to dominate lactic acid bacteria supply for protected designation of origin sausages. DSM sustains competitive pressure through its fermentation expertise spanning enzyme and culture portfolios. Kerry Group anchors its position via backward integration into savory taste systems that bundle with starter cultures.
Meat starter cultures are defined as concentrated preparations of viable microorganisms, primarily lactic acid bacteria and coagulase-negative staphylococci, standardized to specific colony-forming unit counts and inoculated into raw meat to control fermentation pH, suppress pathogens, and develop organoleptic profiles. Powder formats retain cost leadership in high-volume sausage operations where dosing precision matters less than storage stability, while freeze-dried concentrates command premium placement among artisan producers seeking strain-specific aromatic performance. Application gravity sits with fermented meats where controlled acidification underpins shelf-life extension and safety validation, whereas dried meat segments represent a faster-growing adjacent as biltong and jerky producers adopt culture-directed flavor pathways.
EFSA safety qualified presumption of safety protocols shape strain approval timelines and limit market access for novel species, while REACH compliance governs excipient chemistry in culture carriers. USDA FSIS inspection mandates for fermented sausage processes create parallel compliance architecture for exporters targeting American buyers. Stakeholders must monitor evolving strain-level genome editing policies across the EU and US as regulatory divergence threatens to fragment R&D investment priorities.
Market Dynamics
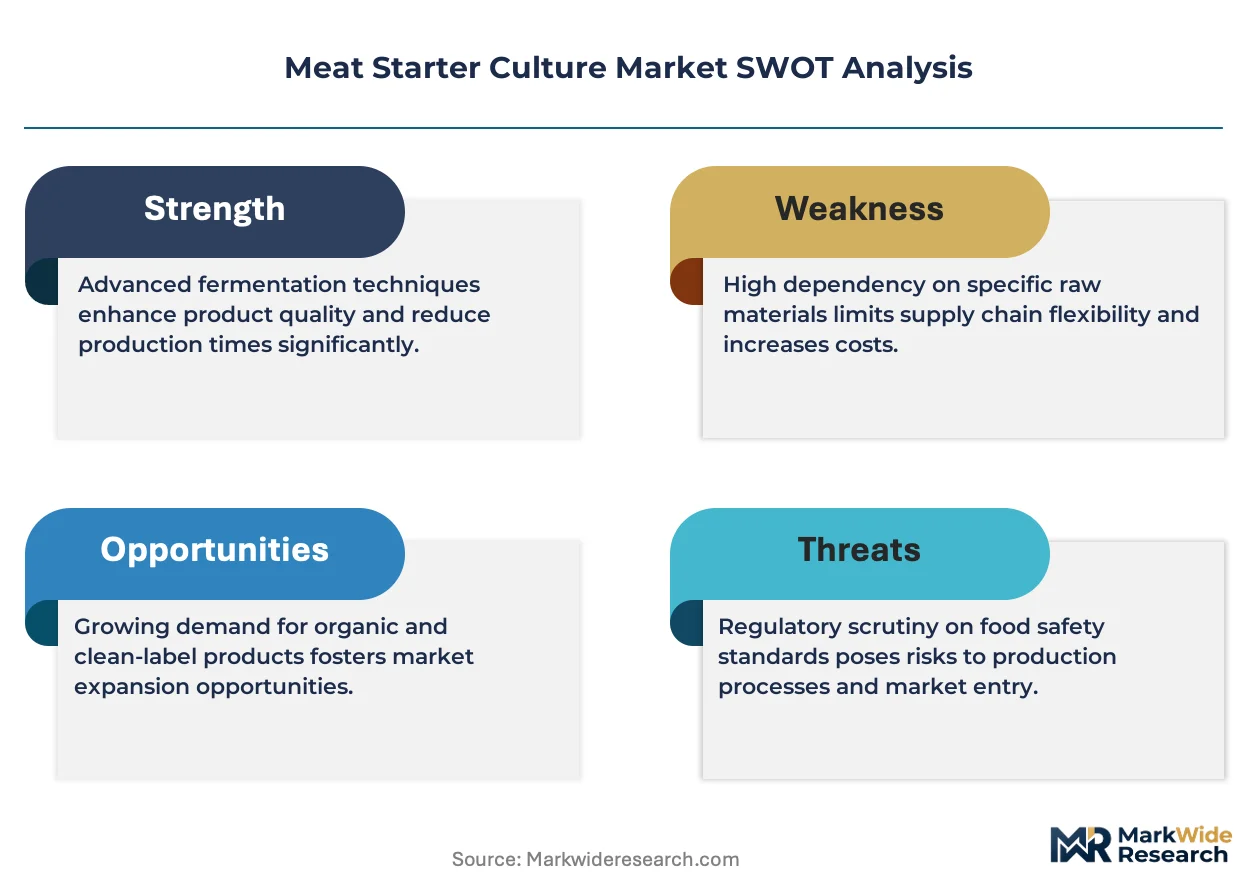
The EU Green Deal's food waste reduction mandates are tightening traceability requirements across European artisan meat processing, forcing starter culture suppliers to reconfigure strain documentation and sourcing protocols to maintain market access.
Growth Catalysts
- EU Green Deal compliance mandates:Food waste reduction targets are accelerating demand for precision-fermentation cultures that extend shelf life while satisfying ingredient traceability requirements for protected designation of origin products.
- Biltong and jerky producers:Dried meat segment manufacturers are adopting culture-directed flavor pathways to differentiate premium positioning against commoditized competitors.
- Freeze-drying technology:Concentrate formats are capturing artisan producer preference as strain-specific aromatic performance commands premium pricing over powder alternatives.
Market Restraints
- EFSA safety qualified presumption of safety protocols:Strain approval timelines extend development cycles and limit market access for novel species, compressing innovation pipelines.
- Excipient chemistry compliance:REACH regulations governing culture carrier materials add formulation complexity and testing costs for European market entry.
- Raw material concentration:Lactic acid bacteria strain collections concentrate among established biobanks, creating supply dependency for new entrants lacking proprietary libraries.
Strategic Opportunities
- USDA FSIS inspection alignment:Fermented sausage producers targeting American buyers can capture export premiums by building parallel compliance architecture alongside European operations.
- Genome editing policy convergence:Monitoring regulatory divergence between EU and US strain-level genome editing frameworks positions early movers to arbitrage R&D investment priorities.
- Savory taste system bundling:Backward integration into flavor systems creates differentiation against standalone culture suppliers in high-volume sausage operations.
Industry Challenges
- Strain characterization expertise:Fermentation microbiology specialization shortages constrain product development velocity as demand for customized aromatic profiles intensifies.
- Multi-jurisdiction certification timelines:Parallel EFSA and USDA validation requirements extend time-to-revenue for novel strain introductions, compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Starter Culture Market |
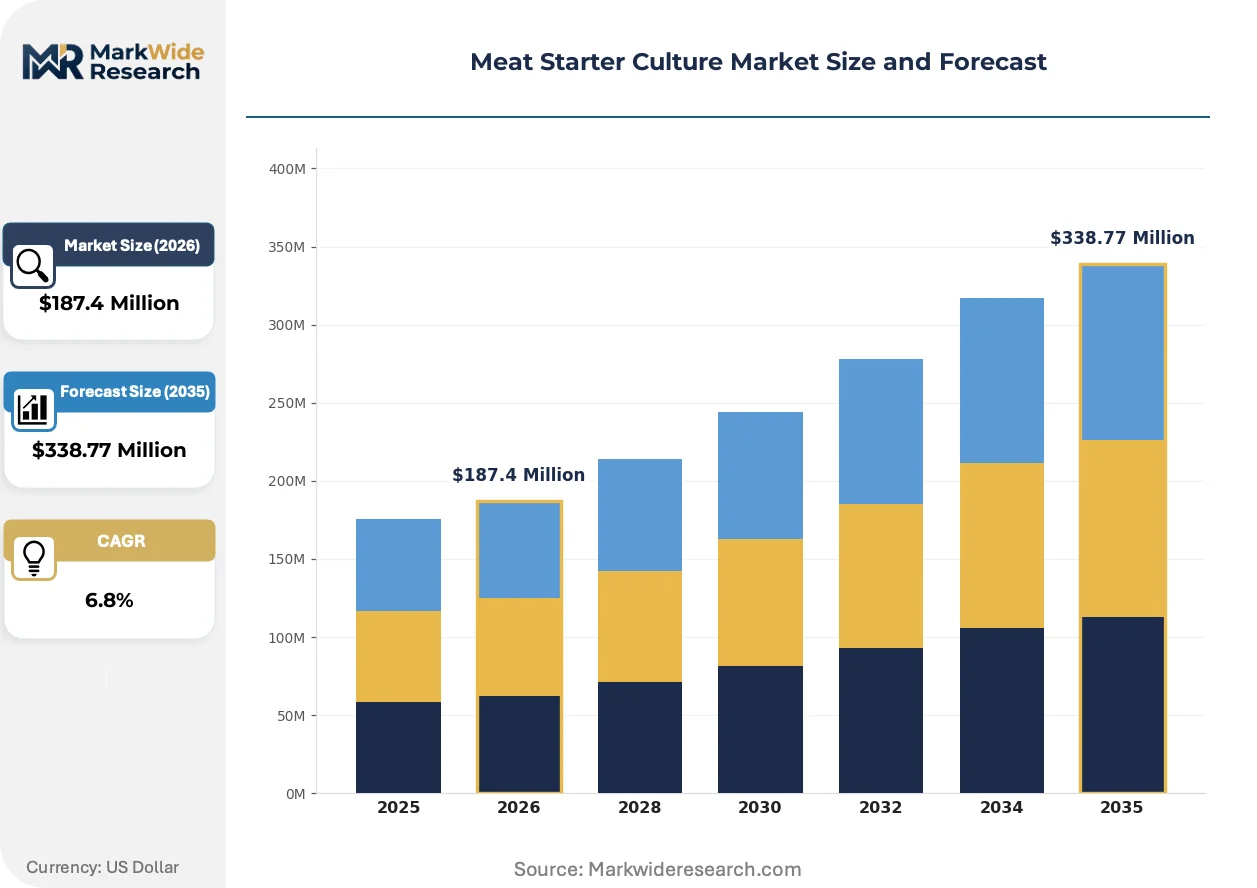
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Freeze-Dried Application: Sausages, Fermented Meats, Dried Meats, Cooked Meats End User: Food Manufacturers, Artisan Producers, Retailers, Restaurants Distribution Channel: Online, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Chr. Hansen A/S, DSM, Kerry Group, DuPont, Lallemand Inc., Biochem S.R.L., International Flavors & Fragrances Inc., Sacco System, CSK Food Enrichment B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Starter Culture Market Strategic Shifts
Active fermentation control technologies are displacing traditional time-dependent curing methods, while regulatory frameworks on both sides of the Atlantic diverge on strain innovation pathways. These forces are compressing product development cycles and reshaping supplier-customer technical relationships.
Next-generation sequencing for strain identification is expanding into quality assurance protocols across European protected designation of origin producers. German and Italian artisan sausage makers are adopting rapid genomic verification to authenticate terroir-linked fermentation profiles. This technology is expanding into supply chain transparency systems that satisfy EU Green Deal traceability mandates while defending premium positioning against industrial competitors.
EFSA's evolving stance on genome-edited microorganisms is creating regulatory uncertainty for strain developers targeting European markets. The agency's deliberation timeline on whether edited strains fall within existing novel food frameworks determines R&D allocation between European and American development centers. Fermented meat startups are responding by maintaining dual strain portfolios—conventional selections for EU commercialization and edited variants for jurisdictions with clearer gene-editing pathways.
Artisan producers are consolidating supplier relationships around technical service capabilities rather than commodity culture pricing. Small-batch cured meat operations in Italy and Germany now prioritize strain-specific aromatic consulting over per-kilogram cost minimization. This pattern concentrates purchasing power among culture houses with embedded application laboratories and sensory science expertise.
Meat Starter Culture Market Segmentation
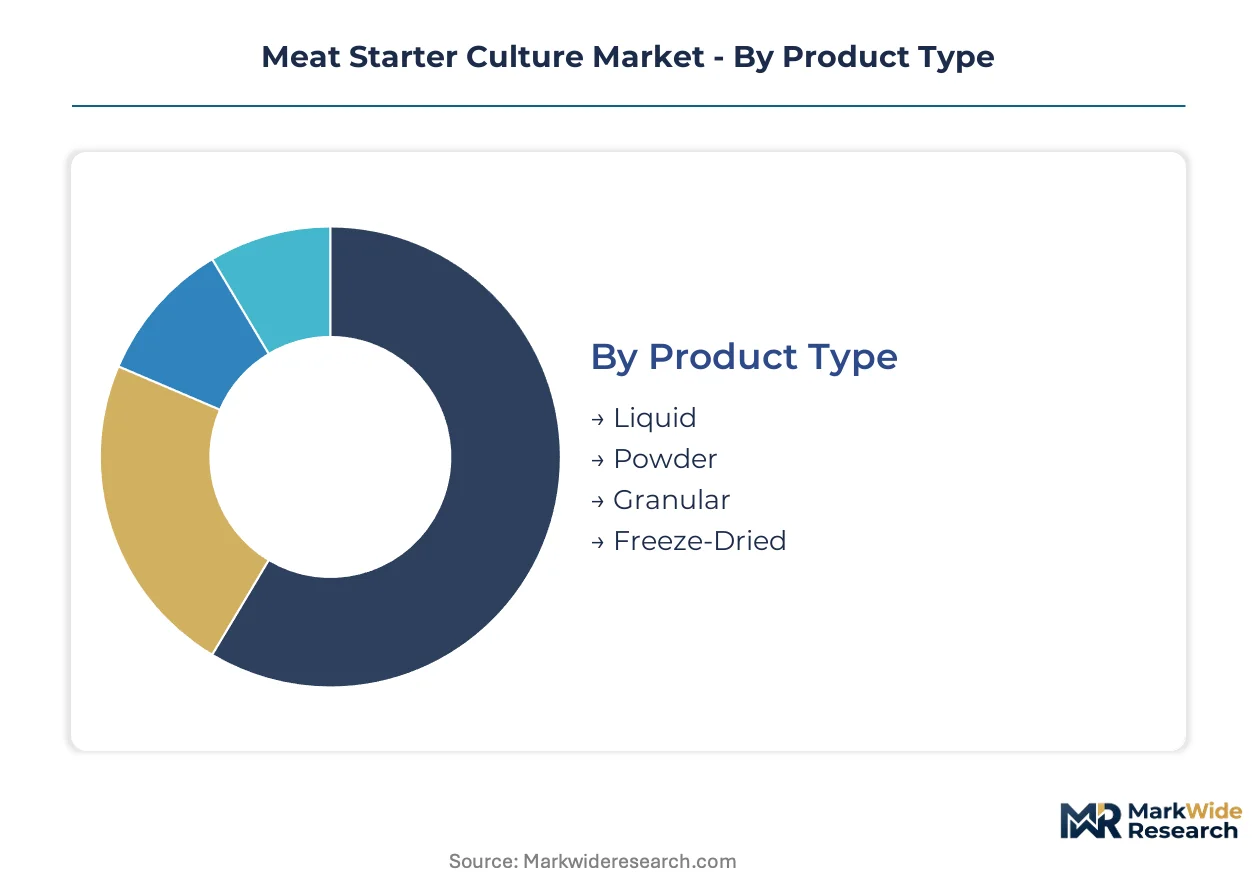
Meat starter culture suppliers configure their portfolios around format economics, application fermentation requirements, and customer technical sophistication. Each segmentation dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning across European artisan and industrial processing segments.
Product Type:
Powder formats dominate high-volume operations where storage stability outweighs dosing precision, while freeze-dried concentrates command premium placement among strain-specific aromatic seekers.
- Powder:Standardized lactic acid bacteria preparations with extended shelf life under ambient conditions. German industrial sausage operations favor this format for cost-efficient bulk inoculation where pH control consistency matters more than aromatic nuance. REACH compliance on carrier excipients adds formulation testing overhead for EU market entry.
- Freeze-Dried:Concentrated viable cultures preserved through sublimation dehydration, retaining strain-specific metabolic activity. Italian protected designation of origin producers pay premiums for these concentrates to achieve terroir-linked fermentation profiles that differentiate artisan positioning against commoditized competitors.
- Liquid:Ready-to-use aqueous suspensions requiring cold chain logistics. Food manufacturers with integrated fermentation lines prefer liquid formats for automated dosing precision.
- Granular:Free-flowing particulate cultures optimized for dry-blending operations. Dried meat processors in the Netherlands adopt granular formats for biltong and jerky production where moisture control is critical.
Today's leader: Powder. Tomorrow's challenger: Freeze-Dried.
Application:
Controlled acidification requirements vary sharply across meat categories, with fermentation depth determining culture specification intensity and regulatory validation burden.
- Fermented Meats:Raw-cured products relying on lactic acid bacteria-driven pH reduction for pathogen suppression and shelf-life extension. EFSA qualified presumption of safety protocols govern strain approvals, compressing innovation pipelines for novel species introductions. Artisan producers across Spain and France concentrate demand here.
- Sausages:Encased meat products spanning fresh, cooked, and fermented variants. German manufacturers drive volume demand for standardized cultures that ensure batch-to-batch consistency in protected designation of origin compliance.
- Dried Meats:Dehydrated products including biltong and jerky where culture-directed flavor pathways enable premium positioning. This segment is gaining share fastest as South African and American-style dried meat formats expand European penetration.
- Cooked Meats:Thermally processed products utilizing starter cultures primarily for flavor development rather than safety-critical acidification. Retail private label manufacturers represent the core demand base.
Fermented Meats anchor current revenue. Dried Meats present the steepest expansion trajectory.
End User:
Customer technical capabilities stratify purchasing criteria from commodity pricing to embedded sensory consulting.
- Food Manufacturers:Industrial-scale processors with integrated quality systems and automated fermentation controls. These buyers prioritize supply security and documentation depth for EU Green Deal traceability mandates.
- Artisan Producers:Small-batch operations emphasizing traditional methods and terroir authenticity. Italian and German cured meat specialists now select suppliers based on strain-specific aromatic consulting capabilities rather than per-kilogram cost.
- Retailers:Private label developers and store-brand meat product lines. Centralized procurement teams drive standardization across multiple co-manufacturer relationships.
- Restaurants:Foodservice operations with in-house curing programs. Michelin-starred establishments in Copenhagen and Paris represent niche demand for customized culture performance.
Artisan Producers currently command premium pricing power. Food Manufacturers represent the volume consolidation target.
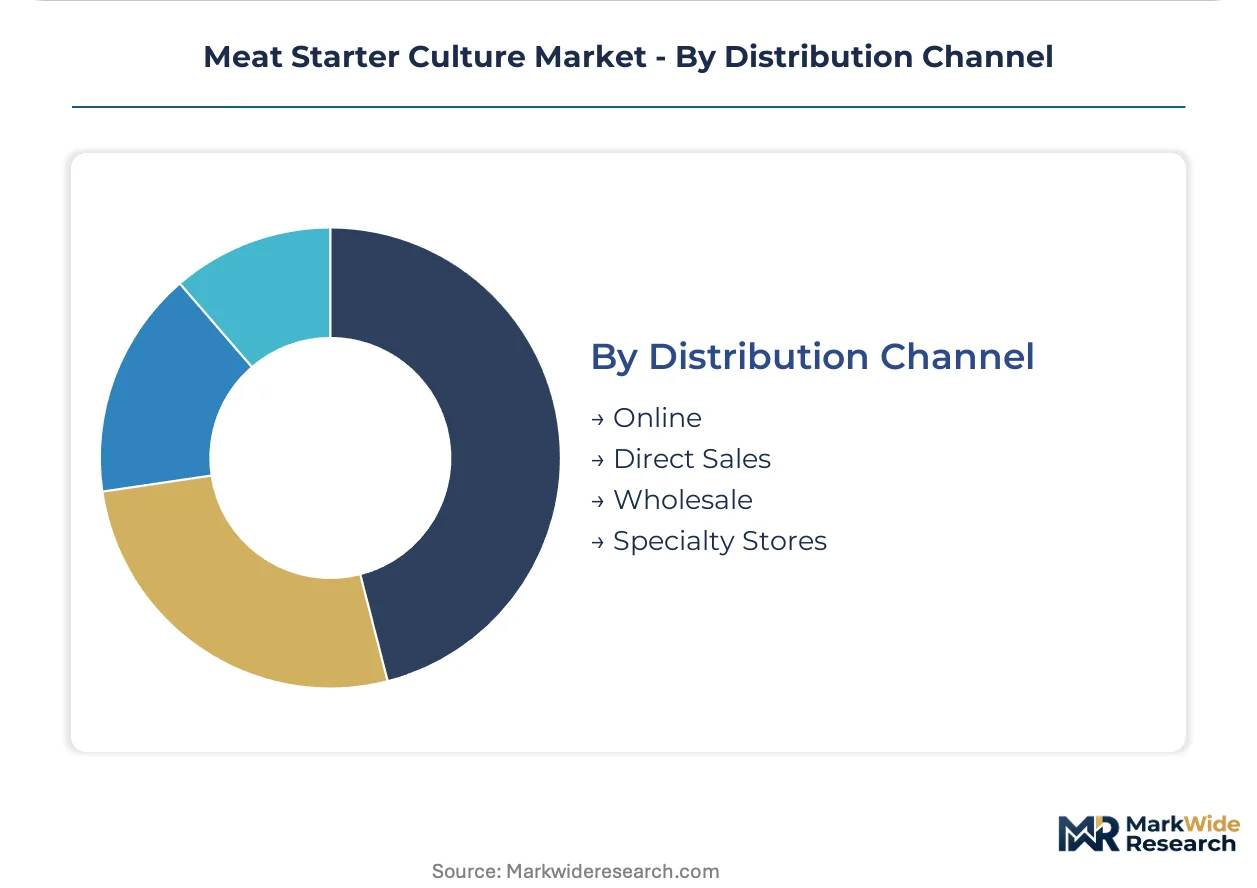
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and geographic concentration of meat processing clusters.
- Direct Sales:Technical representative relationships for large-volume accounts requiring strain customization. Chr. Hansen and DSM deploy dedicated fermentation specialists to major German and Italian sausage manufacturers.
- Wholesale:Distributor networks serving mid-tier processors across dispersed geographies. Regional food ingredient distributors hold inventory positions for just-in-time delivery.
- Online:E-commerce platforms enabling small-batch artisan access to specialized culture portfolios. This channel is expanding most quickly among startup cured meat operations seeking niche strain varieties.
- Specialty Stores:Physical retail points targeting hobbyist and small commercial producers. Equipment suppliers bundling cultures with fermentation chambers dominate this route.
Direct Sales retains the margin crown. Online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microbiologist concentrations in German sausage-producing regions anchor European starter culture demand, while Italian artisan curing traditions sustain specialized strain development capabilities.
Germany
Industrial sausage manufacturers in Lower Saxony and Bavaria drive standardized lactic acid bacteria consumption for protected designation of origin compliance. EFSA qualified presumption of safety protocols govern strain approvals for export-bound production. The Nuremberg metropolitan area hosts fermentation technology clusters where equipment makers co-locate with culture distributors.
Italy
Artisan cured meat producers in Emilia-Romagna and Lombardy prioritize strain-specific aromatic performance over per-kilogram cost minimization. EU Green Deal traceability mandates force documentation upgrades across Parmigiano-Reggiano supply chains. Parma's food technology institutes collaborate with regional culture houses on terroir-linked fermentation profiling.
United States
Biltong and jerky manufacturers in Colorado and Texas adopt culture-directed flavor pathways for premium positioning. USDA FSIS inspection mandates create parallel compliance requirements for fermented sausage exporters. The Wisconsin dairy-meat processing corridor attracts culture suppliers seeking cross-category fermentation expertise.
France
Charcuterie specialists in Auvergne-Rhône-Alpes maintain traditional curing methods while integrating genomic verification for supply chain transparency. ANSM and EFSA dual oversight extends approval timelines for novel strain introductions. Lyon-based food ingredient distributors serve as regional gateways for Southern European artisan producers.
Netherlands
Dried meat processors in North Brabant pioneer granular culture formats for moisture-critical biltong production. REACH compliance on excipient chemistry adds formulation testing overhead for culture carriers. Wageningen University's fermentation research programs supply technical talent to regional biotech clusters.
Meat Starter Culture Market Competitive Environment
Capital-heavy strain collection owners compete with asset-light formulation specialists across the meat starter culture supply base. Chr. Hansen A/S and DSM anchor the consolidated tier through proprietary lactic acid bacteria libraries, while regional distributors fragment the mid-market. Three archetypes dominate: biobank-integrated culture houses, savory taste system bundlers, and specialized fermentation consultants. M&A activity concentrates strain collections among fewer owners, while backward integration into flavor systems reshapes competitive boundaries.
Within the biobank-integrated tier, Chr. Hansen A/S represents the archetype of strain collection depth leveraged for protected designation of origin supply. DSM occupies a position spanning enzyme and culture portfolios through fermentation expertise aggregation. Kerry Group exemplifies the savory taste system bundler model, anchoring competitive position through backward integration into flavor systems that package with starter cultures.
| Leading Market Players |
|---|
| Chr. Hansen A/S |
| DSM |
| Kerry Group |
| DuPont |
| Lallemand Inc. |
| Biochem S.R.L. |
| International Flavors & Fragrances Inc. |
| Sacco System |
| CSK Food Enrichment B.V. |
| Others |
Value Chain & Pricing Dynamics
Artisan producer preference for strain-specific aromatic consulting over per-kilogram cost minimization forces culture houses to embed technical service capabilities into supply relationships, compressing margins on commodity powder formats while elevating premiums for freeze-dried concentrates with documented terroir performance.
Pricing Analysis
The bundled-vs-unbundled service split separates commodity powder suppliers from technical service-integrated culture houses. Three-tier pricing structure across premium, standard, and economy levels tracks format sophistication, with freeze-dried concentrates commanding premium placement against powder alternatives. Cost compression in standard powder tiers is intensifying because German industrial sausage manufacturers consolidate purchasing volumes. Food manufacturers exhibit highest price sensitivity due to automated dosing precision requirements, while Italian protected designation of origin producers show lowest sensitivity when strain-specific aromatic performance guarantees artisan differentiation.
Supply Chain Analysis
Direct-to-artisan channels handle specialized strain demand from Emilia-Romagna and Lombardy curing operations, while distributor networks serve dispersed industrial processors across Lower Saxony and Bavaria. Supply concentration centers on Denmark and the Netherlands for lactic acid bacteria strain collections, with Germany anchoring equipment-culture bundling partnerships. Raw material dependencies include specialized fermentation media, cryoprotectant excipients, and genomic verification reagents. Single-source vulnerability runs through proprietary strain libraries held by established biobanks. Distribution runs through regional food ingredient distributors holding inventory positions for just-in-time delivery to mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The meat starter culture market functions as a stable compounder, with EU Green Deal traceability mandates creating durable demand for documented strain provenance across protected designation of origin supply chains.
For Market Incumbents: Deploy backward integration into savory taste systems to bundle flavor development with starter culture supply, insulating against standalone culture commoditization. Expand application laboratory capabilities in Parma and Nuremberg clusters to deepen artisan producer lock-in through strain-specific aromatic consulting. Acquire regional distributors in fragmented Southern European markets to tighten channel control against emerging biotech entrants.
For New Entrants and Emerging Players: Enter via online channels targeting startup cured meat operations seeking niche strain varieties unavailable through established culture houses. Target the dried meat segment where biltong and jerky producers adopt culture-directed flavor pathways fastest. Pursue white-label supply relationships with equipment suppliers bundling fermentation chambers to bypass direct competition with Chr. Hansen and DSM strain libraries.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized fermentation consultants possessing embedded sensory science expertise and regional artisan relationships. The five-to-ten year viability window favors acquisition of mid-tier culture houses with proprietary terroir-linked strain portfolios but limited geographic reach. Monitor EFSA genome-edited microorganism policy clarity as the signal to watch for R&D investment inflection toward European versus American development centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flavor Systems | Kerry Group's savory taste bundling anchors competitive differentiation against standalone culture suppliers in high-volume sausage operations. |
| Application Laboratory Expansion | Chr. Hansen's embedded sensory consulting capabilities concentrate purchasing power among Italian and German artisan producers seeking strain-specific performance. |
| Online Channel Development | E-commerce platforms enable startup cured meat operations to access specialized culture portfolios without minimum volume requirements from direct sales teams. |
| Dual Strain Portfolio Maintenance | Fermented meat startups maintain conventional selections for EU commercialization and edited variants for jurisdictions with clearer gene-editing pathways. |
| Regional Distributor Acquisition | Mid-market consolidation captures dispersed artisan demand across Southern European curing traditions outside German and Italian concentration zones. |
Study Parameters
Bottom-up artisan and industrial processor modeling reconciled against top-down strain supplier tracking forms the analytical core. Primary interviews with fermentation microbiologists, quality assurance directors at protected designation of origin producers, procurement leads at German sausage manufacturers, and technical sales specialists at culture houses combined with secondary validation from EFSA qualified presumption of safety filings, EU Green Deal implementation reports, customs data on culture imports, and SEC 10-K disclosures from listed ingredient suppliers.
Input-output matrices mapped strain format demand against fermentation application requirements across the projection horizon. Segmentation dimensions modeled include product format, meat application category, end-user technical sophistication, and distribution channel structure. CAGRs were synthesized from volume trajectories in fermented versus dried meat segments and value capture differentials between powder and freeze-dried concentrate tiers. Forecast inputs incorporated EU regulatory approval timelines for novel strains and USDA FSIS inspection mandate evolution for export-bound production.
Inputs from EFSA safety assessments and culture supplier technical documentation were available through the study window; gaps in artisan producer strain-level genomic verification adoption rates introduce uncertainty bands around premium concentrate demand forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Australia Soy Protein Market
Ingredients
Bean Ingredients Market
Ingredients
Murumuru Butter Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Meat Extract Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Starches/Glucose Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
Banana Essence Market
Ingredients
Barley Flake Market
Ingredients
Cheese Cultures Market
Ingredients
Oat Fiber Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Bulk Food Ingredients Market