
 North America Fats and Oils Market | 2026-2036
North America Fats and Oils Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fats and Oils Market Intelligence
Non-GMO Project Verification is redrawing the competitive landscape for specialty oils in North America, creating a distinct premium tier. Large-scale agribusinesses like Cargill Incorporated leverage their extensive supply chains to offer a portfolio of both conventional and certified oils. Archer Daniels Midland Company competes by investing heavily in oilseed processing and refining capabilities across the United States and Canada. Smaller specialists such as Arista Industries differentiate through a focus on niche, high-value specialty oils.
Fats and oils are lipids composed primarily of triglycerides, extracted from plant sources like soybeans and canola or rendered from animal tissues. These substances are distinguished by their physical state at room temperature, with oils being liquid and fats being solid, a property determined by their fatty acid saturation levels. Vegetable oils command the largest market share due to their versatility and perceived health benefits. Within applications, the baking and confectionery segments sustain consistent demand, while the use of specialty oils in personal care represents a high-margin growth area.
The regulatory environment in North America is shaped by agencies like the U.S. Food and Drug Administration (FDA) and Health Canada. Their mandates on nutritional labeling, allergen declarations, and limits on trans fatty acids directly govern product formulation and market access for all producers. Producers must now navigate consumer demand for sustainability and traceability, shifting strategic focus toward transparent sourcing and certified supply chains.
Market Dynamics
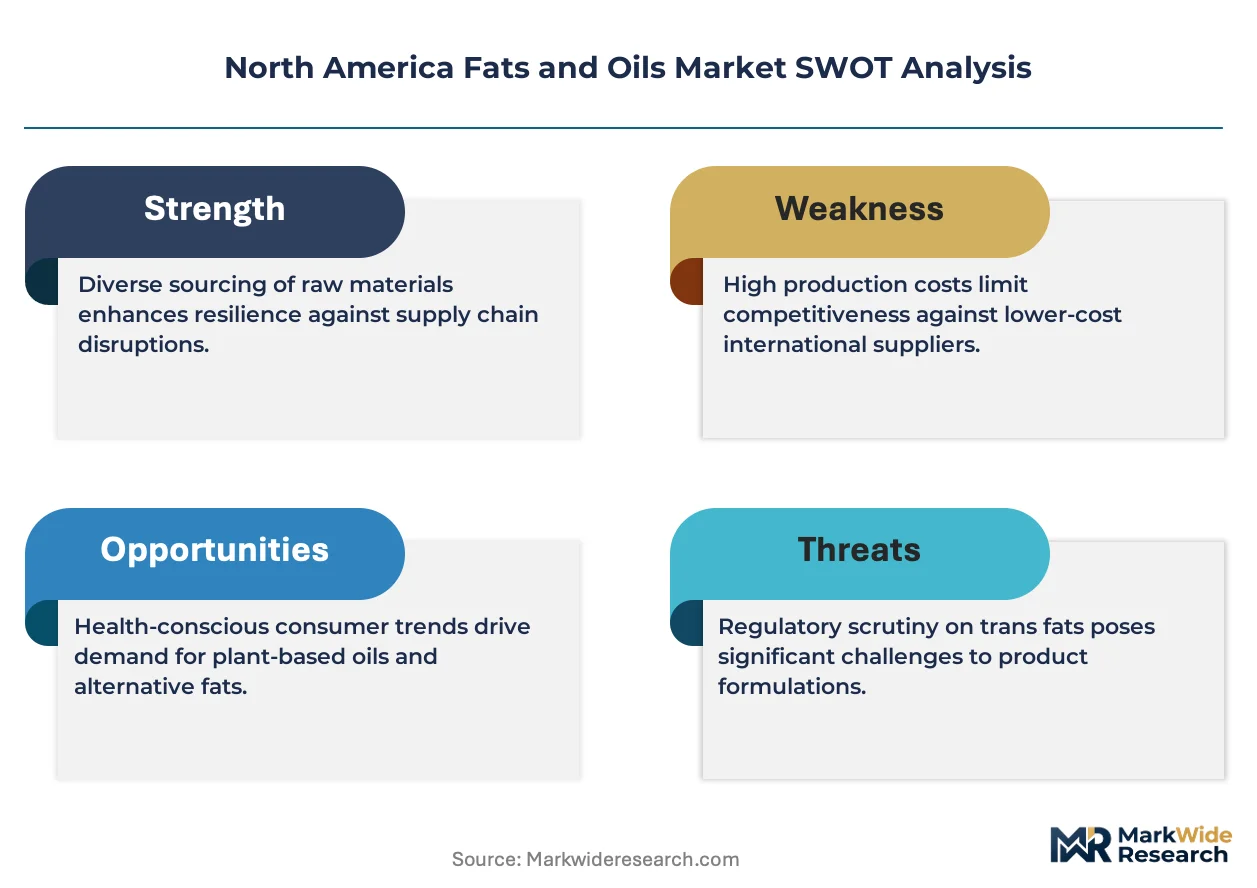
The fundamental dynamic shaping the North America Fats and Oils Market is the regulatory mandate to eliminate trans fats, forcing a complete re-evaluation of raw material sourcing and product formulation against a backdrop of volatile agricultural commodity prices.
Growth Catalysts
- Foodservice Demand for Performance:The North American foodservice sector's requirement for frying oils with extended fry life and improved nutritional profiles propels demand for high-stability variants like high-oleic canola and sunflower oils.
- Regulatory Reformulation Mandates:FDA regulations targeting partially hydrogenated oils (PHOs) act as a direct catalyst, compelling food manufacturers to adopt alternative fat systems, including palm oil fractions and interesterified fats.
- Personal Care Sector Expansion:The use of specialty vegetable oils and exotic butters as functional ingredients in cosmetics and personal care products provides a high-margin growth vector for suppliers.
Market Restraints
- Input Cost Volatility:The market is directly exposed to price fluctuations in oilseed commodities like soybeans and canola, which are influenced by weather events in key growing regions, global supply-demand imbalances, and trade policies.
- Substitution from Novel Ingredients:The development of new fat replacers and lab-grown lipids presents a long-term substitution threat, potentially eroding the market share of traditional plant-based and animal-derived fats.
- Cross-Border Regulatory Complexity:Producers face added compliance costs and logistical hurdles in navigating the distinct nutritional labeling and health claim regulations set by the FDA in the United States and Health Canada.
Strategic Opportunities
- Biolubricant and Industrial Applications:High-oleic vegetable oils offer a renewable and biodegradable alternative to mineral oil-based lubricants and hydraulic fluids, creating an opportunity in industrial applications where sustainability is a key purchasing criterion. *Specialty Blends for Processed Foods: Mexico’s expanding food processing industry presents an opportunity for suppliers to develop customized fat and oil blends tailored to local taste profiles and processing requirements for baked goods and snacks.
- Advanced Refining for Custom Profiles:Combining enzymatic interesterification with advanced fractionation techniques allows for the creation of structured lipids with specific melting points and fatty acid compositions, meeting precise functional needs in confectionery and infant formula.
Industry Challenges
- Dual Supply Chain Management:Maintaining segregated supply chains to ensure the integrity of Non-GMO Project Verified or organic oils alongside conventional products imposes significant logistical complexity and cost on processors and distributors.
- Traceability and Sustainability Verification:Documenting and verifying sustainability claims and oilseed origin from the farm level through the entire supply chain is an operational challenge that requires substantial investment in tracking systems and certification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fats and Oils Market |
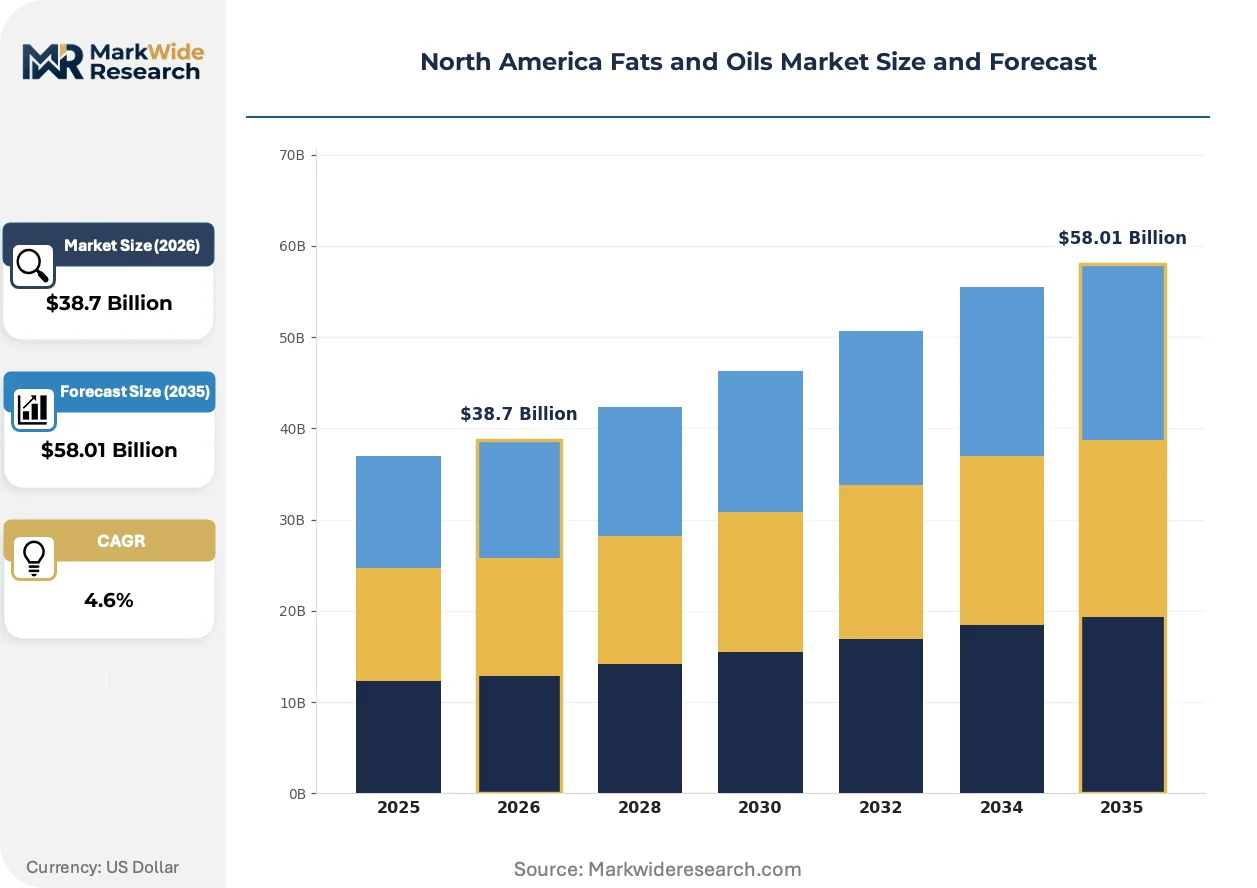
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oils, Animal Fats, Margarine, Shortening, Specialty Oils Application: Baking, Confectionery, Sauces, Snacks, Personal Care End User: Food Processing Companies, Foodservice Providers, Cosmetics Manufacturers, Pharmaceutical Firms Packaging Type: Bulk Containers, Glass Bottles, Plastic Jars, Metal Tins, Sachets |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Bunge Limited, AG Processing Inc., Wilmar International Ltd, Louis Dreyfus Company, Richardson International Limited, Olam International, Arista Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fats and Oils Market Strategic Shifts & Innovations
Product innovation is centered on creating functional replacements for trans fats that do not compromise texture or shelf life. This pursuit drives technological advancements in oil modification and blending, redefining the performance capabilities of plant-based lipids for food manufacturers.
High-stability oils, such as high-oleic soybean and sunflower varieties, are developed through conventional breeding or biotechnology to resist oxidation. Foodservice operators and large-scale food processors are the primary adopters, seeking to extend fry life and improve product stability. This adoption is bifurcating the market into a premium performance tier and a standard commodity tier, creating price differentiation based on fatty acid composition.
The FDA's final determination classifying partially hydrogenated oils (PHOs) as no longer Generally Recognized as Safe (GRAS) triggered a massive reformulation wave across the food industry. This regulatory action effectively eliminated the primary source of artificial trans fats from the U.S. food supply. The baking, confectionery, and snack food segments were most impacted, accelerating their transition to alternatives like palm oil, interesterified fats, and high-oleic liquid oils.
Consumer demand for clean labels and ingredient transparency is altering procurement patterns. This behavioral shift pressures food manufacturers to source oils with clear origins and desirable certifications, such as organic or Non-GMO Project Verified. The trend is most pronounced within the United States' natural and specialty food channels, where brand reputation is closely tied to supply chain integrity.
North America Fats and Oils Market Segmentation
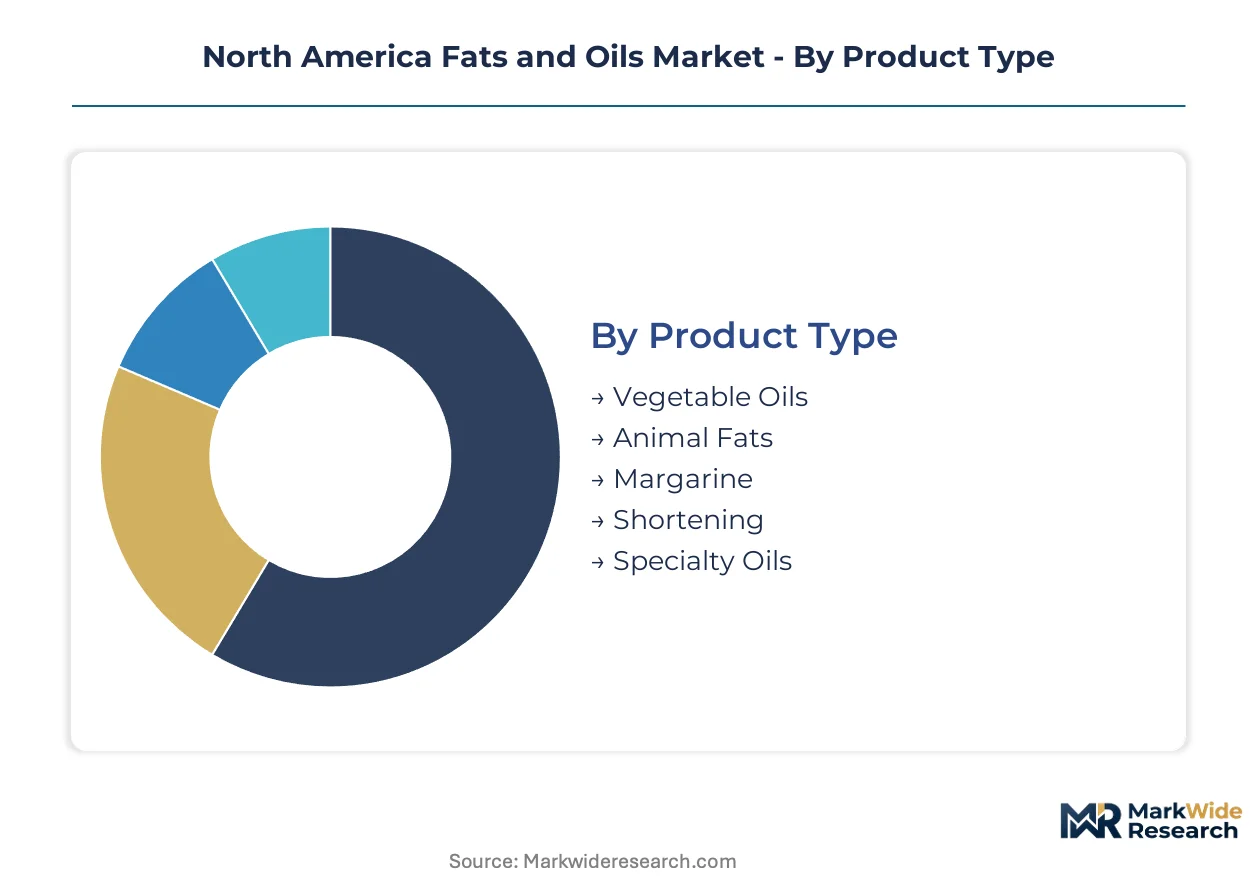
The North America fats and oils market is highly diversified, necessitating a granular segmentation to understand demand drivers and competitive dynamics. Analyzing these segments reveals where value is created and how various product formulations meet specific industrial and consumer needs across the region.
Product Type:
The North American fats and oils market exhibits distinct product type preferences, with some categories dominating domestic consumption and others serving broader export opportunities across the region.
- Vegetable Oils:These lipids are derived from plant sources such as soybeans, canola, and corn, characterized by their liquid state at room temperature due to unsaturated fatty acids. Demand concentrates in the United States due to extensive food processing needs and consumer preference for perceived health benefits.
- Animal Fats:Rendered from animal tissues, these are solid at room temperature and typically include lard and tallow, used in traditional cooking and some industrial applications.
- Margarine:This butter substitute is a water-in-oil emulsion, often made from vegetable oils, extensively used in baking and as a spread across North American households.
- Shortening:Solid fats, usually vegetable-based and interesterified, provide texture and structure in baked goods and frying applications for commercial users.
- Specialty Oils:These high-value oils, such as avocado, flaxseed, or grapeseed, offer unique nutritional profiles or functional properties. Their demand is rapidly expanding in Canada and the United States' natural food channels due to clean label and wellness trends.
Vegetable Oils commands the established base. The steepest expansion runs through Specialty Oils.
Application:
The diverse application landscape for fats and oils in North America reflects specific functional requirements and consumer preferences across various food and non-food sectors.
- Baking:Fats and oils provide structure, moisture, and mouthfeel in products like breads, cakes, and pastries, crucial for consistent product quality. This application sustains consistent demand throughout the United States and Canada, driven by the processed food industry's reliance on stable fat systems.
- Confectionery:These ingredients contribute to texture, gloss, and melt characteristics in chocolates, candies, and other sweet treats, appealing to consumer sensory experiences.
- Sauces:Fats and oils act as emulsifiers, flavor carriers, and texture modifiers in dressings, marinades, and prepared sauces for both retail and foodservice.
- Snacks:Used for frying and as a coating, fats and oils enhance crispness, flavor, and shelf life in chips, crackers, and other snack items.
- Personal Care:Specialty vegetable oils and exotic butters serve as emollients, moisturizers, and active ingredients in cosmetics, skincare, and hair care formulations. This high-margin segment sees significant growth in the United States, propelled by consumer interest in natural and clean beauty products.
Baking represents a foundational application. The Personal Care sector is experiencing the most rapid growth.
End User:
The North American fats and oils market serves a concentrated set of end-user segments, each with distinct procurement needs and volume requirements.
- Food Processing Companies:These large-scale manufacturers use fats and oils as essential ingredients in a vast array of packaged foods, from ready meals to snacks. Their demand is driven by the need for consistent ingredient quality and functional properties across high-volume production lines in the United States.
- Foodservice Providers:Restaurants, cafeterias, and catering services require fats and oils for frying, cooking, and salad preparation, prioritizing performance attributes like extended fry life. Demand from this sector in Canada and Mexico is increasing for healthier oil profiles to meet consumer expectations.
- Cosmetics Manufacturers:These firms integrate specialty oils and butters into their formulations for skin, hair, and beauty products, emphasizing purity and functional benefits.
- Pharmaceutical Firms:Fats and oils serve as excipients, carriers, or active ingredients in certain drug formulations and nutritional supplements, requiring high purity standards.
Food Processing Companies form the largest customer base. Foodservice Providers are driving the quickest expansion.
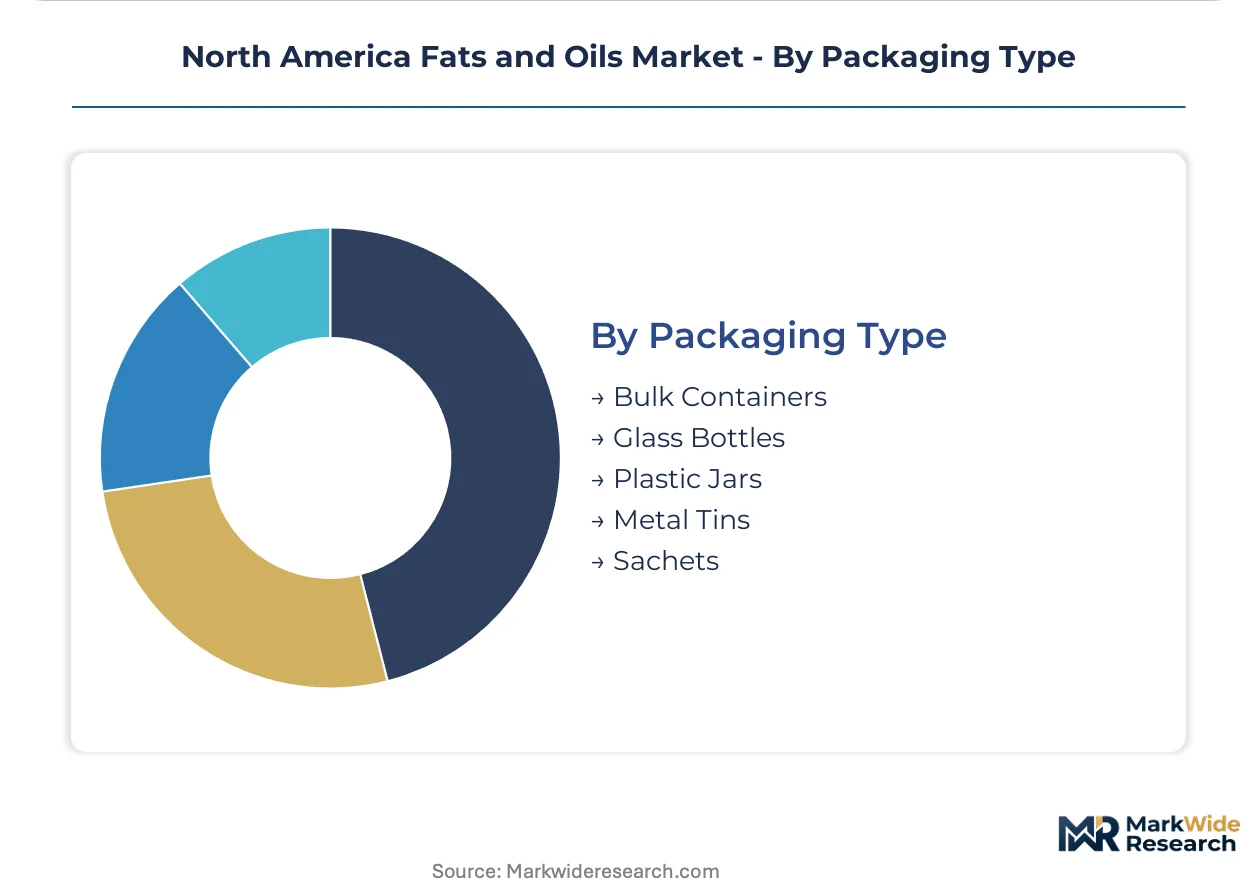
Packaging Type:
Packaging solutions for fats and oils in North America are highly diversified, reflecting the varied scale of operations from industrial processors to individual consumers.
- Bulk Containers:These large-volume packaging options, such as drums, totes, and tanker trucks, are primarily utilized by industrial food manufacturers and processors. Their use optimizes logistics and reduces costs for high-volume ingredient delivery across the entire region.
- Glass Bottles:This packaging type often signifies premium or specialty oils, protecting product integrity and appealing to consumers seeking transparency and quality. Demand for glass-packaged oils is notable in the United States' gourmet and natural food retail channels.
- Plastic Jars:Commonly used for margarine, shortening, and cooking oils, plastic jars offer convenience and cost-effectiveness for retail consumers.
- Metal Tins:These containers provide excellent shelf life and protection from light and air, frequently used for olive oil and specialty cooking fats in retail.
- Sachets:Small, single-serve pouches of oils or fats cater to convenience-focused consumers and portion control needs in foodservice settings.
Bulk Containers dominate industrial supply. Glass Bottles are gaining share most rapidly in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The integrated agricultural trade routes, including extensive rail networks and river systems across North America, underpin the market's regional dynamics. These infrastructure assets facilitate the efficient movement of raw materials and finished products, supporting diverse processing and consumption hubs. The region's regulatory alignment on certain food safety standards also aids cross-border commerce.
United States
Demand for fats and oils in the United States stems from its vast food processing industry and consumer preference for healthier oil profiles. FDA regulations, particularly those targeting partially hydrogenated oils, have compelled manufacturers to reformulate products. Major processing facilities in the Midwest, such as those in Illinois and Iowa, concentrate on soybean and corn oil production for both domestic and export markets.
Canada
Canadian foodservice providers drive demand for high-stability frying oils, while the personal care sector expands its use of specialty oils. Health Canada's nutritional labeling requirements influence product development and ingredient selection. The Prairie Provinces, including Manitoba and Saskatchewan, serve as a primary hub for canola oil production and processing, supplying both Canadian and US markets.
Mexico
Mexico’s expanding food processing industry presents a significant opportunity for customized fat and oil blends tailored to local taste profiles. National health authorities are increasingly focused on improving dietary health, which impacts ingredient choices. Central Mexico, particularly around Jalisco and Mexico City, harbors a growing concentration of food manufacturing plants requiring diverse fat and oil inputs.
North America Fats and Oils Market Key Industry Players
Listed leaders compete with private specialists across supply chain integration and product portfolio breadth within the North American fats and oils market. The competitive structure features large-scale agribusinesses alongside niche producers focusing on high-value segments. Key competitive moves involve strategic partnerships for supply chain resilience and portfolio diversification into specialty oils.
Among the integrated agribusinesses, Cargill Incorporated leverages its extensive supply chains to offer a wide range of conventional and certified oils. Archer Daniels Midland Company competes by investing heavily in oilseed processing and refining capabilities across the United States and Canada. Smaller specialists like Arista Industries differentiate through a focus on niche, high-value specialty oils, catering to specific market demands.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Bunge Limited |
| AG Processing Inc. |
| Wilmar International Ltd |
| Louis Dreyfus Company |
| Richardson International Limited |
| Olam International |
| Arista Industries |
| Others |
Cost & Logistics Intelligence
The substitution of partially hydrogenated oils with alternative fat systems like palm oil and high-oleic variants is reshaping North American supply chains. This shift introduces new sourcing geographies and creates distinct pricing tiers for specialized ingredients.
Pricing Analysis
Volume-discount tiering structures characterize pricing for conventional fats and oils in North America. Price differentiation stems from quality grade and certification level, particularly for Non-GMO Project Verified products. Pricing softness affects commodity-grade vegetable oils due to volatile agricultural commodity prices. Food processing companies are highly price-sensitive for bulk ingredients, while specialty oil buyers prioritize unique functional properties over cost.
Supply Chain Analysis
Just-in-time inventory practices dominate the North American fats and oils supply chain for high-volume commodities. Supply concentration centers on major oilseed producing regions: the U.S. Midwest for soybeans and Canada's Prairie Provinces for canola. Raw material dependencies include soybean, canola, and palm oil. Commodity price volatility presents a significant structural risk, impacting procurement costs. Distribution primarily runs through large agribusinesses and specialized ingredient distributors to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America fats and oils market offers a fragmentation opportunity, driven by consumer demand for clean labels and ingredient transparency. This shift creates lucrative niches for specialty and certified oils.
For Market Incumbents: Fortify existing market share by investing in advanced refining capabilities for high-oleic oils to counter substitution from novel ingredients. Expand sustainable sourcing programs and obtain Non-GMO Project Verification for core product lines. This mitigates brand reputation threats and addresses evolving regulatory scrutiny from agencies like the FDA. Control over distribution channels remains a critical lever.
For New Entrants and Emerging Players: Customized blending services for small to mid-sized food manufacturers represent an underserved segment. Target the rapidly expanding personal care sector in the United States with exotic butters and specialty oils. Focus on transparent, traceable supply chains and unique functional profiles as a go-to-market angle. Mexico's expanding food processing industry also presents specific regional white-space opportunities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized specialty oil processors and ingredient blenders, offering long-term viability over a five-to-ten-year window. Target these agile firms with established niches in the personal care or natural food channels. These companies often possess proprietary blending technologies or unique sourcing relationships. A key signal to watch is the sustained growth in consumer demand for certified and sustainably sourced oils.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Refining Capacity Expansion | Increases supply of high-stability oils for foodservice providers, meeting performance demands. |
| Non-GMO Project Verification Investment | Secures premium market access for specialty oils, aligning with consumer clean label trends. |
| Customized Fat Blend Development | Addresses specific functional needs of Mexico’s expanding food processing industry. |
| Traceability System Implementation | Ensures compliance with regulatory mandates and builds consumer trust in sourcing. |
| Partnerships with Personal Care Brands | Captures high-margin growth in the United States' natural beauty product segment. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association reports, and commodity market data. Primary interviews engaged procurement leads at food processing companies, R&D directors in personal care, and operations managers at foodservice providers. This approach triangulated insights from both top-down market analysis and bottom-up supply chain perspectives. Industry experts also contributed to validating market sizing and segmentation drivers.
Product type, application, end-user, packaging type, and regional adoption patterns formed the core segmentation dimensions modeled. The analytical framework projected market evolution across the analysis window, deriving compound annual growth rates from historical trends and future demand drivers. Key industry-specific forecast inputs included oilseed crop yields and consumer preference shifts towards healthier oil profiles. This ensured a granular and relevant market outlook.
Material uncertainties — including unforeseen geopolitical events and extreme weather patterns impacting crop yields — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and sustained consumer trends. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fish Gelatin Market
Ingredients
Caramel Malt Market
Ingredients
Specialty Yeast Market
Ingredients
China Gelatin Market
Ingredients
Tryptose Market
Ingredients
Soy Protein Isolate Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Honey Powder Market
Ingredients
Konjac Flour Market
Ingredients
Arrowroot Starch Market
Ingredients
Tapioca Pearls Market
Ingredients
Yeast Derivatives Market
Ingredients
Global Distillers Grains Market
Ingredients
Oyster Shell Powder Market
Ingredients
Yeast Autolysates Market
Ingredients
2'-Fucosyllactose (2'-FL) Market