
 Drum Dumper Market | 2026-2036
Drum Dumper Market Size, Share, and Industry Trends Forecast 2026-2036
Drum Dumper Market Analysis
A capital-intensity divergence between domestic fabricators and multinational automation specialists is reorganizing competitive tiers in drum handling equipment. Vestil Manufacturing Corp. leverages its North American manufacturing footprint to control distribution costs across standard-capacity lines. National Bulk Equipment, Inc. differentiates through integrated bulk material handling systems that extend beyond standalone dumpers into complete process circuits. Flexicon Corporation anchors its position with custom-engineered pneumatic and hydraulic configurations for chemical and food processing clients.
A drum dumper is a material handling machine engineered to lift, invert, and discharge contents from standard 55-gallon drums or comparable cylindrical containers, typically achieving dump angles between 45 and 180 degrees depending on flow characteristics of the handled material. The equipment serves primary industrial purposes of eliminating manual lifting hazards, ensuring complete product evacuation, and maintaining containment during transfer of powders, granules, liquids, or viscous substances. Hydraulic dumpers occupy the largest share of product type revenues due to their force output reliability and compatibility with heavy, dense materials in chemical industries. Food processing end users represent the fastest-expanding demand pool, driven by FDA-compliant stainless steel construction requirements and clean-in-place design protocols. Medium capacity units concentrate margin pools by balancing purchase accessibility with sufficient throughput for mid-scale pharmaceutical and specialty chemical operations.
OSHA ergonomic and machine guarding standards directly shape dumper design specifications in the United States, while the EU Machinery Directive and CE marking requirements govern safety interlocks and risk assessments for European deployments. FDA 21 CFR Part 110 and subsequent food safety modernization rules compel stainless steel contact surfaces and sanitary welds in equipment destined for food and pharmaceutical environments. Buyers must monitor evolving carbon footprint disclosure obligations under the EU CSRD, as these will soon extend to capital equipment procurement criteria across multinational manufacturing footprints.
Market Dynamics
Automated material handling mandates from OSHA and the EU Machinery Directive are compressing replacement cycles for legacy drum handling equipment, forcing mid-scale chemical processors to accelerate capital expenditure timelines for compliant dumpers.
Growth Catalysts
- REACH workplace safety mandates:European chemical manufacturers must eliminate manual drum handling hazards, creating immediate replacement demand for interlocked hydraulic systems with certified guarding.
- Pharmaceutical sterile production protocols:FDA 21 CFR Part 110 compliance requirements in the United States are driving stainless steel dumper procurement for cleanroom-adjacent material transfer operations.
- Food processing automation:Clean-in-place design standards are expanding dumper deployment beyond traditional chemical applications into high-volume bakery and dairy operations.
Market Restraints
- Steel price volatility:Fluctuations in cold-rolled stainless steel input costs compress margin predictability for fabricators serving price-sensitive mid-cap buyers.
- Specialized hydraulic component concentration:Precision cylinder and valve sourcing concentrates among German and Japanese suppliers, exposing lead time risk for North American assemblers.
- Pneumatic dumper performance ceiling:Compressed air systems face force output limitations that exclude them from dense ceramic slurry and metal powder applications.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO regulatory harmonization with ICH standards is attracting sterile API production investment requiring hygienic material handling infrastructure.
- Brazil agrochemical formulation:ANVISA environmental containment rules for pesticide manufacturing are creating demand for sealed dumper configurations with vapor recovery integration.
- EU CSRD carbon disclosure:Scope 3 emissions tracking requirements will soon mandate energy-efficient dumper specifications in multinational procurement criteria.
Industry Challenges
- Certification timeline compression:CE marking and FDA validation documentation requirements extend order-to-delivery cycles, straining working capital for project-driven dumper manufacturers.
- Legacy control system integration:Retrofitting automated dumpers into existing SCADA architectures demands specialized protocol translation expertise that resides with a narrow pool of systems integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum Dumper Market |
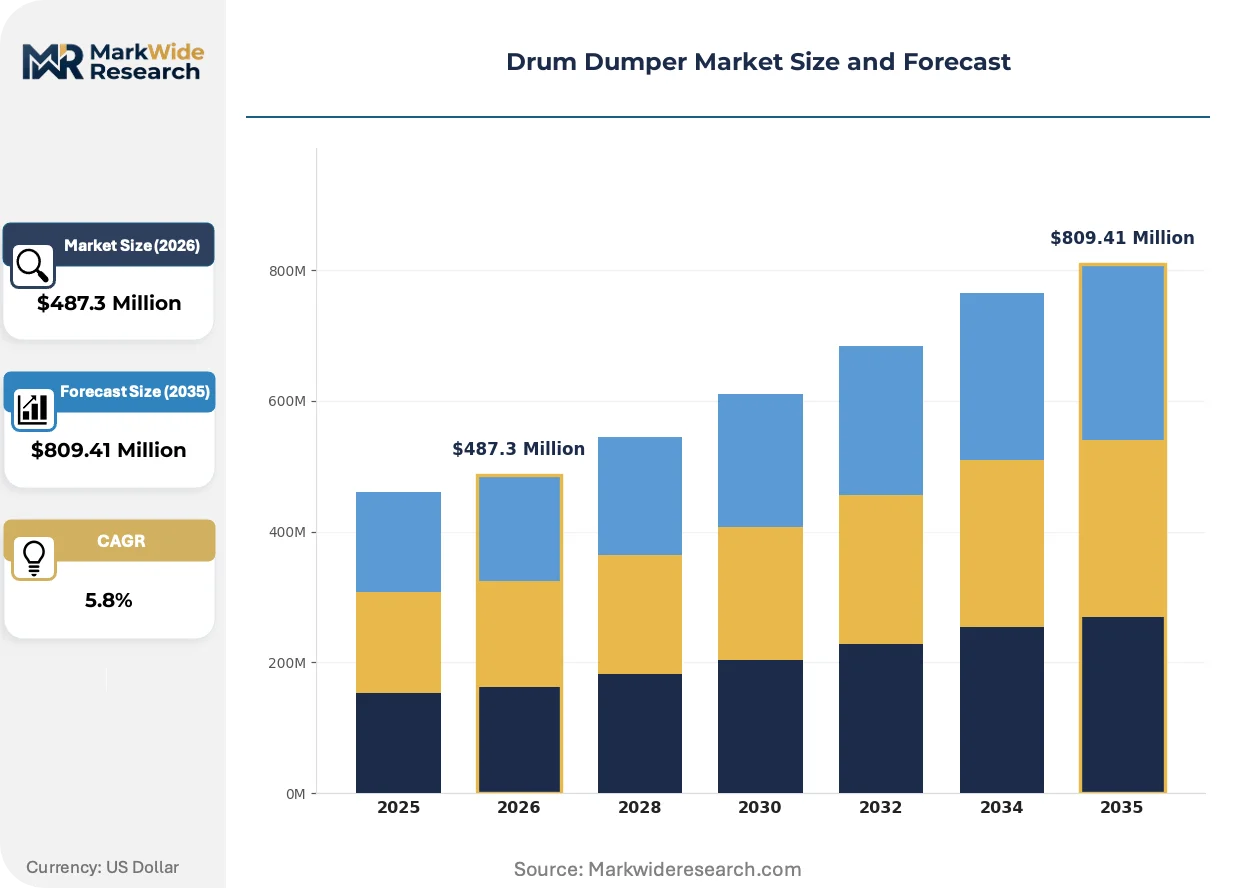
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Dumpers, Pneumatic Dumpers, Electric Dumpers, Manual Dumpers End User: Manufacturing Facilities, Food Processing, Pharmaceutical Companies, Chemical Industries Capacity: Small Capacity, Medium Capacity, Large Capacity, Industrial Capacity Installation: Fixed Installation, Mobile Installation, Semi-Permanent Installation, Custom Installation |
| Companies Covered | Vestil Manufacturing Corp., National Bulk Equipment, Inc., Beacon Industries, Liftomatic Material Handling, Inc., METO Systems, Valley Craft Industries, Inc., Flexicon Corporation, Wuxi Tongyang Machinery Technology Co., Ltd., Morse Manufacturing Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum Dumper Market Emerging Trajectories
Electrification of actuation systems and sensor-enabled predictive maintenance are redefining equipment lifecycle economics, while regulatory disclosure requirements are embedding sustainability metrics into procurement evaluation frameworks.
Brushless DC electric drive systems are supplanting conventional hydraulic power units in food and pharmaceutical installations where oil contamination risk is unacceptable. Medium-capacity processors in Germany and Switzerland are adopting these configurations for their reduced maintenance intervals and elimination of hydraulic fluid disposal costs. The shift is compressing aftermarket service revenue pools historically tied to seal replacement and fluid management.
The EU CSRD corporate sustainability reporting directive is mandating embodied carbon disclosure for capital equipment purchases above defined thresholds. Chemical manufacturers in the Netherlands and France must now document supplier environmental footprints, creating procurement preference for dumpers with verified lifecycle assessments. Equipment vendors are responding by securing ISO 14040-compliant environmental product declarations for standard product lines.
Equipment-as-a-service contracting is displacing outright purchase arrangements among North American contract manufacturing organizations facing capital constraint. Monthly utilization-based payment structures bundle maintenance, compliance updates, and technology refresh cycles. This model concentrates most visibly in pharmaceutical toll manufacturing operations where production campaigns fluctuate seasonally.
Drum Dumper Market Segmentation
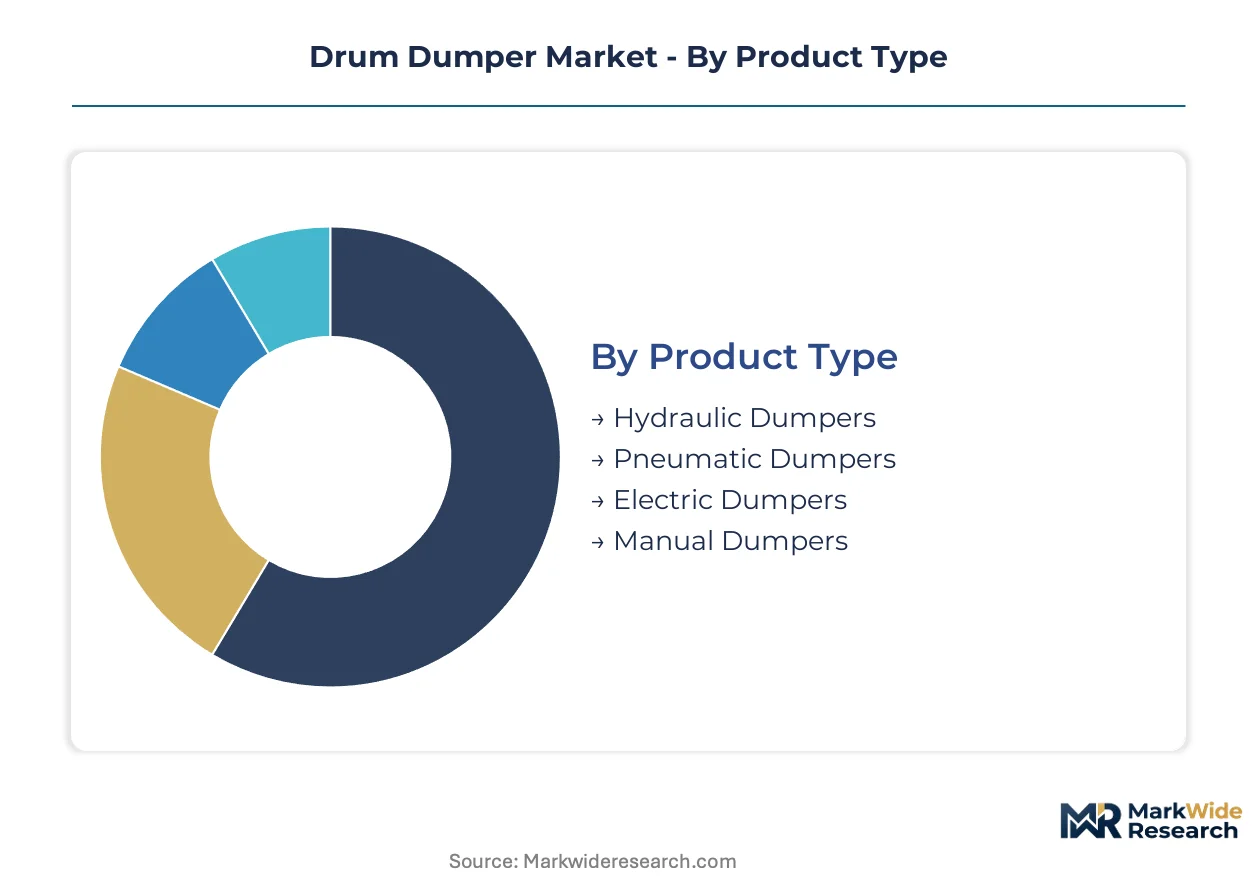
Drum dumper procurement decisions cluster around force delivery mechanisms, regulatory compliance requirements, and throughput specifications. Each segmentation dimension carries distinct substitution pressures that reshape vendor positioning and buyer evaluation criteria across industrial verticals.
Product Type:
Pneumatic dumpers face the most acute substitution threat as electric drive systems capture food and pharmaceutical installations seeking oil-free operation.
- Hydraulic Dumpers:These systems deploy precision-engineered cylinders delivering high-force output for dense ceramic slurries and metal powders. Chemical processing plants in Germany and the United States specify hydraulic configurations for heavy-load applications where force reliability outweighs maintenance overhead. OSHA machine guarding mandates and EU Machinery Directive safety interlock requirements compress replacement cycles for legacy units lacking certified guarding systems.
- Electric Dumpers:Brushless DC drive configurations eliminate hydraulic fluid contamination risk in sterile production environments. Pharmaceutical manufacturers in Switzerland and the Netherlands are adopting these systems for cleanroom-adjacent material transfer, prioritizing reduced maintenance intervals and simplified disposal compliance over upfront capital expenditure.
- Pneumatic Dumpers:Compressed air actuation suits light-density powders and granules in mid-scale bakery operations.
- Manual Dumpers:Hand-cranked mechanical systems serve small-batch specialty chemical producers with intermittent handling needs.
Hydraulic dumpers anchor the volume base while electric dumpers gain share at the steepest rate.
End User:
Margin concentration varies sharply across end-use verticals, with sterile production protocols commanding premium pricing over standard industrial configurations.
- Chemical Industries:Hazardous material handling drives demand for sealed dumper configurations with vapor recovery integration. Agrochemical formulators in Brazil must comply with ANVISA environmental containment rules, forcing capital expenditure on specialized equipment. Dense slurry applications exclude pneumatic alternatives, cementing hydraulic system dominance.
- Pharmaceutical Companies:FDA 21 CFR Part 110 compliance and subsequent food safety modernization rules mandate stainless steel contact surfaces and sanitary welds. Sterile API production investment in India, following CDSCO regulatory harmonization with ICH standards, expands demand for hygienic material handling infrastructure with clean-in-place design protocols.
- Food Processing:High-volume bakery and dairy operations require FDA-compliant stainless steel construction.
- Manufacturing Facilities:General industrial applications span automotive coatings to electronics assembly with varied specification intensity.
Chemical industries generate the largest equipment volume while pharmaceutical companies expand most quickly.
Capacity:
Procurement accessibility and throughput requirements create distinct tier boundaries that separate project-driven custom engineering from catalog-standard configurations.
- Medium Capacity:These units balance purchase accessibility with sufficient throughput for mid-scale pharmaceutical and specialty chemical operations. German and Swiss processors favor this tier for its alignment with campaign-based production schedules and seasonal demand fluctuation. Equipment-as-a-service contracting concentrates visibly at this capacity level among North American contract manufacturing organizations.
- Industrial Capacity:Massive throughput specifications serve continuous-process chemical plants with dedicated material handling infrastructure. Large-scale fertilizer production in the United States and petrochemical complexes in the Netherlands deploy these systems for uninterrupted bulk transfer operations where downtime carries substantial cost penalties.
- Small Capacity:Bench-scale and pilot plant operations utilize compact units for R&D and quality control sampling.
- Large Capacity:Heavy-industry applications bridge medium and industrial tiers for regional chemical processors.
Medium capacity units concentrate margin pools while industrial capacity systems anchor the highest absolute revenue per installation.
Installation:
Capital constraint severity and production layout flexibility determine whether buyers commit to permanent infrastructure or retain operational mobility.
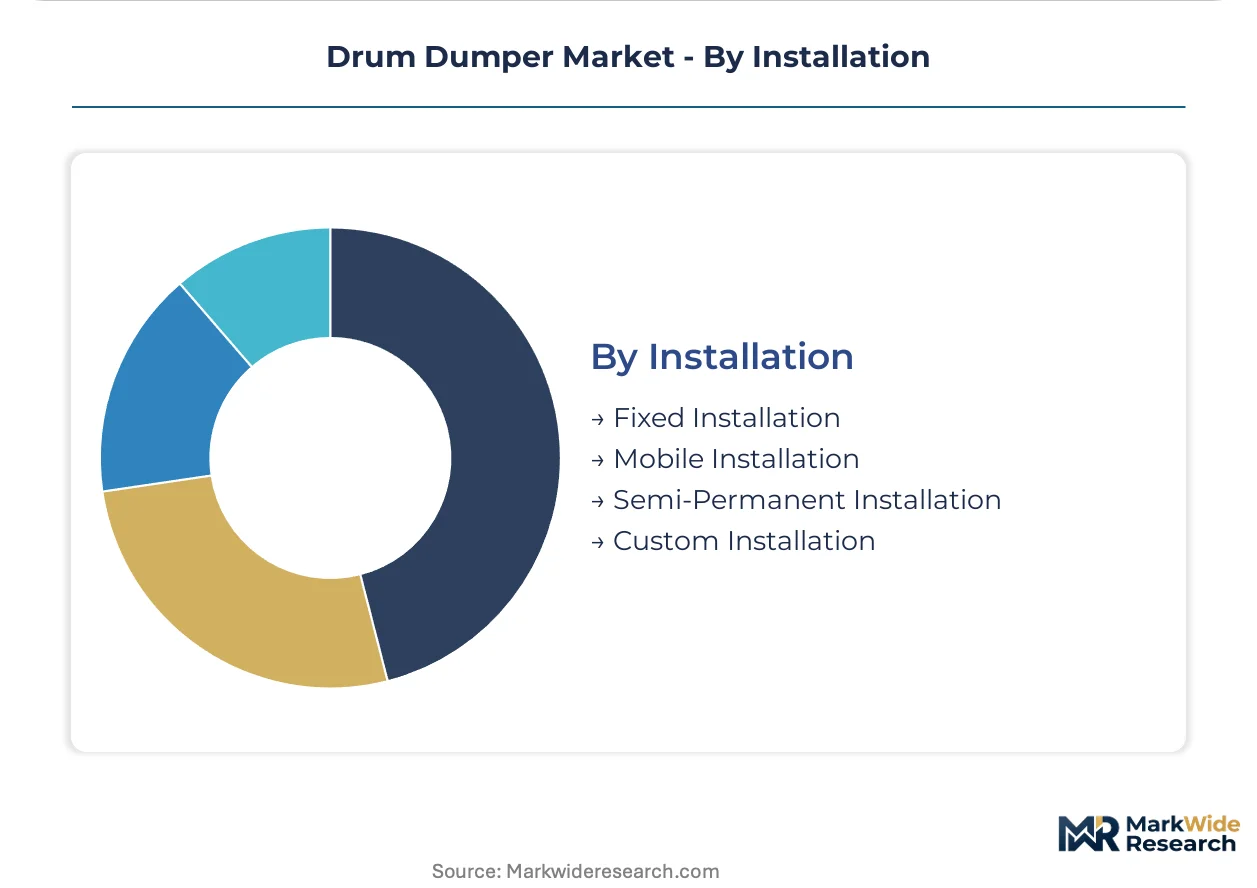
- Fixed Installation:Permanent mounting on production floors suits high-volume continuous operations with stable material flow patterns. Chemical processing plants in North America expanding automated material handling fleets to meet stricter OSHA mandates favor this configuration for its integration with centralized SCADA architectures and predictive maintenance sensor networks.
- Mobile Installation:Castor-mounted or forklift-compatible systems enable rapid redeployment across production lines. Seasonal campaign manufacturers in pharmaceutical toll operations leverage mobility to accommodate fluctuating production schedules without dedicated equipment per process stage.
- Semi-Permanent Installation:Bolt-down bases with detachable power connections balance stability and relocation flexibility.
- Custom Installation:Engineered-to-order configurations address unique facility constraints and specialized material characteristics.
Fixed installation dominates capital-intensive chemical processing while mobile installations climb fastest among contract manufacturing organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators command pricing premiums for CE-certified hydraulic systems while Chinese assemblers compete on stainless steel unit cost. This asymmetry shapes procurement patterns across industrial verticals and capacity tiers.
United States
OSHA ergonomic mandates and machine guarding standards compress replacement cycles for legacy drum handling equipment in chemical processing corridors along the Gulf Coast. FDA 21 CFR Part 110 compliance requirements drive stainless steel dumper procurement for pharmaceutical operations clustered around Boston and Research Triangle Park.
Germany
REACH workplace safety directives eliminate manual drum handling in chemical manufacturing, creating immediate demand for interlocked hydraulic systems. The EU Machinery Directive governs safety interlocks for equipment deployed across the Ruhr industrial basin and Bavarian pharmaceutical clusters near Munich.
China
Domestic pharmaceutical manufacturing expansion under the 14th Five-Year Plan drives hygienic material handling infrastructure investment. GB standards and NMPA regulations shape equipment specifications for sterile API production facilities concentrated in the Yangtze River Delta around Shanghai.
India
CDSCO regulatory harmonization with ICH standards attracts sterile API production investment requiring hygienic drum handling systems. Pharmaceutical manufacturing corridors in Maharashtra and Gujarat deploy stainless steel dumpers with clean-in-place design protocols for export-oriented production.
Brazil
ANVISA environmental containment rules for pesticide manufacturing create demand for sealed dumper configurations with vapor recovery integration. Agrochemical formulation plants in São Paulo state upgrade material handling fleets to comply with stricter workplace exposure limits.
Drum Dumper Market Vendor Landscape
Concentration sits with domestic fabricators leveraging regional manufacturing footprints to control distribution costs across standard-capacity lines. The vendor base organizes across three strategic archetypes: North American volume producers serving mid-cap chemical processors, European precision specialists targeting pharmaceutical sterile production protocols, and Asian scale assemblers competing on stainless steel construction cost. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into integrated bulk material handling systems.
Among North American fabricators, Vestil Manufacturing Corp. and National Bulk Equipment, Inc. occupy positions within the standard-capacity tier serving chemical and food processing verticals. Flexicon Corporation represents the custom-engineering archetype with pneumatic and hydraulic configurations for specialized process circuits. These three entities exemplify competitive positioning strategies visible across the broader vendor landscape.
| Leading Market Players |
|---|
| Vestil Manufacturing Corp. |
| National Bulk Equipment, Inc. |
| Beacon Industries |
| Liftomatic Material Handling, Inc. |
| METO Systems |
| Valley Craft Industries, Inc. |
| Flexicon Corporation |
| Wuxi Tongyang Machinery Technology Co., Ltd. |
| Morse Manufacturing Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Brushless DC electric drive systems displacing hydraulic power units in food and pharmaceutical installations simultaneously relocate component sourcing from German and Japanese precision cylinder suppliers toward East Asian motor and controller manufacturers, compressing the customization-premium spread while fragmenting supplier geography across tiered certification requirements.
Pricing Analysis
The customization-premium spread spans roughly three-to-one between configured-to-order hydraulic systems for dense ceramic slurry handling and catalog-standard pneumatic units for light-density powders. Project-based pricing dominates for chemical industry deployments requiring vapor recovery integration and ANVISA-compliant sealed configurations, while equipment-as-a-service contracting spreads among North American contract manufacturers facing capital constraint. Price differentiation hinges on FDA 21 CFR Part 110 certification tier and stainless steel grade specification, with pharmaceutical buyers showing lowest sensitivity and mid-scale bakery operators most responsive to unit cost. Cost compression in standard-capacity tiers intensifies as Chinese fabricators compete on stainless steel construction cost.
Supply Chain Analysis
Inventory cycles for precision hydraulic cylinders and certified safety interlocks extend lead times for North American assemblers dependent on German and Japanese component suppliers. Manufacturing concentration sits in China for stainless steel fabrication, Germany for CE-certified hydraulic systems, and the United States for OSHA-compliant standard-capacity lines. Raw material dependencies center on cold-rolled stainless steel, precision-engineered hydraulic valves, and brushless DC motor assemblies. Single-source vulnerability concentrates in specialized cylinder sourcing from German suppliers. Distribution runs through regional distributor partnerships for standard lines and direct specification sales for custom-engineered configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drum dumper adoption sits in early-cycle expansion as automated material handling mandates from OSHA and the EU Machinery Directive compress replacement cycles for legacy equipment, opening penetration headroom across mid-scale chemical processors previously reliant on manual handling.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance sensors and compliance update subscriptions into service contracts, countering equipment-as-a-service entrants. Deepen backward integration into stainless steel fabrication to offset cold-rolled input cost volatility and defend margin position against Chinese cost competitors. Prioritize CE marking and FDA validation documentation capabilities to compress order-to-delivery cycles where certification timelines strain working capital.
For New Entrants and Emerging Players: Anchor in mobile installation configurations for seasonal campaign manufacturers in pharmaceutical toll operations, where fluctuating production schedules resist dedicated fixed infrastructure. Target Brazil agrochemical formulation plants facing ANVISA environmental containment upgrades, and India sterile API facilities responding to CDSCO-ICH harmonization. Pursue distributor partnerships with regional material handling integrators rather than direct specification sales to bypass incumbent channel control.
For Investors and Strategic Acquirers: Capital is best deployed toward custom-engineering specialists with pneumatic and hydraulic configuration capabilities for specialized process circuits, where technical differentiation supports durable pricing power. Long-term viability favors vendors with verified ISO 14040-compliant environmental product declarations ahead of EU CSRD Scope 3 disclosure mandates extending to capital equipment procurement. Watch for inflection in equipment-as-a-service contract penetration among North American contract manufacturing organizations as signal of capital constraint severity and recurring revenue model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive supply of FDA-compliant contact surfaces insulates margin from cold-rolled steel price volatility. |
| Equipment-as-a-Service Contracting | Utilization-based payment structures capture capital-constrained pharmaceutical toll manufacturers in North America. |
| ISO 14040 Environmental Product Declaration | Verified lifecycle assessments secure procurement preference under EU CSRD carbon disclosure requirements. |
| Predictive Maintenance Sensor Integration | Sensor-enabled diagnostics compress aftermarket service intervals and lock in recurring revenue streams. |
| Geographic Distributor Partnership Expansion | Regional channel control defends standard-capacity tier share against Chinese cost competitors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from material handling equipment vendors, OSHA and FDA regulatory documentation, and industry association reports from chemical and pharmaceutical manufacturing bodies. Primary interviews engaged plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across chemical processing, pharmaceutical manufacturing, and food processing verticals. Secondary validation drew from EU Machinery Directive implementation guidance, REACH compliance databases, and CDSCO regulatory harmonization circulars. Bottom-up unit economics triangulate against top-down industry spend estimates to anchor volume and value outputs.
Segmentation dimensions modeled include force delivery mechanism, end-use vertical, capacity tier, installation type, and regional regulatory cluster across the projection horizon. Analytical framework applies growth rate derivation from replacement cycle compression, automation mandate penetration curves, and capital expenditure elasticity by buyer size. Industry-specific forecast inputs incorporate stainless steel price trajectory assumptions and certification timeline documentation requirements. CAGRs reflect segment-level growth differentials rather than uniform market expansion.
Material uncertainties — steel price volatility, regulatory timeline delays, and equipment-as-a-service adoption velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions about OSHA enforcement intensity and EU CSRD procurement criteria evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
Steel Coil Handling Equipment Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Shiplifts & Transfer Systems Market