
 Fork Lift Attachments Market | 2026-2036
Fork Lift Attachments Market Size, Share, and Industry Trends Forecast 2026-2036
Fork Lift Attachments Market Foresight
Electro-mechanical actuation is rewriting attachment control architectures, replacing legacy hydraulic circuits with precision servo systems that cut energy draw and maintenance intervals. Cascade Corporation leverages its North American manufacturing footprint to anchor regional spare parts availability. KAUP GmbH sustains engineering intensity across its German production base, specializing in custom load-handling solutions for narrow-aisle configurations. Bolzoni Group competes through integrated attachment-mast systems that extend its reach into OEM supply chains.
Fork lift attachments are load-handling devices mounted to industrial truck carriages, typically rated by capacity class and fork spread dimension, designed to transport unit loads without pallet infrastructure. Carton clamps and push pull units serve slip-sheet operations in consumer goods distribution, while rotators handle bulk material inverting across food processing and recycling streams. Drum handlers and bale clamps occupy mature demand pools with slower replacement cycles, whereas electro-mechanical fork positioners capture expanding margin pools as warehouses automate pallet dimension variability. Cold storage applications drive corrosion-resistant specification upgrades across stainless-steel attachment variants.
OSHA standards govern operator visibility and load stability testing in the United States, while CE marking and the EU Machinery Directive enforce conformity assessment across European distribution. ISO 5057 establishes fork arm dimensional interchangeability, reducing supplier lock-in for fleet operators. Stakeholders must weigh hydraulic versus electro-mechanical technology bets against total cost-of-ownership curves and regional energy price trajectories.
Market Dynamics
Electro-mechanical actuation is compressing total cost-of-ownership curves for attachment fleets by eliminating hydraulic fluid maintenance and cutting energy draw by 30-40% in high-cycle operations. This technology shift is redrawing competitive positioning between established hydraulic specialists and servo-system entrants.
Growth Catalysts
- E-commerce fulfillment density:Automated storage and retrieval systems in consumer goods distribution require fork positioners and carton clamps rated for 24/7 operation cycles.
- OSHA visibility mandates:Operator sightline requirements in the United States are accelerating replacement of legacy carriage designs with transparent or camera-integrated attachment architectures.
- Cold storage corrosion specifications:Stainless-steel attachment variants meeting EU Machinery Directive hygiene standards are capturing specification share in pharmaceutical and food processing verticals.
Market Restraints
- Hydraulic component supply concentration:Precision valve and seal manufacturing clusters in Germany and Japan create lead-time vulnerability for non-integrated attachment producers.
- Steel price volatility:Fork arm and carriage fabrication depends on hot-rolled coil pricing that has swung 40% across recent commodity cycles, compressing margin predictability.
- CE marking conformity costs:EU Machinery Directive third-party assessment fees and technical documentation burdens disproportionately burden low-volume custom attachment builders.
Strategic Opportunities
- India warehouse automation:PLI scheme incentives for logistics infrastructure and the absence of entrenched attachment incumbents create first-mover positioning for electro-mechanical product lines.
- Attachment-as-a-service models:Fleet operators in Germany's industrial logistics corridor are piloting usage-based contracts that unbundle capital expenditure from maintenance and upgrade cycles.
- Battery-electric truck convergence:Integration of regenerative braking-compatible attachments with lithium-ion forklift platforms opens specification windows for energy-harvesting load-handling designs.
Industry Challenges
- Servo technician scarcity:Electro-mechanical attachment deployment requires field service capabilities in programmable logic controller diagnostics and precision encoder calibration that legacy hydraulic repair networks lack.
- ISO 5057 interoperability testing:Fork arm dimensional certification delays for new carriage interfaces extend product launch timelines by 4-6 months for attachment developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fork Lift Attachments Market |
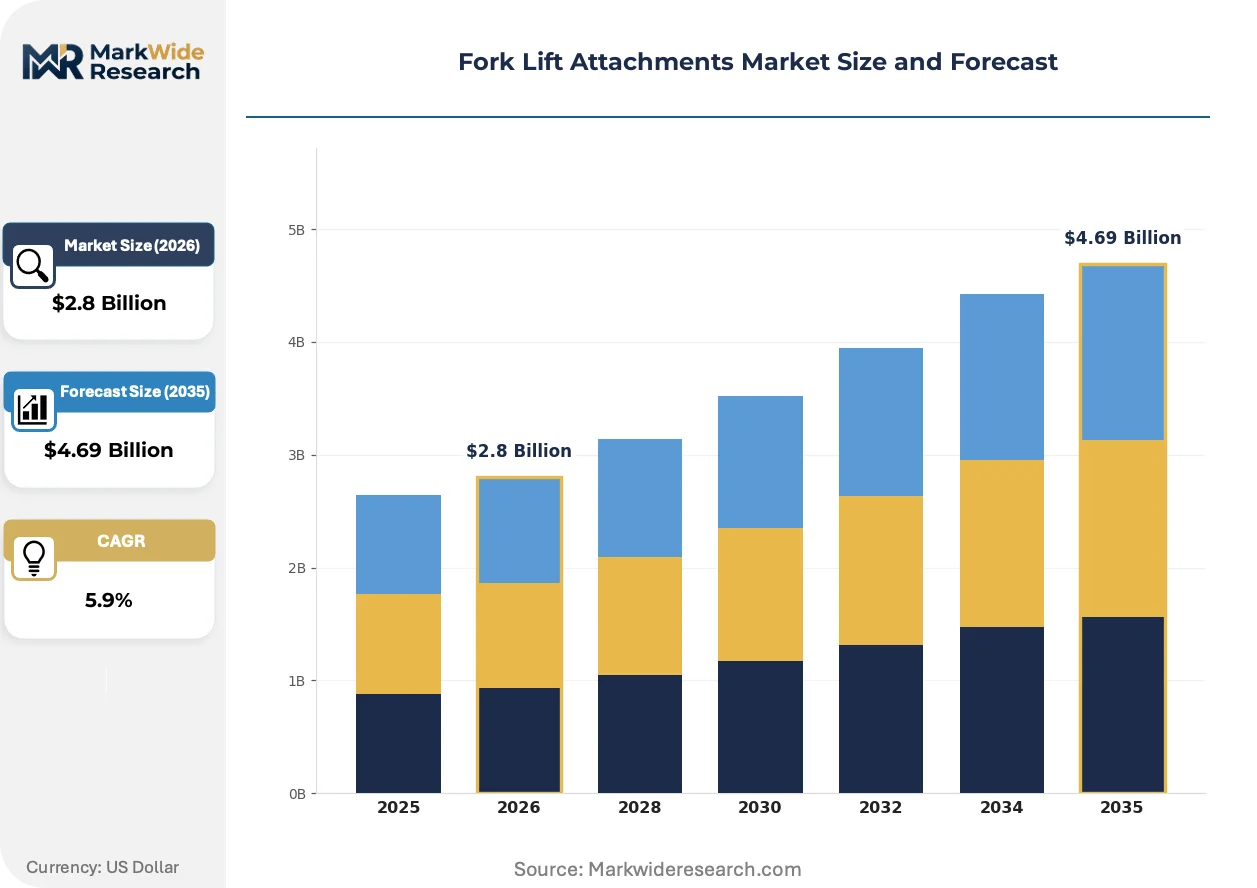
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.69 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fork Positioners, Carton Clamps, Drum Handlers, Bale Clamps, Rotators, Push Pull Units Technology: Hydraulic, Mechanical, Electro-Mechanical, Pneumatic, Manual Application: Warehouse Operations, Port Handling, Manufacturing Plants, Construction Sites, Cold Storage End User Industry: Logistics Providers, OEMs, Aftermarket Suppliers, Fleet Operators, Distribution Centers |
| Companies Covered | Bolzoni Group, Cascade Corporation, KAUP GmbH, TVH Group, Toyota Industries Corporation, Jungheinrich AG, KION Group AG, Palfinger, Attachments International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fork Lift Attachments Market Shifts & Advancements
Attachment control architectures are bifurcating between legacy hydraulic circuits and precision servo systems, with hybrid configurations emerging as a transitional pathway for mid-cycle fleet upgrades. This technological divergence is compressing replacement decision timelines and fragmenting supplier consolidation strategies.
Electro-mechanical fork positioners is hybridizing warehouse automation by enabling real-time pallet dimension sensing and automatic spread adjustment without hydraulic lag. Third-party logistics operators in Germany and the Netherlands are specifying these systems for mixed-SKU fulfillment lines where pallet variability exceeds 200mm in width. The technology is compressing attachment fleet standardization by allowing single-unit deployment across previously segregated product categories.
CE marking enforcement under the EU Machinery Directive is tightening conformity assessment for attachment visibility systems and load stability interlocks. Notified bodies in Germany and Italy are rejecting legacy test protocols that lack documented operator field-of-view measurement. Cold storage attachment suppliers are responding by integrating camera-based rear-view systems as standard rather than optional configuration.
Buyer procurement is consolidating attachment specification authority from regional fleet managers to centralized engineering functions at third-party logistics headquarters. This shift is displacing distributor-led configuration advice with direct OEM engagement and long-term total cost-of-ownership modeling. The pattern is most visible in the United States, where national warehouse operators are standardizing on single attachment platforms across 50+ facility networks.
Fork Lift Attachments Market Segmentation
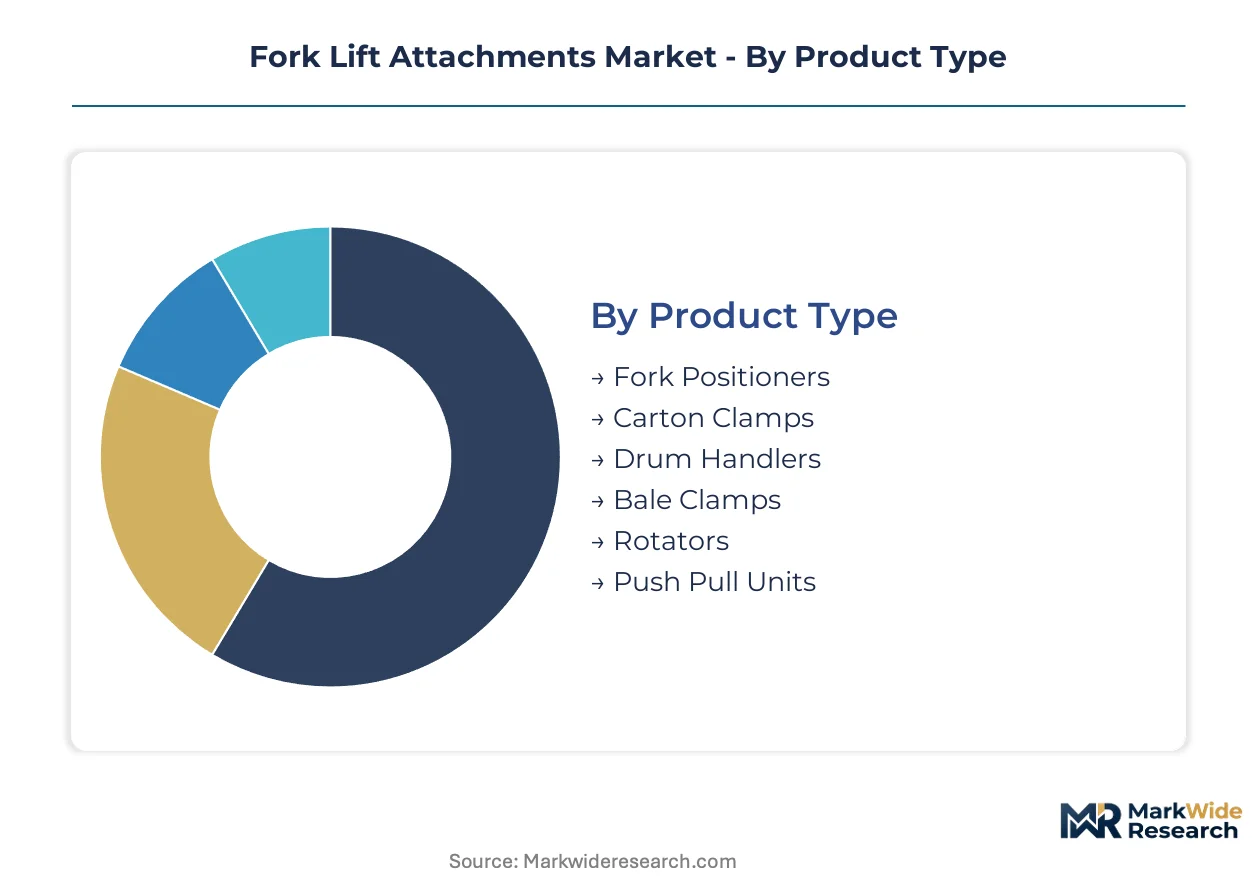
Fork lift attachments fragment across operational intensity, actuation method, and facility type. Buyers configure fleets around pallet infrastructure, load variability, and duty cycle demands rather than universal specifications.
Product Type:
Use-case spectrum spans palletized unit loads to bulk material handling without pallet infrastructure.
- Fork Positioners:Electro-mechanical variants enable real-time spread adjustment for mixed-SKU lines. Demand concentrates in Germany's third-party logistics corridor where pallet dimension variability exceeds 200mm.
- Carton Clamps:Slip-sheet handling for consumer goods distribution. E-commerce fulfillment density in the Netherlands drives 24/7 rated specification upgrades.
- Drum Handlers:Mature replacement cycles in chemical processing.
- Bale Clamps:Recycling and agricultural bulk streams.
- Rotators:Food processing and waste inverting operations.
- Push Pull Units:Slip-sheet operations competing with carton clamps in beverage distribution.
The dominant share belongs to fork positioners, while carton clamps are closing the gap fastest.
Technology:
Cost tier separation runs from capital-intensive servo systems to maintenance-heavy legacy circuits.
- Electro-Mechanical:Precision servo actuation eliminates hydraulic fluid maintenance and cuts energy draw. Cold storage operators in the United States specify these for corrosion-resistant performance.
- Hydraulic:Legacy valve and seal architectures dominate installed base. Supply concentration in German and Japanese precision component clusters creates lead-time vulnerability.
- Mechanical:Fixed-position solutions for standardized load profiles.
- Pneumatic:Explosion-proof applications in chemical handling.
- Manual:Low-cycle operations in construction and maintenance fleets.
Electro-mechanical systems command the premium tier, with hydraulic retaining volume leadership.
Application:
Volume concentrates in high-cycle indoor environments versus intermittent outdoor deployment.
- Warehouse Operations:Automated storage and retrieval integration demands positioners and clamps rated for continuous cycling. India's PLI-backed logistics infrastructure expansion opens specification windows.
- Cold Storage:Stainless-steel variants meet EU Machinery Directive hygiene standards. Pharmaceutical and food processing verticals drive corrosion-resistant upgrades.
- Port Handling:Heavy-duty rotators and bale clamps for containerized bulk.
- Manufacturing Plants:Just-in-time feed lines with mixed attachment fleets.
- Construction Sites:Manual and mechanical solutions for intermittent duty.
Warehouse operations anchor procurement volume, with cold storage delivering the steepest expansion trajectory.
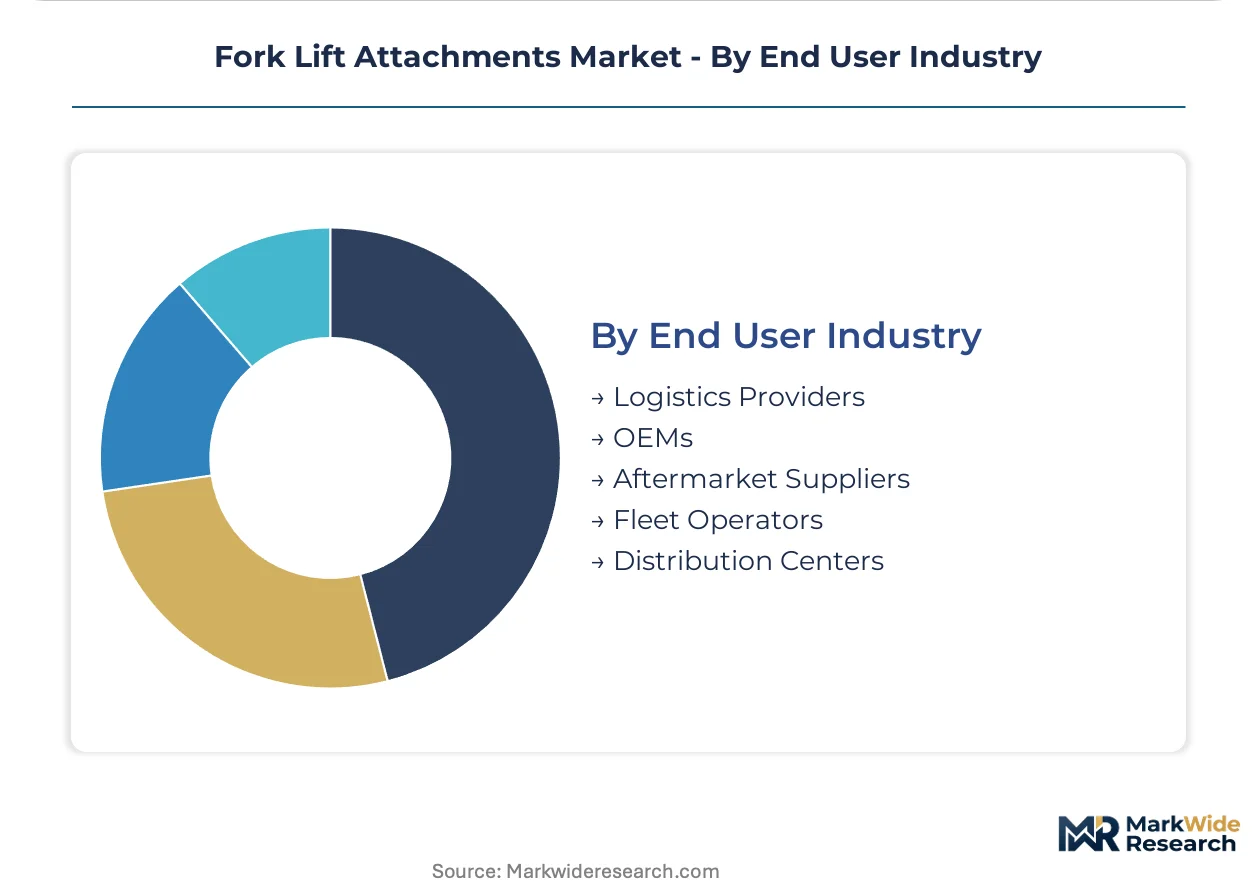
End User Industry:
Customer type determines specification authority and contract structure.
- Logistics Providers:Centralized engineering functions at third-party logistics headquarters now control attachment specification. United States national operators standardize single platforms across 50-plus facility networks.
- Fleet Operators:Usage-based service contracts pilot in Germany's industrial logistics corridor, unbundling capital expenditure from maintenance cycles.
- Distribution Centers:E-commerce fulfillment density drives attachment-as-a-service adoption.
- OEMs:Integrated attachment-mast system partnerships.
- Aftermarket Suppliers:Spare parts availability anchored by regional manufacturing footprints.
Logistics providers hold specification dominance, while fleet operators are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for precision hydraulic components tilts trade balances toward Germany and Japan, while electro-mechanical attachment exports from North American and European bases reshape regional supply positions.
United States
OSHA visibility mandates accelerate carriage redesign cycles across e-commerce fulfillment networks. Third-party logistics operators in the Midwest and Southeast are standardizing attachment platforms across multi-facility deployments. Cold storage operators in California and Texas specify corrosion-resistant variants for pharmaceutical distribution.
Germany
The EU Machinery Directive enforces conformity assessment for load stability interlocks and operator field-of-view systems. CE marking costs burden low-volume custom builders disproportionately. The industrial logistics corridor spanning North Rhine-Westphalia and Bavaria pilots attachment-as-a-service contracts that unbundle capital expenditure from maintenance cycles.
China
Domestic warehouse automation drives specification demand for electro-mechanical positioners in Yangtze River Delta distribution hubs. GB standards govern fork arm interchangeability testing protocols. Local fabricators in Jiangsu and Zhejiang provinces compete on cost for standardized mechanical attachments.
India
PLI scheme incentives for logistics infrastructure open specification windows for electro-mechanical product lines absent entrenched incumbents. BIS certification requirements create entry barriers for imported hydraulic systems. Maharashtra and Karnataka warehouse clusters drive initial adoption of automated storage and retrieval-compatible attachments.
Japan
JIS standards maintain dimensional precision requirements that sustain premium positioning for domestic attachment producers. METI industrial efficiency programs promote energy-saving electro-mechanical retrofits in aging logistics facilities. Osaka-based component suppliers concentrate precision valve and seal manufacturing for regional hydraulic attachment producers.
Fork Lift Attachments Market Competitive Landscape
On the supply side, the industry is consolidating around integrated attachment-mast system partnerships and regional spare parts availability networks. Tiered competitive positioning separates hydraulic specialists with legacy installed bases from servo-system entrants capturing high-cycle warehouse specifications. Strategic archetypes include integrated OEM suppliers, independent attachment specialists, and diversified industrial conglomerates. Dominant competitive moves span backward integration into precision component manufacturing and geographic expansion through distributor network acquisition.
Among Germany-based engineering specialists, KAUP GmbH and Jungheinrich AG exemplify the premium-tier archetype anchored in custom load-handling solutions. Cascade Corporation represents North American manufacturing footprint strategies that anchor regional spare parts availability. Bolzoni Group occupies a position within integrated attachment-mast system supply chains that extend into OEM partnerships. These three named entities illustrate divergent geographic and structural positioning without exhausting the competitive field.
| Leading Market Players |
|---|
| Bolzoni Group |
| Cascade Corporation |
| KAUP GmbH |
| TVH Group |
| Toyota Industries Corporation |
| Jungheinrich AG |
| KION Group AG |
| Palfinger |
| Attachments International |
| Others |
Supply & Pricing Matrix
Osaka's precision valve and seal manufacturing clusters anchor hydraulic component supply for regional attachment producers, translating upstream capacity discipline into pricing leverage for integrated OEM suppliers over independent fabricators. Hot-rolled coil volatility and electro-mechanical servo adoption are compressing margin predictability across tiered product positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with electro-mechanical fork positioners commanding premium positioning against legacy hydraulic alternatives. Price differentiation separates CE-marked visibility-integrated systems from uncertified mechanical variants, while volume scale drives contract-based long-term offtake for national logistics operators. Pricing pressure stems from steel input volatility and servo technician scarcity forcing service bundling. Fleet operators exhibit highest price sensitivity on capital expenditure, whereas cold storage pharmaceutical distributors prioritize corrosion-resistant specifications over unit cost.
Supply Chain Analysis
Hot-rolled coil feedstock draws from integrated steel mills in China, Japan, and South Korea, with precision valve components resting on German and Japanese manufacturing concentration. Raw material dependencies span high-grade structural steel, corrosion-resistant stainless alloys, and rare-earth servo motor elements. Single-source vulnerability concentrates in precision seal manufacturing clusters. Distribution runs through OEM-integrated attachment-mast partnerships and regional aftermarket service networks anchored by North American and European manufacturing footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro-mechanical attachment adoption sits in early-cycle expansion, with warehouse automation tailwinds in India and Germany opening specification windows before incumbent lock-in solidifies.
For Market Incumbents: Harden backward integration into precision servo component manufacturing to offset supply concentration risk in Osaka and Stuttgart valve clusters. Capture certification investment in OSHA visibility-compliant architectures before 2025 mandate deadlines displace legacy carriage designs. Defensive consolidation around regional spare parts availability networks protects against emerging Chinese electro-mechanical entrants. For New Entrants and Emerging Players: Establish a beachhead in India's Maharashtra warehouse automation corridor, where PLI scheme infrastructure incentives and absent hydraulic incumbents create first-mover positioning for servo-system product lines. Penetrate the cold storage pharmaceutical vertical through stainless-steel corrosion-resistant specifications that bypass commodity pricing pressure. Go-to-market through direct OEM attachment-mast integration partnerships rather than distributor-led configuration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized attachment divisions lacking electro-mechanical R&D intensity. Long-term viability frames around 5-10 year warehouse automation penetration curves rather than replacement cycle timing. Signal to watch: attachment-as-a-service contract velocity in Germany's industrial logistics corridor as indicator of procurement model inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Servo Components | Captive supply of encoder and actuator elements insulates margin from Osaka valve cluster lead-time volatility. |
| CE Marking Investment for Visibility Systems | Pre-emptive conformity assessment with EU Machinery Directive field-of-view protocols secures specification share in Netherlands distribution. |
| Attachment-as-a-Service Platform Launch | Usage-based contracts in North Rhine-Westphalia unbundle capital expenditure from maintenance cycles for fleet operators. |
| India Manufacturing Footprint Establishment | Maharashtra production base exploits PLI logistics infrastructure incentives before BIS certification barriers harden. |
| OEM Attachment-Mast System Partnership | Integrated supply chain positioning with KION or Jungheinrich platforms displaces independent distributor channels. |
Research Methodology
A spread of perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors converged on the working assumptions underlying segment sizing. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, customs and trade data, OSHA regulatory dockets, and EU Machinery Directive conformity assessment records. Bottom-up attachment unit deployment estimates triangulated against top-down logistics infrastructure investment flows across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling electro-mechanical versus hydraulic technology substitution curves, pallet dimension variability coefficients, and cold storage corrosion specification penetration. Segmentation dimensions spanned actuation method, facility type, end-use industry vertical, and regional regulatory cluster. CAGRs derived from fitted adoption curves cross-checked against historical replacement cycle patterns and warehouse automation capital expenditure trajectories.
Stress conditions across steel price volatility bands, servo component supply disruption scenarios, and OSHA mandate implementation timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology substitution elasticity and regulatory enforcement intensity. Cross-checking against customs shipment data and regional logistics employment indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
Dewatering Screen Market