
 Asia-Pacific Forklift Rental Market | 2026-2036
Asia-Pacific Forklift Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Forklift Rental Market Insights
Electrification of material handling fleets is narrowing the total-cost gap between owned and rented electric forklifts across Asia-Pacific industrial corridors. Toyota Material Handling leverages its regional service density to sustain long-term rental margins in Japanese and Australian warehousing markets. Hangcha Group anchors its competitive stance through in-house lithium battery production and direct distribution across Chinese provincial hubs. Nishio Rent All competes by maintaining specialized technician networks that reduce equipment downtime for construction sector clients.
A forklift rental arrangement provides temporary or contracted access to powered industrial trucks designed to lift and transport materials over short distances, typically featuring load capacities from one to fifty tons and mast heights reaching twelve meters for container stacking operations. The primary commercial purpose centers on converting capital-intensive equipment ownership into operational expenditures while ensuring compliance with operator certification and maintenance protocols. Electric forklifts now lead product type demand as warehouse operators prioritize zero-emission indoor compliance, while short-term rentals capture the fastest growth within service types due to project-based construction cycles and e-commerce peak seasonality. Long-term rentals retain the deepest margin pools through multi-year contracts that bundle maintenance services and operator training.
China's MIIT enforces GB standards for non-road diesel emissions that restrict older forklift models from operating in designated low-emission zones, directly expanding electric rental demand in Shanghai and Shenzhen logistics corridors. Japan's METI industrial safety regulations mandate periodic operator recertification and equipment inspection, embedding compliance services into rental contract structures. India's CEA electrical safety codes for battery charging infrastructure shape how rental providers site and maintain electric fleets in NCR and Maharashtra industrial belts. Stakeholders must monitor how evolving carbon accounting rules across these jurisdictions redefine lease-versus-own calculations for fleet procurement decisions.
Market Dynamics
China's MIIT emissions standards for non-road mobile machinery are compressing diesel forklift residual values and accelerating fleet turnover decisions across coastal manufacturing corridors. This regulatory pressure is restructuring rental contract economics and reshaping lessor asset management strategies throughout the region.
Growth Catalysts
- E-commerce Peak Seasonality:Third-party logistics operators in Southeast Asia are expanding short-term rental agreements to manage warehouse throughput spikes during festival shopping periods without capital-intensive fleet ownership.
- MIIT GB Standards:China's designated low-emission zones now restrict older diesel forklift models, directly expanding electric rental demand in Shanghai and Shenzhen logistics corridors where compliance deadlines concentrate.
- Lithium Battery Cost Curves:In-house battery production by major equipment manufacturers is narrowing total-cost differentials between electric and internal combustion rental options across Chinese provincial hubs.
Market Restraints
- Charging Infrastructure Capex:Battery electric fleet deployment requires substantial depot electrical upgrades, with India's CEA electrical safety codes imposing additional siting and maintenance compliance burdens on rental providers.
- Technician Network Concentration:Specialized maintenance capabilities for advanced electric drivetrains remain concentrated in tier-one Chinese and Japanese metropolitan markets, limiting rural and secondary city service coverage.
- Residual Value Uncertainty:Rapid technology transitions in battery chemistry and fleet telematics are compressing secondary market pricing visibility for mid-life electric equipment.
Strategic Opportunities
- India's NCR Fulfillment Expansion:Third-party logistics providers scaling multi-year rental contracts for new fulfillment infrastructure in Delhi's National Capital Region represent underpenetrated contract depth.
- Telematics-Enabled Outcome Pricing:Integration of IoT fleet monitoring with usage-based rental billing models allows providers to capture value from operational efficiency guarantees rather than equipment availability alone.
- ASEAN Manufacturing Relocation:Vietnam and Indonesia's industrial zone development is creating greenfield demand for rental fleet partnerships as foreign manufacturers establish regional supply chain nodes.
Industry Challenges
- Operator Certification Velocity:Japan's METI-mandated periodic recertification requirements create administrative bottlenecks for rental providers scaling multi-site deployments across compressed project timelines.
- Multi-Brand Fleet Integration:Warehouse operators mixing rental equipment from competing OEMs face proprietary telematics platform fragmentation that complicates unified fleet management and downtime tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Forklift Rental Market |
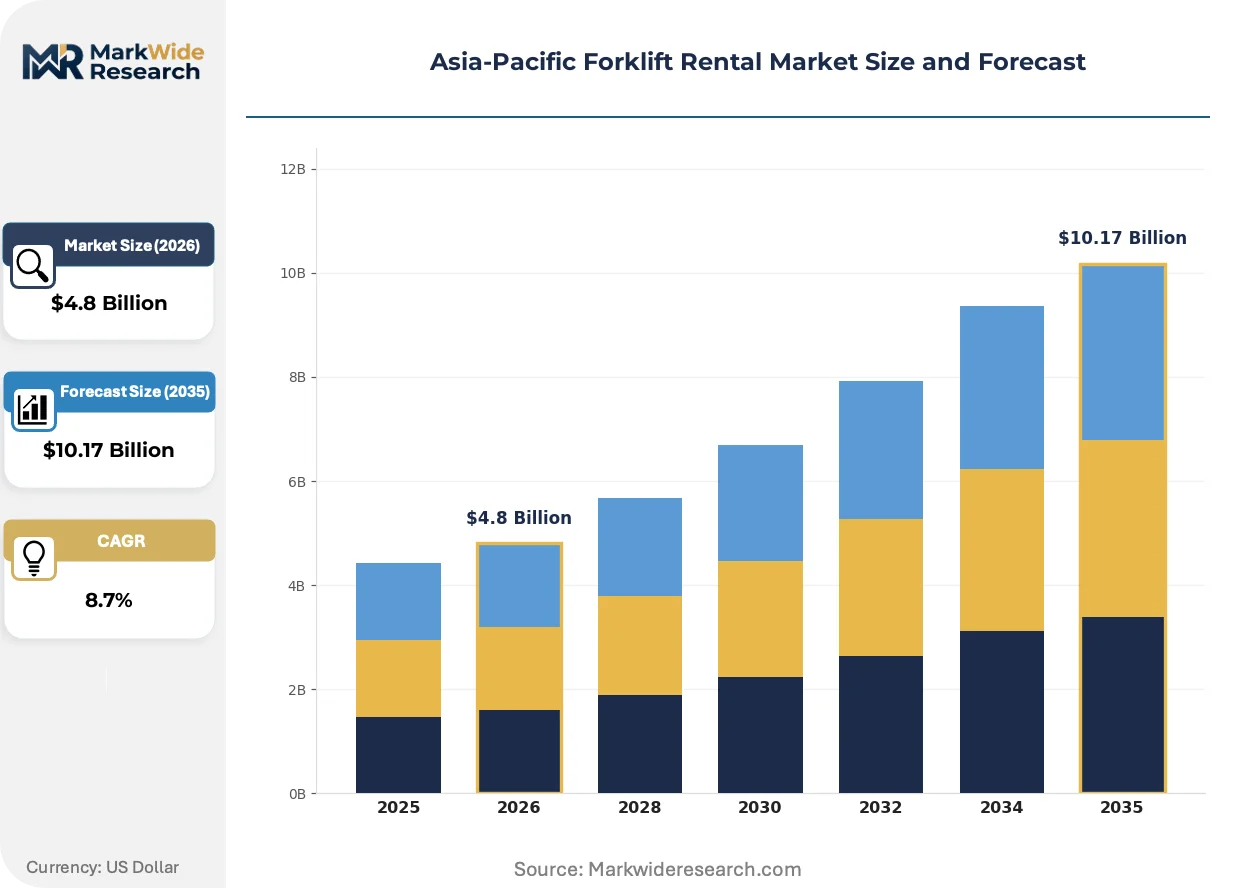
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, Diesel Forklifts, Gas Forklifts, Industrial Reach Trucks End User: Construction, Warehousing, Manufacturing, Logistics Service Type: Short-term Rentals, Long-term Rentals, Maintenance Services, Operator Services Deployment: On-site Deployments, Remote Deployments, Urban Deployments, Rural Deployments |
| Companies Covered | XCMG Group, ZPMC, Hyundai Construction Equipment, Doosan Bobcat, Nishio Rent All, Toyota Material Handling, KION Group, Jungheinrich AG, Hangcha Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Forklift Rental Market Trends and Innovations
Fleet telematics and predictive maintenance systems are digitizing asset utilization patterns and compressing service response intervals across Asia-Pacific warehousing operations. These capabilities are redefining competitive differentiation beyond equipment availability toward guaranteed uptime performance.
Telematics-integrated rental management platforms are digitizing real-time battery state-of-health monitoring and automated maintenance scheduling for electric forklift fleets. Large e-commerce fulfillment operators in China's Yangtze River Delta are mandating these capabilities in multi-year tender specifications. The technology is digitizing lessor balance sheet risk by enabling predictive asset replacement and residual value optimization.
Japan's METI industrial safety regulations now embed mandatory periodic operator recertification and equipment inspection protocols into commercial rental contract structures. Compliance service bundling has become standard in Japanese and Australian warehousing markets where liability exposure concentrates. Construction sector clients in Australia's mining corridors are responding by demanding technician-attached rental packages that transfer certification liability to lessors.
Usage-based procurement models are displacing fixed-term rental agreements among high-variability warehouse operators in Southeast Asia. Peak-season e-commerce logistics providers in Indonesia and Thailand now favor hourly or pallet-movement-based billing over monthly minimum commitments. This shift is most visible in third-party logistics contracts where throughput volatility makes capital-intensive fleet ownership economically unfavorable.
Asia-Pacific Forklift Rental Market Segmentation
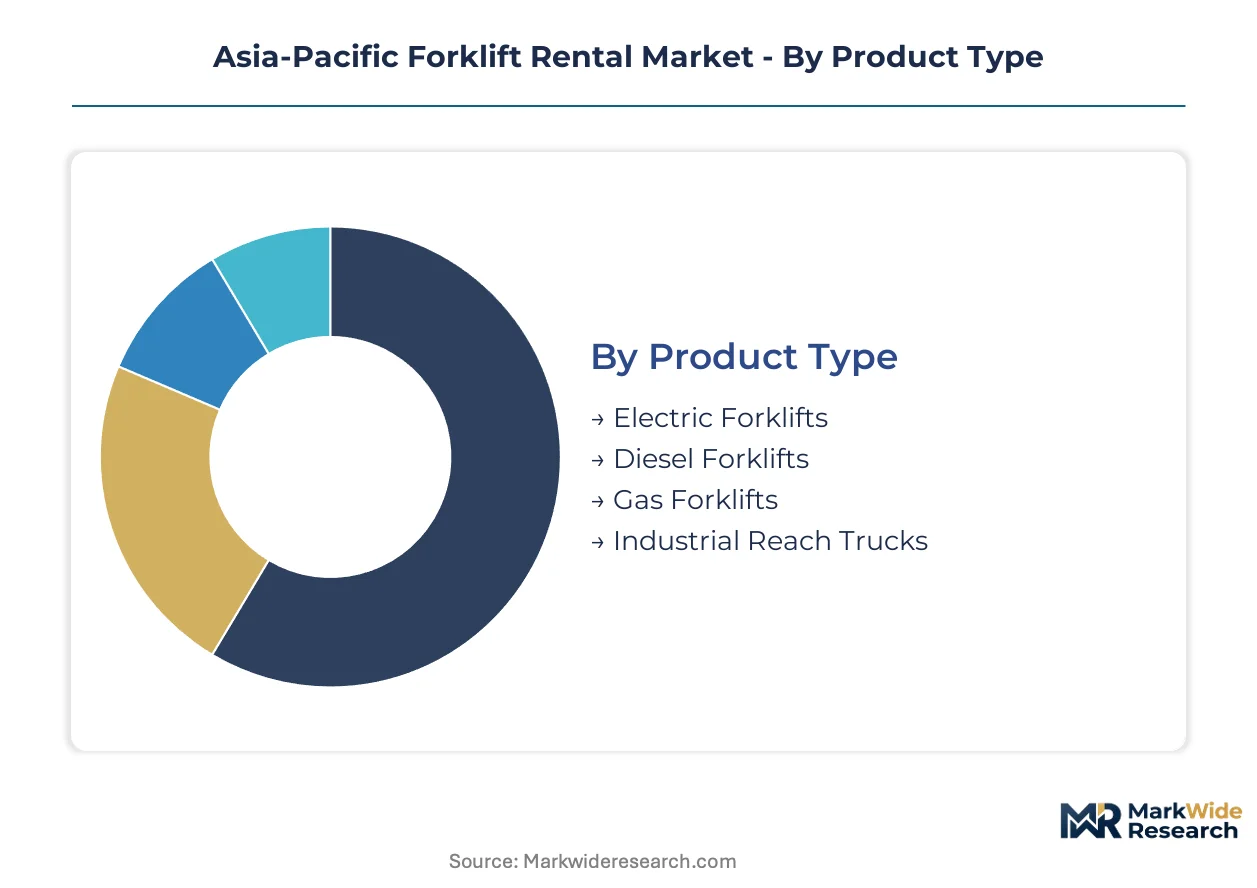
Forklift rental segmentation in Asia-Pacific reflects divergent equipment requirements across indoor warehousing and outdoor construction environments. Each category captures distinct procurement behaviors shaped by emissions compliance, project duration, and operator certification burdens.
Product Type:
Use-case spectrum spans zero-emission indoor operations to heavy-lift outdoor material handling across manufacturing and logistics corridors.
- Electric Forklifts:Battery-powered units with lithium-ion chemistry dominate indoor warehousing due to zero-emission compliance requirements. Demand concentrates in Shanghai and Shenzhen logistics corridors where China's MIIT GB standards restrict diesel equipment from low-emission zones.
- Diesel Forklifts:Internal combustion engines deliver higher torque for outdoor construction and heavy manufacturing loads. Fleet turnover accelerates across coastal Chinese manufacturing belts as residual values compress under tightening emissions enforcement.
- Gas Forklifts:LPG and CNG variants bridge indoor-outdoor flexibility for mixed-use facilities. Adoption persists in Indian National Capital Region warehousing where charging infrastructure capex delays full electrification.
- Industrial Reach Trucks:Specialized mast designs extend to twelve meters for high-density container stacking. Deployment clusters around Australian mining corridors and Japanese automotive manufacturing hubs requiring vertical storage optimization.
Established volume favors diesel equipment in legacy outdoor applications; emerging adoption favors electric forklifts in compliance-sensitive indoor corridors.
End User:
Customer-type concentration reveals how rental procurement patterns diverge between project-based construction cycles and continuous-flow logistics operations.
- Construction:Project-temporary equipment needs drive short-term rental demand with technician-attached service bundles. Australia's mining sector clients transfer certification liability to lessors through comprehensive operator packages.
- Warehousing:E-commerce fulfillment operators scale multi-year contracts for seasonal throughput spikes. India's NCR third-party logistics providers represent underpenetrated contract depth for new infrastructure buildouts.
- Manufacturing:Continuous production lines favor long-term rental structures with predictive maintenance guarantees. Japanese automotive plants embed METI-mandated inspection protocols into contract terms.
- Logistics:Multi-site fleet operators face telematics platform fragmentation when mixing OEM equipment. Southeast Asian third-party providers prioritize usage-based billing over fixed commitments.
Contract maturity favors warehousing for multi-year structures; procurement flexibility favors logistics for outcome-based pricing experiments.
Service Type:
Margin architecture separates equipment availability pricing from guaranteed uptime performance and compliance burden transfer.
- Short-term Rentals:Hourly or daily billing structures capture festival seasonality and construction project peaks. Indonesian and Thai e-commerce operators favor pallet-movement-based billing over monthly minimums.
- Long-term Rentals:Multi-year agreements bundle maintenance, parts, and operator training into predictable operational expenditures. These contracts retain the deepest margin pools across Japanese and Australian warehousing markets.
- Maintenance Services:Predictive systems using IoT battery monitoring automate scheduling and compress response intervals. Yangtze River Delta fulfillment operators mandate these capabilities in tender specifications.
- Operator Services:Certification and recertification bundling addresses Japan's METI-mandated periodic requirements. Administrative bottlenecks emerge when scaling multi-site deployments across compressed timelines.
Revenue concentration favors long-term rentals for margin stability; technology differentiation favors maintenance services for data-enabled outcome pricing.
Deployment:
Geographic deployment patterns expose infrastructure asymmetries between electrified urban logistics hubs and technician-scarce rural markets.
- On-site Deployments:Equipment stationed at single-facility operations with dedicated charging infrastructure. China's provincial manufacturing hubs anchor this model through direct OEM distribution networks.
- Remote Deployments:Distributed fleet management across multiple locations requiring centralized telematics oversight. Platform fragmentation complicates unified downtime tracking for multi-brand operators.
- Urban Deployments:Concentrated in tier-one metropolitan markets with established technician networks and electrical grid capacity. Service coverage gaps emerge in secondary Chinese and Japanese cities.
- Rural Deployments:Limited penetration due to specialized maintenance capability concentration and depot electrical upgrade requirements. India's CEA electrical safety codes impose additional siting burdens outside major industrial belts.
Service density favors urban deployments for response-time guarantees; greenfield expansion favors rural deployments for untapped contract origination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports forklift equipment to Southeast Asian logistics corridors while importing lithium battery components from South Korean suppliers, creating a triangular trade flow that shapes regional rental fleet procurement patterns.
China
Shanghai and Shenzhen logistics operators scale electric forklift rentals to comply with MIIT GB standards restricting diesel equipment from low-emission zones. The country's dual carbon goals accelerate fleet turnover decisions across coastal manufacturing belts. Yangtze River Delta fulfillment centers mandate telematics-integrated rental platforms in multi-year tender specifications.
Japan
Automotive manufacturing hubs in Nagoya and Osaka embed long-term rental structures with predictive maintenance guarantees. METI-mandated periodic operator recertification protocols compress administrative timelines for multi-site deployments. Kanto region warehousing markets sustain premium rental margins through compliance service bundling.
India
Third-party logistics providers in Delhi's National Capital Region negotiate multi-year rental contracts for new fulfillment infrastructure buildouts. CEA electrical safety codes impose additional siting burdens on battery charging infrastructure outside Maharashtra industrial belts. Gujarat and Karnataka manufacturing zones drive diesel-to-electric conversion demand among automotive component suppliers.
Australia
Mining corridor operators in Western Australia and Queensland transfer certification liability to lessors through technician-attached rental packages. Construction project cycles favor short-term billing structures with comprehensive operator services. New South Wales warehousing markets adopt usage-based procurement models for seasonal throughput variability.
Vietnam
Foreign manufacturers establishing regional supply chain nodes in Hai Phong and Bac Ninh industrial zones create greenfield demand for rental fleet partnerships. Provincial logistics operators favor electric forklifts as EU-bound export compliance requirements tighten. Ho Chi Minh City warehousing clusters expand short-term agreements to manage e-commerce festival seasonality.
Asia-Pacific Forklift Rental Market Competitive Landscape
On the supply side, the industry is tiered between integrated equipment manufacturers with captive battery production, specialized rental service providers with dense technician networks, and regional distributors leveraging direct provincial hub access. Equipment-centric archetypes compete on lithium battery cost curves and telematics platform integration. Rental service archetypes differentiate through compliance bundling and guaranteed uptime performance. The dominant competitive moves involve strategic partnerships for charging infrastructure deployment and portfolio diversification into predictive maintenance services.
Among Japanese and German industrial equipment specialists, Toyota Material Handling and Jungheinrich AG occupy positions emphasizing premium-tier service density and long-term contract structures. Chinese manufacturers exemplify scale-driven competitive positioning through in-house component production. Korean construction equipment providers sit within the diversified industrial conglomerate archetype. These named entities anchor industry-level commentary on how regional service density, captive battery supply, and compliance bundling reshape margin architecture across Asia-Pacific warehousing and construction applications.
| Leading Market Players |
|---|
| XCMG Group |
| ZPMC |
| Hyundai Construction Equipment |
| Doosan Bobcat |
| Nishio Rent All |
| Toyota Material Handling |
| KION Group |
| Jungheinrich AG |
| Hangcha Group |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure on South Korean lithium battery imports compresses margin spreads between premium and economy rental tiers while forcing fleet lessors toward Chinese cell suppliers and domestic assembly partnerships. This trade friction simultaneously widens pricing differentials across electrification-ready corridors and reshapes procurement geography toward vertically integrated equipment manufacturers.
Pricing Analysis
The technology-generation pricing gap separating lithium-ion electric fleets from legacy lead-acid and internal combustion units spans three distinct tiers. Three-tier pricing structure across premium telematics-enabled, standard compliance-grade, and economy basic-service levels reflects battery chemistry grade and METI/CEA certification burden. Cost compression in economy diesel rentals is intensifying because MIIT GB standard enforcement erodes residual values and compresses secondary market liquidity. Third-party logistics operators in Southeast Asia exhibit highest price sensitivity, while Japanese automotive manufacturing hubs show lowest sensitivity due to bundled compliance service requirements.
Supply Chain Analysis
Extended payment terms from Chinese lithium carbonate refiners and supply-chain finance facilities anchored in Shanghai commodity exchanges ease working capital burdens for fleet acquisition. Battery cell production concentrates in China, South Korea, and Japan, while forklift chassis assembly clusters in Chinese provincial manufacturing belts. Raw material dependencies span lithium carbonate, rare-earth permanent magnets, and high-grade steel. Single-source vulnerability in South Korean cathode active material exposes rental providers to geopolitical supply disruption. Distribution runs through direct OEM provincial hub networks and specialized rental service providers with dense technician coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific forklift rental represents a high-growth disruption as China's MIIT emissions deadlines force diesel-to-electric fleet turnover across coastal logistics corridors.
For Market Incumbents: Build captive battery supply moats through in-house lithium cell production or binding offtake agreements with South Korean suppliers. Toyota Material Handling and Hangcha Group anchor defensive positioning through proprietary telematics platforms that lock in multi-year warehousing contracts. Counter emerging Chinese OEM price pressure by embedding METI-mandated compliance services into contract structures that transfer certification liability. Add dedicated charging infrastructure capacity in India's NCR and Maharashtra industrial belts before CEA siting requirements tighten. For New Entrants and Emerging Players: Vietnam's Hai Phong and Bac Ninh industrial zones offer greenfield rental fleet partnerships as EU-bound export compliance tightens electrification requirements. Indonesia's e-commerce logistics corridors present underpenetrated short-term rental demand for festival seasonality management. Target Australia's mining sector with technician-attached packages that assume operator certification burdens. Prioritize usage-based billing platforms that capture pallet-movement data for outcome pricing experiments. For Investors and Strategic Acquirers: The market sits at a regulatory-inflection phase that favors vertically integrated equipment manufacturers with captive battery supply over pure-play rental service providers. Long-term viability across the projection horizon hinges on telematics-enabled asset management capabilities and charging infrastructure deployment scale. Acquisition target archetype: mid-cap regional rental providers with dense technician networks in tier-one Chinese or Japanese metropolitan markets. Monitor MIIT enforcement velocity in Shanghai and Shenzhen low-emission zones as the signal for fleet turnover acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | CEA electrical safety compliance in Indian industrial belts requires depot electrical upgrade coordination with grid operators. |
| Telematics Platform Integration | Yangtze River Delta fulfillment operators mandate real-time battery state-of-health monitoring in tender specifications. |
| Backward Integration into Lithium Cells | Hangcha Group's captive battery production narrows total-cost differentials against internal combustion rental options. |
| Compliance Service Bundling | Japan's METI-mandated recertification protocols embed liability transfer into premium rental contract structures. |
| Geographic Expansion into Vietnam | Hai Phong industrial zone development creates greenfield demand for rental fleet partnerships among EU-export manufacturers. |
Research Methodology
The analysis maps electric forklift, diesel forklift, gas forklift, and industrial reach truck sub-sectors, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with warehouse operators, construction project managers, and fleet lessor executives combined with secondary validation from customs/trade data, MIIT regulatory filings, and SEC 10-K disclosures. Bottom-up equipment deployment estimates triangulated against top-down regional industrial output projections.
The assumption-set holds MIIT GB standard enforcement timelines and lithium carbonate price trajectories fixed while varying e-commerce penetration rates and ASEAN manufacturing relocation velocity. Segmentation dimensions modeled span product type, end-user industry, service duration, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and fleet telematics utilization data. Forecast inputs include battery cost curve trajectories and charging infrastructure deployment pipelines.
Macroeconomic conditions sit as an overlay; deviation in regional industrial production indices or cross-border trade policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Vertical Platform Lift Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Stair Lifts and Climbing Devices Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Bulk Material Handling System Market