
 Forklift Truck Market | 2026-2036
Forklift Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift Truck Market Intelligence
Multi-source component procurement is recalibrating how forklift manufacturers balance cost against supply security. Toyota Material Handling leverages its captive production of electric drivetrains to control quality and delivery timelines. Hangcha Group competes aggressively on manufacturing scale, while Jungheinrich AG specializes in narrow-aisle warehouse trucks for high-density European distribution networks.
A forklift truck is a powered industrial vehicle equipped with hydraulic lifting mechanisms, typically rated by load capacity from 1 ton to 10 tons, designed to transport and stack materials over short distances. Electric variants now dominate new orders in indoor applications due to zero-emission operation and lower total cost of ownership. Warehouse handling applications absorb the largest volume of electric units, while shipping ports still favor diesel and LPG configurations for heavy outdoor lifts. The 3-ton and 5-ton load capacity brackets capture the widest buyer base across manufacturing plants and logistic centers.
The EPA enforces Tier 4 Final emissions standards for diesel forklifts in the United States, compelling engine redesigns and after-treatment systems. The EU F-Gas Regulation and REACH framework constrain refrigerant choices and material composition in European-sold equipment. OSHA mandates operator certification and workplace safety protocols that shape fleet purchasing criteria. Stakeholders must monitor how battery chemistry regulations and charging infrastructure investments alter the electric-versus-combustion procurement calculus.
Market Dynamics
Battery-electric powertrains are compressing the traditional diesel-LPG technology hierarchy as emissions protocols tighten across industrial corridors. Fleet operators now face capital allocation decisions between upfront battery costs and long-term operational savings, reshaping procurement cycles and supplier relationships simultaneously.
Growth Catalysts
- E-commerce fulfillment infrastructure:Distribution centers in the United States and Germany are expanding automated material handling capacity. Multi-shift operations favor electric units for indoor air quality compliance.
- REACH material constraints:The EU framework is phasing out hazardous substances in hydraulic fluids and battery components. Equipment redesigns toward compliant chemistries open replacement demand.
- Lithium-ion cell cost curves:Energy density improvements are extending electric forklift runtime into applications previously reserved for internal combustion. Manufacturing plants in China's Jiangsu province are capturing scale advantages in battery pack assembly.
Market Restraints
- Cathode material volatility:Lithium and cobalt price swings distort total cost of ownership calculations for electric fleet conversions. Buyers defer commitments during commodity spikes.
- Charging infrastructure gaps:Warehouse electrical capacity in older industrial zones limits fast-charging deployment. Retrofit costs often exceed vehicle price premiums.
- Skill scarcity in high-voltage maintenance:Certified technicians for battery management systems remain concentrated in automotive hubs. Regional service networks lack coverage density.
Strategic Opportunities
- India's manufacturing corridors:The PLI scheme for advanced chemistry cell production is localizing battery supply chains. Forklift electrification aligns with the country's dual carbon commitments under MEE guidelines.
- Autonomous navigation convergence:LiDAR and machine vision integration is enabling unmanned pallet movement in hazardous environments. Chemical processing facilities represent early adoption verticals.
- Rental and subscription channels:Asset-light procurement models are penetrating small and mid-sized logistics operators. Third-party fleet managers assume residual value risk.
Industry Challenges
- OSHA certification bottlenecks:Operator training program capacity constraints extend onboarding timelines for new fleet deployments. Qualified instructors concentrate in metropolitan logistics clusters.
- Legacy fleet integration:Mixed combustion-electric environments complicate maintenance standardization and parts inventory management. Facilities managers face workflow fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift Truck Market |
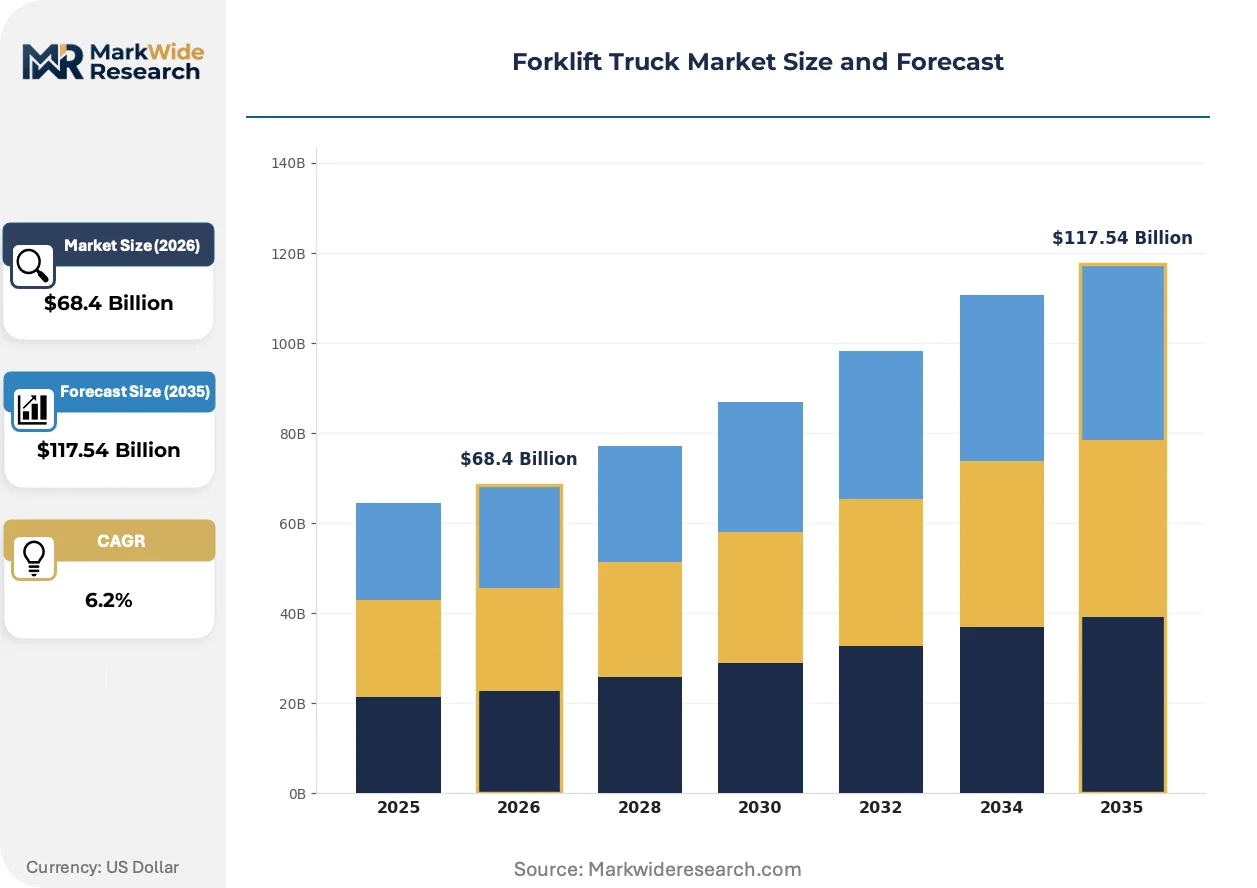
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Diesel, LPG, Gasoline, Hydraulic Load Capacity: 1 Ton, 2 Tons, 3 Tons, 5 Tons, 10 Tons Application: Warehouse Handling, Construction Sites, Manufacturing Plants, Shipping Ports, Logistic Centers End User Industry: Logistics Companies, Construction Contractors, Manufacturing Firms, Warehousing Services |
| Companies Covered | Mitsubishi Logisnext, Crown Equipment, Toyota Material Handling, Doosan Industrial Vehicle, Hangcha Group, KION Group, Hyster-Yale Group, Clark Material Handling, Jungheinrich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift Truck Market Strategic Shifts & Innovations
Telematics and predictive maintenance systems are transforming fleet management from reactive repair schedules to uptime optimization. Data-driven asset utilization is compressing replacement cycles and reshaping supplier service obligations.
Fleet telematics platforms are decentralizing maintenance decision-making away from centralized workshop models. Third-party logistics operators in the United States are adopting over-the-air diagnostics to triage faults before dispatch. Real-time battery health monitoring is enabling opportunistic charging protocols that extend shift coverage without infrastructure expansion.
The EPA Tier 4 Final standards are forcing diesel engine redesigns with selective catalytic reduction and diesel particulate filter integration. After-treatment complexity is elevating purchase prices and maintenance intervals for combustion units. Port operators in Long Beach and Rotterdam are accelerating electric pilot programs to avoid compliance cost escalation.
Leasing structures are displacing outright purchase in mid-market segments as buyers prioritize cash flow flexibility. Full-service contracts bundle maintenance, energy, and software into per-hour rates. German automotive suppliers and Dutch cold-chain distributors are driving this contract structure toward standard industry practice.
Forklift Truck Market Segmentation
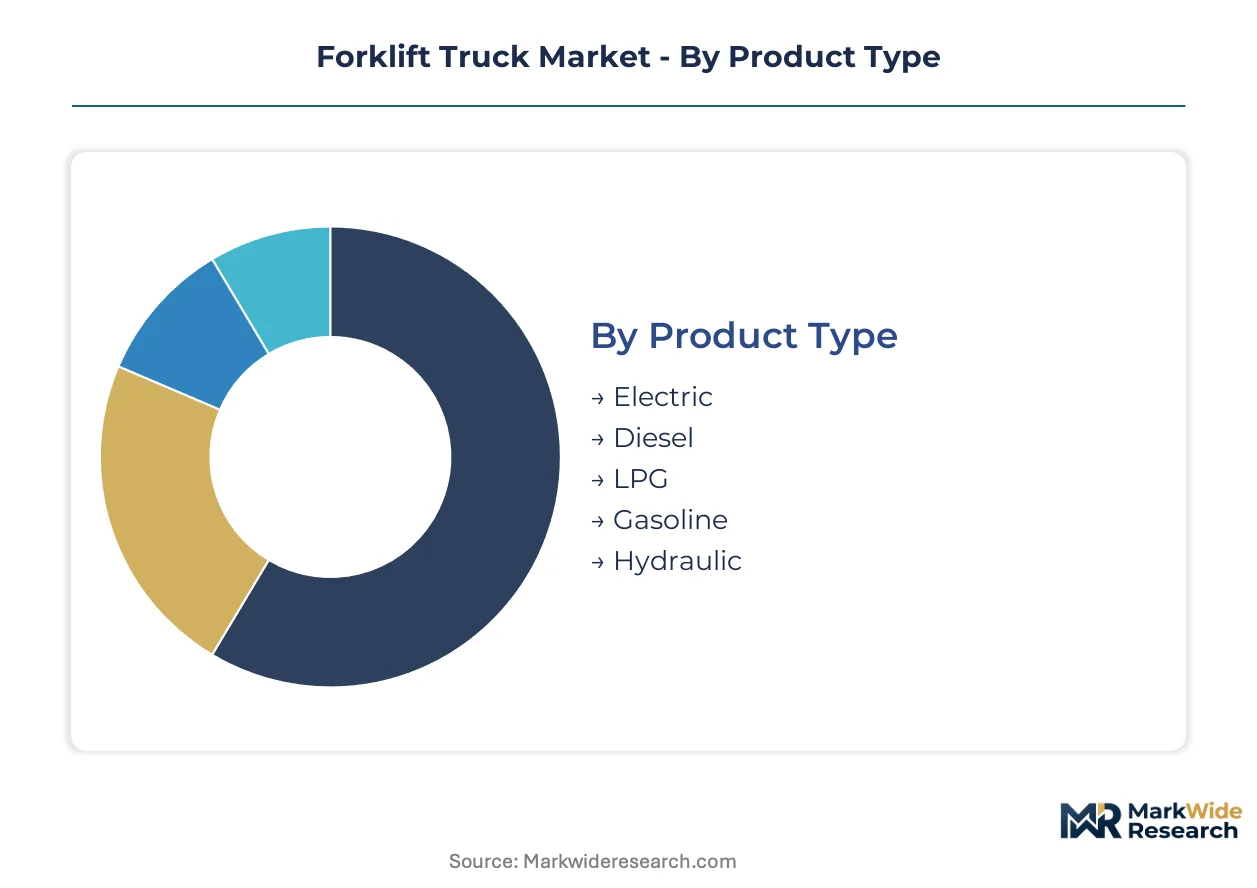
Segmentation in the forklift truck market reveals how regulatory pressure and operational intensity concentrate procurement decisions across distinct equipment categories. Buyers align powertrain choices, load ratings, and application specifications with site-specific emissions protocols and duty cycle demands.
Product Type:
EPA Tier 4 Final certification governs diesel forklifts in the United States, while EU F-Gas Regulation constrains refrigerant-bearing electric systems. OSHA operator training mandates apply uniformly across powertrain categories.
- Electric:Battery-electric units utilize lithium-ion or lead-acid chemistries with zero tailpipe emissions. Warehouse handling in Germany's logistics corridor absorbs the highest order volumes as REACH compliance tightens indoor air quality standards. Lithium-ion cost curves compress total cost of ownership advantages against LPG alternatives.
- Diesel:Compression-ignition engines rated above 5 tons dominate shipping port operations in Long Beach and Rotterdam. Selective catalytic reduction and diesel particulate filter integration elevate upfront costs and maintenance intervals under Tier 4 Final mandates.
- LPG:Liquid propane gas configurations bridge indoor-outdoor flexibility with moderate emissions profiles. Food distribution centers in the United States favor LPG where electric infrastructure remains insufficient.
- Gasoline:Spark-ignition engines persist in emerging market construction applications where fuel accessibility trumps emissions compliance. China's manufacturing belt shows residual demand for gasoline units in provincial logistics operations.
- Hydraulic:Fluid-power lifting mechanisms integrate with rough-terrain chassis for uneven ground conditions. Mining and forestry contractors in Canada specify hydraulic systems for slope stability requirements.
Electric sits at the top of the volume ranking, with LPG climbing the fastest as hybrid procurement strategies bridge infrastructure gaps.
Load Capacity:
Cost tier stratification separates premium heavy-lift configurations from standardized mid-capacity workhorses. Margin concentration follows duty cycle intensity rather than absolute tonnage.
- 3 Tons:The universal workhorse rating balances maneuverability with payload flexibility across manufacturing plants and distribution centers. Jiangsu province assembly lines in China standardize on 3-ton electric units for component feeding operations. Multi-shift deployment favors battery swap configurations at this capacity point.
- 5 Tons:Heavy-duty indoor applications and light outdoor duty converge at this specification. Automotive suppliers in Stuttgart specify 5-ton electrics for powertrain component sequencing under just-in-time protocols.
- 1 Ton:Compact pedestrian-operated stackers serve narrow-aisle retail backrooms and pharmaceutical cleanrooms. Cold-chain distributors in the Netherlands deploy 1-ton lithium units for freezer compartment access.
- 2 Tons:Mid-light capacity fills e-commerce fulfillment slotting operations where pallet weights cluster below 1,800 kilograms. Amazon regional sortation centers in the United States standardize fleet procurement at this rating.
- 10 Tons:Heavy-lift container handlers and steel coil transporters require reinforced masts and counterweight engineering. Port authorities in Hamburg specify 10-ton diesel-electrics for intermodal yard operations.
3 Tons commands the largest installed base, while 5 Tons gains share fastest as electrification extends into heavier indoor applications.
Application:
Geographic procurement patterns concentrate electric orders in urban logistics clusters and combustion units in heavy industrial zones. Site-specific emissions enforcement drives technology selection more than operational function alone.
- Warehouse Handling:High-density storage retrieval demands narrow-aisle maneuverability and precise load positioning. Third-party logistics operators in the United States prioritize electric reach trucks for multi-tenant distribution facilities. Telematics integration enables fleet optimization across shift rotations.
- Shipping Ports:Container yards and vessel loading operations expose equipment to salt corrosion and continuous heavy cycling. Rotterdam port authority electrification pilots test 10-ton battery units for transshipment handling under EU Green Deal timelines.
- Construction Sites:Rough-terrain forklifts navigate unpaved surfaces with oscillating axles and all-wheel drive. German construction contractors specify Tier 4 Final diesel units for infrastructure projects under federal emissions enforcement.
- Manufacturing Plants:Assembly line feeding and work-in-progress movement require synchronized delivery windows. Automotive OEMs in China's Guangdong province deploy autonomous guided vehicles for component sequencing.
- Logistic Centers:Cross-dock operations and last-mile consolidation facilities balance throughput velocity with space constraints. Dutch cold-chain distributors integrate electric pallet trucks with refrigerated trailer loading systems.
Warehouse Handling leads order volumes, with Shipping Ports expanding most quickly as electrification pilots scale toward fleet conversion.
End User Industry:
Customer type determines procurement sophistication, with logistics specialists deploying fleet management systems and construction buyers prioritizing acquisition price over lifetime optimization.
- Logistics Companies:Asset-heavy operators deploy telematics platforms and predictive maintenance contracts across multi-site networks. DHL Supply Chain in Germany standardizes Jungheinrich electrics with full-service leasing structures.
- Manufacturing Firms:Captive fleet operations align equipment specification with production line cadence and facility layout constraints. Bosch manufacturing sites in Stuttgart specify narrow-aisle configurations for component supermarket retrieval.
- Construction Contractors:Project-based procurement favors rental channels and short-term leasing over capital deployment. Turner Construction in the United States sources rough-terrain units through national rental networks.
- Warehousing Services:Third-party storage operators face tenant-driven equipment requirements and multi-shift utilization pressure. Prologis facilities in the Netherlands integrate electric charging infrastructure into building specifications.
Logistics Companies dominate fleet procurement scale, with Manufacturing Firms showing the steepest expansion trajectory as in-house distribution networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's logistics corridor generates the densest concentration of electric forklift procurement, driven by multi-shift distribution networks and stringent indoor emissions protocols. Fleet operators across Stuttgart, Hamburg, and the Ruhr industrial belt prioritize battery-electric configurations for warehouse automation. Regulatory enforcement of EU F-Gas Regulation and REACH framework accelerates equipment replacement cycles.
United States
E-commerce fulfillment centers in Illinois, Pennsylvania, and California's Inland Empire drive electric unit procurement for indoor air quality compliance. EPA Tier 4 Final standards compel diesel engine redesigns with selective catalytic reduction systems. Port operators in Long Beach pilot 10-ton battery configurations to avoid escalating after-treatment maintenance costs.
China
Manufacturing plants in Jiangsu and Guangdong provinces standardize on 3-ton electric units for component feeding and assembly line sequencing. The Ministry of Ecology and Environment's dual carbon goals accelerate electrification timelines. Battery pack assembly clusters in Suzhou capture scale advantages from domestic lithium-ion cell production.
Germany
Automotive suppliers in Stuttgart and third-party logistics operators in the Ruhr region deploy narrow-aisle electric reach trucks for high-density storage retrieval. EU F-Gas Regulation constrains refrigerant choices in cold-chain equipment. Jungheinrich AG's captive production network anchors specialized warehouse truck supply.
India
The Production-Linked Incentive scheme for advanced chemistry cell production localizes battery supply chains for forklift electrification. Manufacturing corridors in Maharashtra and Gujarat absorb mid-capacity electric units under MEE carbon commitment timelines. Logistics operators in Mumbai-Pune belt face charging infrastructure gaps in older industrial zones.
Netherlands
Cold-chain distributors in Rotterdam and Venlo integrate electric pallet trucks with refrigerated trailer loading systems. EU Green Deal timelines drive port authority electrification pilots for transshipment handling. Prologis facilities embed charging infrastructure specifications into warehouse construction standards.
Forklift Truck Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue autonomous navigation and battery chemistry specialization. The vendor base stratifies across three archetypes: integrated drivetrain manufacturers controlling captive electric component supply, scale-driven fabricators competing on manufacturing throughput, and narrow-aisle specialists serving high-density European distribution networks. Strategic moves concentrate on backward integration into battery pack assembly and telematics platform development.
Among Germany-based specialists, Jungheinrich AG exemplifies the narrow-aisle warehouse truck archetype. Toyota Material Handling represents the integrated drivetrain tier with captive electric component production. Hangcha Group occupies a position within the scale-driven manufacturing segment. These three anchors illustrate how competitive positioning diverges across specialization vectors rather than converging on uniform technology platforms.
| Leading Market Players |
|---|
| Mitsubishi Logisnext |
| Crown Equipment |
| Toyota Material Handling |
| Doosan Industrial Vehicle |
| Hangcha Group |
| KION Group |
| Hyster-Yale Group |
| Clark Material Handling |
| Jungheinrich AG |
| Others |
Cost & Logistics Intelligence
Captive in-house production of lithium-ion battery packs anchors competitive positioning for electric forklift manufacturers, compressing supplier margins while securing procurement predictability against cathode material volatility. Toyota Material Handling leverages this integration pattern to buffer pricing power from commodity swings, whereas Hangcha Group absorbs cost compression through manufacturing scale advantages in Jiangsu province.
Pricing Analysis
Input-cost pass-through from lithium carbonate and cobalt sulfate fluctuations reshapes total cost of ownership calculations for fleet operators evaluating electric conversions. Three-tier pricing structure across premium, standard, and economy levels separates Jungheinrich AG's narrow-aisle specialists from volume-driven Chinese fabricators and rental-channel intermediaries. Cost compression in the standard tier intensifies because Hangcha Group and Anhui Heli scale Jiangsu assembly lines. Small logistics operators show highest price sensitivity, while automotive OEM captive fleets prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
India's Production-Linked Incentive scheme for advanced chemistry cell production reshapes sourcing patterns, compelling manufacturers to localize battery pack assembly under MEE carbon commitment timelines. Geographic supply concentration centers on China for lithium-ion cells, South Korea for cathode materials, and Germany for precision hydraulic components. Raw material dependencies draw from Chilean lithium brine, Indonesian nickel laterite, and Japanese electrolyte formulations. Single-source vulnerability in cathode precursor supply elevates disruption risk. Distribution runs through manufacturer-direct channels for large fleet accounts and third-party rental networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Tier 4 Final and EU F-Gas Regulation milestones force fleet replacement cycles regardless of underlying industrial demand.
For Market Incumbents: Anchor defensive positioning through backward integration into battery management system production and telematics platform development. Threat from autonomous navigation startups compressing service revenue pools demands preemptive software investment. Certification leverage under OSHA operator training mandates protects channel control against rental-channel disintermediation. For New Entrants and Emerging Players: Enter via India's Maharashtra and Gujarat manufacturing corridors where PLI-localized cell production erodes incumbent battery cost advantages. White-space targets include high-voltage maintenance service networks in secondary US industrial zones and autonomous pallet movement for chemical processing facilities. Go-to-market angle emphasizes asset-light subscription pricing for mid-market logistics operators. For Investors and Strategic Acquirers: Roll-up economics work for regional forklift rental specialists because fragmented fleet ownership among small logistics operators creates consolidation arbitrage on residual value management. Long-term viability hinges on charging infrastructure deployment velocity as electrification penetration inflection. Signal to watch: port authority electrification pilot conversion rates in Long Beach and Rotterdam scaling from trial units to fleet procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term lithium-ion cell offtake secures cost predictability against cathode material volatility. |
| Telematics Platform Development | Over-the-air diagnostics shift maintenance revenue from reactive repair to subscription uptime guarantees. |
| Charging Infrastructure Partnership | Collaboration with warehouse developers embeds electrical capacity specifications into new construction standards. |
| Autonomous Navigation Investment | LiDAR and machine vision integration enables unmanned pallet movement in hazardous chemical environments. |
| Regional Rental Network Acquisition | Consolidation of third-party fleet managers captures residual value risk and recurring service revenue streams. |
Research Approach
Direct dialogue with plant engineers, OEM procurement teams, aftermarket service heads, and warehouse operations directors grounded qualitative findings in operational constraints. Secondary validation drew from EPA enforcement records, EU F-Gas Regulation implementation guidance, SEC filings of publicly listed material handling equipment manufacturers, and customs trade data on lithium-ion battery pack imports. Bottom-up fleet deployment estimates triangulated against top-down manufacturing capacity assessments across the analysis window.
Segment-level projections incorporated powertrain technology, load capacity tier, application intensity, and regional emissions enforcement clustering. CAGRs derived from historical replacement cycle patterns, electrification penetration curves, and infrastructure deployment timelines. Industry-specific inputs included lithium-ion cell cost trajectories, OSHA certification program capacity constraints, and port authority pilot conversion assumptions.
The model holds under sustained regulatory enforcement of Tier 4 Final and REACH frameworks; deviation in battery chemistry safety standards or charging infrastructure subsidy withdrawal would shift electrification penetration trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Conveyor Belt Market