
 Pallet Circulation System Market | 2026-2036
Pallet Circulation System Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Circulation System Market Analytics
Subscription-based maintenance and software-defined fleet tracking is repositioning pallet circulation from capital expenditure into operating expenditure models. Weckenmann Anlagentechnik leverages its German engineering base to dominate high-throughput precast concrete applications. Vollert Anlagenbau anchors its position through deep backward integration into steel fabrication and control systems. Olmet competes in Southern European markets with modular, scalable configurations that reduce installation downtime.
A pallet circulation system is an engineered material-handling infrastructure that moves standardized load carriers through closed-loop paths using roller conveyors, chain drives, or automated guided vehicles, typically rated for loads exceeding 1,500 kg per pallet position, designed to synchronize production flow with inventory buffers in manufacturing and distribution environments. Automated systems command the widest installed base among product configurations, though hybrid systems that blend manual intervention with selective automation are capturing margin pools in mid-scale operations. Within end-user categories, manufacturing units sustain the deepest penetration because just-in-time assembly lines require synchronized pallet return mechanisms that warehouse operators rarely replicate at comparable intensity.
The EU Green Deal and its packaging waste directives, alongside Germany's KBA transport safety standards and REACH chemical compliance for polymer pallet components, are tightening material traceability and durability requirements across European supply chains. FDA food-contact regulations in North America and China's GB standards for load-bearing industrial equipment add parallel compliance layers for multinational operators. Stakeholders must decide whether to pursue region-specific certification strategies or harmonize product platforms across regulatory regimes before committing capital to new production capacity.
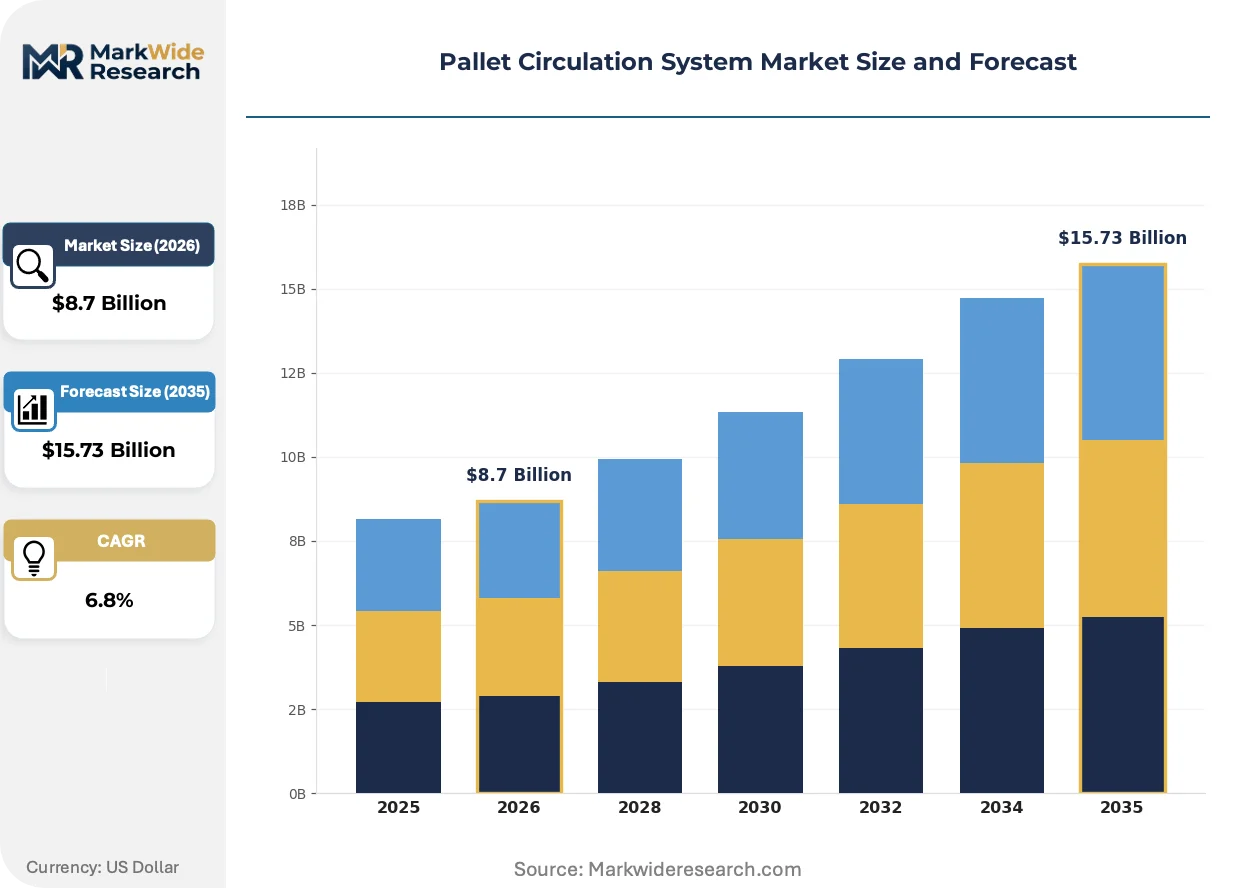
Market Dynamics
Subscription-based fleet tracking software is converting pallet circulation from capital expenditure to operating expenditure, forcing manufacturers to build recurring revenue capabilities alongside hardware engineering.
Growth Catalysts
- EU Green Deal packaging directives:Reusable pallet mandates are accelerating closed-loop network investments across European cold-chain logistics operators.
- Precast concrete manufacturing clusters:Germany's dense concentration of precast plants generates specialized demand for heavy-duty circulation systems rated above 1,500 kg per position.
- Food and beverage cold-chain expansion:Pooling programs are displacing single-use packaging as operators face waste reduction targets.
Market Restraints
- Steel input cost volatility:Roller conveyor and chain drive fabrication depends on steel price stability, squeezing margins when commodity markets fluctuate.
- REACH compliance burden:Polymer pallet component manufacturers face chemical traceability requirements that extend certification timelines.
- Manual handling substitution:Forklift and manual pallet jack operations retain cost advantages in low-throughput warehouse environments.
Strategic Opportunities
- Hybrid system white space:Mid-scale manufacturing operations seek selective automation blending manual intervention with automated guided vehicle segments.
- GB standards alignment:China's load-bearing equipment certification creates entry pathways for European suppliers targeting industrial logistics modernization.
- Software-defined fleet convergence:Integration of IoT sensors with predictive maintenance platforms opens service revenue streams beyond hardware sales.
Industry Challenges
- Control systems integration complexity:Legacy manufacturing execution systems require custom middleware to interface with modern pallet circulation controllers.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact, KBA transport safety, and REACH compliance extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Circulation System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Hybrid Systems, Custom Solutions End User: Warehouse Operators, Distribution Centers, Retailers, Manufacturing Units Technology: RFID Tracking, Conveyor Systems, Robotics, IoT-Based Solutions Application: Food & Beverage, Pharmaceuticals, Consumer Goods, Automotive Parts |
| Companies Covered | Weckenmann Anlagentechnik, Vollert Anlagenbau, Olmet, Tecno Germa, Avermann, PREQAST Precast Technology, Unitechnik, Moldtech, INDIAPRECAST, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Circulation System Market Evolving Landscape
Electrification of drive mechanisms and sensor networks is compressing the performance gap between automated and hybrid system configurations.
Brushless DC motor arrays with regenerative braking are electrifying roller conveyor segments previously powered by pneumatic or hydraulic systems. Precast concrete manufacturers in Germany are adopting these electrified drives to synchronize curing cycle timing with pallet return velocity. The shift is electrifying demand for integrated power management systems that consolidate motor control into centralized software platforms.
REACH chemical compliance is forcing polymer pallet component suppliers to reformulate glass-filled nylon compounds and eliminate restricted plasticizers. The regulation is compressing supplier qualification timelines as manufacturers demand batch-level traceability documentation. Food-contact applications face the steepest compliance burden, with operators in France and Germany requiring third-party certification for every polymer formulation change.
Buyers are unbundling after-sales service contracts from initial equipment procurement, treating maintenance as a separate competitive tender. Manufacturing units with just-in-time assembly lines are driving this shift, demanding uptime guarantees rather than parts warranties. The pattern is most visible in Southern European markets where modular system configurations reduce installation downtime and enable faster vendor switching.
Pallet Circulation System Market Segmentation
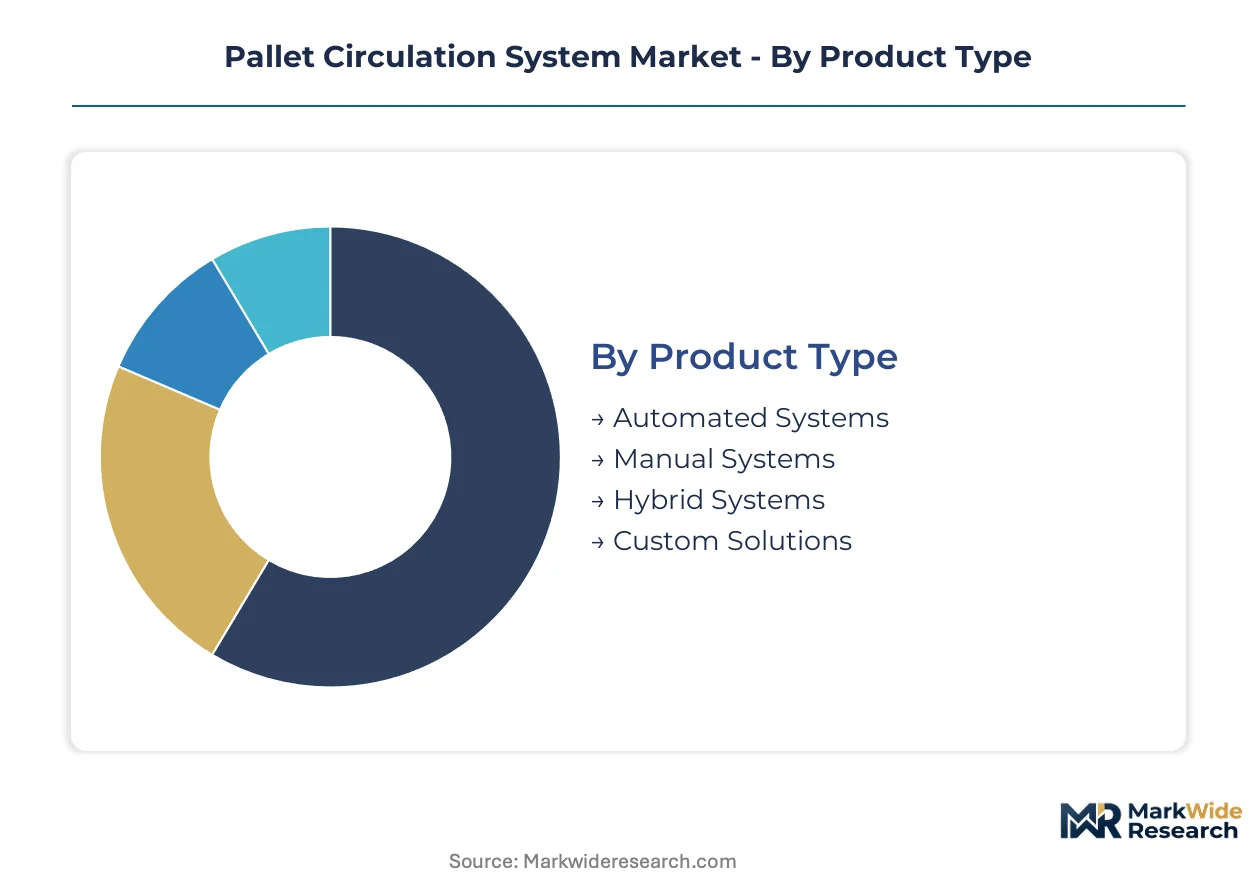
Pallet circulation system procurement varies sharply by operational intensity and load requirements. Buyers prioritize throughput velocity, regulatory compliance exposure, and integration complexity when selecting across product configurations and technology tiers.
Product Type:
Capital commitment thresholds and labor substitution ratios separate buyers across automation levels.
- Automated Systems:Roller conveyor and chain drive configurations synchronized with programmable logic controllers handle continuous flows exceeding 1,500 kg per pallet position. German precast concrete manufacturers deploy these for curing cycle synchronization where downtime costs exceed €50,000 per hour.
- Hybrid Systems:Blending manual intervention zones with selective automated guided vehicle segments, these configurations target mid-scale operations seeking staged automation. Southern European food processors favor modular installations that reduce commissioning downtime during facility retrofits.
- Manual Systems:Forklift-compatible gravity roller sections serve low-throughput warehouse operators in France and Italy where labor arbitrage persists.
- Custom Solutions:Engineered-to-order configurations address non-standard load geometries or extreme temperature ranges in pharmaceutical cold-chain applications.
Automated systems lead volumes today; hybrid configurations are gaining share fastest among budget-constrained expansions.
End User:
Inventory velocity and just-in-time synchronization requirements determine specification intensity across buyer categories.
- Manufacturing Units:Assembly line synchronization demands closed-loop pallet return mechanisms with sub-minute cycle times. German automotive suppliers mandate EU Green Deal-compliant reusable networks to eliminate single-use packaging from inbound component flows.
- Distribution Centers:Cross-docking operations prioritize throughput over storage density, driving demand for high-speed conveyor segments with RFID-based sortation. Operators in the Netherlands face REACH chemical traceability requirements for polymer pallet components in food-contact applications.
- Warehouse Operators:Third-party logistics providers balance capital efficiency against service-level agreements, often leasing hybrid configurations to preserve balance sheet flexibility.
- Retailers:Store-level backroom constraints limit system scale, favoring compact manual or semi-automated solutions for inbound merchandise handling.
Manufacturing units command specification authority today; distribution centers are expanding installed base most rapidly.
Technology:
Data granularity and predictive capability separate technology tiers rather than mechanical performance alone.
- IoT-Based Solutions:Sensor networks embedding vibration, temperature, and load sensors enable predictive maintenance platforms that convert hardware sales into recurring service revenue. German engineering firms integrate these with centralized power management for electrified drive arrays.
- RFID Tracking:Ultra-high frequency tags coupled with fixed reader infrastructure provide batch-level traceability documentation demanded by REACH-compliant polymer component suppliers. French food-contact applications require third-party certification for every formulation change tracked through these systems.
- Conveyor Systems:Brushless DC motor arrays with regenerative braking are displacing pneumatic and hydraulic power in roller segments, compressing energy consumption and maintenance intervals.
- Robotics:Articulated arm and gantry systems handle non-standard pallet configurations or depalletizing operations in pharmaceutical serialization environments.
Conveyor systems anchor installed base today; IoT-based solutions are climbing the fastest as subscription models displace capital sales.
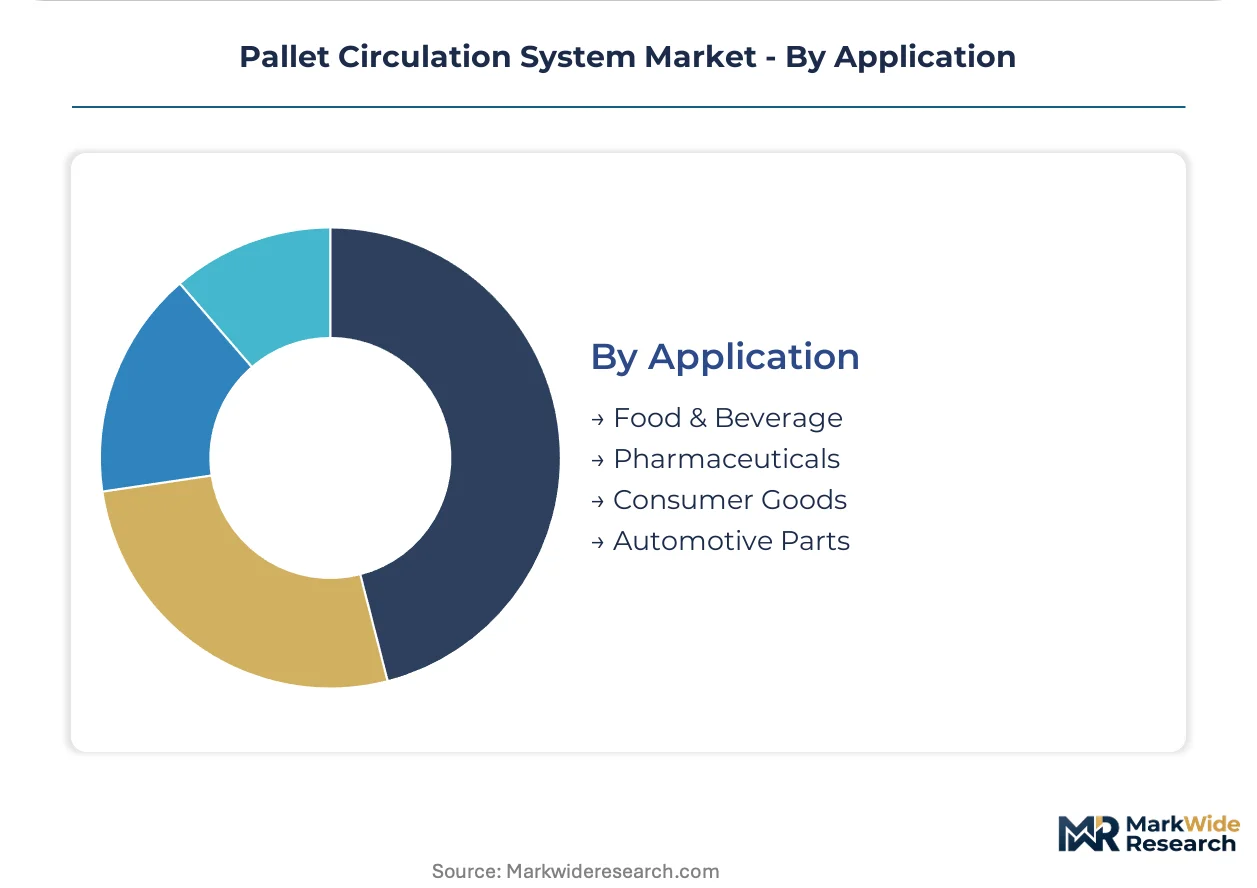
Application:
Regulatory exposure and load standardization determine system specification across vertical markets.
- Food & Beverage:Cold-chain operators face EU Green Deal packaging waste directives accelerating closed-loop pooling program investments. German dairy processors deploy heavy-duty circulation systems rated for hygienic washdown cycles and temperature cycling between ambient and frozen zones.
- Pharmaceuticals:Serialization and anti-counterfeiting mandates drive RFID and IoT sensor integration for unit-level traceability. Operations in Germany and France demand FDA-aligned documentation for export-bound production.
- Automotive Parts:Just-in-sequence delivery to assembly plants requires sub-minute pallet return cycles synchronized with production scheduling systems.
- Consumer Goods:High SKU variability and seasonal demand spikes favor modular hybrid configurations that scale throughput without full automation commitment.
Food and beverage leads segment volumes today; pharmaceuticals are expanding specification intensity fastest under serialization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specialized heavy-duty demand while the United States drives software-enabled fleet tracking adoption. France and Italy concentrate food-contact compliance investments. China's industrial logistics modernization creates parallel certification pathways.
Germany
Precast concrete manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia sustain demand for systems rated above 1,500 kg per pallet position. KBA transport safety standards and REACH chemical compliance tighten material traceability requirements across polymer component supply chains. Weckenmann Anlagentechnik and Vollert Anlagenbau anchor their engineering bases in southwestern industrial corridors serving automotive and construction material flows.
United States
FDA food-contact regulations drive RFID and IoT sensor integration for cold-chain traceability in dairy and pharmaceutical distribution. The EPA's focus on industrial energy efficiency accelerates brushless DC motor adoption with regenerative braking in conveyor segments. Midwest automotive suppliers and Southeast food processors are unbundling after-sales service contracts from initial equipment procurement.
France
Food-contact applications face steep compliance burdens under EU Green Deal packaging directives and REACH chemical traceability requirements. Third-party certification for every polymer formulation change compresses supplier qualification timelines. Dairy processors in Normandy and Brittany deploy heavy-duty circulation systems rated for hygienic washdown cycles between ambient and frozen zones.
Italy
Modular system configurations reduce installation downtime and enable faster vendor switching in Southern European markets. Olmet competes with scalable configurations targeting mid-scale manufacturing operations seeking staged automation. Emilia-Romagna's packaging machinery corridor and Lombardy's logistics hubs drive hybrid system specifications blending manual intervention with selective automation.
China
GB standards for load-bearing industrial equipment create entry pathways for European suppliers targeting industrial logistics modernization. MIIT's smart manufacturing initiatives accelerate IoT sensor deployment in automotive and consumer goods distribution. Yangtze River Delta and Pearl River Delta manufacturing clusters are expanding pallet pooling programs to displace single-use packaging waste.
Pallet Circulation System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with engineering-intensive configurations favoring integrated solution providers while standardized components attract fabrication houses. The vendor base concentrates around German precision engineering, Italian modular flexibility, and emerging Asian scale players. Three archetypes dominate: full-system integrators with captive steel fabrication, modular configuration specialists, and component suppliers seeking upstream assembly partnerships. Competitive positioning hardens through backward integration into control systems and predictive maintenance platform development.
Among German-based engineering firms, Weckenmann Anlagentechnik GmbH and Vollert Anlagenbau GmbH exemplify the integrated-system archetype with deep backward integration into steel fabrication and centralized power management. Olmet S.r.l. represents the modular-specialist position with configurations targeting Southern European retrofit markets. These three entities anchor the competitive landscape across distinct geographic and specification tiers without overlapping strategic positioning.
| Leading Market Players |
|---|
| Weckenmann Anlagentechnik |
| Vollert Anlagenbau |
| Olmet |
| Tecno Germa |
| Avermann |
| PREQAST Precast Technology |
| Unitechnik |
| Moldtech |
| INDIAPRECAST |
| Others |
Value Network & Pricing Analysis
Electrification of drive mechanisms through brushless DC motor arrays with regenerative braking is compressing both capital and operating cost structures while concentrating supply relationships among German engineering firms with captive steel fabrication capabilities. This technological shift simultaneously reduces energy consumption per pallet position and raises barriers for component suppliers lacking centralized power management integration.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for standardized conveyor segments while European producers defend premium positioning through REACH-compliant polymer formulations and KBA-certified transport safety documentation. Three-tier pricing structure across premium, standard, and economy levels separates fully automated systems with predictive maintenance platforms from modular hybrid configurations and manual gravity roller installations. Cost compression in economy-tier manual systems is intensifying because Chinese fabricators are expanding export capacity for forklift-compatible segments. Third-party logistics providers leasing hybrid configurations exhibit highest price sensitivity, while German precast concrete manufacturers with downtime costs exceeding €50,000 per hour demonstrate lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Belgium function as hub-and-spoke consolidation points for RFID tracking hardware and IoT sensor networks serving European cold-chain operators. Geographic supply concentration centers on Germany for precision-engineered steel frames and control systems, Italy for modular configuration platforms, and China for motor drives and standardized roller components. Raw material dependencies draw from specialty steel grades for heavy-duty load positions, glass-filled nylon compounds reformulated for REACH compliance, and semiconductor chips for programmable logic controllers. Single-source vulnerability persists for EU-certified polymer formulations required by French food-contact applications. Distribution runs through direct OEM relationships for automated systems and aftermarket parts distributors for maintenance-intensive hybrid installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pallet circulation system procurement has shifted toward premium specifications as just-in-time assembly lines demand uptime guarantees rather than parts warranties, transforming this into a late-cycle quality story where engineering depth and service integration determine sustainable positioning.
For Market Incumbents: To counter margin erosion from Chinese fabricators expanding into standardized conveyor segments, deepen backward integration into steel fabrication and predictive maintenance platform development. Prioritize certification investment for REACH-compliant polymer formulations and KBA transport safety documentation that creates switching costs for German automotive and precast concrete customers. Channel control through captive service networks preserves pricing power against leasing-oriented third-party logistics providers.
For New Entrants and Emerging Players: The mid-scale manufacturing price-point gap between premium automated systems and economy manual configurations offers viable entry territory for modular hybrid specialists. Southern European food processors in Italy and Spain present the most penetrable geography, where installation downtime sensitivity and faster vendor switching enable competitive displacement. Go-to-market execution should emphasize staged automation roadmaps with subscription-based fleet tracking software that converts capital expenditure into operating expenditure.
For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers lacking upstream assembly partnerships or predictive maintenance capabilities. Long-term viability over the next decade favors integrated-system archetypes with captive steel fabrication and software-defined fleet convergence. Acquisition targets should display control systems integration expertise and recurring service revenue streams. Watch for inflection when EU Green Deal packaging waste directives trigger mandatory closed-loop pooling program investments across food and beverage cold-chain operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Captive supply of heavy-duty frames insulates margin from commodity volatility and secures KBA certification pathways. |
| Predictive Maintenance Platform Development | IoT sensor networks embedding vibration and load monitoring convert hardware sales into recurring service revenue streams. |
| REACH-Compliant Polymer Reformulation | Third-party certified glass-filled nylon compounds unlock French and German food-contact applications with batch-level traceability. |
| Hybrid System Modular Configuration | Scalable installations reducing commissioning downtime target Southern European retrofit markets with faster payback periods. |
| GB Standards Alignment for China Entry | MIIT smart manufacturing initiatives in Yangtze River Delta clusters create certification pathways for European engineering firms. |
Research Methodology
Bottom-up manufacturing unit and distribution center modeling reconciled against top-down steel fabrication and control systems supplier tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads were combined with secondary validation from customs and trade data, SEC filings of publicly listed material handling equipment manufacturers, and EU regulatory notification databases. Triangulation across these sources ensures segmentation outputs reflect actual procurement patterns rather than theoretical demand curves.
Input-output matrices mapping pallet position throughput to steel input requirements and electrified drive component demand were constructed across the analysis window. Segmentation dimensions modeled include automation level, end-user operational intensity, technology tier by data granularity, and application-specific regulatory exposure. CAGRs were derived from installed base evolution and replacement cycle timing informed by curing cycle synchronization requirements in precast concrete and just-in-sequence delivery mandates in automotive assembly.
Caveats apply where steel price volatility, REACH compliance timeline extensions, or multi-jurisdiction certification delays could materially shift the outlook. Forecasts reflect documented assumptions regarding electrification adoption curves and subscription-based service penetration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Industrial Mezzanines Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Heavy Hex Nuts Market