
 High-Performance Seals Market | 2026-2036
High-Performance Seals Market Size, Share, and Industry Trends Forecast 2026-2036
High-Performance Seals Market Intelligence
Aerospace OEMs is redrawing procurement priorities across the high-performance seals value chain. Trelleborg Sealing Solutions dominates fluoropolymer aerospace applications through captive compounding capabilities in Europe. Freudenberg Sealing Technologies anchors automotive powertrain sealing through backward integration into custom rubber formulation. James Walker competes in nuclear and marine sectors with UK-certified elastomer grades that resist radiation degradation.
High-performance seals are engineered elastomeric or thermoplastic components designed to maintain fluid or gas containment under extreme pressure, temperature, and chemical exposure, typically operating from cryogenic ranges through sustained temperatures above 300°C depending on material grade. Their primary purpose is to prevent leakage in critical rotating, reciprocating, or static equipment interfaces where standard commodity seals would fail. O-rings and gaskets represent the mature volume base, while PTFE and polyurethane formulations capture expanding margin pools in semiconductor fabrication and hydraulic fracturing equipment. Aerospace and oil & gas applications drive specification intensity, with material certification cycles acting as a structural barrier to new entrants.
The EPA enforces material emissions thresholds under TSCA Section 6 for perfluoroalkyl substances used in premium seal grades, while REACH restricts candidate substance migration in European supply chains. The FAA's Parts Manufacturer Approval process shapes aerospace seal qualification timelines and OEM sourcing concentration. ISO 23936-2 and NORSOK M-710 standards govern sour gas compatibility for oil & gas deployments, filtering supplier eligibility by documented aging test performance. Stakeholders must track regulatory divergence between EPA and ECHA substance restrictions when configuring multi-region material platforms.
Market Dynamics
Fluorocarbon material bans under EPA TSCA Section 6 and REACH substance restrictions are forcing compound reformulation across aerospace and automotive supply chains. OEMs are accelerating qualification cycles for PFAS-free alternatives while managing performance degradation risks in critical sealing applications.
Growth Catalysts
- REACH substance restrictions:European chemical phase-outs are compelling seal manufacturers to develop next-generation elastomer formulations. This regulatory pressure creates first-mover advantages for compounders with validated alternatives.
- Aerospace propulsion thermal loads:Next-generation turbine architectures are demanding seal grades rated above 400°C sustained operation. Fluorosilicone and perfluoroelastomer specifications are expanding in engine core zones.
- Hydrogen infrastructure buildout:Germany's industrial corridor around Stuttgart and Mannheim is concentrating demand for high-pressure hydrogen sealing solutions. Fuel cell stack and compression equipment OEMs are sourcing certified H2-compatible grades.
Market Restraints
- Fluoropolymer feedstock concentration:Virgin PTFE and FKM resin supply concentrates among three global chemical producers. Price volatility in tetrafluoroethylene monomer flows directly to seal compounders.
- FAA Parts Manufacturer Approval timelines:Aerospace seal qualification cycles extend 18-36 months for new material platforms. This certification friction locks out unqualified suppliers from OEM sourcing pools.
- Perfluoroalkyl substance liability exposure:Litigation risk around legacy fluorocarbon seal formulations is elevating insurance costs. Manufacturers face retrospective cleanup obligations in industrial groundwater zones.
Strategic Opportunities
- India PLI scheme for specialty chemicals:Domestic compounding incentives are attracting seal material investments near Pune and Ahmedabad. Local formulation capabilities can serve Middle Eastern oil field demand with shorter logistics.
- Additive manufacturing convergence:3D-printed thermoplastic elastomer geometries are enabling complex seal profiles impossible through molding. Semiconductor equipment OEMs are piloting printed labyrinth seals for vacuum chambers.
- EU Green Deal public procurement mandates:Government infrastructure tenders are prioritizing low-carbon seal supply chains. Bio-based polyurethane grades are gaining specification traction in water treatment applications.
Industry Challenges
- Fluoroelastomer compounding expertise scarcity:Formulation chemists with cross-link density optimization experience are concentrated among retiring cohorts. Knowledge transfer gaps threaten quality consistency in custom seal production.
- Multi-standard certification burden:Oil field suppliers must simultaneously satisfy ISO 23936-2 sour gas aging, NORSOK M-710 rapid gas decompression, and API 6A wellhead requirements. Parallel testing regimes compress margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Performance Seals Market |
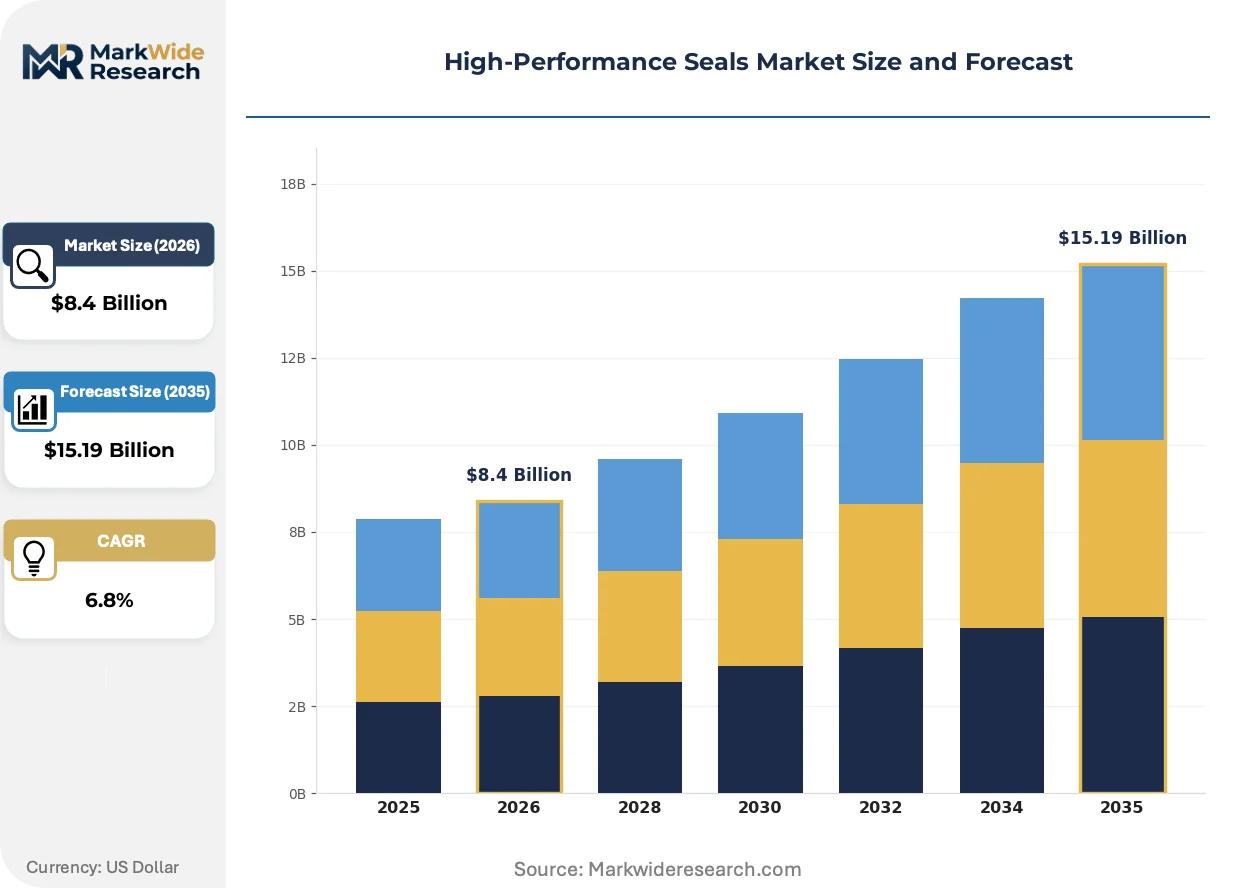
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, U-Cups, Sealing Films Material: Rubber, Polyurethane, PTFE, Silicon Application: Automotive, Aerospace, Oil & Gas, Electronics End User: Manufacturers, Contractors, Distributors, Maintenance Providers |
| Companies Covered | James Walker, John Crane, Parker Hannifin Corp, EagleBurgmann, Saint-Gobain Performance Plastics, Trelleborg Sealing Solutions, Freudenberg Sealing Technologies, IDG-Dichtungstechnik GmbH, SKF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Performance Seals Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning in high-performance sealing. Three developments are commanding strategic attention from compounders and OEM sourcing teams.
Perfluoroelastomer (FFKM) grades with enhanced plasma resistance are supplanting standard fluorocarbon seals in semiconductor etch chamber applications. Wafer fabrication equipment OEMs in South Korea and Taiwan are specifying these grades for 3nm process nodes. The technology is compressing replacement cycles while elevating material specification thresholds for incumbent suppliers.
EPA enforcement of TSCA Section 6(h) for long-chain PFAS is accelerating fluoropolymer phase-outs in US industrial applications. Seal manufacturers are reformulating with short-chain fluorotelomer alternatives and hybrid thermoplastic elastomers. Automotive powertrain applications are most affected, with Detroit-area OEMs demanding certified PFAS-free platforms by 2027.
Digital twin-enabled predictive maintenance is altering aftermarket seal procurement patterns. Oil field operators in the Permian Basin are unbundling seal replacement from full-service contracts, buying direct from compounders with IoT-validated wear algorithms. This channel disintermediation is compressing distributor margins while rewarding suppliers with sensor-integrated product offerings.
High-Performance Seals Market Segmentation
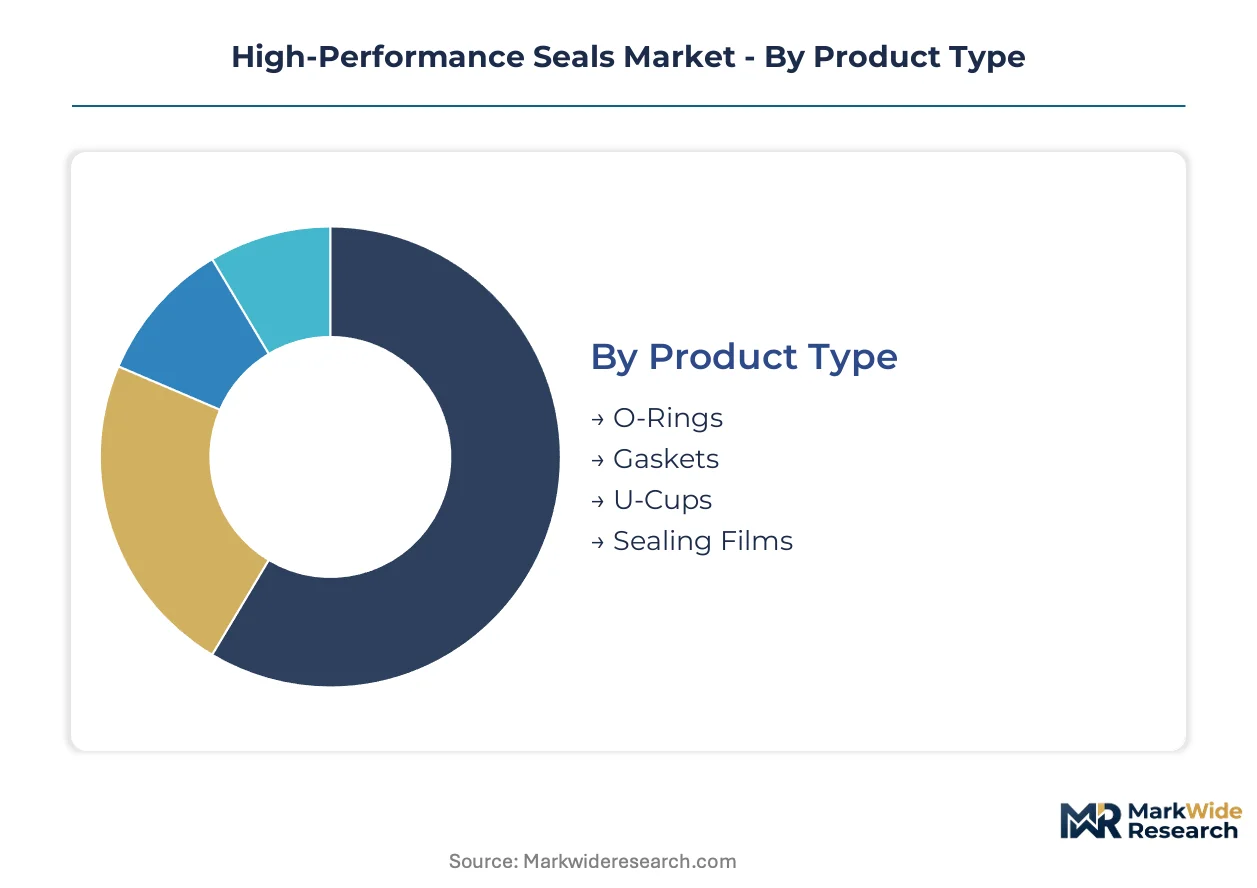
High-performance seals serve radically different duty cycles across propulsion systems, semiconductor fabs, and sour gas wells. Segmentation reveals how material specifications, certification burdens, and channel economics fragment what appears to be a unified components market.
Product Type:
Channel economics diverge sharply: O-rings and gaskets flow through high-volume distribution networks serving maintenance providers, while U-cups and sealing films command direct OEM relationships with extended qualification timelines.
- O-Rings:Circular elastomeric loops precision-molded in standard and custom cross-sections. Stuttgart-area automotive tier-1s are consolidating procurement for thermal management systems around validated FKM grades. By volume, O-rings lead. By growth pace, sealing films are climbing the fastest.
- Gaskets:Flat-sealing elements engineered for flange interfaces under bolted compression. Oil field contractors in the Permian Basin specify spiral-wound and metal-reinforced variants for wellhead assemblies. EPA emissions compliance is compressing acceptable filler material options.
- U-Cups:Lip-profile seals for unidirectional hydraulic pressure retention. Mobile hydraulic OEMs in Germany's industrial corridor source these for construction equipment cylinders.
- Sealing Films:Ultra-thin thermoplastic barriers for semiconductor vacuum chambers and fuel cell stack interfaces. Wafer fabrication equipment demand in South Korea is validating plasma-resistant FFKM formulations.
By margin contribution, sealing films outearn O-rings per unit. By procurement frequency, O-rings dominate replacement cycles.
Material:
Cost tiers stratify procurement: PTFE and perfluoroelastomers command aerospace and semiconductor premiums, while rubber and polyurethane serve automotive volume applications with compressed qualification overhead.
- Rubber:Nitrile, EPDM, and hydrogenated nitrile formulations for general industrial and automotive duty. Detroit-area powertrain OEMs are accelerating PFAS-free rubber qualification under EPA TSCA Section 6 pressure.
- Polyurethane:Cast and injection-molded elastomers combining abrasion resistance with hydraulic compatibility. Mining equipment rebuilders in Australia specify these for rod seal applications.
- PTFE:Virgin and filled polytetrafluoroethylene grades for chemical inertness and cryogenic service. Semiconductor etch chamber OEMs in Taiwan are specifying plasma-resistant modified PTFE for 3nm process nodes.
- Silicon:Fluorosilicone and VMQ grades for extreme temperature cycling. Aerospace propulsion engineers specify fluorosilicone for turbine zones exceeding 200°C sustained operation.
By specification intensity, PTFE and silicon outrank rubber. By tonnage, rubber and polyurethane together dominate compounding throughput.
Application:
Customer maturity separates segments: oil & gas and aerospace buyers demand documented aging test data and multi-standard certification, while automotive and electronics procurement emphasizes scale economics and supply assurance.
- Automotive:Powertrain, thermal management, and fuel system sealing. German OEMs are consolidating fluorocarbon seal sourcing around backward-integrated compounders with captive resin supply.
- Aerospace:Engine core, airframe, and landing gear applications. FAA Parts Manufacturer Approval cycles extend 18-36 months, locking qualified suppliers into long-term OEM agreements.
- Oil & Gas:Wellhead, downhole, and subsea pressure containment. NORSOK M-710 and ISO 23936-2 sour gas compatibility requirements filter supplier eligibility to documented performers.
- Electronics:Semiconductor fabrication and hydrogen fuel cell sealing. South Korean wafer equipment OEMs are specifying FFKM grades with enhanced plasma resistance for advanced node production.
By certification burden, aerospace and oil & gas exceed automotive and electronics. By unit volume, automotive outproduces all other segments combined.
End User:
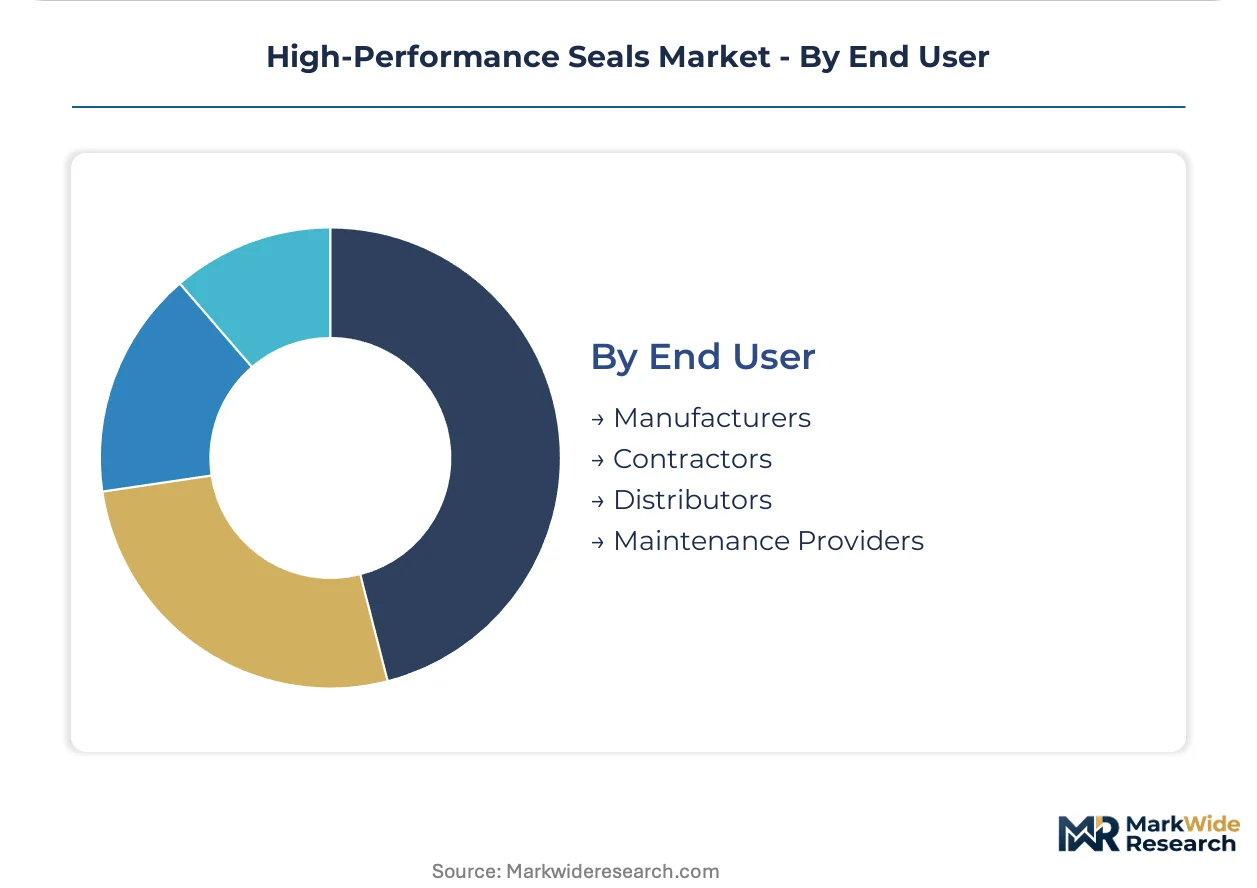
Channel power concentrates with manufacturers holding direct OEM qualifications, while distributors and maintenance providers compete on inventory velocity and technical service.
- Manufacturers:Tier-1 and tier-2 component suppliers with in-house sealing design capability. Stuttgart-based automotive suppliers are qualifying PFAS-free formulations for 2027 model year compliance.
- Contractors:Oil field service and industrial construction firms procuring project-specific seal kits. Permian Basin operators are unbundling seal procurement from full-service contracts.
- Distributors:Industrial supply houses carrying standardized O-ring and gasket inventory. German distributors around Mannheim are consolidating logistics for hydrogen infrastructure project demand.
- Maintenance Providers:Equipment rebuild and aftermarket service operations. Digital twin-enabled predictive maintenance is shifting procurement from scheduled replacement to condition-based ordering.
By technical specification control, manufacturers lead. By transaction frequency, maintenance providers and distributors outpace direct OEM procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oil & gas operators, aerospace OEMs, and automotive tier-1s concentrate procurement across five national manufacturing corridors. Each geography shapes demand through distinct regulatory chemistry restrictions and industrial cluster specialization.
United States
Permian Basin operators are unbundling seal procurement from full-service contracts, buying direct from compounders with validated wear algorithms. EPA enforcement of TSCA Section 6(h) for long-chain PFAS is accelerating fluoropolymer phase-outs in Detroit-area automotive powertrain applications. Houston anchors oil field service demand for NORSOK M-710 certified sour gas seals.
Germany
Stuttgart-based automotive tier-1s are consolidating fluorocarbon seal sourcing for thermal management systems around backward-integrated compounders. REACH substance restrictions are compelling Mannheim-area manufacturers to develop next-generation elastomer formulations. The industrial corridor between Stuttgart and Mannheim is concentrating demand for high-pressure hydrogen sealing solutions.
China
Wafer fabrication equipment demand is validating plasma-resistant FFKM formulations for advanced node semiconductor production. MIIT standards for hydrogen fuel cell stack interfaces are shaping domestic certification requirements. Yangtze River Delta manufacturing clusters are scaling PTFE compounding for chemical processing equipment exports.
South Korea
Semiconductor etch chamber OEMs are specifying perfluoroelastomer grades with enhanced plasma resistance for 3nm process nodes. MFDS chemical substance notifications are filtering imported seal material eligibility. Gyeonggi-do fabrication equipment corridors are compressing seal replacement cycles while elevating material specification thresholds.
Japan
Automotive powertrain OEMs are qualifying PFAS-free rubber formulations under METI chemical management guidelines. METI's dual carbon goals are prioritizing low-carbon seal supply chains in government infrastructure tenders. Nagoya-area aerospace suppliers are extending fluorosilicone specifications for turbine zones exceeding 200°C sustained operation.
High-Performance Seals Market Key Industry Players
Player mix skews toward European and North American specialists with captive compounding capabilities and multi-decade OEM qualification relationships. Market structure concentrates among compounders with backward integration into custom resin formulation and documented aging test libraries. Two archetypes dominate: integrated material-platform suppliers serving aerospace and oil & gas certification regimes, and regional fabricators competing on logistics proximity for automotive volume. Competitive moves center on PFAS-free formulation pipelines and additive manufacturing qualification for complex seal geometries.
Within the integrated material-platform tier, Trelleborg Sealing Solutions and Freudenberg Sealing Technologies exemplify compounders with European captive compounding capabilities and automotive powertrain anchoring respectively. James Walker occupies a position representing UK-certified specialists serving nuclear and marine radiation-degradation resistance requirements. These three names illustrate how geographic origin and certification heritage shape competitive positioning rather than scale alone.
| Leading Market Players |
|---|
| James Walker |
| John Crane |
| Parker Hannifin Corp |
| EagleBurgmann |
| Saint-Gobain Performance Plastics |
| Trelleborg Sealing Solutions |
| Freudenberg Sealing Technologies |
| IDG-Dichtungstechnik GmbH |
| SKF |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with tetrafluoroethylene monomer indexation lock in supply access and price visibility for compounders serving aerospace and semiconductor OEMs. These agreements insulate qualified suppliers from spot volatility while embedding performance-grade premiums into multi-year procurement frameworks.
Pricing Analysis
Cost-plus contracts with tetrafluoroethylene monomer indexation dominate procurement between resin producers and seal compounders. Three-tier pricing structure across aerospace-certified, automotive-grade, and industrial-commodity levels separates qualification-intensive applications from volume-driven replacement cycles. Cost compression in automotive-grade fluorocarbon formulations is intensifying because Detroit-area OEMs are demanding PFAS-free platforms without performance degradation. Maintenance providers and distributors exhibit highest price sensitivity due to unbundled procurement and inventory velocity pressures.
Supply Chain Analysis
Strategic stockpiling of virgin PTFE and FKM resins prevails among qualified compounders managing 18-36 month aerospace qualification cycles. Raw material supply concentrates in the United States, Germany, and Japan where three chemical producers control tetrafluoroethylene monomer output. Feedstock dependency rests on fluoropolymer resin availability, specialty curative chemicals, and high-purity metal fillers for reinforced grades. Single-source vulnerability in monomer supply elevates disruption risk for non-integrated compounders. Distribution runs through direct OEM channels for certified grades and high-volume distributors for standard O-ring and gasket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-performance seals represent an early-cycle expansion story as hydrogen infrastructure buildout and semiconductor node advancement create specification-intensive demand that outpaces commodity seal replacement economics.
For Market Incumbents: Shield compound formulation expertise through accelerated knowledge transfer programs as retiring fluorocarbon chemists concentrate institutional capability. Secure backward integration into captive resin compounding to offset feedstock price volatility and lock out unqualified competitors from OEM sourcing pools. Prioritize FAA Parts Manufacturer Approval maintenance and REACH pre-registration for next-generation PFAS-free platforms. For New Entrants and Emerging Players: Predictive maintenance algorithm development represents a service-layer gap where incumbents under-serve Permian Basin oil field operators unbundling procurement from full-service contracts. Target hydrogen infrastructure sealing in Germany's Stuttgart-Mannheim corridor where certification backlogs create entry windows for qualified newcomers. Pursue additive manufacturing qualification for complex labyrinth seal geometries in semiconductor vacuum applications as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward compounders with documented aging test libraries and multi-standard certification heritage spanning aerospace and oil & gas regimes. Long-term viability across the analysis window hinges on PFAS-free formulation pipelines and captive resin supply security. Watch EPA TSCA Section 6 enforcement velocity as the inflection signal that accelerates incumbent reformulation investment and elevates acquisition premiums for qualified alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Pipeline | EPA TSCA Section 6 compliance locks qualified suppliers into long-term OEM sourcing agreements. |
| Backward Integration into Resin Compounding | Captive tetrafluoroethylene supply insulates margin structures from monomer price volatility. |
| Additive Manufacturing Qualification | 3D-printed thermoplastic elastomer geometries enable complex profiles for semiconductor vacuum chambers. |
| FAA Parts Manufacturer Approval Investment | 18-36 month qualification cycles create structural barriers against unqualified competitors. |
| Digital Twin-Enabled Predictive Maintenance | IoT-validated wear algorithms capture oil field procurement unbundling from distributor channels. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with procurement directors at aerospace OEMs, compound formulation chemists, oil field maintenance supervisors, and semiconductor equipment sourcing managers. Secondary validation drew from FAA Parts Manufacturer Approval databases, EPA TSCA Section 6 enforcement records, REACH substance restriction notifications, and NORSOK M-710 certification registries. Bottom-up segment sizing triangulated against top-down industry association data from chemical and aerospace trade bodies.
Across the analysis window, forecasts modeled volume and value trajectories through product type, material grade, application intensity, and regional regulatory cluster segmentation. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Industry-specific inputs included semiconductor node advancement timelines, hydrogen infrastructure deployment cadence, and fluoropolymer phase-out regulatory velocity.
Forecasts assume regulatory continuity in EPA TSCA and REACH substance restriction regimes; material policy shifts would require re-modeling compound qualification timelines and OEM sourcing concentration. Revision becomes warranted when PFAS-free formulation performance gaps or feedstock supply disruptions cross thresholds that alter competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Torque Limiting Couplings Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Global Forklift Market