
 Global Intragastric Balloon Market | 2026-2036
Global Intragastric Balloon Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intragastric Balloon Market Foresight
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for intragastric balloon manufacturers seeking European market access. Apollo Endosurgery sustains technology leadership through proprietary endoscopic delivery systems. Allurion Technologies differentiates via a swallowable balloon platform that eliminates procedural anesthesia requirements. Spatz3 anchors adjustable volume technology, allowing physicians to modify fill levels during the treatment period.
An intragastric balloon is a temporary, space-occupying medical device inserted into the stomach to induce early satiety and restrict caloric intake, typically constructed from silicone elastomer and filled with saline or gas to volumes between 400-700 mL. The device serves as a non-surgical alternative to bariatric surgery for patients with BMI thresholds of 30-40 kg/m² who have failed conservative weight management. Saline-filled balloons command the largest installed base due to established reimbursement codes and physician familiarity, while gas-filled balloons represent the fastest-expanding category driven by reduced intolerance profiles and nausea incidence. Adjustable balloons concentrate margin pools through premium pricing tied to customization capabilities and extended dwell times up to twelve months.
FDA 510(k) clearance pathways and EMA MDR compliance requirements shape product development timelines and clinical evidence burdens for manufacturers targeting major markets. Brazil's ANVISA and South Korea's MFDS impose additional local testing protocols that filter market entrants without dedicated regulatory infrastructure. Stakeholders must monitor evolving CMS national coverage determinations and comparable payer decisions across Germany's G-BA and South Korea's HIRA, as reimbursement expansion or contraction will directly alter addressable patient populations and commercial model viability.
Market Dynamics
Medicare reimbursement criteria tightening for metabolic procedures is redirecting patient flows toward non-surgical alternatives, compressing procedural volumes in traditional bariatric surgery while expanding the addressable pool for endoscopic obesity interventions.
Growth Catalysts
- Silicone polymer advances:New elastomer formulations reduce deflation rates and improve biocompatibility profiles, extending dwell times and improving patient tolerance metrics.
- Endoscopic placement protocols:Standardized ambulatory procedures eliminate operating room requirements, cutting facility costs and expanding site-of-service options to outpatient clinics.
- Germany's G-BA coverage expansion:National health system reimbursement for non-surgical obesity interventions removes out-of-pocket barriers and accelerates physician adoption curves.
Market Restraints
- Saline input cost volatility:Medical-grade sterile saline supply concentrates among three dominant manufacturers, exposing margins to periodic shortage pricing.
- CE marking MDR compliance burden:EU Medical Device Regulation clinical evidence requirements extend approval timelines and raise capital barriers for new entrants.
- Gastric sleeve substitution threat:Laparoscopic sleeve gastrectomy maintains superior long-term weight loss outcomes, limiting balloon candidacy to BMI 30-40 kg/m² corridors.
Strategic Opportunities
- Brazil's ANVISA pathway maturation:Streamlined local testing protocols for established CE-marked devices create first-mover advantages in Latin America's largest obesity market.
- Swallowable platform convergence:Elimination of procedural anesthesia requirements opens office-based administration channels and reduces per-procedure overhead structures.
- South Korea's HIRA reimbursement tailwind:National insurer coverage expansion for metabolic disease management prioritizes cost-effective interventions over surgical alternatives.
Industry Challenges
- Interventional gastroenterology talent scarcity:Endoscopic bariatric procedure training programs remain underdeveloped relative to deployment targets, constraining site activation velocity.
- Dual regulatory certification timelines:Concurrent FDA 510(k) and EMA MDR submissions demand parallel clinical evidence generation, stretching R&D budgets and compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intragastric Balloon Market |
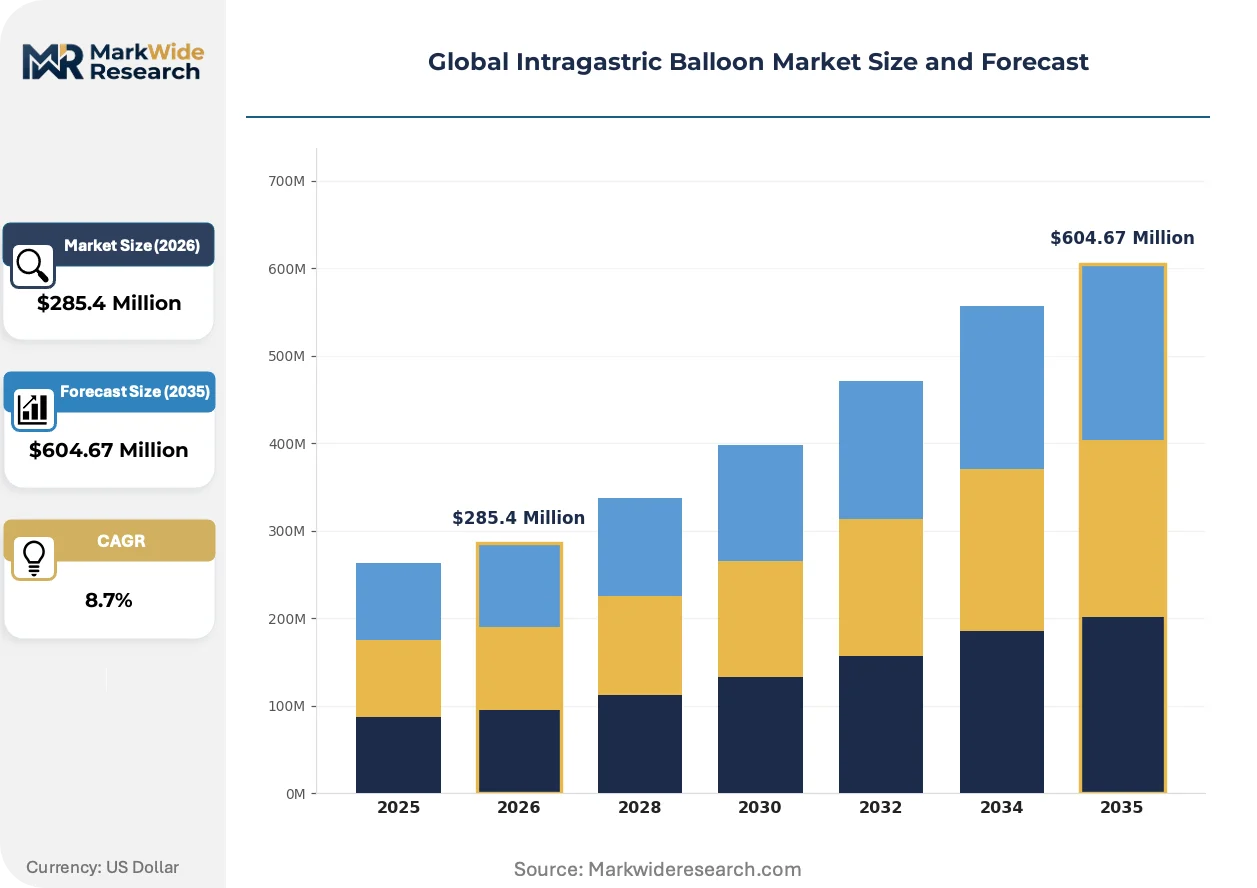
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Balloons, Fixed Volume Balloons, Gas-Filled Balloons, Saline-Filled Balloons Application: Weight Management, Obesity Treatment, Preoperative Weight Loss, Metabolic Disorder Control End User: Bariatric Clinics, Surgical Centers, Medical Weight Loss Facilities, Outpatient Care Providers Deployment: Endoscopic Placement, Fluoroscopy Guided, Non-Invasive Techniques, Ambulatory Surgery |
| Companies Covered | Boston Scientific, Apollo Endosurgery, Allurion Technologies, ReShape Lifesciences, Spatz3, Obalon Therapeutics, Helioscopie, Endalis, Silimed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intragastric Balloon Market Shifts & Advancements
Adjustable volume technology is redrawing competitive boundaries by enabling physician-controlled customization during the treatment period, collapsing the traditional fixed-balloon paradigm and creating new margin structures around extended dwell protocols.
Silicone elastomer composite materials are fragmenting the legacy single-layer construction standard. Bariatric clinics in the United States are adopting multi-layer barrier systems at accelerating rates. This material evolution is fragmenting procurement patterns as facilities reassess supplier relationships based on rupture-resistance specifications rather than legacy brand loyalty.
EU MDR clinical evidence requirements are compressing product development timelines for manufacturers targeting European market access. The regulation mandates extended follow-up data and post-market surveillance systems that favor established players with dedicated regulatory infrastructure. Adjustable balloon platforms face the steepest compliance burden due to their mechanical complexity and longer intended dwell periods.
Patient self-pay financing models are displacing traditional insurance-dependent channels in markets with incomplete reimbursement coverage. Direct-to-consumer payment plans and medical tourism aggregators are capturing growing share of Brazilian and South Korean demand. This behavioral shift concentrates margin capture with manufacturers owning integrated patient access platforms rather than pure device suppliers.
Global Intragastric Balloon Market Segmentation
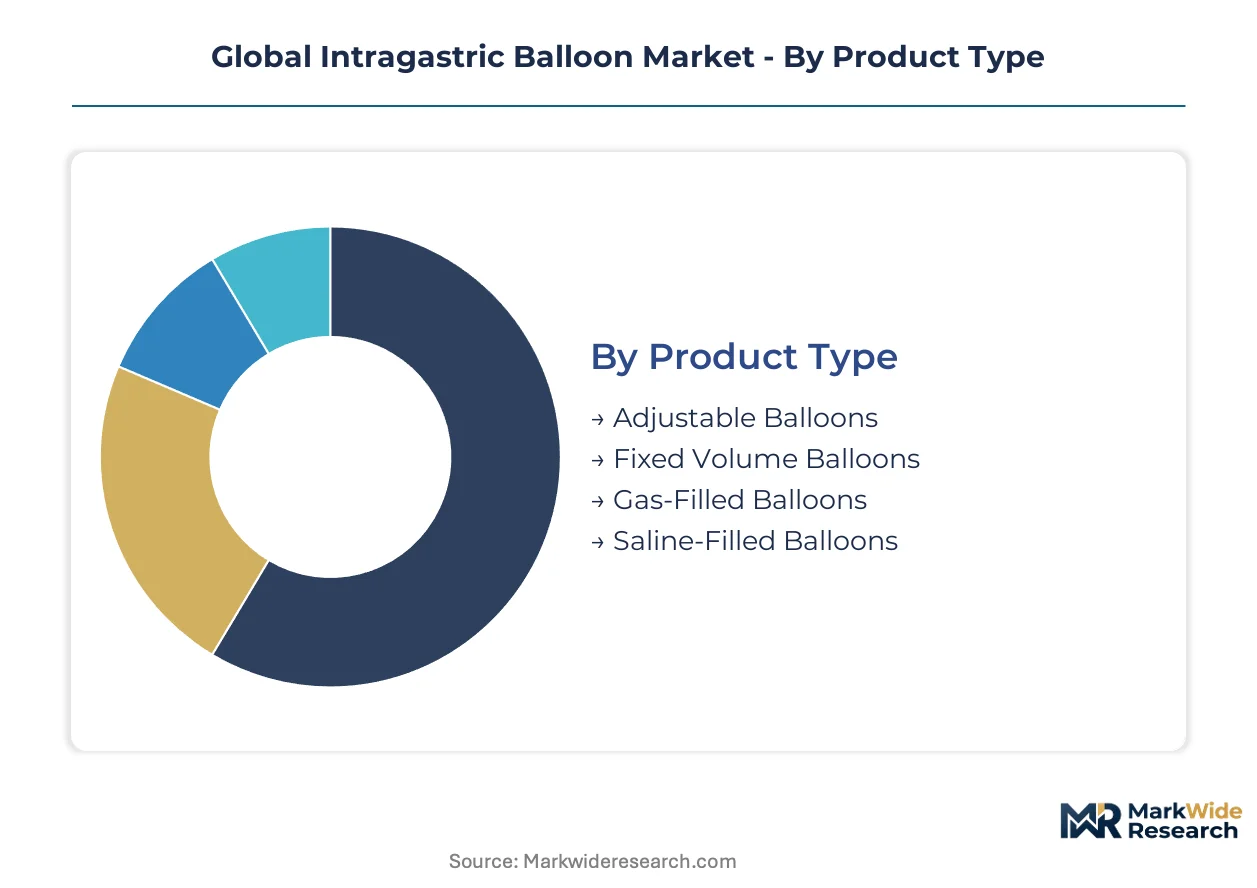
Intragastric balloon manufacturers face divergent competitive pressures across product architectures and clinical settings. Segmentation choices directly determine reimbursement eligibility, procedural economics, and vulnerability to substitute therapies like sleeve gastrectomy.
Product Type:
Fixed volume balloons face the most acute substitution pressure from adjustable alternatives, while saline-filled designs confront rising gas-filled competition on tolerance metrics.
- Saline-Filled Balloons:Silicone elastomer shells inflated with sterile saline to 400-700 mL volumes dominate installed bases through established CPT reimbursement codes and physician familiarity with fluid-based fill protocols. Bariatric clinics in the United States concentrate procurement around saline designs due to predictable deflation detection and straightforward endoscopic removal workflows.
- Gas-Filled Balloons:Nitrogen or air-filled alternatives constructed from multi-layer polymer barriers reduce nausea incidence and early intolerance episodes that drive premature explantation. Demand concentrates in Germany and South Korea where patient comfort scores influence national health system purchasing criteria.
- Adjustable Balloons:Volume-modifiable designs enabling physician-controlled fill adjustments during the treatment period command premium pricing through extended twelve-month dwell protocols.
- Fixed Volume Balloons:Single-fill devices with predetermined volumes offer lower per-unit costs but limited customization for patient anatomy variations.
Saline-filled balloons retain volume leadership; gas-filled alternatives hold the steepest expansion curve.
Application:
Cost tier differentiation separates elective weight management from reimbursed metabolic interventions, with preoperative applications commanding distinct procurement channels.
- Obesity Treatment:Primary indication for BMI 30-40 kg/m² patients failing conservative management, requiring comprehensive metabolic monitoring and multidisciplinary care coordination. Bariatric clinics in Brazil anchor demand through direct-to-consumer financing models where insurance coverage remains incomplete.
- Preoperative Weight Loss:Bridge therapy for high-risk surgical candidates requiring BMI reduction before laparoscopic procedures, with strict timelines dictating device selection for rapid effect. Surgical centers in South Korea prioritize this segment under HIRA reimbursement protocols that prioritize cost-effective interventions.
- Weight Management:Lifestyle-focused applications emphasizing behavioral modification alongside mechanical restriction.
- Metabolic Disorder Control:Adjunct therapy for type 2 diabetes and dyslipidemia management through caloric restriction mechanisms.
Obesity treatment captures the dominant revenue pool; preoperative weight loss applications are climbing the fastest.
End User:
Site-of-service economics concentrate margin capture with ambulatory-capable facilities versus hospital-based surgical centers.
- Bariatric Clinics:Specialized obesity medicine practices with dedicated endoscopic suites and metabolic nursing staff generate the highest procedural volumes through streamlined patient pathways. Facilities in the United States leverage these settings to bypass hospital outpatient department fees and capture professional component revenue.
- Outpatient Care Providers:General gastroenterology practices adopting swallowable balloon platforms eliminate anesthesia requirements and expand addressable physician pools. Adoption concentrates in Germany where G-BA reimbursement expansion supports office-based administration.
- Surgical Centers:Ambulatory surgery facilities with operating room infrastructure for endoscopic placement under sedation.
- Medical Weight Loss Facilities:Non-physician supervised programs with limited procedural capabilities focused on device retrieval and monitoring.
Bariatric clinics retain volume leadership; outpatient care providers hold the steepest expansion curve.
Deployment:
Supply concentration in endoscopic instrumentation manufacturers shapes procurement bundling and site activation economics.
- Endoscopic Placement:Standard transoral delivery via flexible gastroscopy under conscious sedation represents the dominant deployment mode with established training pathways and device compatibility. Bariatric clinics across all major markets default to this technique for adjustable and fixed-volume balloons requiring visual fill confirmation.
- Non-Invasive Techniques:Swallowable capsule-based delivery systems eliminating procedural anesthesia and endoscopy suite requirements reshape patient access economics. South Korea's HIRA coverage decisions increasingly favor these modalities for cost containment.
- Fluoroscopy Guided:Radiographic-assisted placement for anatomically challenging cases or failed endoscopic attempts.
- Ambulatory Surgery:Hospital outpatient department-based procedures with full anesthesia support for complex patient populations.
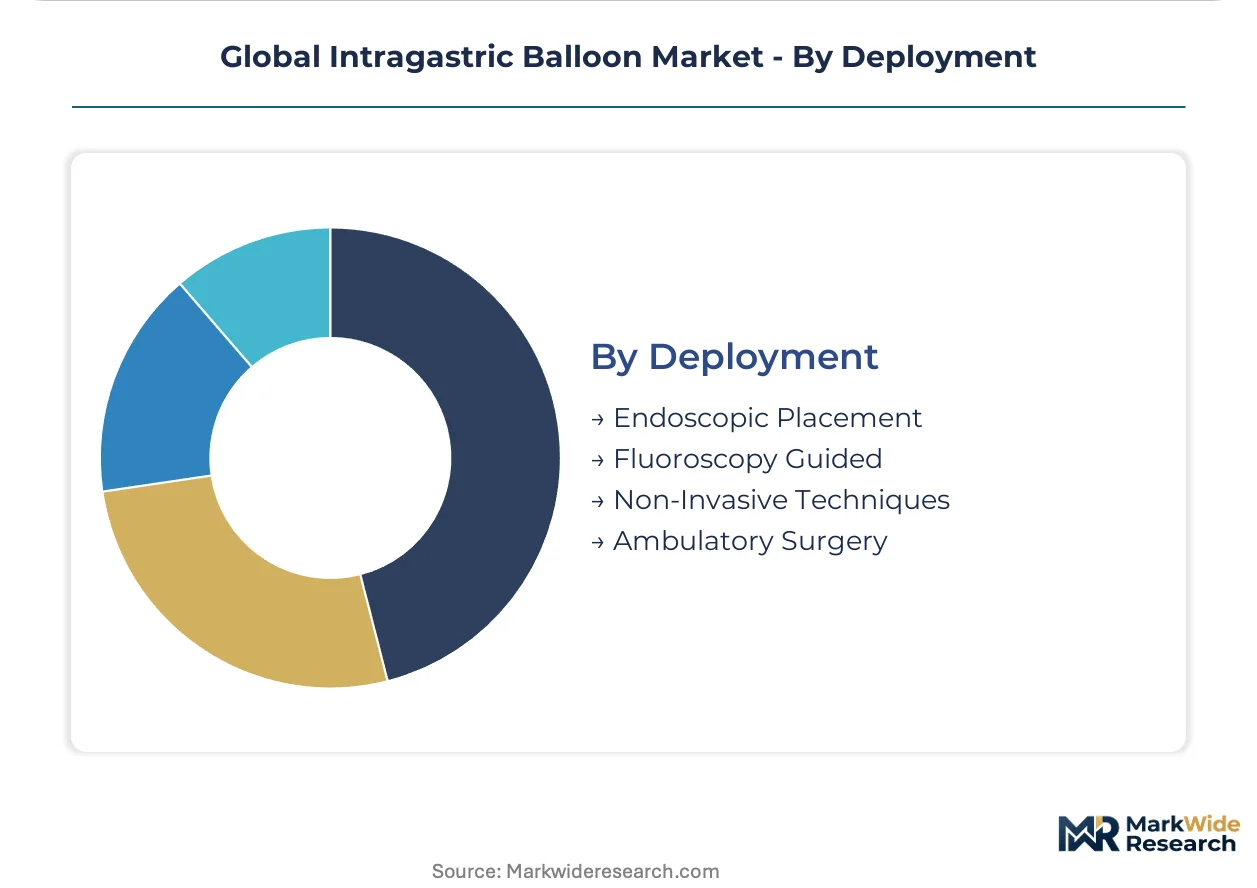
Endoscopic placement retains volume leadership; non-invasive techniques hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bariatric clinics and specialized endoscopy centers concentrate procurement authority across major markets, with reimbursement policy shifts in Germany, Brazil, South Korea, and the United States redirecting patient volumes toward non-surgical interventions.
United States
Medicare coverage determinations from CMS tighten eligibility for metabolic surgery, funneling BMI 30-40 patients toward intragastric balloons. FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting ambulatory surgery centers. Endoscopic bariatric programs in Texas and Florida expand fastest as physician-owned clinics bypass hospital outpatient department fees.
Germany
G-BA reimbursement expansion for non-surgical obesity interventions removes cost barriers for statutory health insurance patients. CE marking under EU MDR imposes extended clinical evidence requirements that filter market entrants without dedicated regulatory infrastructure. Bariatric centers in North Rhine-Westphalia and Bavaria lead adoption curves for gas-filled balloon designs prioritizing patient comfort metrics.
Brazil
ANVISA regulatory pathways for established CE-marked devices streamline market entry for international manufacturers. Direct-to-consumer financing models capture growing demand as national health system coverage remains incomplete. São Paulo anchors Latin America's largest obesity medicine cluster, with private clinics driving swallowable platform adoption.
South Korea
HIRA national insurer coverage prioritizes cost-effective metabolic interventions over surgical alternatives, expanding addressable patient pools. MFDS local testing protocols require dedicated regulatory infrastructure that advantages established multinationals. Seoul Capital Area medical centers concentrate the highest procedural volumes for adjustable balloon platforms.
Global Intragastric Balloon Market Competitive Landscape
Player mix skews toward specialized endoscopic device manufacturers with dedicated bariatric portfolios and integrated delivery systems. Market structure concentrates around three to five dominant platforms with proprietary placement technologies, while mid-tier entrants compete on price in markets with incomplete reimbursement. Strategic archetypes include swallowable platform specialists, adjustable volume technology leaders, and multi-layer material innovators. Competitive moves center on regulatory certification stacking across FDA, CE marking, and ANVISA pathways, plus ambulatory site-of-service partnerships that bypass hospital economics.
Among US-based device manufacturers, Boston Scientific and Apollo Endosurgery occupy positions as scale-driven incumbents with established endoscopic delivery infrastructures. Allurion Technologies represents the swallowable platform archetype, eliminating anesthesia requirements to open office-based administration channels. These three exemplify how regulatory certification breadth and site-of-service flexibility determine competitive positioning in markets where reimbursement expansion is fragmenting by geography.
| Leading Market Players |
|---|
| Boston Scientific |
| Apollo Endosurgery |
| Allurion Technologies |
| ReShape Lifesciences |
| Spatz3 |
| Obalon Therapeutics |
| Helioscopie |
| Endalis |
| Silimed |
| Others |
Supply & Pricing Matrix
Multi-layer silicone elastomer composites displacing single-layer construction simultaneously concentrate procurement authority with North Rhine-Westphalia material suppliers and compress per-unit margins for legacy manufacturers locked into older formulations. This substitution dynamic redraws supplier geography toward German polymer specialists while pricing power accumulates with bariatric clinics capable of certifying rupture-resistance specifications.
Pricing Analysis
Cost-plus contracts with medical-grade saline indexation dominate procurement between bariatric clinics and balloon manufacturers, with fill-volume tiers separating premium adjustable platforms from standard fixed-volume alternatives. Price differentiation rests on CE marking grade and extended dwell-time certification, with HIRA reimbursement protocols in South Korea intensifying cost compression in the gas-filled balloon category. Bariatric clinics exhibit highest price sensitivity due to Medicare reimbursement tightening, while outpatient care providers absorb premium pricing for swallowable platforms eliminating anesthesia overhead.
Supply Chain Analysis
Port congestion along the Rotterdam-Singapore trade lane elevates inbound logistics costs for silicone elastomer raw materials sourced from German and Chinese chemical manufacturers. Supply concentrates in Germany, China, and the United States for medical-grade polymer feedstock, with sterile saline solution drawing from domestic pharmaceutical suppliers in each major market. Single-source vulnerability permeates the multi-layer barrier membrane segment, where proprietary formulations create captive supplier relationships. Distribution runs through hospital purchasing committees and GPO contracts in the United States, direct-to-consumer channels in Brazil, and national health system tenders in Germany and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laparoscopic sleeve gastrectomy maintains superior long-term metabolic outcomes, forcing intragastric balloon incumbents to defend procedural volumes through non-surgical positioning and anesthesia elimination.
For Market Incumbents: Shield market position by deepening backward integration into silicone elastomer compounding to secure multi-layer barrier supply, while accelerating FDA 510(k) stacking for swallowable platforms that neutralize the gastric sleeve substitution threat through office-based administration channels. For New Entrants and Emerging Players: Anchor in Brazil's ANVISA streamlined pathway for CE-marked devices, where direct-to-consumer financing models capture demand outside national health system coverage, and target outpatient gastroenterology practices in Germany leveraging G-BA reimbursement expansion for non-surgical obesity interventions. For Investors and Strategic Acquirers: The market sits at a reimbursement-fragmentation phase that favors platform-integrated device manufacturers with dedicated regulatory infrastructure across FDA, CE marking, and ANVISA pathways. Long-term viability hinges on swallowable technology convergence and adjustable volume capabilities, with acquisition targets clustering around multi-layer material innovators lacking geographic certification breadth. The signal to watch is CMS national coverage determination shifts that would compress or expand Medicare-eligible patient pools.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance under EMA frameworks unlocks German G-BA reimbursement and filters price-competitive entrants. |
| Hospital System Partnership | Texas and Florida bariatric clinic networks bypass hospital outpatient department fees and capture professional component revenue. |
| Reimbursement Strategy | HIRA coverage expansion in South Korea prioritizes cost-effective metabolic interventions over surgical alternatives. |
| Software Companion Development | Digital monitoring platforms for adjustable balloon fill protocols extend dwell times and create subscription revenue streams. |
| FDA Submission | 510(k) clearance for swallowable platforms eliminates anesthesia requirements and opens office-based administration channels. |
Research Methodology
The analysis maps saline-filled, gas-filled, adjustable, and fixed-volume balloon sub-sectors, each validated through bariatric surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined regulatory affairs leads at ANVISA and MFDS with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS national coverage determinations. Bottom-up unit economics triangulated against top-down reimbursement expansion models.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation by product architecture, application indication, end-user site-of-service, and deployment modality, with CAGRs derived from procedure volume trajectories and pricing tier evolution. Forecast inputs incorporated ANVISA pathway maturation timelines and G-BA coverage expansion protocols without year-specific assumptions.
Underlying assumptions cover reimbursement stability in Germany and South Korea, with deviation risk concentrated in CMS Medicare coverage determinations and saline input cost volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gastrointestinal Devices Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Eye Socket Implants Market
Medical Devices
Breast Localization System Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
US Electrosurgical Generators Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
US Stethoscope Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Knee Braces Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
AI-enabled Medical Devices Market
Medical Devices
Global Deep Brain Stimulation Devices Market