
 Global Minimally Invasive Spine Surgery Market | 2026-2036
Global Minimally Invasive Spine Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Minimally Invasive Spine Surgery Market Analysis
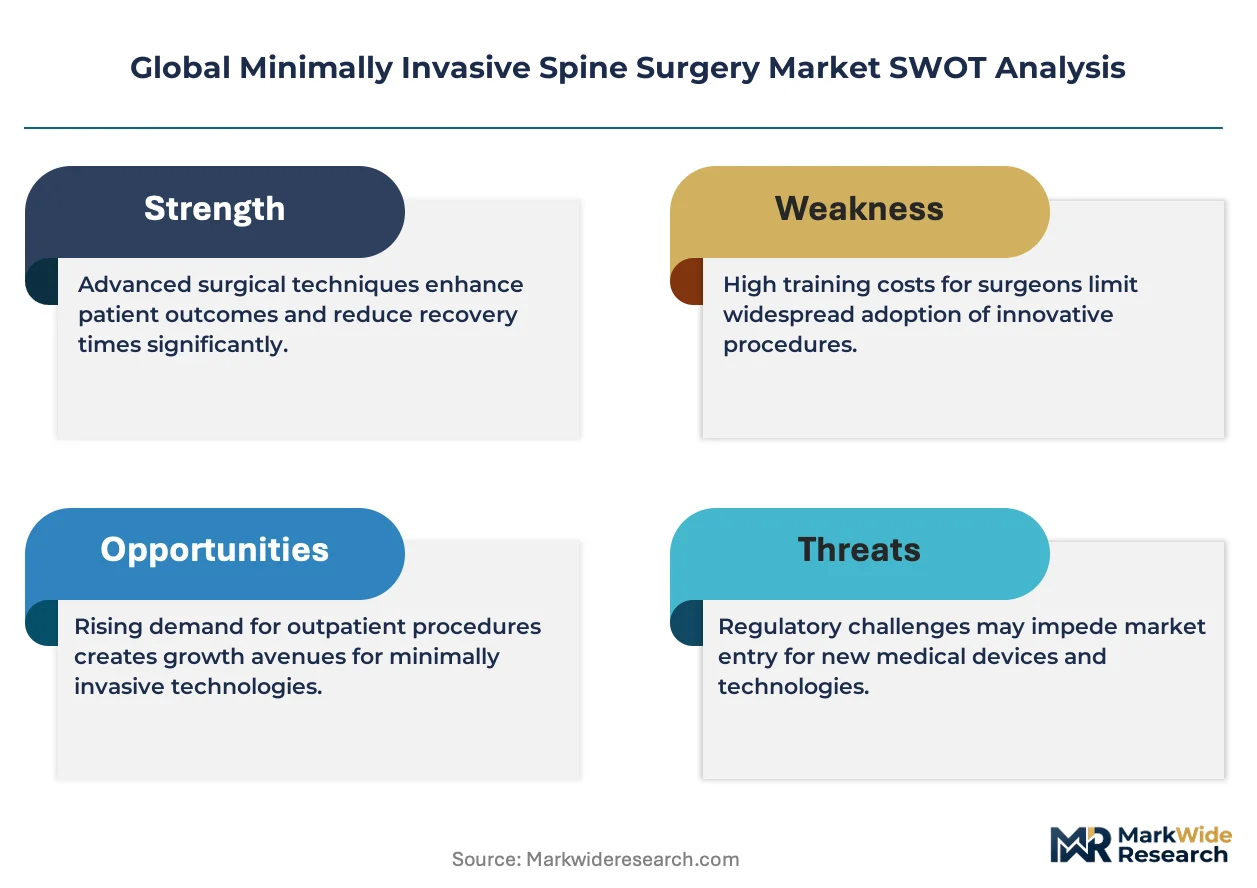
Recurring software licensing for robotic navigation platforms is consolidating around long-term service contracts that lock in disposable instrument revenue. Medtronic plc leverages its integrated surgical ecosystem to sustain high switching costs across installed base upgrades. Stryker Corporation anchors its position through proprietary navigation hardware that controls aftermarket consumable flows. NuVasive Inc. specializes in lateral access techniques that differentiate its portfolio from posterior-approach competitors.
Minimally invasive spine surgery employs percutaneous instrumentation, tubular retractors, and image-guided navigation to access spinal pathology through incisions under two centimeters while preserving paraspinal musculature. Fluoroscopy and robotic assistance technologies command premium positioning as hospitals prioritize precision and reduced radiation exposure for operating staff. Ambulatory surgery centers represent the fastest-growing end user channel as payors push procedure migration away from inpatient settings. Bone screws and interspinous spacers retain mature margin pools, though surgical instruments face pricing pressure from commoditized Asian manufacturing.
FDA 510(k) predicate requirements, EU MDR clinical evaluation obligations, and Japan PMDA foreign manufacturer registration collectively shape product development timelines and market access costs for spinal implant vendors. The EU AI Act introduces additional scrutiny for robotic assistance algorithms that automate intraoperative decision support. Stakeholders must monitor reimbursement parity between inpatient and outpatient spinal codes as this determines capital deployment speed across ambulatory surgery center networks.
Market Dynamics
Recurring software licensing for robotic navigation platforms is consolidating around long-term service contracts that lock in disposable instrument revenue, fundamentally altering how capital equipment vendors capture lifetime value from hospital customers.
Growth Catalysts
- FDA 510(k) Pathway:Streamlined predicate-based clearance accelerates product entry for spinal implant vendors targeting the US market, compressing time-to-revenue cycles.
- German Orthopedic Clustering:Specialized clinics concentrated around university hospitals in Berlin and Munich generate dense referral networks that normalize minimally invasive techniques.
- Ambulatory Surgery Centers:Payor pressure for outpatient migration creates structural demand pull for procedures compatible with same-day discharge protocols.
Market Restraints
- EU MDR Clinical Evaluation:Expanded obligations for spinal implant documentation extend approval timelines and inflate regulatory compliance costs.
- Asian Manufacturing Concentration:Surgical instrument commoditization from concentrated low-cost production erodes margin pools for established suppliers.
- Radiation Exposure Limits:Operating staff safety thresholds constrain fluoroscopy utilization rates in high-volume spine centers.
Strategic Opportunities
- Japan PMDA Registration:Foreign manufacturer pathways for robotic navigation systems remain underpenetrated relative to procedural volume potential.
- AI-Assisted Decision Support:Convergence of intraoperative imaging with machine learning algorithms creates premium positioning for algorithm-enabled platforms.
- Direct-to-ASC Distribution:Bypassing traditional hospital procurement committees unlocks faster capital deployment across independent surgery center networks.
Industry Challenges
- Paraspinal Muscle Preservation Training:Surgical technique proficiency gaps limit adoption velocity among fellowship-trained spine surgeons.
- Interoperability Standards:Proprietary navigation hardware from competing vendors blocks seamless data exchange between installed base systems.
- Disposable Instrument Supply:Locked-in consumable flows face renegotiation pressure as ASC administrators scrutinize per-procedure supply costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Minimally Invasive Spine Surgery Market |
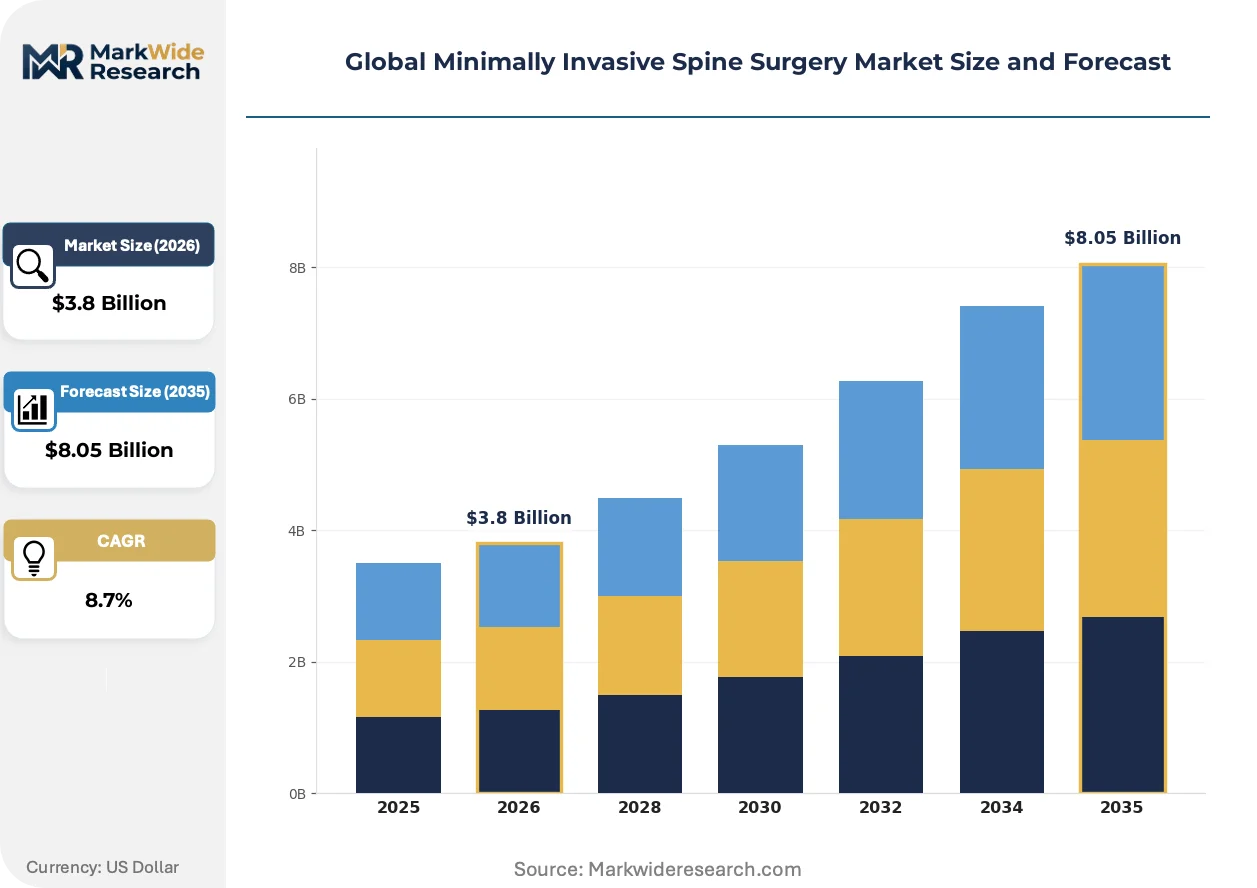
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interspinous Spacers, Bone Screws, Facet Screw Systems, Surgical Instruments Application: Herniated Discs, Spinal Stenosis, Spinal Tumors, Scoliosis End User: Hospitals, Ambulatory Surgery Centers, Rehabilitation Clinics, Orthopedic Clinics Technology: Fluoroscopy, Endoscopy, Robotic Assistance, Navigation Systems |
| Companies Covered | Zimmer Biomet Holdings Inc., DePuy Synthes, Medtronic plc, Orthofix Medical Inc., Alphatec Holdings Inc., Stryker Corporation, Globus Medical Inc., Aesculap Implant Systems LLC, NuVasive Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Minimally Invasive Spine Surgery Market Emerging Trajectories
Fluoroscopy and robotic assistance technologies command premium positioning as hospitals prioritize precision and reduced radiation exposure for operating staff, reshaping competitive differentiation around intraoperative imaging capabilities.
Robotic navigation platforms is rewriting how spinal instrumentation is planned and executed, with university-affiliated hospitals in Germany and the US adopting these systems at accelerated cadences. The technology is compressing variance in screw placement accuracy while extending procedure times, creating tension between clinical outcomes and operating room throughput economics.
EU AI Act scrutiny of robotic assistance algorithms is mandating additional documentation burdens for vendors deploying automated intraoperative decision support. Spinal implant manufacturers with European market exposure are responding by segregating algorithm-enabled features into standalone regulatory submissions, fragmenting product launch timelines across geographies.
Hospital procurement committees are unbundling after-sales service from capital equipment contracts, forcing navigation platform vendors to compete on discrete maintenance pricing. This pattern is most visible in North American health systems where centralized supply chain functions have gained negotiating leverage over vendor-installed bases.
Global Minimally Invasive Spine Surgery Market Segmentation
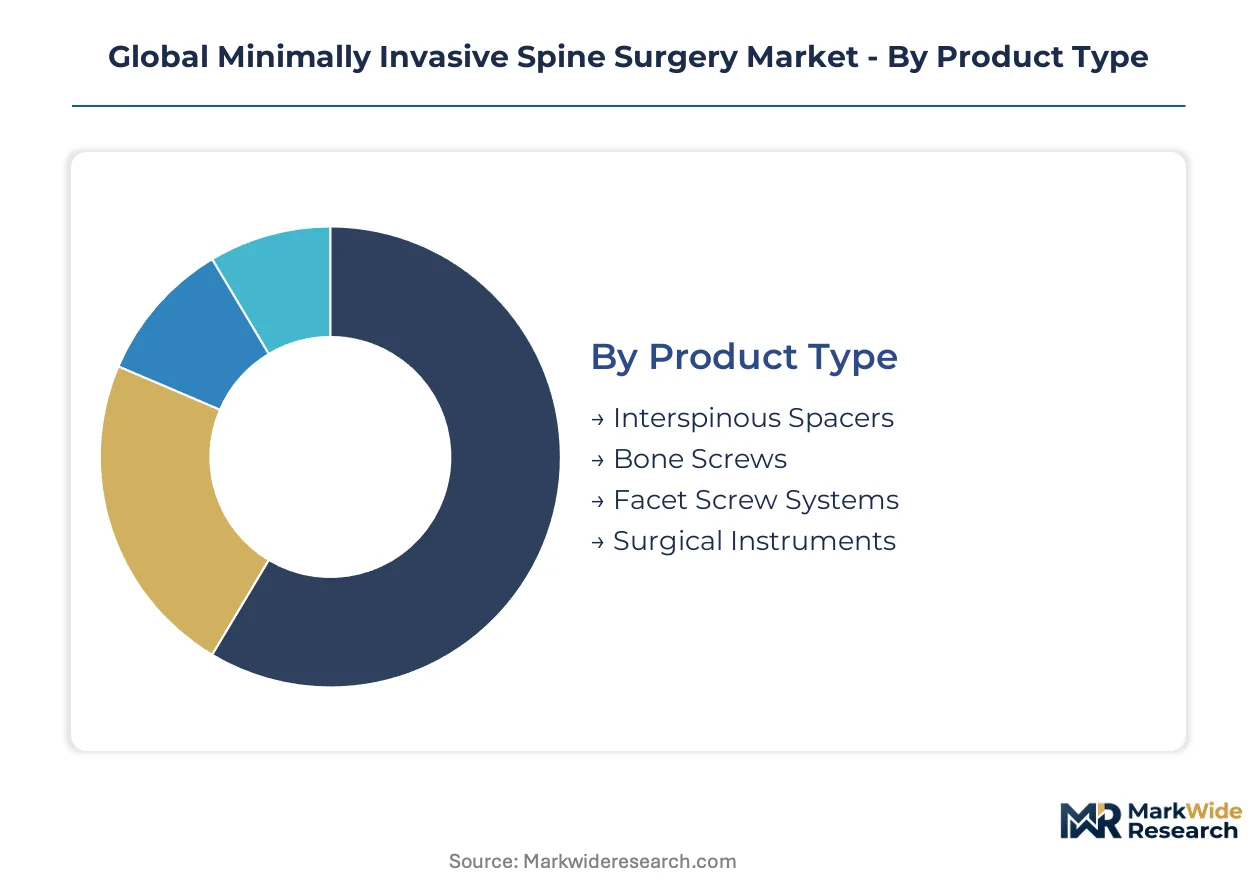
Spinal implant vendors configure product portfolios around procedure-specific instrumentation bundles. Segmentation reveals where hardware commoditization pressures intersect with premium technology attach rates.
Product Type:
Customization intensity varies from patient-matched interbody devices to off-the-shelf instrument kits standardized across hospital systems.
- Interspinous Spacers:Polyetheretherketone and titanium alloy constructs stabilize motion segments without fusion. German university hospitals in Berlin and Munich drive specification for dynamic stabilization designs that preserve segmental mobility.
- Bone Screws:Pedicle and cortical screw systems anchor fixation constructs through minimally invasive trajectories. Ambulatory surgery centers in the United States prioritize cannulated designs compatible with percutaneous delivery to support same-day discharge protocols.
- Facet Screw Systems:Translaminar and transfacet screws provide posterior stabilization without pedicle breach risk.
- Surgical Instruments:Tubular retractors, dilators, and targeting guides face margin compression from concentrated Asian manufacturing.
Most installed capacity flows through Bone Screws. Expansion is steepest in Interspinous Spacers.
Application:
Procedure volume distributes across degenerative conditions with established reimbursement codes versus complex deformity cases requiring specialized training.
- Herniated Discs:Microdiscectomy and percutaneous nucleotomy address radiculopathy through sub-centimeter access ports. United States payor preference for outpatient migration concentrates demand in ambulatory settings.
- Spinal Stenosis:Decompression with interspinous distraction or laminectomy targets neurogenic claudication. Japanese orthopedic clinics adopt indirect decompression techniques to manage aging demographics.
- Spinal Tumors:Metastatic lesion stabilization and primary tumor resection require navigation-enabled precision for oncologic margins.
- Scoliosis:Adolescent idiopathic and adult degenerative deformity correction demands longer constructs with higher screw density.
Procedure economics favor Herniated Discs for ASC penetration. Spinal Stenosis is climbing the fastest as populations age across developed markets.
End User:
Capital deployment cycles diverge between integrated health systems with centralized procurement and independent surgery centers with owner-operator decision velocity.
- Hospitals:Academic medical centers and community hospitals maintain high-volume spine programs with hybrid operating rooms. Germany's clustered orthopedic clinics around university hospitals normalize minimally invasive techniques through fellowship pipelines.
- Ambulatory Surgery Centers:Independent and hospital-affiliated facilities capture migration of lumbar decompression and single-level fusion. United States payor pressure accelerates capital deployment for navigation-enabled platforms.
- Rehabilitation Clinics:Post-acute facilities manage non-operative candidates and post-surgical recovery protocols.
- Orthopedic Clinics:Office-based practices with surgical suites perform limited interventions under local anesthesia.
Revenue concentration sits with Hospitals. Ambulatory Surgery Centers are gaining share fastest as reimbursement parity expands.
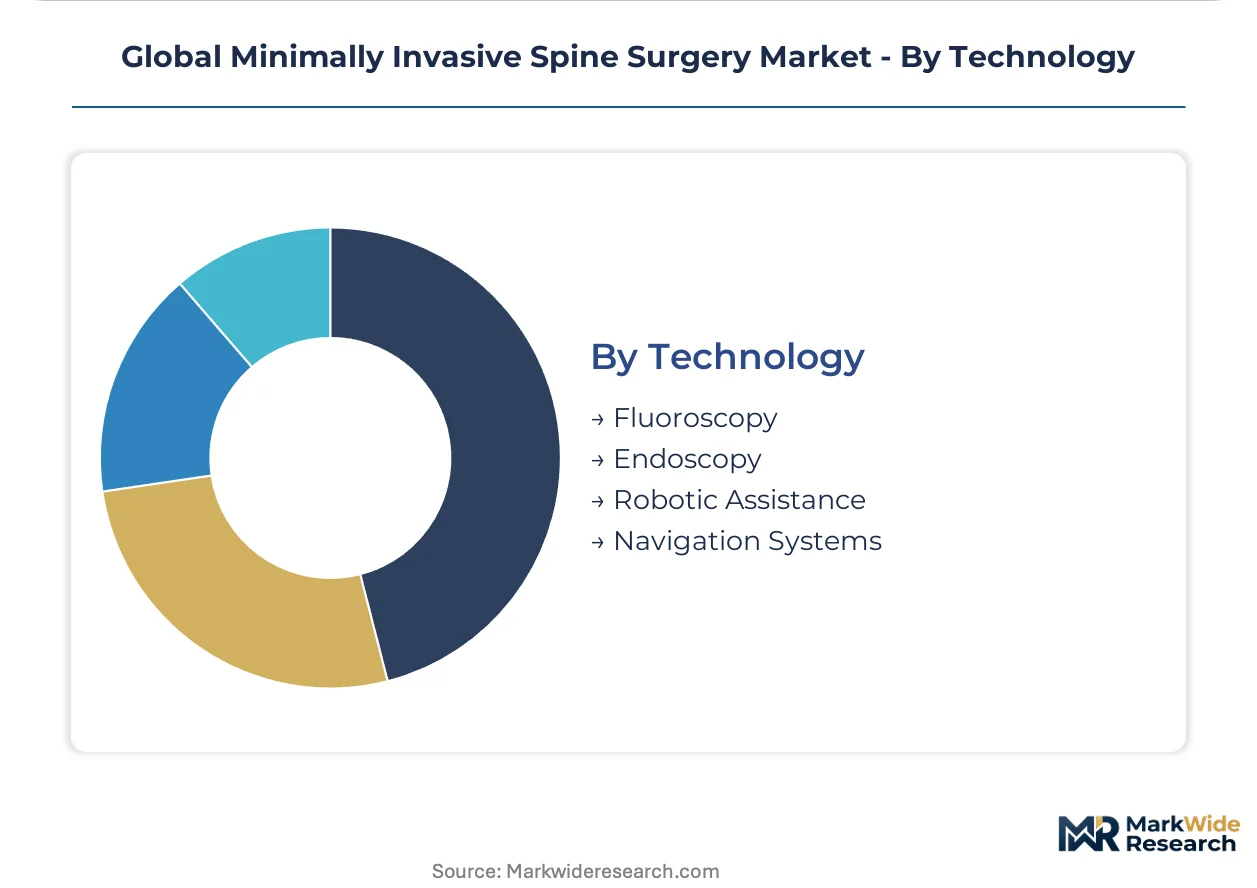
Technology:
Pricing power stratifies between radiation-dependent modalities and capital-intensive robotic platforms with recurring software revenue.
- Fluoroscopy:C-arm and O-arm systems provide real-time bony anatomy visualization during instrumentation. Operating staff exposure limits in high-volume United States centers drive demand for pulsed fluoroscopy and shielded suites.
- Robotic Assistance:Preoperative planning with intraoperative execution platforms command premium positioning. FDA 510(k) predicate pathways accelerate entry for screw guidance algorithms targeting United States hospitals.
- Endoscopy:Transforminal and interlaminar approaches enable direct visualization through working channels.
- Navigation Systems:Optical and electromagnetic tracking registers patient anatomy to preoperative imaging for instrument guidance.
Capital allocation prioritizes Navigation Systems for accuracy gains. Robotic Assistance shows the steepest expansion trajectory as vendors lock in disposable instrument flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany generates denser referral networks for minimally invasive spine procedures than the United States, though American ambulatory surgery centers deploy capital equipment at faster velocities. Japan's aging demographics sustain procedural volume expansion despite slower regulatory pathways. China's hospital procurement centralization is compressing vendor margins across all technology tiers.
United States
Ambulatory surgery centers in Texas and Florida drive same-day discharge protocols for lumbar decompression. FDA 510(k) predicate pathways accelerate screw guidance system clearances for vendors targeting hospital networks. The Pacific Northwest corridor clusters robotic navigation adoption around Seattle and Portland academic medical centers.
Germany
Specialized orthopedic clinics concentrate around Berlin and Munich university hospitals, normalizing lateral access techniques through fellowship pipelines. EU MDR clinical evaluation obligations extend spinal implant documentation timelines for manufacturers. The Baden-Württemberg region anchors navigation platform servicing infrastructure for southwestern European markets.
Japan
PMDA foreign manufacturer registration requirements filter robotic system entrants despite substantial procedural demand from aging populations. METI industrial policy supports domestic imaging equipment development for intraoperative navigation. The Kansai region around Osaka maintains higher per-capita spinal stenosis intervention rates than greater Tokyo.
China
Provincial hospital procurement consortiums in Jiangsu and Guangdong centralize minimally invasive spine equipment purchasing. NMPA medical device classification rules differentiate navigation hardware from disposable implant registration pathways. The Yangtze River Delta spine surgery volume concentrates in Shanghai municipal hospital networks.
United Kingdom
NHS England reimbursement parity between inpatient and outpatient spinal codes determines ASC capital deployment speed across independent surgery networks. MHRA post-Brexit device regulations retain EU MDR technical standards with modified conformity assessment routes. The Greater Manchester health system pilots bundled payment models for single-level fusion procedures.
Global Minimally Invasive Spine Surgery Market Vendor Landscape
Top-tier vendors anchor integrated surgical ecosystems, while mid-tier specialists concentrate on single-approach differentiation. The vendor base stratifies across three archetypes: diversified medtech conglomerates with navigation hardware platforms, pure-play spine implant specialists, and Asian manufacturing entities supplying commoditized instruments. M&A activity targets robotic navigation capabilities, while strategic partnerships lock in disposable instrument flows across installed bases.
Within the diversified conglomerate tier, Medtronic plc and Stryker Corporation exemplify ecosystem-based positioning that sustains high switching costs through recurring software licensing and service contract bundling. NuVasive Inc. occupies a specialist position anchored in lateral access technique differentiation. These three entities represent distinct strategic vectors: full-stack integration, navigation hardware control, and procedural approach specialization.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings Inc. |
| DePuy Synthes |
| Medtronic plc |
| Orthofix Medical Inc. |
| Alphatec Holdings Inc. |
| Stryker Corporation |
| Globus Medical Inc. |
| Aesculap Implant Systems LLC |
| NuVasive Inc. |
| Others |
Supply Flow & Price Mechanics
Titanium alloy pricing benchmarks cascade through spinal implant manufacturing, compressing margin pools for pedicle screw systems while amplifying cost advantages for vendors with captive forging capacity in Germany and the United States. This raw-material cost pressure stratifies the market into three tiers: premium robotic-navigation bundles, standard instrument kits, and economy consumables sourced from Asian contract manufacturers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for tubular retractors and targeting guides, forcing established suppliers toward subscription-based software licensing for robotic platforms. Price differentiation hinges on FDA 510(k) predicate status and bundled service contracts, with academic medical centers showing lowest sensitivity and independent ambulatory surgery centers driving hardest per-procedure negotiations. Cost compression in commoditized instruments is intensifying because Jiangsu and Guangdong procurement consortiums centralize purchasing leverage.
Supply Chain Analysis
Domestic-content mandates in Japan's METI industrial policy are reshaping sourcing patterns for navigation hardware, pushing foreign manufacturers toward local assembly partnerships. Supply concentration rests on precision machining in Germany, polymer processing in the United States, and titanium forging in China. Critical dependencies include PEEK resin for interbody devices, surgical-grade stainless steel, and optical tracking components. Single-source vulnerability concentrates in electromagnetic sensor supply. Distribution runs through hospital procurement committees in North America and direct-to-ASC channels accelerating in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in minimally invasive spine surgery rests on two vectors: software attach rates climbing on robotic platforms and Asian contract manufacturing absorbing instrument commoditization. Vendors capturing both dynamics separate from competitors trapped in hardware-only economics.
For Market Incumbents: To counter locked-in disposable flows facing renegotiation pressure from ASC administrators, Medtronic plc and Stryker Corporation should deepen backward integration into PEEK resin compounding and expand proprietary navigation hardware servicing infrastructure across southwestern Europe. Certification investment in EU MDR clinical evaluation documentation preserves pricing power in German university hospital clusters. For New Entrants and Emerging Players: Enter via Japan PMDA foreign manufacturer registration pathways for robotic navigation systems, where procedural demand from aging demographics outpaces installed base penetration. Target independent ambulatory surgery centers in Texas and Florida with direct distribution models bypassing hospital procurement committees. White-space concentrates in AI-assisted intraoperative decision support algorithms facing EU AI Act documentation burdens that fragment incumbent launch timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where interoperability standards block seamless data exchange between competing navigation platforms, creating acquisition rationale for middleware specialists bridging proprietary hardware ecosystems. Long-term viability favors vendors with recurring software revenue exceeding 40% of total spinal implant sales. Watch FDA 510(k) predicate accumulation rates as inflection signal for time-to-revenue compression among emerging robotic platform developers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Accumulation | Accelerated clearance pathways compress time-to-revenue for screw guidance algorithms targeting United States hospitals. |
| EU MDR Clinical Evaluation Investment | Expanded documentation obligations extend approval timelines but preserve premium positioning in German orthopedic clusters. |
| Robotic Navigation Platform Integration | Preoperative planning with intraoperative execution locks in disposable instrument revenue across installed hospital bases. |
| Direct-to-ASC Distribution Buildout | Bypassing traditional procurement committees unlocks faster capital deployment in independent Texas and Florida surgery networks. |
| AI-Assisted Decision Support Development | Machine learning algorithm integration creates premium positioning amid EU AI Act scrutiny of automated intraoperative guidance. |
Methodological Framework
Multiple input streams — primary interviews with spine surgeons and hospital purchasing committees, GPO contract databases, and FDA 510(k) submission records — were reconciled against secondary validation from CMS Medicare reimbursement data and hospital procurement disclosures. Bottom-up procedure volume estimates across ambulatory surgery centers and academic medical centers were triangulated with top-down spinal implant revenue segmentation by product type and technology tier.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling dimensions spanning procedure type, technology modality, end-user channel, and regional regulatory cluster. CAGRs were derived from weighted average growth contributions across segment-level trajectories, with specific inputs including fluoroscopy utilization rates in high-volume United States centers and robotic navigation adoption cadences in German university-affiliated hospitals.
The model holds under stable reimbursement parity between inpatient and outpatient spinal codes; deviation in payor pressure for procedure migration or EU MDR documentation burden escalation would shift capital deployment velocity forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Veterinary Orthopedic Drills Market
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
Global Orthopedic Digit Implants Market